Cardiac Ablation Market (2026-2036)
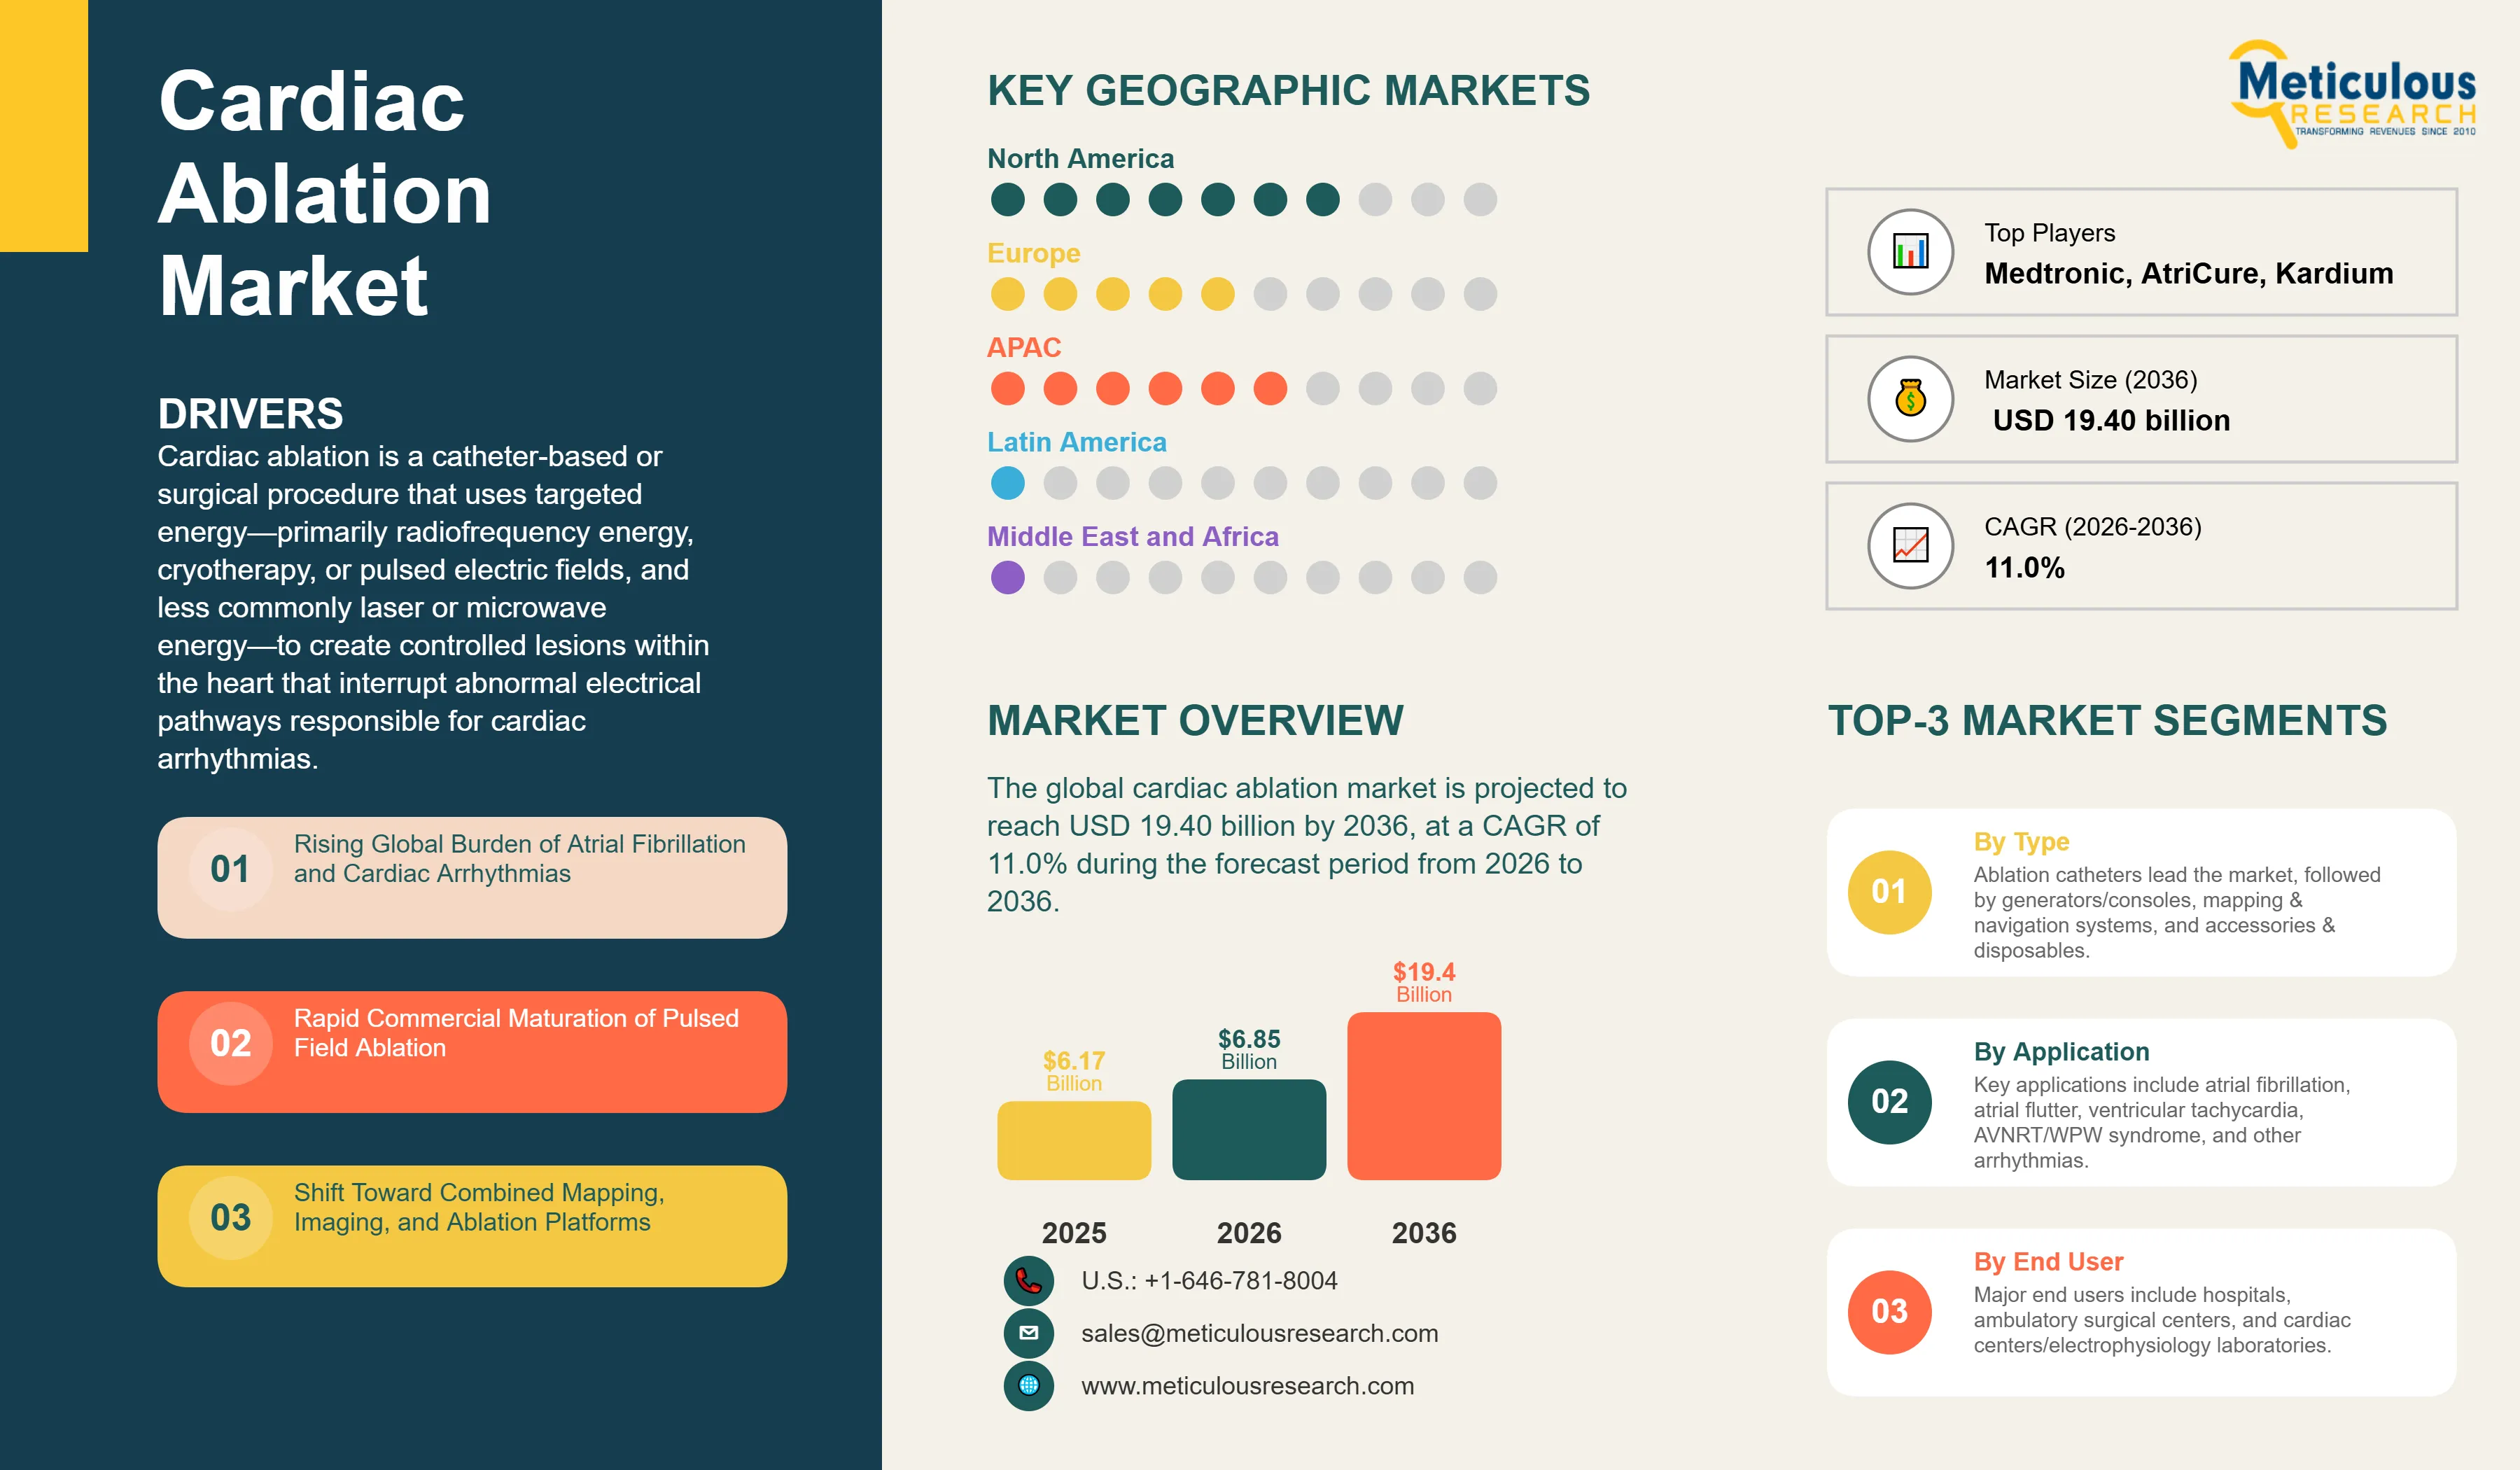
The global cardiac ablation market is projected to reach USD 19.40 billion by 2036 from an estimated USD 6.85 billion in 2026, at a CAGR of 11.0% during the forecast period from 2026 to 2036.
- Published
- Jul 2026
- Pages
- 309
- Format
- PDF + Excel
- Report ID
- MR-2107
- Base year
- 2025
- 2026 · ESTIMATED
- $6.85B
- 2036
- $19.40B
- CAGR 2026–2036
- 11.0%
2025 baseline · 2026–2036 forecast at 11.0% CAGR · hover a bar for the value
Key highlights
The global cardiac ablation market is projected to reach USD 19.40 billion by 2036, growing at a CAGR of 11.0% during 2026 to 2036.
Rising atrial fibrillation and arrhythmia burden, tied to aging populations and the growing prevalence of hypertension, obesity, and diabetes, continues to expand the pool of patients eligible for ablation.
Pulsed field ablation (PFA) has moved from a single-vendor category to a four-way contest among the largest electrophysiology companies within roughly two years of its U.S. launch.
Ablation catheters hold the largest market share in 2026, reflecting the high per-procedure consumable spend inherent to catheter-based ablation, while pulsed field ablation platforms are expected to grow the fastest.
The catheter-based approach holds the largest share in 2026, given its minimally invasive profile relative to surgical (Maze) procedures.
The atrial fibrillation application holds the largest share in 2026, as AF remains the dominant indication driving ablation procedure volumes.
The hospitals segment holds the largest share in 2026, while ambulatory surgical centers and dedicated cardiac/EP centers are expected to register the fastest growth.
North America accounts for the largest share of the global market in 2026, supported by high procedure volumes and rapid pulsed field ablation adoption.
Asia-Pacific is expected to witness the fastest growth over the forecast period, driven by expanding electrophysiology lab infrastructure and rising arrhythmia diagnosis rates.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 11.0% |
| Format | PDF, Excel & Cloud Portal · 309 pages |
| Market Size (Value) in 2026 | USD 6.85 Billion* |
| Market Size (Value) in 2036 | USD 19.40 Billion* |
| Segments Covered | By Product Type: Ablation Catheters, Generators/Consoles, Mapping & Navigation Systems, Accessories · By Technology: Radiofrequency Ablation, Cryoablation, Pulsed Field Ablation, Microwave/Laser Ablation · By Approach: Catheter-based, Surgical · By Application: Atrial Fibrillation, Atrial Flutter, Ventricular Tachycardia, AVNRT/WPW Syndrome, Other Arrhythmias · By End User: Hospitals, Ambulatory Surgical Centers, Cardiac Centers/EP Labs |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Australia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (Saudi Arabia, UAE, South Africa, and Rest of Middle East & Africa) |
| Key Companies | Medtronic plc (Ireland), Johnson & Johnson MedTech (U.S.), Abbott Laboratories (U.S.), Boston Scientific Corporation (U.S.), MicroPort Scientific Corporation (China), BIOTRONIK SE & Co. KG (Germany), AtriCure, Inc. (U.S.), Japan Lifeline Co., Ltd. (Japan), Stereotaxis, Inc. (U.S.), CardioFocus, Inc. (U.S.), Kardium Inc. (Canada), Adagio Medical Holdings, Inc. (U.S.), Acutus Medical, Inc. (U.S.), CathRx Ltd. (Australia), Imricor Medical Systems, Inc. (U.S.) |
Report overview
Segments covered: product type, technology, approach, application, end user. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
Cardiac ablation is a catheter-based or surgical procedure that uses targeted energy—primarily radiofrequency energy, cryotherapy, or pulsed electric fields, and less commonly laser or microwave energy—to create controlled lesions within the heart that interrupt abnormal electrical pathways responsible for cardiac arrhythmias. The market comprises ablation catheters, generators and consoles, three-dimensional mapping and navigation systems, and procedure-related accessories and disposables that together enable complete cardiac ablation procedures and form the technological foundation of modern electrophysiology practice.
Demand for these systems closely follows the global burden of cardiac arrhythmias, particularly atrial fibrillation (AF), which continues to rise worldwide. An estimated 52.55 million individuals were living with atrial fibrillation and atrial flutter globally in 2021, representing a 137% increase compared with 1990, while adults aged over 40 years face an approximately 25% lifetime risk of developing AF. The expanding prevalence of arrhythmias, supported by population aging, improved diagnosis, and increasing cardiovascular risk factors, is expected to sustain procedural volumes throughout the forecast period.
Technological innovation continues to reshape the market. Pulsed field ablation (PFA), which uses high-voltage electrical pulses to selectively ablate myocardial tissue while minimizing injury to adjacent structures such as the esophagus and phrenic nerve, has rapidly progressed from early commercialization into one of the fastest-growing segments of cardiac electrophysiology. At the same time, advanced three-dimensional electroanatomical mapping, intracardiac echocardiography integration, contact-force sensing, and artificial intelligence-assisted workflow optimization are enhancing procedural precision, efficiency, and safety, increasing the strategic importance of software and imaging platforms alongside ablation catheters.
The delivery of cardiac ablation procedures is also evolving. Hospitals remain the primary care setting because of their ability to support complex electrophysiology laboratories and manage high-risk patients; however, an increasing proportion of procedures is being performed in ambulatory surgical centers and specialized cardiac centers as technologies become faster, safer, and more efficient. Collectively, the growing global burden of arrhythmias, continued adoption of pulsed field ablation, ongoing advances in mapping and imaging technologies, and the gradual shift toward lower-cost outpatient care settings are expected to drive sustained double-digit growth in the global cardiac ablation market over the coming decade.
Report infographic
Market dynamics
5 factors across 2 forcesRising Global Burden of Atrial Fibrillation and Cardiac Arrhythmias
The primary driver of the cardiac ablation market is the steady increase in the number of patients with cardiac arrhythmias who become candidates for interventional treatment. As populations age, the prevalence of atrial fibrillation (AF), the most common sustained cardiac arrhythmia, continues to rise, while associated risk factors such as hypertension, obesity, diabetes, heart failure, and chronic kidney disease further contribute to disease burden. In Europe, the number of individuals living with AF and atrial flutter is projected to reach 8.8–18 million by 2060, while the prevalence of AF in the United States is expected to continue increasing substantially over the coming decades. As a growing proportion of diagnosed AF patients become eligible for rhythm-control strategies when pharmacological therapy proves inadequate or is poorly tolerated, the expanding patient population is expected to provide a sustained and long-term source of demand for cardiac ablation procedures and associated technologies.
Rapid Commercial Maturation of Pulsed Field Ablation
A second major growth driver is the rapid commercialization of pulsed field ablation (PFA), which has evolved from an emerging technology into one of the most competitive segments of the cardiac electrophysiology market. Boston Scientific Corporation received U.S. FDA approval for its FARAPULSE™ Pulsed Field Ablation System in January 2024, and within a short period the technology achieved rapid adoption across the United States and Europe while also expanding into China and Japan. By 2026, more than 200,000 patients had been treated using the FARAPULSE platform, demonstrating strong physician acceptance and accelerating the transition toward non-thermal ablation technologies. Subsequently, Abbott Laboratories received FDA approval for its Volt™ Pulsed Field Ablation System in December 2025, joining Medtronic plc, Boston Scientific Corporation, and Johnson & Johnson MedTech in the rapidly expanding U.S. PFA market. The near-simultaneous commercialization of PFA platforms by the industry's leading electrophysiology companies is accelerating technology replacement cycles, increasing hospital investment in next-generation electrophysiology systems, and intensifying competition across the global cardiac ablation market.
Shift Toward Combined Mapping, Imaging, and Ablation Platforms
A third driver is the move toward fully integrated electrophysiology platforms rather than standalone catheters. Johnson & Johnson has introduced its CARTOSOUND SONATA Module, which uses artificial intelligence with the CARTO System to automatically transform intracardiac echocardiography images into detailed maps, allowing physicians to build accurate models of multiple heart chambers, illustrating how vendors are bundling ablation energy, navigation, and imaging into a single procedural workflow. Hospitals evaluating new electrophysiology investments increasingly weigh the full platform, not the catheter in isolation, which favors vendors with mapping, imaging, and ablation capabilities under one roof.
Table of contents
12 chapters · 117 sections · 309 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Ablation Catheters | — |
| By Technology | Radiofrequency ablation | Pulsed Field Ablation |
| By Approach | Catheter-based Ablation | — |
| By Application | Atrial Fibrillation | — |
| By End User | Hospitals | Ambulatory surgical centers and dedicated cardiac centers |
By Product Type
- Ablation Catheters Lead the Market in 2026
- Ablation catheters are expected to account for the largest share of the market in 2026, reflecting their nature as a per-procedure consumable that is replaced with every case, unlike capital equipment which is purchased once and used across many procedures.
- Mapping and navigation systems are projected to register strong growth as integrated, AI-assisted platforms become a standard part of new electrophysiology lab builds.
By Technology
- Radiofrequency Ablation Leads, Pulsed Field Ablation Grows Fastest
- Radiofrequency ablation holds the largest share in 2026, supported by decades of clinical precedent and its status as a default choice across many arrhythmia types beyond atrial fibrillation.
- Pulsed field ablation is projected to grow the fastest by a wide margin, having expanded from a single commercial vendor to four major competitors within roughly two years of its first U.S. approval.
By Approach
- Catheter-based Ablation Leads the Market in 2026
- Catheter-based procedures hold the dominant share given their minimally invasive nature, shorter recovery time, and lower procedural trauma relative to surgical Maze-type procedures, which are typically reserved for patients undergoing concurrent open-heart surgery.
By Application
- Atrial Fibrillation Leads the Market in 2026
- Atrial fibrillation accounts for the largest share in 2026, consistent with its position as the most common sustained cardiac arrhythmia and the leading indication for ablation referral globally.
By End User
- Hospitals Lead the Market in 2026
- Hospitals hold the largest share in 2026, supported by their capacity to run advanced mapping suites and manage procedural complications.
- Ambulatory surgical centers and dedicated cardiac centers are expected to grow the fastest as procedure times shorten and site-of-care shifts continue.
Geographic analysis
North America
Largest shareNorth America holds the largest share in 2026, supported by high procedure volumes, favorable reimbursement for electrophysiology interventions, and the fastest pace of pulsed field ablation adoption among the major device makers. The United States is the dominant national market, reflecting its role as the first launch market for nearly every major ablation platform. North America Leads the Market in 2026
Asia-Pacific
Fastest growthAsia-Pacific is expected to record the fastest growth over the forecast period, driven by expanding electrophysiology lab infrastructure, rising diagnosis rates for atrial fibrillation, and the phased extension of pulsed field ablation approvals into China and Japan.
Europe
Europe remains an important market, supported by strong adoption of next-generation ablation platforms and an active clinical research base presenting data at meetings such as the European Heart Rhythm Association congress.
Competitive landscape
Leading companies in the market have grown through new product launches, regulatory approvals, clinical data generation, and strategic acquisitions of smaller pulsed field ablation and mapping specialists. Securing regulatory clearance for pulsed field platforms, expanding integrated mapping and imaging capabilities, and presenting late-breaking clinical data at major electrophysiology congresses have been the most common ways players have strengthened their position through 2026.
- April 2026
At the Heart Rhythm Society (HRS) annual meeting, Johnson & Johnson MedTech introduced the CARTOSOUND™ SONATA Module, which combines artificial intelligence with the CARTO™ 3 System to automatically convert intracardiac echocardiography (ICE) images into detailed three-dimensional maps of multiple cardiac chambers.
- December 2025
Abbott received U.S. FDA approval for its Volt™ Pulsed Field Ablation System, a catheter-based platform that uses targeted high-energy electrical pulses to treat drug-refractory recurrent symptomatic paroxysmal and persistent atrial fibrillation.
- Early 2026
Medtronic continued expanding its Affera™ cardiac ablation platform, including advancement of the Sphere-360™ pulsed field ablation catheter and related technologies, as disclosed in the company's SEC filings and investor communications.
- Medtronic plc · Ireland
- Johnson & Johnson MedTech (U.S.)
- Abbott Laboratories (U.S.)
- Boston Scientific Corporation (U.S.)
- MicroPort Scientific Corporation · China
- BIOTRONIK SE & Co. KG · Germany
- AtriCure, Inc. (U.S.)
- Japan Lifeline Co., Ltd. · Japan
- Stereotaxis, Inc. (U.S.)
- CardioFocus, Inc. (U.S.)
- Kardium Inc. · Canada
- Adagio Medical Holdings, Inc. (U.S.)
- Acutus Medical, Inc. (U.S.)
- CathRx Ltd. · Australia
- Imricor Medical Systems, Inc. (U.S.)
Expert perspectives
“Pulsed field ablation has moved from a promising concept to a standard-of-care option in a remarkably short window. Electrophysiologists are drawn to the combination of shorter procedure times and a differentiated safety profile compared with thermal energy sources.”
“Health systems are no longer buying a catheter in isolation. They are evaluating an entire ecosystem, mapping, imaging, and navigation, that needs to work together to shorten procedures and improve first-pass success.”
“The competitive intensity in pulsed field ablation has been unlike anything we've seen in electrophysiology. Every major player now has a commercial platform, and the differentiation battle has shifted to catheter design, mapping integration, and procedural workflow.”
Frequently asked questions
The global cardiac ablation market size is estimated at USD 6.85 billion in 2026 (directional, pending internal model validation).
Cite this report
Meticulous Research. (2026). Cardiac Ablation Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-2107). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/cardiac-ablation-market-6790