Busbar Systems Market (2026-2036)
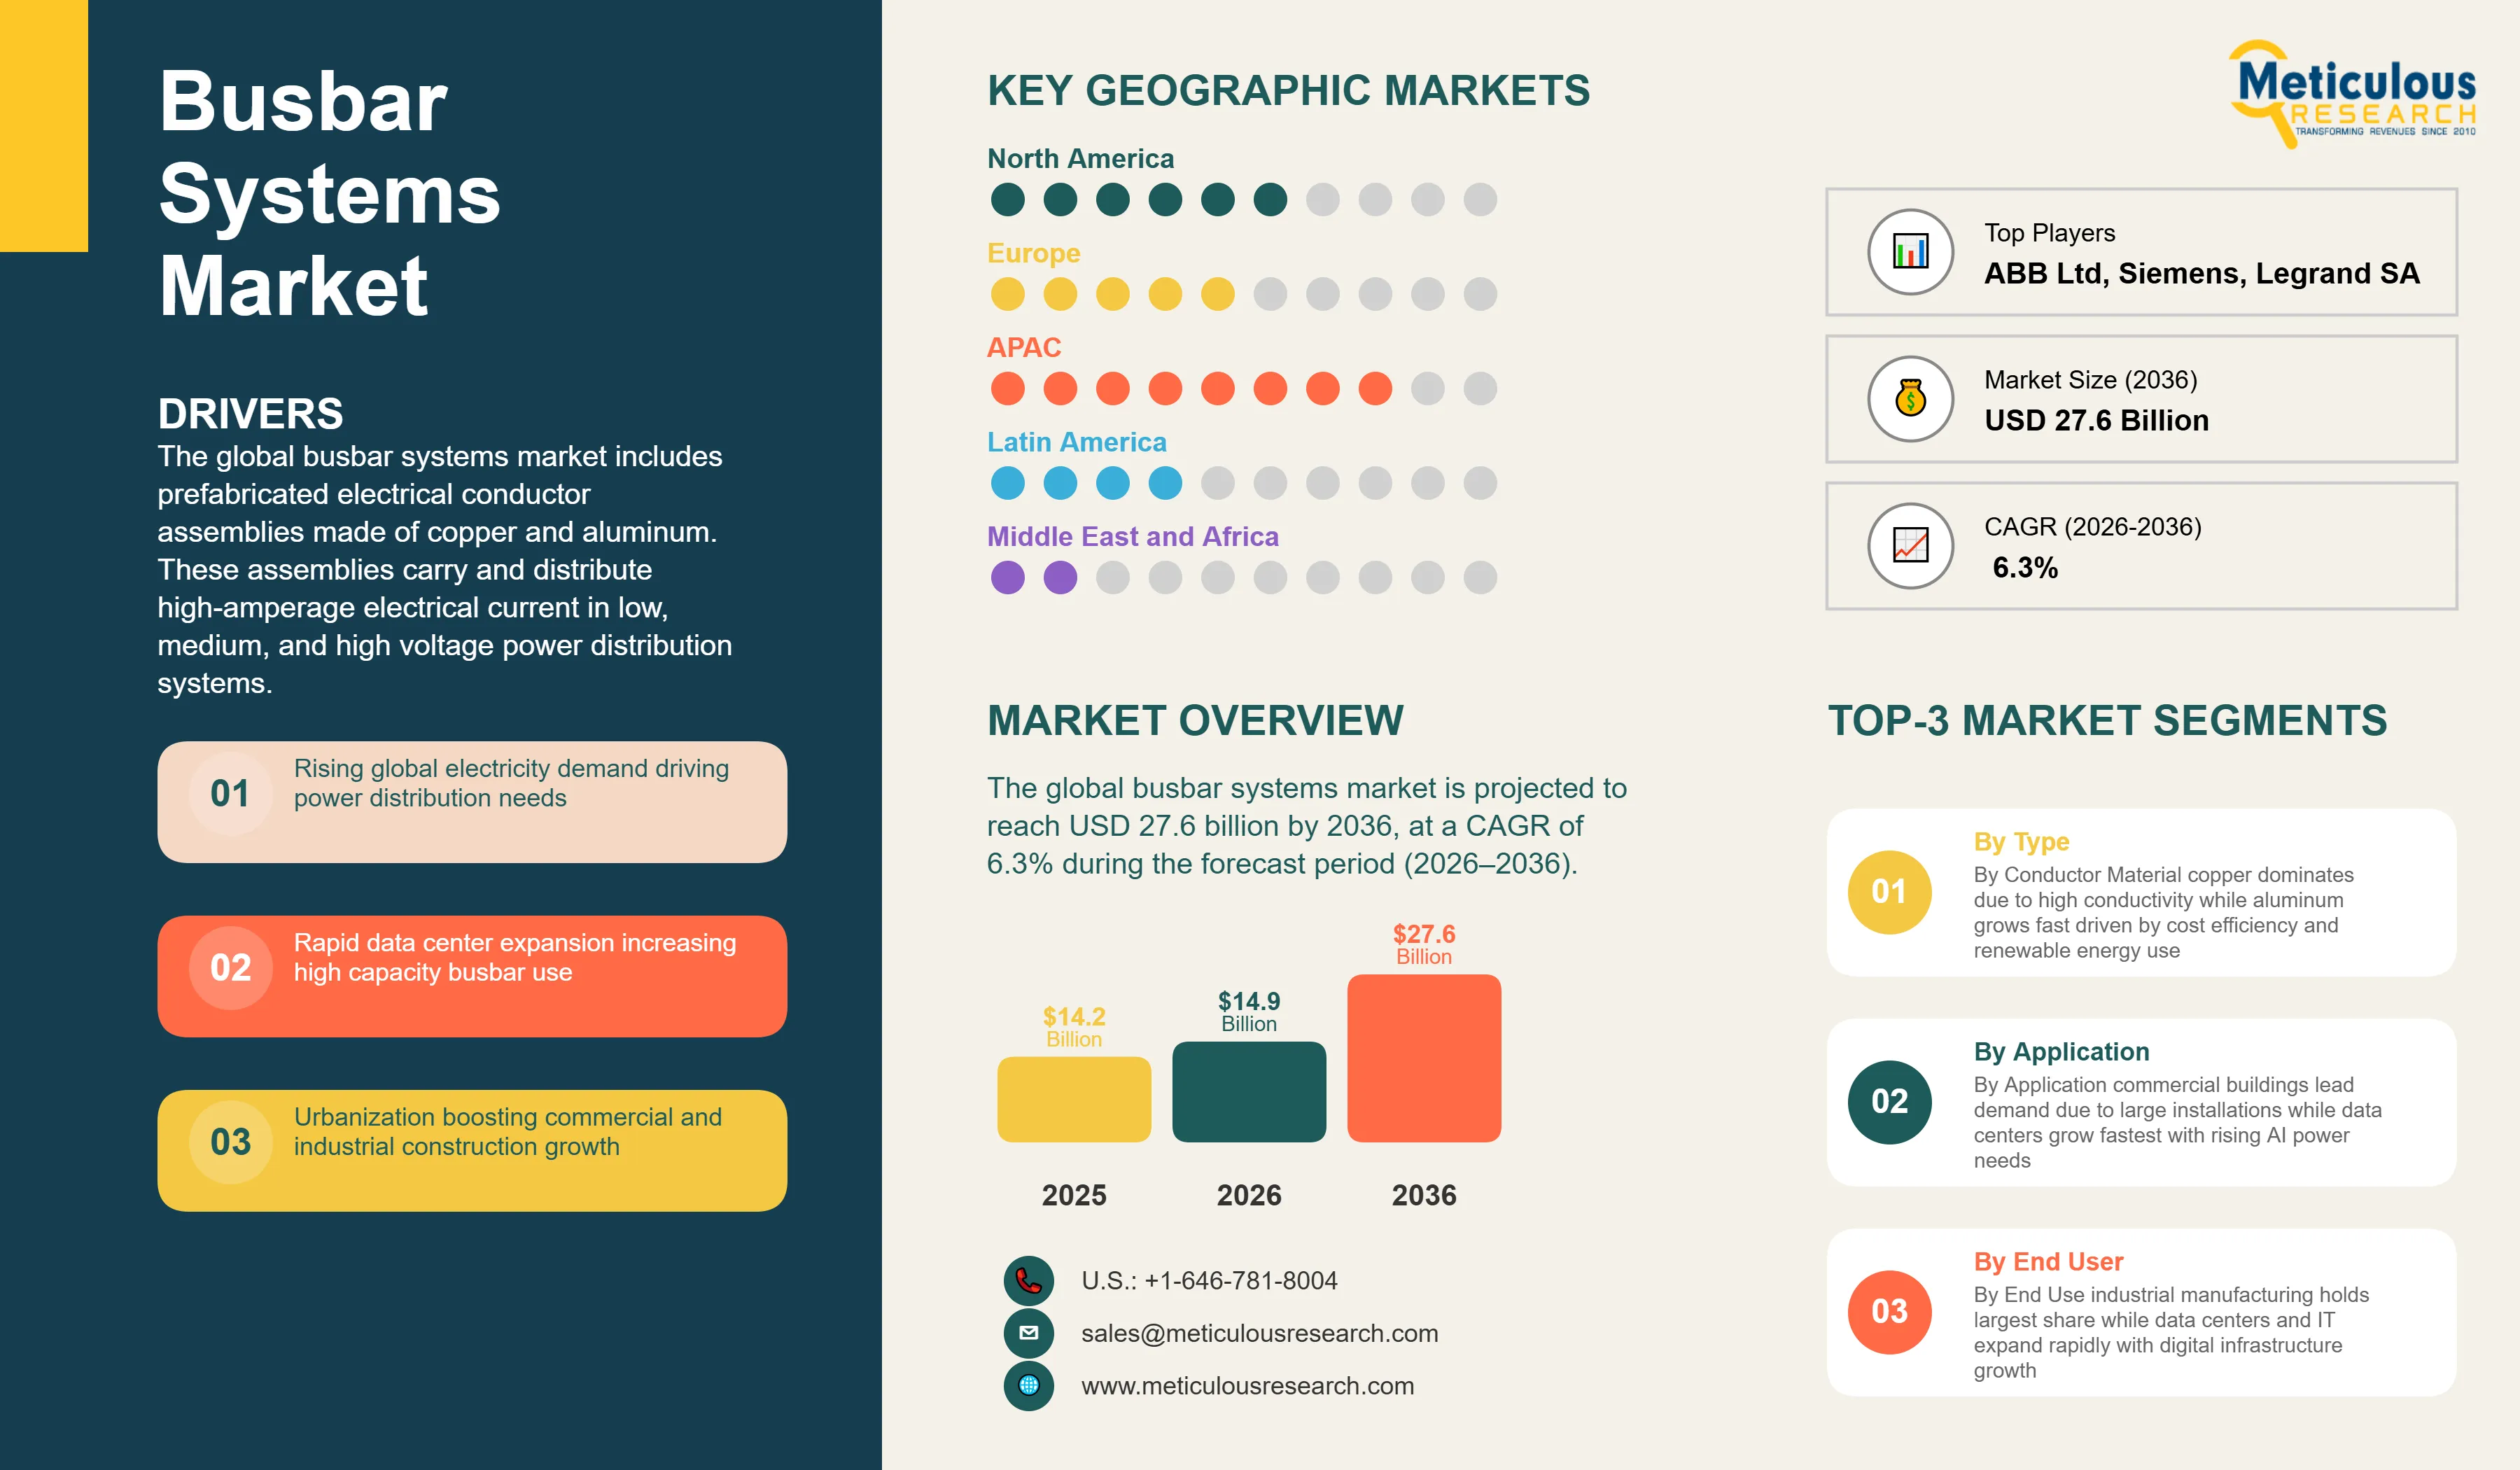
The global busbar systems market was valued at USD 14.2 billion in 2025. The market is projected to reach USD 27.6 billion by 2036, growing from USD 14.9 billion in 2026 at a CAGR of 6.3% during the forecast period (2026–2036).
- Published
- Apr 2026
- Pages
- 296
- Format
- PDF + Excel
- Report ID
- MR-1888
- Base year
- 2025
- 2025 · BASELINE
- $14.20B
- 2036
- $27.60B
- CAGR 2026–2036
- 6.3%
2025 baseline · 2026–2036 forecast at 6.3% CAGR · hover a bar for the value
Key highlights
The global busbar systems market is projected to reach USD 27.6 billion by 2036.
The market is expected to grow at a CAGR of 6.3% during the forecast period 2026–2036.
The global busbar systems market was valued at USD 14.2 billion in 2025 and is estimated to reach USD 14.9 billion in 2026.
Asia Pacific is expected to dominate the global busbar systems market with the largest market share in 2026, driven by the scale and pace of construction and power infrastructure investment in China, India, Japan, and Southeast Asia, the presence of a large base of domestic and international busbar manufacturers, and the continued expansion of industrial and commercial real estate across the region.
The Middle East and Africa is projected to witness the fastest growth during the forecast period, driven by the acceleration of large-scale infrastructure investment programs across Gulf Cooperation Council nations under national transformation agendas and the growing expansion of power transmission and distribution networks across Sub-Saharan Africa.
By conductor material, the copper segment is expected to hold the largest market share in 2026.
By conductor material, the aluminum segment is projected to register the highest CAGR during the forecast period, driven by growing cost-conscious procurement in utility-scale renewable energy and large commercial construction applications.
By voltage level, the low voltage busbar systems segment is expected to account for the largest share of the global busbar systems market in 2026.
By voltage level, the medium voltage busbar systems segment is projected to register the highest CAGR during the forecast period.
By product type, the sandwich busbar trunking systems segment is expected to account for the largest share in 2026, while the isolated phase busbar systems segment is projected to register the highest CAGR during the forecast period.
By application, the commercial buildings segment is expected to account for the largest share in 2026, while the data centers segment is projected to register the highest CAGR during the forecast period.
By end use, the industrial manufacturing segment is expected to account for the largest share in 2026, while the data centers and IT segment is projected to register the highest CAGR.
By geography, Asia Pacific is expected to dominate the market in 2026, while the Middle East and Africa is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 27.6 Billion |
| Market Size in 2026 | USD 14.9 Billion |
| Market Size in 2025 | USD 14.2 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 6.3% |
| Format | PDF, Excel & Cloud Portal · 296 pages |
| Dominating Conductor Material | Copper |
| Fastest Growing Conductor Material | Aluminum |
| Dominating Voltage Level | Low Voltage |
| Fastest Growing Voltage Level | Medium Voltage |
| Dominating Product Type | Sandwich Busbar Trunking Systems |
| Fastest Growing Product Type | Isolated Phase Busbar Systems |
| Dominating Application | Commercial Buildings |
| Fastest Growing Application | Data Centers |
| Dominating End Use | Industrial Manufacturing |
| Fastest Growing End Use | Data Centers and IT |
| Dominating Geography | Asia Pacific |
| Fastest Growing Geography | Middle East and Africa |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: product type, voltage level, conductor material, application, end-use industry.
The global busbar systems market includes prefabricated electrical conductor assemblies made of copper and aluminum. These assemblies carry and distribute high-amperage electrical current in low, medium, and high voltage power distribution systems. They are used in sandwich busbar trunking, air insulated busbar trunking, segregated phase, and isolated phase forms. You can find these systems in commercial buildings, industrial facilities, data centers, power generation plants, renewable energy sites, and transportation infrastructure. They provide reliable and high-capacity power distribution in situations where traditional cable-based wiring is not practical.
The market for busbar systems is mainly attributed due to the steady increase in electricity demand worldwide. This rise is linked to the expansion of power distribution networks in commercial buildings, industrial automation, and large-scale digital infrastructure. The fast growth of data center construction, especially those focused on AI, is driving high-demand for flexible, high-capacity busbar trunking systems. These data centers need a lot of power at the rack and row level. At the same time, the global shift towards electrification in transportation, manufacturing, and utilities is broadening the use of busbar systems beyond traditional building wiring and into new areas.
Increasing urbanization and commercial real estate construction in Asia Pacific, the Middle East, and Africa are driving the demand for low voltage busbar trunking. This is becoming the preferred power distribution solution in high-rise commercial and residential towers, airports, hospitals, and shopping centers. The trend toward prefabricated electrical assemblies is also helping market growth. Busbar systems provide clear benefits, such as faster installation, better space efficiency, higher current-carrying capacity, and easier modifications for distribution layouts during a building's life.
Despite the growth prospects, the market faces challenges such as the upfront cost of busbar systems is relatively high compared to traditional cable-based power distribution. This is particularly important for price sensitive customers in emerging markets where cable installation is the norm. Furthermore, fluctuations in copper and aluminum prices create uncertainty in procurement costs for both manufacturers and customers, complicating long-term project budgets. Finding trained labor for busbar installation and jointing, coupled with the need for coordination between electrical, structural, and mechanical trades during construction, adds complexity to large project timelines.
The rapid growth of AI data centers and the increase in building-level power capacity requirements present significant opportunities for busbar manufacturers. They can create product lines designed for data center power density needs, featuring ratings up to 6,300 amperes and improved plug-in options for flexible power distribution along server aisles. The shift toward renewable energy and modernizing the grid in both developed and developing countries is also opening new application areas, especially for aluminum busbar systems in large-scale solar and wind projects. Additionally, the rising use of busbar systems in electric vehicle charging networks and battery energy storage setups is creating a new demand driver, expanding the market beyond traditional building and industrial uses.
Report infographic
Market dynamics
2 factors across 1 forceAI and Hyperscale Data Center Construction Driving Demand for High-Ampacity, Modular Busbar Trunking Solutions
The rapid growth of the global data center construction is changing demand patterns in the busbar systems market. This growth is mainly fueled by the rising needs of artificial intelligence training and inference tasks. Major cloud providers like Microsoft, Google, Amazon Web Services, and Meta are investing in large data center campus projects across North America, Europe, and Asia Pacific. Each of these projects requires extensive power distribution infrastructure that delivers electrical power at levels unseen in traditional commercial buildings.
Busbar trunking systems are becoming the preferred choice for power distribution in these settings. They are replacing old cable-based methods because they offer high-ampacity distribution with ratings from 800 amperes to 6,300 amperes. These systems have standardized plug-in tap-off options, allowing easy reconfiguration as power density needs change. Top busbar manufacturers like ABB, Schneider Electric, and Siemens have launched dedicated product lines for data centers. These products feature IP-rated enclosures, integrated power monitoring, and low-impedance designs optimized for modern AI data center layouts.
The data center sector is expected to drive the growth of the busbar systems market. This growth comes from long-term investments by hyperscale companies, with commitment periods ranging from five to ten years. This shift is urging mid-sized busbar manufacturers to create data center-specific product certifications and form partnerships with mechanical and electrical contractors. This strategy aims to gain a larger share of the expanding order pipeline.
Aluminum Busbar Systems Gaining Procurement Share Across Utility-Scale Renewable Energy and Large Commercial Applications
The growth of large-scale solar and wind energy infrastructure, along with ongoing fluctuations in copper prices on international metal markets is accelerating the adoption of aluminum conductor busbar systems in areas where material cost is a key factor. The lighter weight of aluminum also offers significant structural and installation advantages. Aluminum busbar systems provide about 61% of the electrical conductivity of copper while being roughly 30% lighter. They are becoming the preferred option for large solar power plants, onshore and offshore wind energy systems, and major commercial building distribution applications, where the larger size needed to match copper's current-carrying capacity is not a feasible limitation.
Leading manufacturers like ABB, Legrand, and Mersen are developing new aluminum alloy formulas and jointing methods. These efforts tackle long-standing issues with oxide formation at connection points and the reliability of connections between aluminum and copper in demanding environments. This work is gradually making aluminum systems more comparable to copper systems. At the same time, the overall push for greener infrastructure supply chains is highlighting the lower carbon footprint of producing primary aluminum compared to mining and refining copper. This reinforces aluminum busbar systems as an environmentally friendly choice for large infrastructure developers and public sector project owners.
As the addition of renewable energy capacity increases worldwide, driven by policy goals in the European Union, China, India, and the United States under national decarbonization plans, the demand for aluminum busbar systems in the energy and utilities sector is expected to rise faster than the market average through the forecast period. This trend will likely boost aluminum's share of the overall conductor material mix in new busbar system installations.
Electrification of Transportation and Industrial Processes Creating Structurally New High-Growth Demand Beyond Traditional Power Distribution
The shift toward electrification in transportation, industrial manufacturing, and large-scale energy storage is creating new application areas for busbar systems. These areas are different from the traditional commercial and industrial power distribution markets that have defined this industry for years. The growth of the electric vehicle charging infrastructure at highways, logistics and distribution centers, in urban public transport hubs, and at automotive manufacturing sites requires high-current AC and DC distribution assemblies. These assemblies need to serve multiple high-power charging points at once from a central switchboard. This setup is well-suited for modular plug-in busbar trunking systems.
In the industrial sector, replacing fossil fuel-based equipment with electric alternatives, along with the increasing use of high-power robotics and automated systems, is raising the need for flexible, high-capacity power distribution in factories. Busbar trunking systems with IP55 or higher protection ratings are now preferred for tough industrial conditions. Manufacturers like Siemens, Eaton, and C&S Electric provide configurations that can handle dust, moisture, and vibration found in automotive assembly, food processing, and chemical production facilities.
Furthermore, the rollout of grid-scale battery energy storage systems as part of renewable energy support and grid stability initiatives is increasing the need for high-current DC busbar assemblies. This need arises from an application area that did not exist commercially a decade ago. These new application segments represent a significant expansion of the market for busbar systems. They are expected to drive a large portion of revenue growth during the forecast period, especially in regions with strong electrification policies.
Table of contents
13 chapters · 136 sections · 296 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Conductor Material | Copper | Aluminum |
| By Voltage Level | Low Voltage | Medium voltage busbar systems |
| By Product Type | Sandwich Busbar Trunking Systems | Isolated phase busbar systems |
| By Application | Commercial Buildings | Data centers |
| By End-use | Industrial Manufacturing | Data centers and IT |
By Conductor Material
- The Copper Segment to Dominate the Global Busbar Systems Market
- The copper segment is expected to account for the largest share of the global busbar systems market.
- The dominant position of copper is attributed to its superior electrical conductivity, established compatibility with standardized termination hardware and jointing methods, preferred status in safety-critical applications including data centers, hospitals, and industrial automation systems, and its ability to achieve equivalent current ratings in a more compact cross-section than aluminum alternatives.
- Copper busbar systems are specified as the default conductor material by major infrastructure developers, construction consultants, and electrical contractors in most commercial and industrial applications globally, mainly in high-density environments where minimizing conductor and enclosure cross-section is architecturally important.
- The long-term reliability track record of copper in demanding service environments and the favorable oxide formation properties that maintain good contact resistance at joints and terminations over the full service life of an installation continues to support copper's dominant position across all major voltage levels and product types.
- However, the aluminum segment is projected to register the highest growth during the forecast period.
- The growing adoption of aluminum conductor busbar systems in utility-scale solar and wind generation infrastructure, large commercial buildings in cost-sensitive emerging markets, and main distribution applications where the larger cross-section of aluminum busbars is not architecturally constraining is driving above-average revenue growth for this segment.
- The growing sophistication of aluminum alloy joining technology and the expanding range of OEM-certified aluminum busbar products from major manufacturers are progressively reducing the technical barriers that have historically limited aluminum's market penetration to lower-sensitivity applications.
By Voltage Level
- The Low Voltage Segment to Hold the Largest Share
- The low voltage busbar systems segment is expected to account for the largest share of the global busbar systems market.
- The growth is mainly driven by the very large volume of commercial building, industrial facility, and data center applications that require power distribution within the low voltage range, which collectively represents the most widely deployed application domain for busbar trunking and distribution systems globally.
- Low voltage busbar trunking systems in the 100-ampere to 6, 300-ampere rating range from leading manufacturers including ABB's BD3 and MNS families, Siemens' SIVACON 8PS and 8PV busbar families, Schneider Electric's Canalis range, and Eaton's Pow-R-Way product line are the primary product families driving this segment's dominant market position, with broad distribution across virtually every building type and industrial configuration globally.
- However, the medium voltage busbar systems segment is projected to register the fastest growth during the forecast period.
- This high growth is driven by the increasing installation of medium voltage switchgear and associated busbar assemblies in large-scale renewable energy substations, industrial process facilities requiring primary power distribution at 6.6 kV, 11 kV, or 33 kV, and the growing construction of compact urban electrical substations in dense metropolitan areas where space constraints make factory-assembled medium voltage busbar solutions preferable to site-built cable-based distribution alternatives.
By Product Type
- The Sandwich Busbar Trunking Systems Segment to Account for the Largest Share
- The sandwich busbar trunking systems is expected to hold the largest share of the global busbar systems market.
- This shows the prevalent use of enclosed, insulated sandwich-type busbar trunking as the main power distribution solution in commercial buildings, industrial facilities, data centers, and public infrastructure worldwide.
- Sandwich busbar trunking systems consist of copper or aluminum conductors arranged within an insulated sandwich stack and enclosed in a sheet steel housing.
- They offer high current capacity, IP-rated protection, modular plug-in tap-off ability, and easy installation.
- These features make them the preferred choice for power distribution in nearly all major end-use sectors.
- The plug-in capability of sandwich busbar systems, which allows authorized personnel to connect and disconnect tap-off boxes at any point along a busbar run without deenergizing the main circuit, is a particularly valued feature in data centers and large industrial facilities where operational continuity is critical and power distribution layouts need to be modified as equipment configurations evolve.
- However, the isolated phase busbar systems segment is projected to register the fastest growth during the forecast period.
- This growth is mainly driven by the increasing global investment in new power generation capacity, including combined-cycle gas turbine plants, large-scale hydroelectric facilities, and nuclear power stations, all of which require isolated phase busbar assemblies for the high-current connection between generator terminals and main step-up transformers.
- The continued addition of large-scale generation capacity to meet rising global electricity demand, combined with growing deployment of large power transformers in renewable energy collection systems and grid interconnection projects, is expected to sustain above-market growth in demand for isolated phase busbar assemblies throughout the forecast period.
By Application
- The Commercial Buildings Segment to Account for the Largest Share
- The commercial buildings segment is expected to account for the largest share of the global busbar systems market, driven by the very large and geographically distributed installation base of busbar trunking systems in office towers, shopping centers, hospitals, airports, educational institutions, and hotel complexes globally.
- Commercial buildings represent the highest-volume application for low voltage busbar trunking systems, with multi-story construction projects in Asia Pacific, Europe, North America, and the Middle East requiring busbar trunk runs across multiple floors and service risers per building, generating large and consistent procurement volumes from construction and building services contractors.
- However, the data centers segment is projected to register the fastest growth during the forecast period.
- The fast growth of this segment is driven by the accelerating global construction of hyperscale and colocation data centers in response to the exponential growth of AI workloads and cloud computing demand, with each large-scale data center campus requiring extensive high-ampacity busbar trunking for power distribution from the main transformer and switchgear room through to individual server hall power distribution units.
- The data center segment's ability to sustain above-average growth over an extended forecast horizon reflects the long duration and large committed capital investment pipeline of data center construction programs by major hyperscale operators and specialist colocation developers globally.
By End-use
- The Industrial Manufacturing Segment to Hold the Largest Share
- The industrial manufacturing sector is expected to hold the largest share of the global busbar systems market.
- This is due to the prevalent use of busbar systems for power distribution on factory floors, supplying machine tools, connecting motor control centers, and feeding automation panels in manufacturing facilities around the world.
- Industrial manufacturers are a varied and significant buyer of busbar systems at all voltage levels, from low voltage trunking in production areas to medium voltage switchgear busbar assemblies in primary distribution substations that serve large factory complexes.
- The depth and global breadth of the industrial manufacturing end-use base, spanning automotive, food and beverage, chemical, metal, textile, and electronics production, ensures this segment retains its dominant position throughout the forecast period.
- However, the data centers and IT segment is projected to register the fastest growth during the forecast period, driven by the structural increase in global data center power capacity requirements and the increasing specification of busbar trunking systems as the primary power distribution backbone in new hyperscale, colocation, and enterprise data center construction projects globally.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia Pacific is expected to account for the largest share of the global busbar systems market. This dominant position is driven by China's standing as the world's largest construction and electrical equipment market, the rapid pace of infrastructure development across India, Japan, South Korea, and Southeast Asia, and the large and growing base of industrial manufacturing and commercial real estate construction activity across the region. China's domestic busbar manufacturers, alongside international manufacturers operating production facilities in the region, benefit from the scale of infrastructure investment driven by urbanization, industrial expansion, and the continued buildout of national power distribution and generation infrastructure. India's rapidly expanding commercial real estate, manufacturing corridor, and data center development programs are contributing increasingly significant incremental demand, while Southeast Asian nations are at an earlier stage of urban infrastructure buildout that represents a multi-decade volume growth opportunity for busbar system suppliers.
Middle East & Africa
Fastest growthHowever, the Middle East and Africa busbar systems market is expected to grow at the fastest CAGR from 2026 to 2036. The rapid growth of this market is driven by the scale of infrastructure investment programs in Saudi Arabia under the Vision 2030 national transformation agenda, the UAE's continued large-scale commercial, industrial, and tourism infrastructure development, and the growing investment in power transmission and distribution network expansion across Sub-Saharan Africa to address electricity access gaps and support industrialization. The Gulf Cooperation Council's industrial diversification programs, including new manufacturing hubs, logistics cities, renewable energy facilities, and large-scale tourism destinations, are generating a sustained pipeline of commercial and industrial construction projects that require large volumes of busbar systems for electrical power distribution, positioning the Middle East and Africa as the highest-growth regional market over the forecast period.
Competitive landscape
- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Eaton Corporation plc
Frequently asked questions
The global busbar systems market is expected to reach USD 27.6 billion by 2036 from an estimated USD 14.9 billion in 2026, at a CAGR of 6.3% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Busbar Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1888). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/busbar-systems-market-6571