Satellite Earth Observation Market (2026-2036)
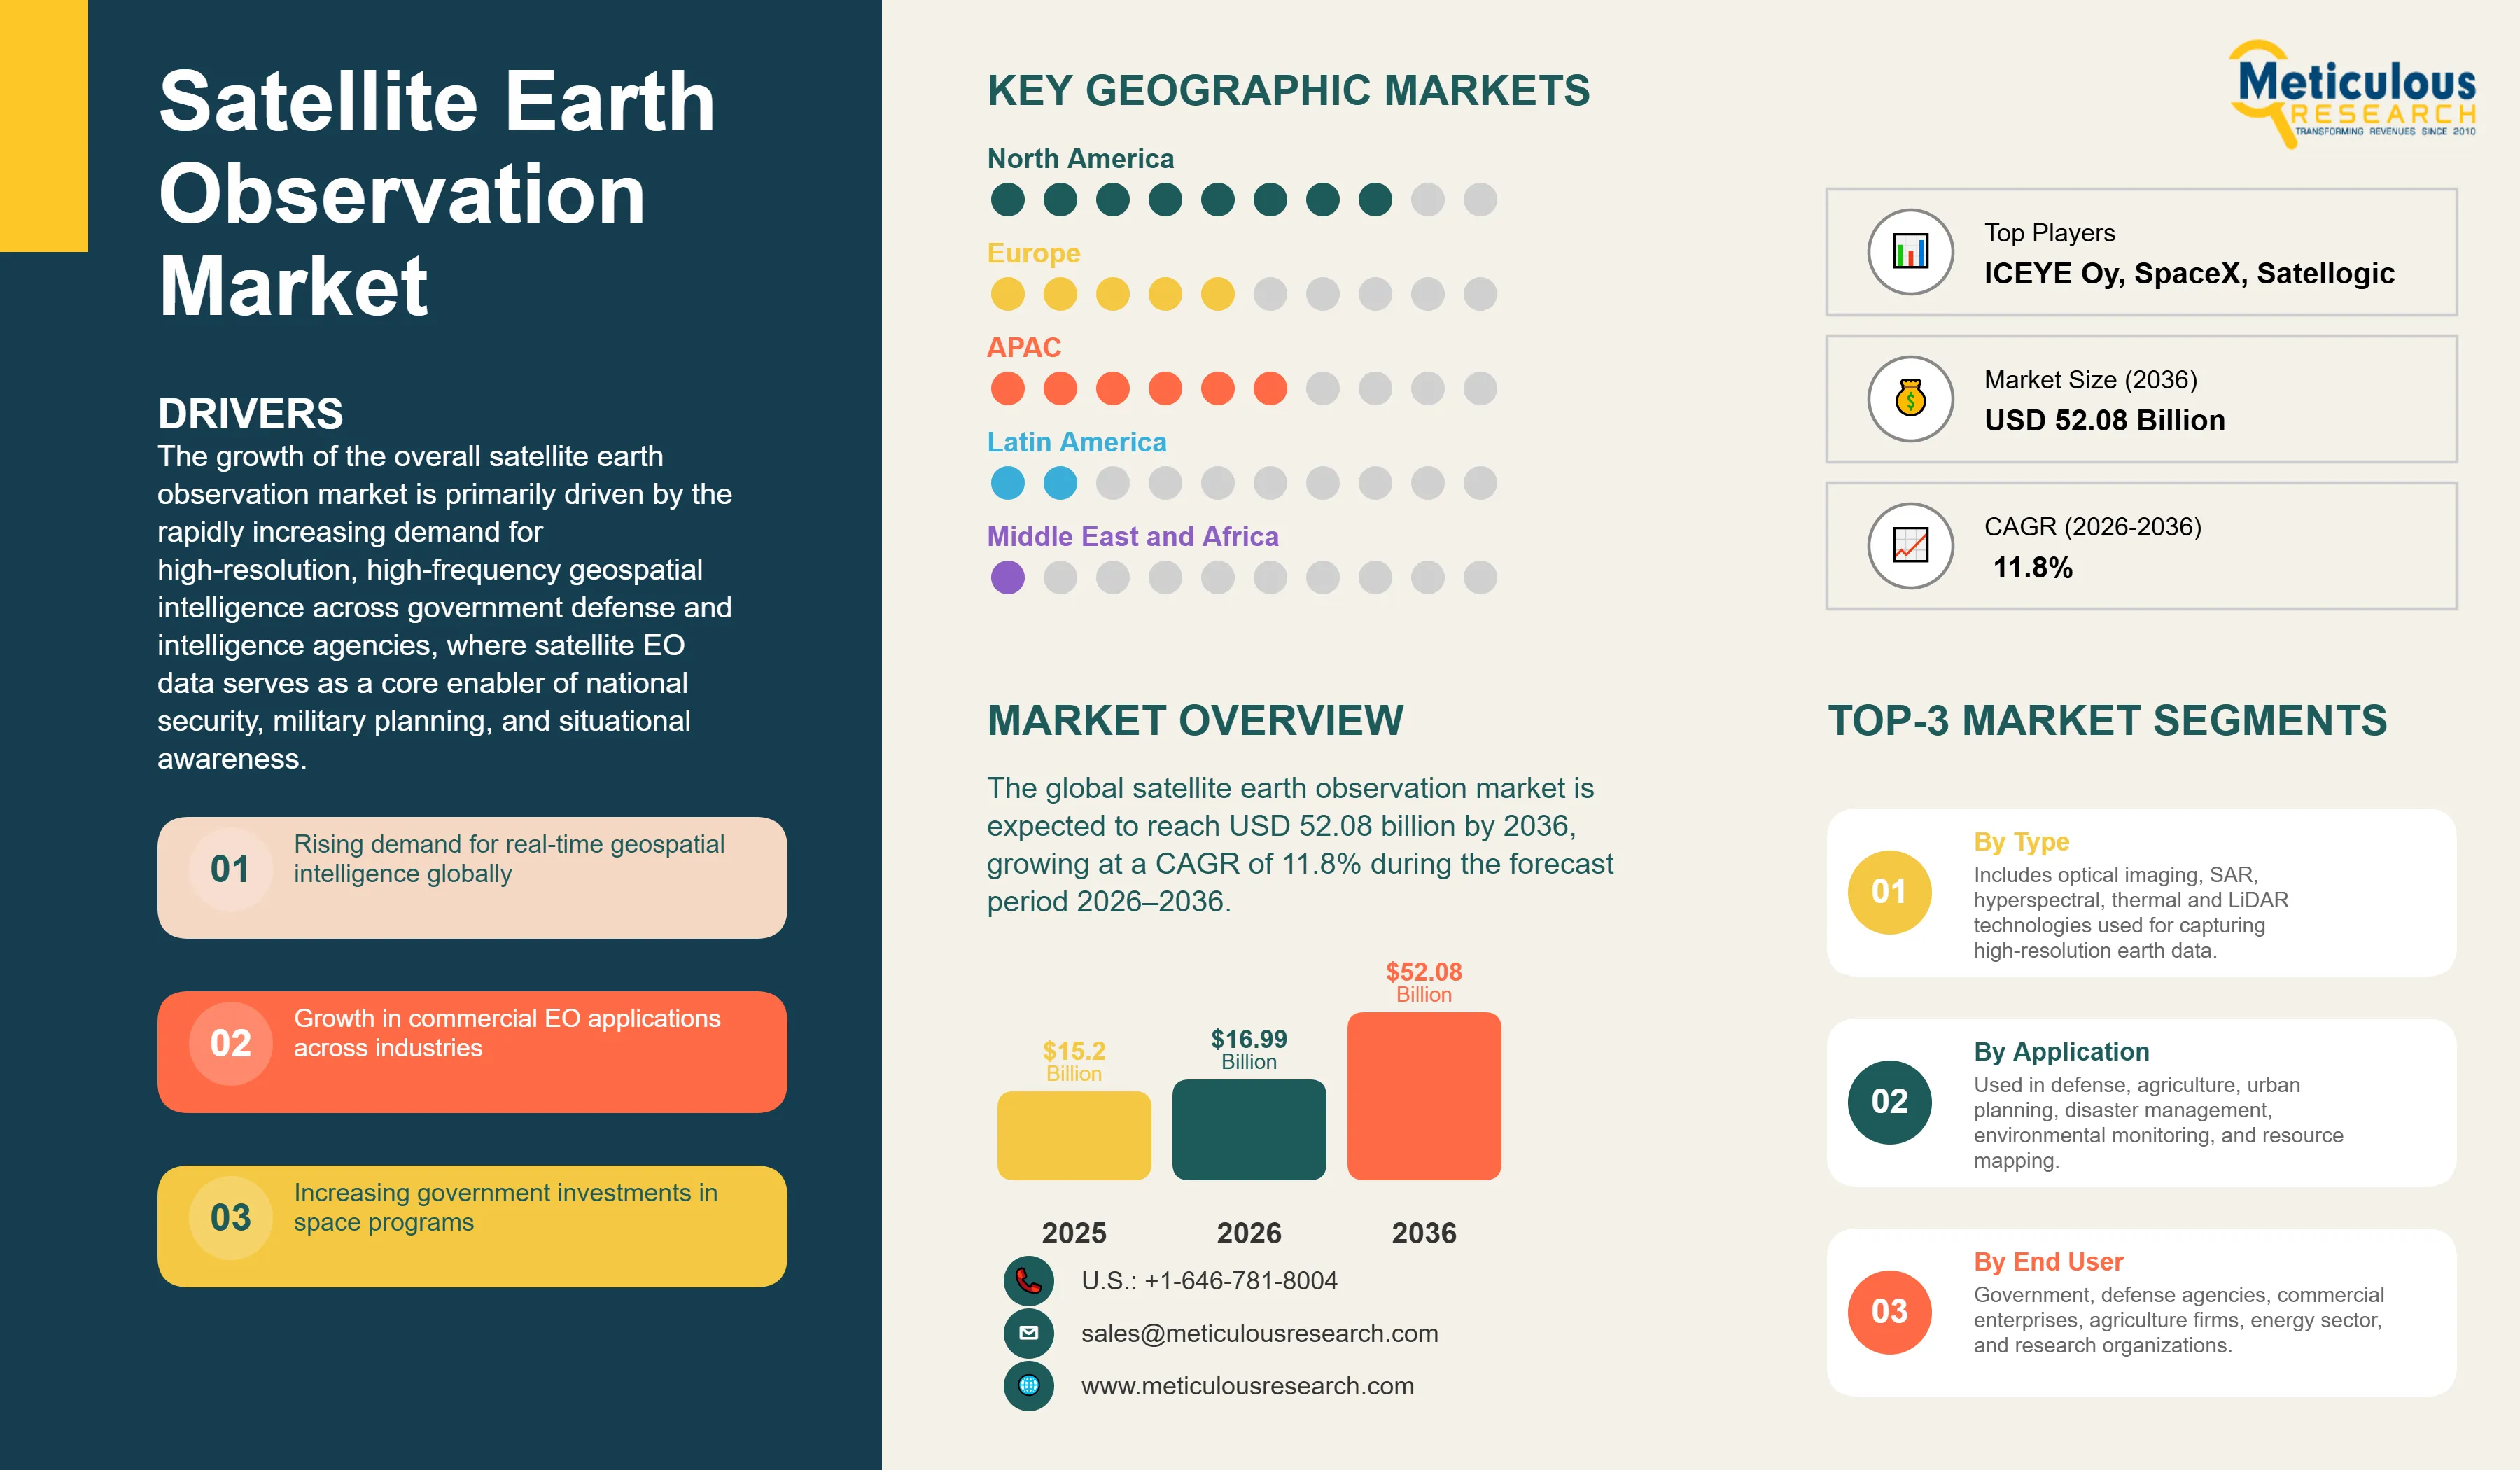
The global satellite earth observation market was valued at USD 15.20 billion in 2025. This market is expected to reach USD 52.08 billion by 2036 from an estimated USD 16.99 billion in 2026, growing at a CAGR of 11.8% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 287
- Format
- PDF + Excel
- Report ID
- MR-1868
- Base year
- 2025
- 2025 · BASELINE
- $15.20B
- 2036
- $52.08B
- CAGR 2026–2036
- 11.8%
2025 baseline · 2026–2036 forecast at 11.8% CAGR · hover a bar for the value
Key highlights
The global satellite earth observation market is projected to reach USD 52.08 billion by 2036, growing at a CAGR of 11.8% during 2026–2036.
The market was valued at USD 15.20 billion in 2025 and is estimated to reach USD 16.99 billion in 2026, reflecting strong year-on-year growth driven by expanding commercial and government demand.
The number of active Earth observation satellites continues to expand rapidly, with over 1,600 satellites in orbit by early 2026, supported primarily by the proliferation of commercial small satellite constellations accounting for the majority of new deployments.
North America is expected to dominate the market in 2026, driven by strong government funding and a mature commercial ecosystem, while Asia-Pacific is projected to register the highest growth, supported by expanding national space programs in China, India, Japan, and South Korea.
By technology, optical imaging is expected to account for the largest market share in 2026 due to its widespread use across mapping, agriculture, and environmental monitoring applications, while synthetic aperture radar (SAR) is projected to register the fastest growth owing to its all-weather, day-and-night imaging capabilities.
By component, data & services are expected to dominate the market, driven by increasing demand for value-added analytics and subscription-based EO platforms, while software (AI/ML-based analytics) is expected to witness the fastest growth.
By orbit, low Earth orbit (LEO) is expected to hold the largest share due to its suitability for high-resolution imaging and frequent revisit rates, with Very Low Earth Orbit (VLEO) emerging as a key high-growth segment.
By application, defense & intelligence and environmental monitoring are expected to account for significant shares, while precision agriculture and infrastructure monitoring are projected to grow rapidly.
By end-use, government & defense remains the dominant segment, while the commercial segment is expected to register the fastest growth driven by increasing enterprise adoption of geospatial intelligence solutions.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 52.08 Billion |
| Market Size in 2026 | USD 16.99 Billion |
| Market Size in 2025 | USD 15.20 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 11.8% |
| Format | PDF, Excel & Cloud Portal · 287 pages |
| Dominating Technology | Optical Imaging |
| Fastest Growing Technology | Synthetic Aperture Radar (SAR) |
| Dominating Orbit | Low Earth Orbit (LEO) |
| Fastest Growing Orbit | Geostationary Earth Orbit (GEO) |
| Dominating Payload Type | Imaging (Optical / Multi-Spectral) |
| Fastest Growing Payload Type | EO/IR (Electro-Optical / Infrared) |
| Dominating Application | Infrastructure & Urban Planning |
| Fastest Growing Application | Disaster Management & Response |
| Dominating End-Use | Defense & Intelligence |
| Fastest Growing End-Use | Agriculture & Environmental Monitoring |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: technology, component, orbit, payload, application, end-use.
The global satellite earth observation (EO) market comprises the integrated ecosystem of satellite systems, data products, and analytical services that enable continuous monitoring and analysis of the Earth’s surface, atmosphere, and oceans.
The market spans the full value chain, including satellite hardware (spacecraft, optical and radar payloads, and ground infrastructure), EO data products (panchromatic, multispectral, hyperspectral, SAR, and thermal infrared imagery), and value-added services such as geospatial analytics, AI-driven insights, and customized intelligence solutions delivered to government, defense, commercial, and research end users.
Key application areas include defense and intelligence, precision agriculture, urban planning, environmental monitoring, maritime surveillance, disaster management, energy and resource management, and ESG compliance.
The growth of the overall satellite earth observation market is primarily driven by the rapidly increasing demand for high-resolution, high-frequency geospatial intelligence across government defense and intelligence agencies, where satellite EO data serves as a core enabler of national security, military planning, and situational awareness. In parallel, growing commercial adoption across agriculture, insurance, energy, infrastructure, and logistics sectors, supported by declining cost per image from small satellite constellations and the proliferation of cloud-based data platforms, is significantly broadening market accessibility.
Additionally, the rising need for continuous global environmental monitoring, driven by climate change, biodiversity tracking, carbon accounting, and disaster management, is further driving demand for satellite-based observation capabilities.
However, the growth of this market is restrained by the high capital requirements associated with satellite development, launch, and ground infrastructure, along with increasing concerns around orbital congestion and space debris in low Earth orbit (LEO). Furthermore, the availability of free and open-access data from government programs such as NASA, ESA Copernicus, and ISRO limits pricing power for commercial providers in baseline imagery segments.
Key opportunities lie in the advancement of hyperspectral imaging technologies enabling detection of chemical and biological signatures for applications such as precision agriculture, environmental monitoring, and resource exploration; the growing integration of artificial intelligence and machine learning for automated analytics and real-time intelligence generation; and the rising demand for satellite-verified data to support ESG reporting and sustainability compliance.
Furthermore, the emergence of Very Low Earth Orbit (VLEO) constellations, enabling higher revisit frequency and near-continuous monitoring capabilities, is a major trend shaping the evolution of the global satellite earth observation market.
Report infographic
Market dynamics
3 factors across 1 forceAI-Driven Geospatial Intelligence Transforming Raw Imagery into Real-Time Decision Support
The integration of artificial intelligence (AI) and machine learning (ML) into satellite earth observation (EO) data pipelines is a key trend transforming the market from a raw imagery supply model to a high-value geospatial intelligence services ecosystem. Competitive differentiation is increasingly defined by the speed, accuracy, and actionability of AI-driven insights rather than satellite hardware capabilities alone.
Leading operators are embedding AI directly into their processing workflows to enable automated, large-scale analytics. Maxar Technologies, Inc. has integrated AI-enabled capabilities such as change detection, object classification, and damage assessment across its high-resolution imagery platforms, significantly reducing analysis time and enhancing operational decision-making. BlackSky Technology, Inc. is advancing AI-native architectures through its next-generation satellite systems designed for high-frequency monitoring and real-time analytics applications, including dynamic mapping and situational awareness.
In parallel, specialized analytics firms are driving this shift by developing application-specific AI platforms. Companies such as EOS Data Analytics are delivering advanced solutions for precision agriculture, combining satellite imagery with crop classification, yield prediction, and field-level monitoring. Emerging players, including Satellogic Inc., are exploring AI-driven data interaction models to simplify the use of high-resolution imagery and enable rapid application development across industries.
This evolution is enabling the emergence of subscription-based analytics models with higher customer stickiness and recurring revenue streams, gradually replacing transactional imagery sales.
As EO data becomes increasingly integrated into operational workflows across defense, agriculture, infrastructure monitoring, and supply chain intelligence, AI-driven geospatial insights are becoming central to value creation in the satellite earth observation market.
SAR Constellation Proliferation Enabling All-Weather Real-Time Monitoring
The rapid expansion of commercial Synthetic Aperture Radar (SAR) satellite constellations, capable of penetrating cloud cover, operating in complete darkness, and detecting surface deformation with high sensitivity, is significantly broadening the applicability of satellite earth observation beyond the limitations of optical, weather-dependent imaging systems. This capability is particularly critical for mission-critical applications requiring continuous monitoring, including maritime surveillance, disaster response, and infrastructure assessment.
Leading operators are scaling SAR constellations to deliver high-revisit, all-weather imaging. ICEYE Oy has expanded its constellation to enhance coverage for applications such as flood monitoring and maritime domain awareness, while Capella Space Corp. continues to strengthen its position in defense-focused intelligence through high-resolution SAR data and government partnerships. These developments indicate SAR’s growing importance in both commercial and defense segments.
SAR satellites are accounting for an increasing share of new EO satellite deployments, reflecting rising investments from both public and private stakeholders in radar-based imaging technologies. The ability to generate reliable, high-frequency data irrespective of atmospheric conditions is driving adoption across sectors where optical limitations previously constrained use cases.
Furthermore, the integration of SAR and optical data is emerging as a key value driver, combining the weather independence and structural sensitivity of SAR with the visual interpretability of optical imagery. This multi-sensor data fusion approach is enabling advanced analytics and premium applications, including flood risk modeling, infrastructure health monitoring, and precision agriculture, thereby enhancing the overall value proposition of satellite earth observation services.
Hyperspectral and Specialized Sensor Payloads Opening High-Margin New Vertical Markets
The commercialization of hyperspectral imaging satellites, capable of capturing hundreds of contiguous spectral bands compared to conventional multispectral systems, is enabling a new class of satellite EO applications based on precise chemical and material identification. This capability allows for surface fingerprinting of minerals, vegetation health, pollutants, and other environmental indicators, significantly reducing reliance on ground-based surveys and laboratory analysis.
Emerging players such as Pixxel Space Technologies Pvt. Ltd. are advancing high-resolution hyperspectral constellations targeting applications in mineral exploration, precision agriculture, environmental monitoring, and carbon assessment. These systems enable detection of subtle spectral variations, supporting use cases such as nutrient mapping, soil analysis, and pollution tracking with a level of granularity not achievable with traditional optical imaging.
In parallel, GHGSat Inc. is pioneering satellite-based greenhouse gas monitoring, offering high-resolution detection of methane and carbon dioxide emissions at the point-source level. This capability is increasingly critical for regulatory compliance, emissions accountability, and carbon market verification, particularly as ESG reporting requirements and climate disclosure frameworks continue to expand globally.
These specialized sensor payloads are enabling the development of high-value, application-specific verticals within the EO market. Compared to standard multispectral imagery, hyperspectral and emissions-monitoring data command premium pricing due to their unique analytical capabilities and direct applicability in revenue-generating use cases. As demand grows across industries such as mining, agriculture, and environmental compliance, hyperspectral and specialized EO solutions are expected to represent a rapidly expanding, high-margin segment of the global satellite earth observation market.
Table of contents
14 chapters · 168 sections · 287 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Technology | Optical Imaging | Hyperspectral |
| By Orbit | LEO | Low Earth orbit (LEO) |
| By Application | Infrastructure & Urban Planning | — |
| By Segmental | — | Disaster management |
By Technology
- Optical Imaging to Dominate the Global Satellite EO Market
- The optical imaging segment is expected to account for the largest share of the market.
- The dominance of this segment is primarily attributed to the ability of optical satellites to deliver high-resolution, visually intuitive imagery that is easily interpretable by both human analysts and AI-based systems.
- Optical data, mainly RGB and multispectral imagery, integrates seamlessly with GIS platforms and analytics workflows, making it suitable for a wide range of applications, including urban planning, agriculture monitoring, infrastructure inspection, and disaster assessment.
- Leading operators such as Maxar Technologies, Inc. (WorldView Legion), Planet Labs PBC (SuperDove constellation), and Airbus Defence and Space (Pléiades Neo) continue to expand high-resolution optical imaging capabilities, supporting strong commercial and government demand.
- Within optical imaging, the hyperspectral sub-segment is expected to register the fastest growth, driven by its ability to capture detailed spectral signatures for advanced applications such as mineral identification, precision agriculture, and environmental monitoring.
- However, the SAR segment is projected to witness the highest growth during the forecast period.
- This growth is driven by SAR’s ability to capture imagery independent of weather conditions and lighting, making it critical for applications such as maritime surveillance, disaster monitoring, infrastructure assessment, and defense intelligence.
- Additionally, advanced techniques such as interferometric SAR (InSAR) enable detection of minute surface deformations, supporting use cases in infrastructure risk monitoring, geohazard detection, and resource management that cannot be effectively addressed through optical imaging alone.
By Orbit
- LEO to Hold the Largest Market Share
- LEO is expected to account for the largest market share, with the sub-600 km segment alone contributing a significant portion of total EO deployments.
- This dominance is driven by LEO satellites’ ability to deliver high spatial resolution, frequent revisit rates, and lower deployment costs, making them the preferred orbit for commercial earth observation missions.
- Satellites operating in the 300–600 km range can achieve sub-meter resolution with relatively small payloads, enabling cost-efficient constellation models.
- The rapid expansion of commercial small satellite constellations, driven by the availability of cost-effective rideshare launch services from players such as SpaceX, has further accelerated LEO adoption across both commercial and government segments.
- In contrast, MEO plays a relatively limited role in EO applications due to its trade-off between coverage and resolution, and is primarily utilized for navigation systems rather than high-resolution imaging.
- However, the GEO segment is expected to register steady growth during the forecast period.
- GEO satellites provide continuous, fixed-area coverage, making them particularly suitable for applications such as weather monitoring, environmental observation, and persistent regional surveillance.
- While GEO systems typically offer lower spatial resolution compared to LEO, ongoing advancements in sensor technologies are improving imaging capabilities, enhancing their relevance for applications where continuous temporal coverage is more critical than high spatial detail.
- Overall, the market is expected to remain LEO-centric, with GEO complementing LEO constellations in applications requiring persistent monitoring and broad-area coverage.
By Application
- Infrastructure & Urban Planning to Hold the Largest Share
- The infrastructure & urban planning segment is expected to account for the largest share of the overall satellite earth observation market.
- This dominance is driven by the increasing use of satellite imagery for urban expansion planning, transportation network development, smart city initiatives, and large-scale infrastructure monitoring.
- The EO data is extensively utilized by governments and private stakeholders for construction progress tracking, asset monitoring, land-use mapping, and post-event infrastructure assessment.
- The integration of satellite data with GIS platforms, digital twins, and urban analytics systems is further enhancing its role in long-term planning and real-time decision-making across infrastructure projects.
By Segmental
- Environmental monitoring remains a core application area, supported by rising demand for climate tracking, deforestation monitoring, and carbon accounting.
- Surveillance & security continues to be a significant contributor, particularly in defense, border monitoring, and intelligence applications.
- Energy & natural resource management is gaining traction with increasing use of EO in mining, oil & gas monitoring, and renewable energy site assessment.
- However, the disaster management segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing frequency and severity of climate-related events, including floods, wildfires, hurricanes, and earthquakes, which are driving demand for real-time monitoring, early warning systems, and rapid damage assessment.
- Satellite EO plays a critical role in disaster response by enabling large-area damage assessment, population displacement tracking, and coordination of emergency operations.
- Additionally, the growing adoption of EO data in the insurance sector for catastrophe modeling, risk assessment, and claims verification is further strengthening demand in disaster-related applications.
Geographic analysis
North America
Largest shareNorth America is expected to account for the largest share of the global satellite earth observation market in 2026, driven by strong government-backed programs and a highly developed commercial ecosystem. The U.S. market is characterized by strong regional leadership driven by long-standing civil and defense initiatives led by agencies such as NASA, NOAA, USGS, and NGA, supporting continuous demand for EO data across environmental monitoring, weather forecasting, and geospatial intelligence applications. In parallel, the presence of leading commercial players, such as Maxar Technologies, Inc., Planet Labs PBC, BlackSky Technology, Inc., Capella Space Corp., Spire Global, Inc., and Satellogic Inc., ensures strong commercial adoption across defense, intelligence, and enterprise applications. The ongoing procurement from defense and intelligence agencies, along with increasing integration of commercial EO data into government workflows, continues to drive the growth of the satellite earth observation market in the region.
Asia-Pacific
Fastest growthThe Asia-Pacific satellite earth observation market is poised to grow at the fastest CAGR during the forecast period, driven by expanding national space programs, increasing private sector participation, and rising demand for EO applications across agriculture, urban planning, and maritime monitoring. China leads regional growth through large-scale government-backed missions and the expansion of commercial constellations, while India is strengthening its capabilities through ISRO-led programs and growing private sector initiatives. Japan and South Korea are advancing through established satellite programs and emerging SAR-focused companies, while Southeast Asian countries are increasingly adopting EO solutions for resource management and disaster monitoring. Overall, strategic focus on space sovereignty, combined with growing application demand and investments in next-generation satellite technologies, is driving the growth of the satellite earth observation market in Asia-Pacific.
Competitive landscape
- Maxar Technologies, Inc.
- Planet Labs PBC
- Airbus Defence and Space
- ICEYE Oy
- Capella Space Corp.
- BlackSky Technology, Inc.
- Spire Global, Inc.
- Satellogic Inc.
- L3Harris Technologies, Inc.
- Thales Alenia Space
- Pixxel Space Technologies Pvt. Ltd.
- ImageSat International N.V.
- GHGSat Inc.
- Satrec Initiative Co., Ltd.
- Surrey Satellite Technology Ltd.
- SpaceX
- Northrop Grumman Corporation
- Orbital Insight
- Leonardo S.p.A
Frequently asked questions
The global satellite earth observation market was valued at USD 15.20 billion in 2025. This market is expected to reach USD 52.08 billion by 2036 from an estimated USD 16.99 billion in 2026, growing at a CAGR of 11.8% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Satellite Earth Observation Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1868). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/satellite-earth-observation-market-6551