Drug Delivery in Cancer Market (2026-2036)
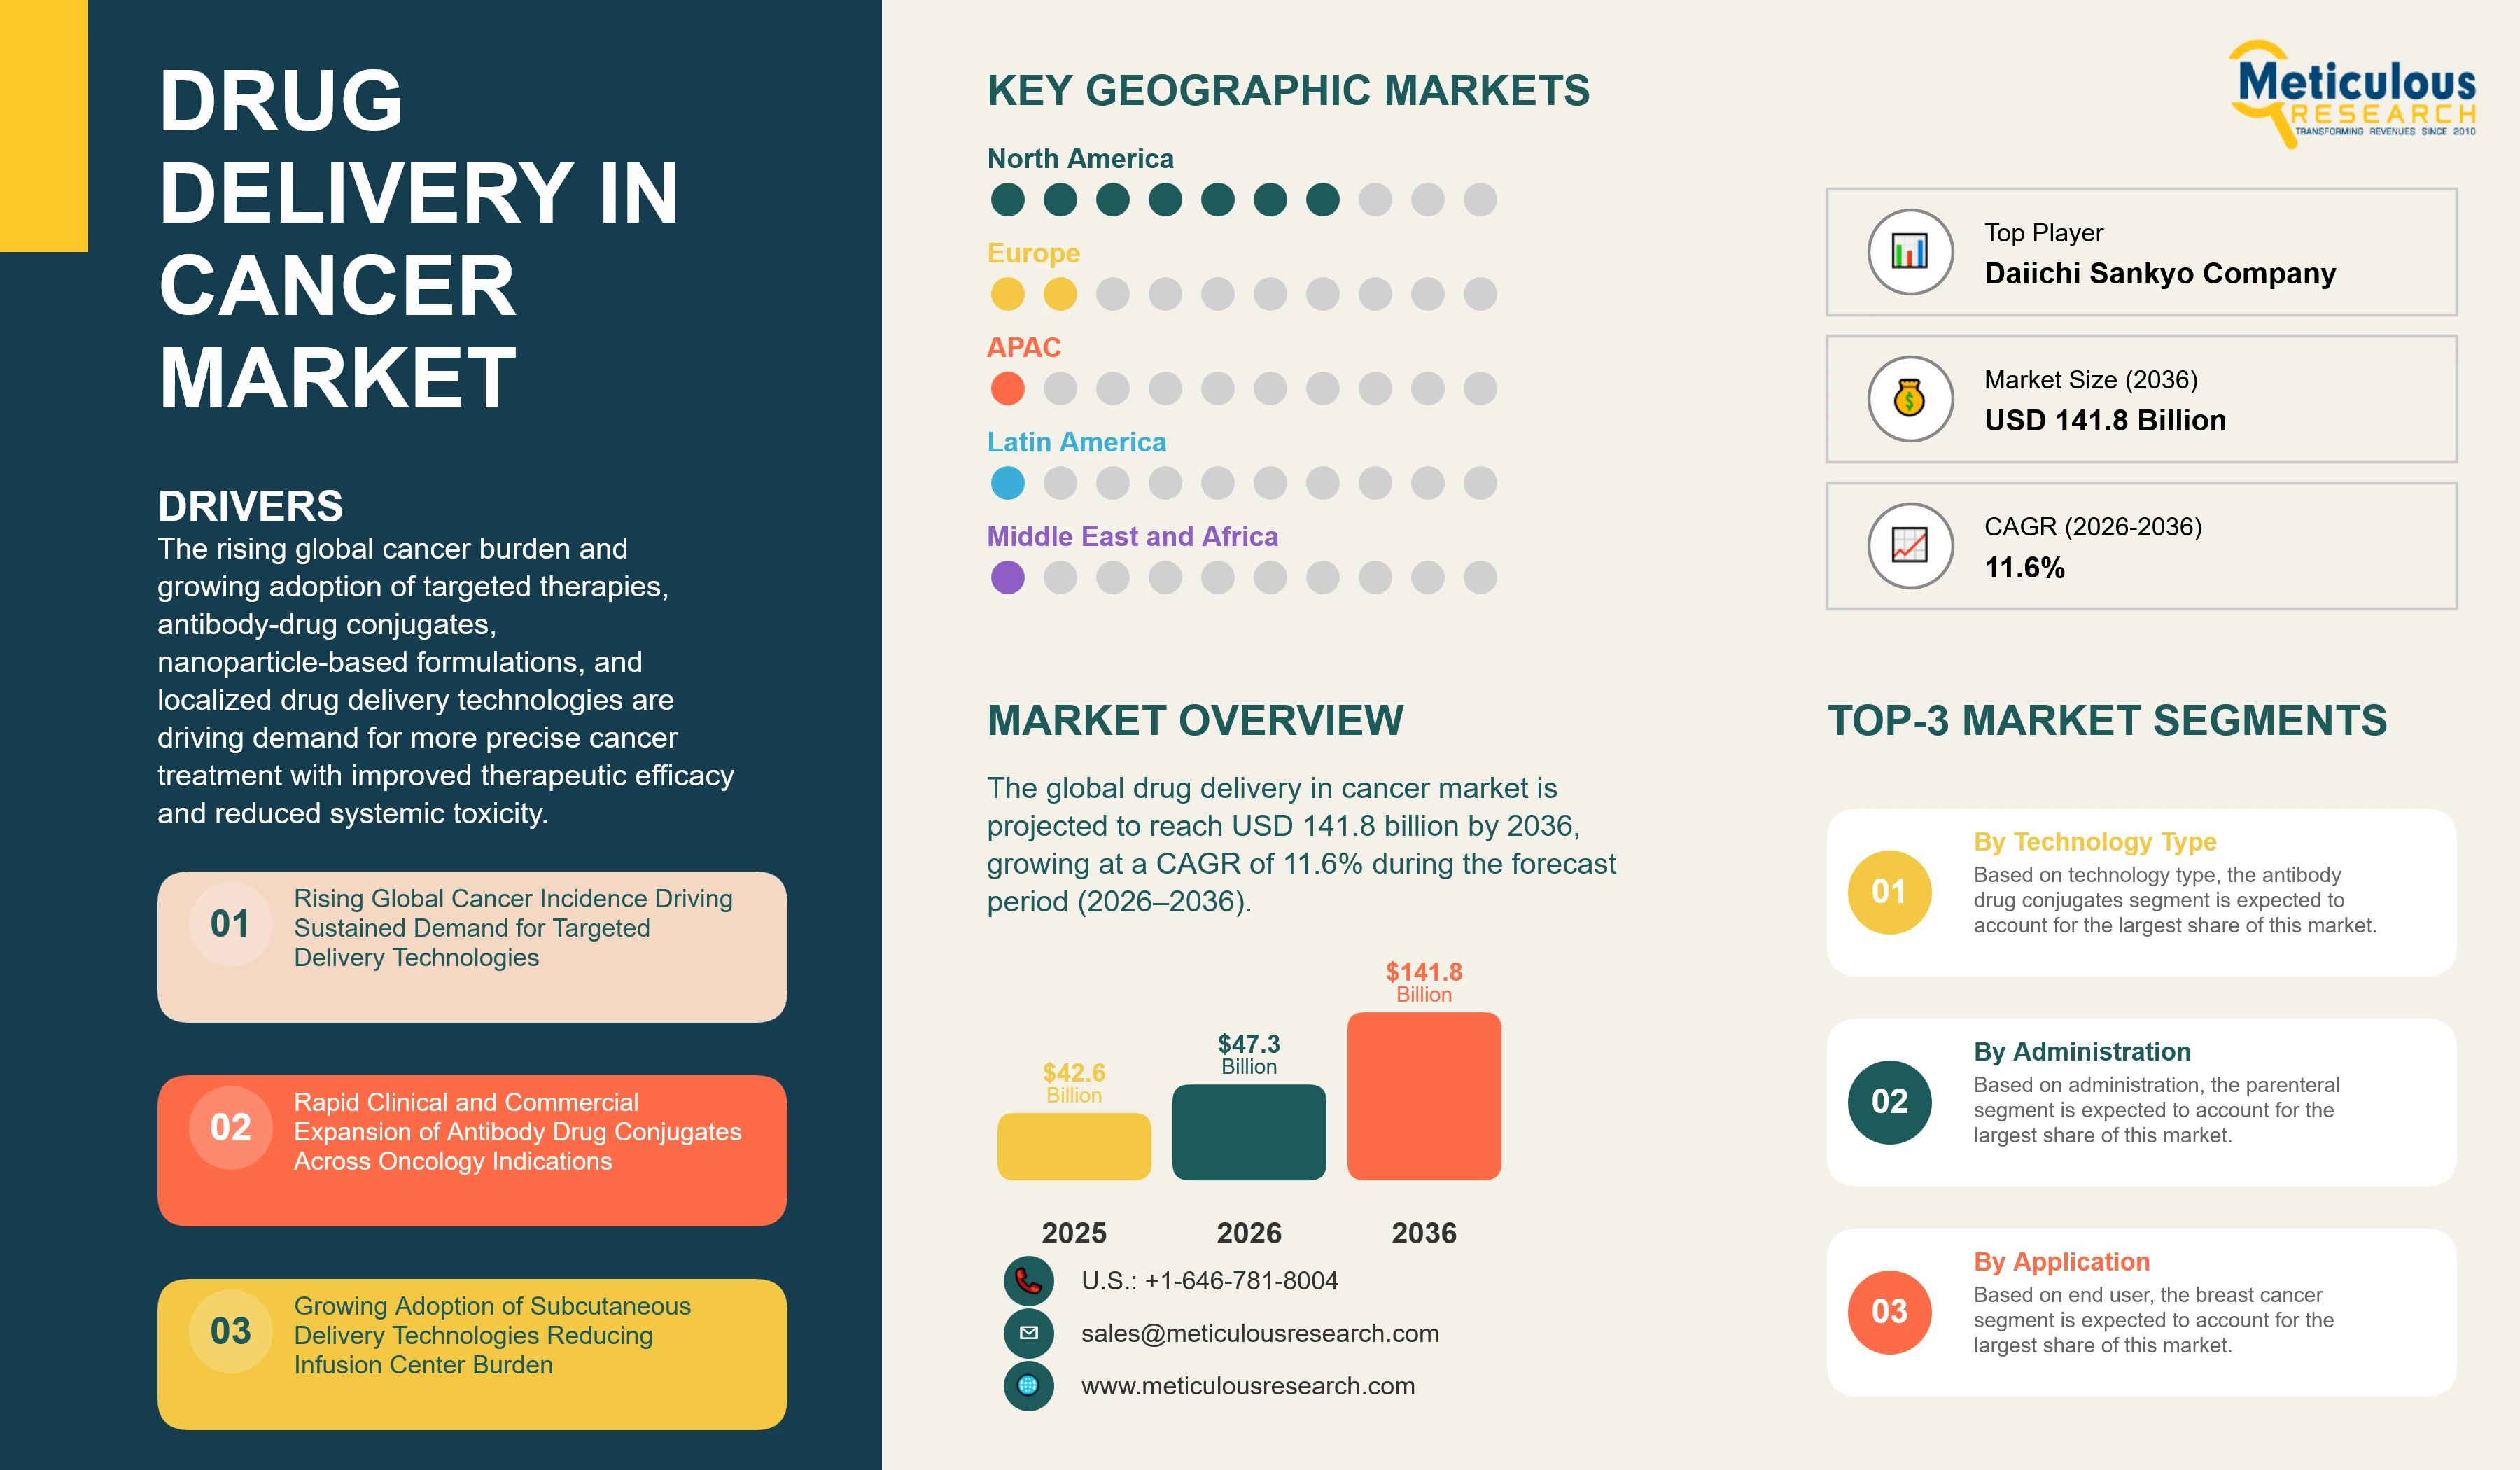
The global drug delivery in cancer market was valued at USD 42.6 billion in 2025. The market is projected to reach USD 141.8 billion by 2036, growing from USD 47.3 billion in 2026 at a CAGR of 11.6% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 316
- Format
- PDF + Excel
- Report ID
- MR-2148
- Base year
- 2025
- 2025 · BASELINE
- $42.60B
- 2036
- $141.8B
- CAGR 2026–2036
- 11.6%
2025 baseline · 2026–2036 forecast at 11.6% CAGR · hover a bar for the value
Key highlights
The global drug delivery in cancer market is projected to reach USD 141.8 billion by 2036.
The market is expected to grow at a CAGR of 11.6% during the forecast period 2026–2036.
The total drug delivery in cancer market was valued at USD 42.6 billion in 2025 and is estimated to reach USD 47.3 billion in 2026.
North America is expected to dominate this market with the largest revenue share in 2026, driven by the concentration of antibody drug conjugate and cell therapy manufacturers headquartered in the region, the highest per capita oncology treatment spending globally, and the presence of a well-established interventional oncology infrastructure across major cancer centers.
Asia Pacific is projected to witness the fastest revenue growth during the forecast period, driven by the rising cancer patient pool across China, India, Japan, and South Korea, growing domestic biologics and biosimilar manufacturing capacity, and expanding government cancer care access programs.
By technology, the antibody drug conjugates segment is expected to hold the largest share of the market in 2026, driven by an expanding number of approved conjugates and their rapid uptake across breast, lung, and blood cancer treatment protocols.
By technology, the liposomal and lipid based delivery systems segment is projected to register the highest growth during the forecast period, supported by an expanding pipeline of lipid nanoparticle formulated oncology therapeutics.
By route of administration, the parenteral segment is expected to account for the largest share of the market in 2026, reflecting the continued dominance of intravenous and subcutaneous administration for biologic and cytotoxic cancer therapeutics.
By route of administration, the subcutaneous delivery segment is projected to register the highest growth during the forecast period, driven by the ongoing shift of intravenous biologic regimens toward subcutaneous formulations that reduce infusion chair time.
By application, the breast cancer segment is expected to account for the largest share in 2026, while the blood cancer segment is projected to register the highest CAGR during the forecast period.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 141.8 Billion |
| Market Size in 2026 | USD 47.3 Billion |
| Market Size in 2025 | USD 42.6 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 11.6% |
| Format | PDF, Excel & Cloud Portal · 316 pages |
| Dominating Technology | Antibody Drug Conjugates |
| Fastest Growing Technology | Liposomal and Lipid Based Delivery Systems |
| Dominating Route of Administration | Parenteral |
| Fastest Growing Route of Administration | Subcutaneous |
| Dominating Application | Breast Cancer |
| Fastest Growing Application | Blood Cancer |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: technology, route of administration, application.
The global drug delivery in cancer market encompasses technologies, devices, and formulation platforms designed to deliver therapeutic agents to tumors and cancer-affected tissues with greater precision, controlled release, and reduced systemic exposure. The market includes antibody-drug conjugates (ADCs), liposomal and lipid-based delivery systems, polymeric nanoparticles and micelles, drug-eluting embolic systems, infusion and injectable delivery systems, and implantable drug delivery systems across breast, lung, colorectal, liver, prostate, and hematological cancers.
Market growth is driven by the rising global cancer burden and increasing demand for treatments that improve therapeutic efficacy while limiting treatment-related toxicity. According to the International Agency for Research on Cancer (IARC), approximately 20 million new cancer cases and 9.7 million cancer-related deaths were estimated globally in 2022, with the burden expected to increase substantially as populations grow and age. This growing patient population is supporting demand for targeted and localized drug delivery technologies.
ADCs have become a major growth area by combining monoclonal antibodies with cytotoxic payloads to enable targeted drug delivery. Commercial successes such as Enhertu and Padcev have accelerated investment in the technology, including Pfizer's acquisition of Seagen and AbbVie's acquisition of ImmunoGen. Meanwhile, drug-eluting embolic systems enable localized delivery of chemotherapy to tumors, particularly in interventional oncology applications.
Advances in nanoparticle formulations, subcutaneous delivery technologies, and implantable systems are further expanding the market. However, complex manufacturing requirements, high development costs, specialized payload and linker production, regulatory requirements, and reimbursement challenges remain key constraints. Increasing oncology manufacturing capacity in Asia Pacific and the region's growing cancer burden are expected to create significant opportunities for advanced drug delivery platforms.
Report infographic
Market dynamics
3 factors across 1 forceAntibody Drug Conjugates Redefining Targeted Payload Delivery Across Solid Tumors and Hematological Malignancies
The rapid commercial maturation of antibody drug conjugates represents the most significant technology shift currently reshaping the drug delivery in cancer market. By combining a monoclonal antibody's antigen specificity with a highly potent cytotoxic payload linked through an engineered chemical bridge, this modality allows oncologists to deliver cell killing agents that would be too toxic for systemic administration directly to antigen expressing tumor cells.
Products such as Daiichi Sankyo Company, Limited's Enhertu, co-developed and commercialized with AstraZeneca plc, and Pfizer Inc.'s Padcev have expanded conjugate use well beyond their original indications, with ongoing trials evaluating conjugate combinations with checkpoint inhibitors and other targeted agents across earlier lines of therapy. Genentech, Inc., a member of the Roche Group, and Gilead Sciences, Inc. continue to expand approved indications for Kadcyla, Polivy, and Trodelvy, while AbbVie Inc.'s Elahere has established a position in ovarian cancer treatment following the company's acquisition of ImmunoGen, Inc.
This growth is placing significant demand on specialized bioconjugation manufacturing capacity. Lonza Group AG has announced capacity expansion at its Singapore facility to address rising commercial and clinical demand for conjugate manufacturing, reflecting the broader capacity constraints facing the sector as more conjugates advance through clinical development and toward approval.
Locoregional and Embolic Delivery Technologies Establishing Standard of Care Positions in Liver Directed Cancer Therapy
Drug eluting embolic beads and microspheres have moved from a niche interventional technique to an established treatment pathway for hepatocellular carcinoma and liver metastases from colorectal cancer, where interventional radiologists deliver chemotherapeutic agents directly into the tumor's blood supply through catheter based access.
Boston Scientific Corporation's DC Bead and LC Bead platforms, Merit Medical Systems, Inc.'s HepaSphere microspheres, and Terumo Corporation's LifePearl beads each allow drug loading prior to embolization, with the bead subsequently eluting a controlled and sustained chemotherapy dose to the tumor while restricting blood flow to the malignant tissue. This dual mechanism, combining ischemic and chemotherapeutic tumor injury, has driven continued clinical adoption relative to conventional chemoembolization approaches.
Manufacturers in this segment continue to expand their interventional oncology portfolios through both internal development and acquisition, exemplified by Boston Scientific Corporation's acquisition of Obsidio, Inc. to add gel embolic material technology to its existing embolization offering, reinforcing the competitive importance of a broad locoregional delivery portfolio.
Subcutaneous Delivery Technologies and Nanoparticle Platforms Reducing Treatment Burden and Expanding Formulation Options
The migration of intravenous biologic oncology regimens toward subcutaneous administration is reshaping how cancer therapeutics reach patients, driven by enzymatic delivery technologies that temporarily modify the extracellular matrix under the skin to permit rapid absorption of large volume biologic doses that would otherwise require infusion. Halozyme Therapeutics, Inc.'s ENHANZE drug delivery technology has been licensed by multiple oncology drug developers to convert existing intravenous antibody therapies into subcutaneous formulations, reducing administration time from hours to minutes and easing capacity pressure on infusion centers.
In parallel, lipid based and polymeric nanoparticle platforms continue to expand the range of deliverable oncology payloads. Liposomal formulations such as Jazz Pharmaceuticals plc's Vyxeos and Ipsen S.A.'s Onivyde encapsulate cytotoxic agents within lipid vesicles engineered to accumulate preferentially in tumor tissue through the enhanced permeability of tumor vasculature, improving the therapeutic window relative to the free drug. Contract development and manufacturing organizations including Evonik Industries AG and Catalent, Inc., a Novo Holdings company, continue to expand polymer and lipid excipient manufacturing capacity to support this growing pipeline of nanoparticle formulated oncology therapeutics moving through clinical development.
Table of contents
11 chapters · 124 sections · 316 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Technology | Antibody Drug Conjugates | Liposomal and lipid based delivery systems |
| By Route of Administration | Parenteral | Subcutaneous delivery |
| By Application | Breast Cancer | Blood cancer |
By Technology
- The antibody drug conjugates segment is expected to account for the largest share of this market.
- The leading position of this segment is attributed to the expanding number of approved conjugates across breast, lung, urothelial, and hematological cancer indications, continued label expansion of established products into earlier treatment lines, and sustained investment by large pharmaceutical companies seeking to secure conjugate platforms through acquisition and licensing.
- However, the liposomal and lipid based delivery systems segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by an expanding clinical pipeline of lipid nanoparticle formulated oncology therapeutics, growing use of liposomal encapsulation to improve the therapeutic window of established cytotoxic agents, and continued manufacturing capacity investment by contract development organizations supporting this formulation class.
By Route of Administration
- The Parenteral Segment to Hold the Largest Share
- The parenteral segment is expected to account for the largest share of this market.
- The growth of this segment is driven by the continued dominance of intravenous administration for biologic and cytotoxic cancer therapeutics, where precise dose control and direct systemic access remain clinically necessary for a large share of approved oncology treatments.
- However, the subcutaneous delivery segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the ongoing conversion of established intravenous biologic regimens to subcutaneous formulations, growing adoption of enzymatic delivery technologies that enable large volume subcutaneous dosing, and the reduced treatment center burden and improved patient convenience associated with subcutaneous administration relative to lengthy infusion sessions.
By Application
- The Breast Cancer Segment to Hold the Largest Share
- The breast cancer segment is expected to account for the largest share of this market, reflecting the high global incidence of the disease and the concentration of approved antibody drug conjugates and liposomal formulations developed specifically for HER2 positive and triple negative breast cancer treatment.
- However, the blood cancer segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the expanding use of antibody drug conjugates and cell based delivery approaches in leukemia, lymphoma, and multiple myeloma treatment, alongside a growing pipeline of targeted delivery candidates advancing through clinical development for hematological malignancies.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the market. The region's leading position is supported by the strong concentration of oncology and biologics developers in the U.S., advanced cancer treatment infrastructure, extensive interventional oncology capabilities, and strong regulatory and clinical research ecosystems. The presence of major companies such as Boston Scientific Corporation, Merit Medical Systems, Gilead Sciences, Inc., and Pfizer Inc., together with substantial investment in oncology research and development, further strengthens the regional market.
Asia-Pacific
Fastest growthAsia Pacific is expected to register the fastest growth from 2026 to 2036. Growth is supported by the region's large and increasing cancer burden, expanding healthcare expenditure, improving access to advanced cancer therapies, and growing pharmaceutical and biologics manufacturing capabilities across China, India, Japan, and South Korea. Government initiatives to expand cancer screening and treatment infrastructure are also supporting adoption of advanced drug delivery technologies.
Europe
Europe represents a mature market, supported by established oncology care infrastructure, strong pharmaceutical and biotechnology capabilities, clinical research activity, and supportive regulatory frameworks. Companies such as Lonza Group AG and Evonik Industries AG contribute to the region's drug-development, formulation, and manufacturing ecosystem.
Middle East & Africa
The Middle East and Africa represent emerging markets, supported by increasing investment in specialized oncology infrastructure, particularly in Saudi Arabia and the UAE.
Latin America
Latin America is also expected to expand as cancer treatment access improves in Brazil, Mexico, and other major markets, alongside increasing adoption of advanced oncology and interventional treatment approaches.
Competitive landscape
- Daiichi Sankyo Company, Limited
- AstraZeneca plc
- Pfizer Inc.
- Gilead Sciences, Inc.
- AbbVie Inc.
Frequently asked questions
The global drug delivery in cancer market is expected to reach USD 141.8 billion by 2036 from an estimated USD 47.3 billion in 2026, at a CAGR of 11.6% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Drug Delivery in Cancer Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-2148). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/drug-delivery-in-cancer-market-6831