Microneedle Drug Delivery Systems Market (2026-2036)
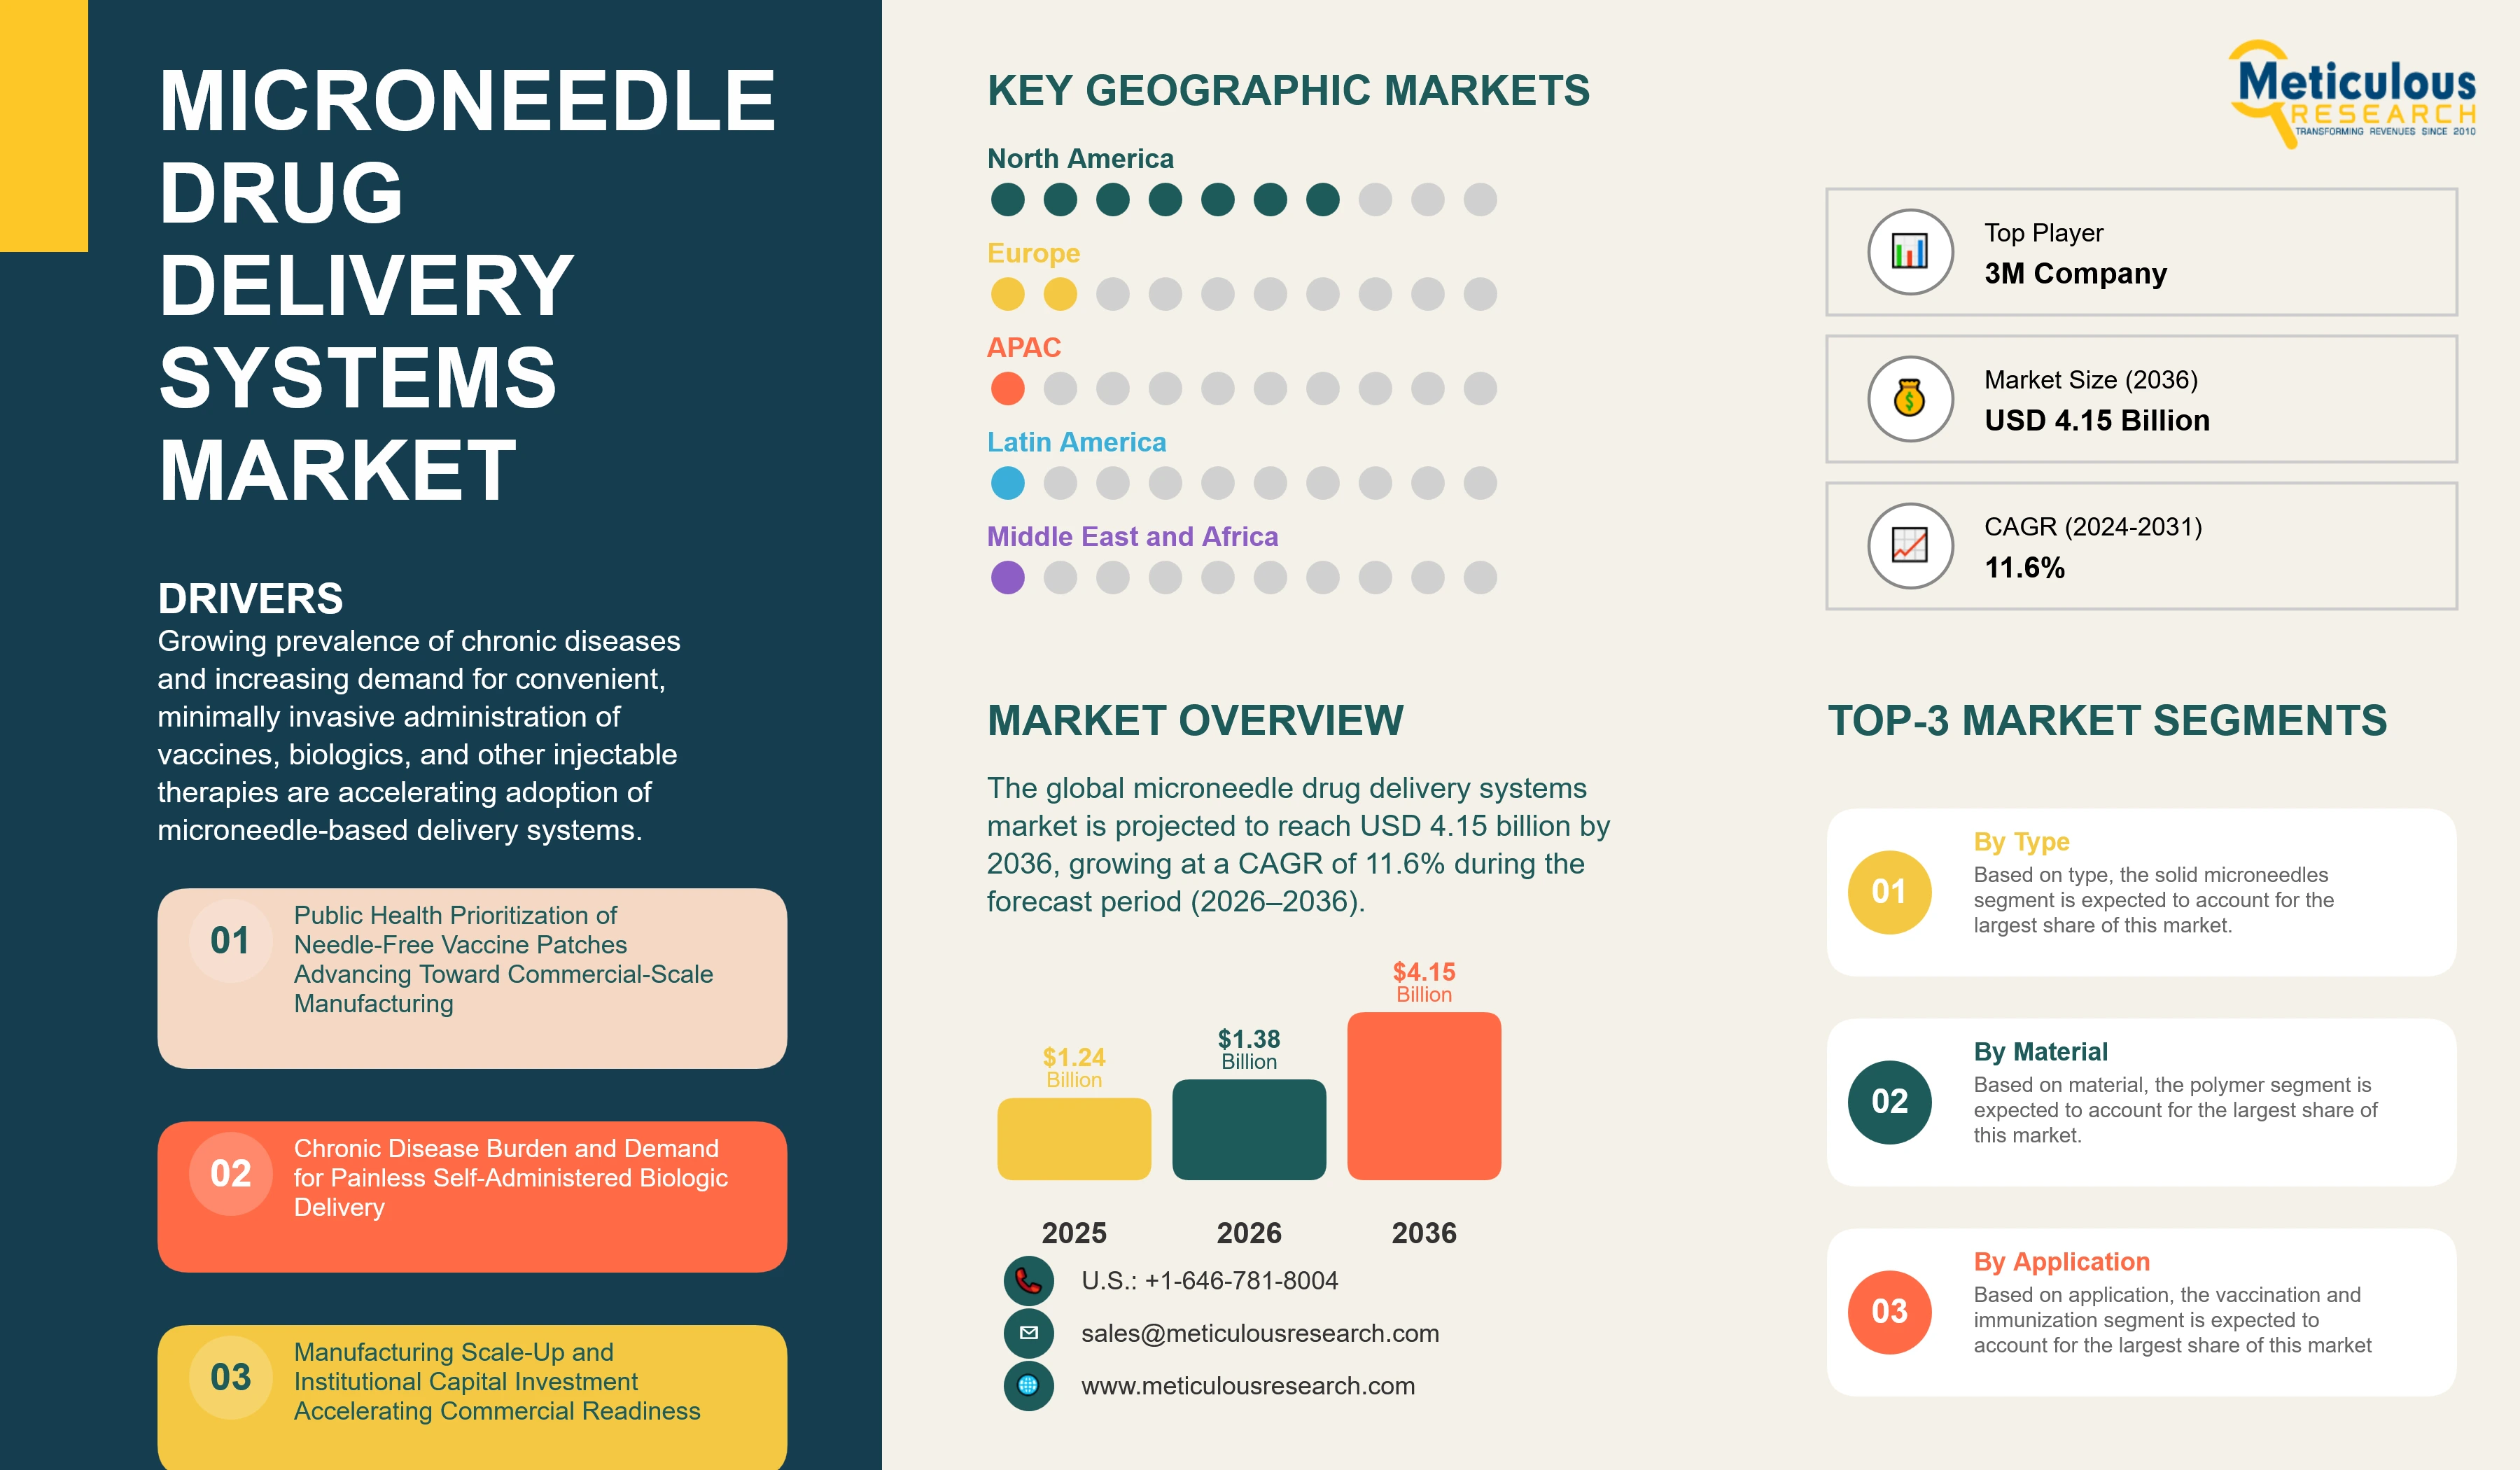
The global microneedle drug delivery systems market was valued at USD 1.24 billion in 2025. The market is projected to reach USD 4.15 billion by 2036, growing from USD 1.38 billion in 2026 at a CAGR of 11.6% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 306
- Format
- PDF + Excel
- Report ID
- MR-2131
- Base year
- 2025
- 2025 · BASELINE
- $1.24B
- 2036
- $4.15B
- CAGR 2026–2036
- 11.6%
2025 baseline · 2026–2036 forecast at 11.6% CAGR · hover a bar for the value
Key highlights
The global microneedle drug delivery systems market is projected to reach USD 4.15 billion by 2036.
The market is expected to grow at a CAGR of 11.6% during the forecast period 2026–2036.
The total microneedle drug delivery systems market was valued at USD 1.24 billion in 2025 and is estimated to reach USD 1.38 billion in 2026.
North America is expected to dominate this market with the largest revenue share in 2026, supported by the concentration of clinical-stage microneedle developers, an active combination-product regulatory pathway at the U.S. Food and Drug Administration, and government-backed vaccine patch programs including the Biomedical Advanced Research and Development Authority's incentive prize for needle-free patch delivery.
Asia Pacific is projected to witness the fastest revenue growth during the forecast period, driven by a dense manufacturing base of microneedle patch developers across South Korea and Japan, rising chronic disease and immunization demand across China and India, and growing government interest in self-administered vaccination technologies.
By product type, the solid microneedles segment is expected to hold the largest share of the market in 2026, supported by its manufacturing simplicity and established role in skin pretreatment and cosmetic applications.
By product type, the dissolving microneedles segment is projected to register the highest growth during the forecast period, driven by its ability to deliver a complete drug payload without generating sharps waste and its suitability for vaccine and biologic self-administration.
By material, the polymer segment is expected to account for the largest share of the market in 2026, reflecting the dominance of dissolving and hydrogel-forming microneedle designs built on biocompatible and biodegradable polymer matrices.
By material, the metal segment is projected to register the highest growth during the forecast period, driven by rising demand for hollow microneedle architectures capable of precise, higher-volume delivery of biologics and vaccines.
By application, the vaccination and immunization segment is expected to account for the largest share in 2026, while the diabetes and biologic self-administration segment is projected to register the highest CAGR during the forecast period.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 4.15 Billion |
| Market Size in 2026 | USD 1.38 Billion |
| Market Size in 2025 | USD 1.24 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 11.6% |
| Format | PDF, Excel & Cloud Portal · 306 pages |
| Dominating Product Type | Solid Microneedles |
| Fastest Growing Product Type | Dissolving Microneedles |
| Dominating Material | Polymer |
| Fastest Growing Material | Metal |
| Dominating Application | Vaccination and Immunization |
| Fastest Growing Application | Diabetes and Biologic Self-Administration |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: product type, material, application.
The global microneedle drug delivery systems market comprises micron-scale needle array technologies designed to deliver vaccines, biologics, and small-molecule therapeutics through the skin with minimal pain and reduced sharps waste. The market includes solid, hollow, coated, dissolving, and hydrogel-forming microneedles manufactured from polymers, metals, silicon, ceramics, and carbohydrate-based materials. Key applications include vaccination and immunization, diabetes and biologic self-administration, dermatology and aesthetic treatment, pain management, and other therapeutic uses.
Systemic drug and vaccine delivery remains largely in the clinical-development and early commercialization stage, although microneedle technologies have achieved broader adoption in dermatology and aesthetic applications. Growth is supported by increasing demand for convenient self-administration of chronic therapies and the need for simpler vaccine delivery. In the U.S., 40.1 million people had diagnosed or undiagnosed diabetes in 2023, representing 12.0% of the population.
Vaccination is another major growth driver. In 2023, only 83% of children globally received a first measles vaccine dose, while more than 22 million children missed it. A 2024 Phase 1/2 trial in The Gambia demonstrated that a measles-rubella vaccine delivered through a microneedle patch generated immune responses comparable to conventional injection, supporting further development of microarray patches for routine and outbreak immunization.
Commercialization activity is also accelerating. Vaxxas secured approximately A$90 million in financing in August 2025 and subsequently obtained a TGA manufacturing licence, while Micron Biomedical raised more than USD 33 million in total Series A financing to expand commercial manufacturing.
Despite these opportunities, precision manufacturing, dose consistency, regulatory requirements for drug-device combination products, scalability, and performance across different skin types remain key challenges.
Market dynamics
3 factors across 1 forcePublic Health Prioritization of Needle-Free Vaccine Patches Advancing Toward Commercial-Scale Manufacturing
The prioritization of microarray patch (MAP) technology by global public health bodies represents a significant development shaping the long-term trajectory of the microneedle drug delivery systems market. Global first-dose measles vaccination coverage remained at 83% in 2023, with more than 22 million children missing their first measles vaccine dose, highlighting persistent immunization gaps. MAPs can address several logistical barriers by eliminating vaccine reconstitution, reducing reliance on trained healthcare personnel, minimizing sharps waste, and potentially reducing cold-chain requirements through improved thermostability.
Clinical validation has also advanced. A Phase 1/2 trial conducted in The Gambia demonstrated that measles-rubella vaccine delivered through a microneedle patch generated immune responses comparable to conventional subcutaneous injection in infants and children, while the technology was reported to be safe and well tolerated. WHO subsequently identified Vaxxas and Micron Biomedical as the two leading MR-MAP candidates in clinical development. Vaxxas is advancing its high-density microarray patch (HD-MAP) platform toward scalable vaccine manufacturing, while Micron Biomedical is developing dissolvable microarray technology for needle-free vaccines and therapeutics.
The sector is increasingly moving from proof-of-concept research toward commercial-scale manufacturing. Micron Biomedical opened a more than 26,000-square-foot commercial-scale manufacturing facility in May 2026, strengthening its capacity for pivotal clinical development and future commercialization. This transition is expected to support continued investment in manufacturing infrastructure and accelerate development of vaccine and therapeutic microneedle platforms during the forecast period.
Chronic Disease Burden and Demand for Painless Self-Administered Biologic Delivery
The rising burden of chronic diseases requiring injectable therapies is creating structural demand for patient-friendly delivery technologies. WHO estimates that 830 million people worldwide were living with diabetes in 2022, with more than half of adults aged 30 years and older not receiving medication; in the U.S., 40.1 million people had diagnosed or undiagnosed diabetes in 2023, including 11.0 million adults with undiagnosed disease. This large and recurring treatment burden is encouraging developers to investigate microneedle platforms for insulin, biologics, and other self-administered therapies alongside vaccines. WHO has also established a global target that 100% of people with type 1 diabetes should have access to affordable insulin and blood-glucose monitoring by 2030, reinforcing the need for accessible delivery technologies.
Manufacturing Scale-Up and Institutional Capital Investment Accelerating Commercial Readiness
Microneedle developers are increasingly moving from laboratory and clinical development toward commercial-scale manufacturing. Vaxxas secured approximately A$90 million in financing in August 2025 to advance commercialization of its needle-free vaccination technology and subsequently obtained a TGA licence to manufacture therapeutic goods in December 2025. Micron Biomedical raised more than USD 33 million in Series A financing in January 2025, with the funding specifically supporting expansion of commercial manufacturing capabilities. The company subsequently opened a commercial-scale manufacturing facility in Georgia in May 2026.
These developments indicate a transition from proof-of-concept research toward industrialization. As additional developers advance clinical programs and manufacturing capabilities, access to qualified, scalable production capacity is likely to become an increasingly important competitive differentiator and support partnerships between microneedle developers and established pharmaceutical and vaccine manufacturers.
Table of contents
11 chapters · 126 sections · 306 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Solid Microneedles | Dissolving microneedles |
| By Material | Polymer | Metal |
| By Application | Vaccination and Immunization | Diabetes and biologic self-administration |
By Product Type
- The solid microneedles segment is expected to account for the largest share of this market.
- The leading position of this segment is attributed to its comparatively simple and well-established manufacturing process, its established commercial role in skin pretreatment ahead of topical drug or cosmetic application, and its broad use in aesthetic and dermatology devices that have already achieved regulatory clearance and market adoption, giving the segment a larger installed commercial base than newer microneedle formats still progressing through clinical development.
- However, the dissolving microneedles segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by its ability to fully dissolve and release an encapsulated drug or vaccine payload within the skin without leaving behind sharps waste, its compatibility with thermostable formulations that reduce cold-chain dependency, and its suitability for self-administration, all of which have made it the preferred platform for the vaccine patch and chronic disease biologic programs currently advancing through clinical trials at companies including Vaxxas, Micron Biomedical, and Vaxess Technologies.
By Material
- The Polymer Segment to Hold the Largest Share
- The polymer segment is expected to account for the largest share of this market.
- The leading position of this segment reflects the dominance of dissolving and hydrogel-forming microneedle designs, which rely on biocompatible and biodegradable polymer matrices to encapsulate and release therapeutic payloads, as well as the comparatively lower manufacturing cost and design flexibility polymer materials offer relative to silicon and metal alternatives.
- However, the metal segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by rising demand for hollow microneedle architectures capable of delivering larger drug volumes with greater dosing precision, a design requirement that is becoming increasingly important as microneedle developers extend their pipelines from single-dose vaccine antigens toward higher-volume biologic and insulin formulations.
By Application
- The vaccination and immunization segment is expected to account for the largest share of this market, reflecting sustained public health sector investment in patch-based vaccine delivery as a tool to close persistent global immunization coverage gaps.
- With global first-dose measles coverage remaining at 83 percent and over 22 million children missing a first vaccine dose annually, national immunization programs and multilateral health organizations continue to prioritize microarray patch development as a means of simplifying vaccine logistics and improving reach in underserved populations.
- However, the diabetes and biologic self-administration segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the large and growing population managing chronic disease through recurring injectable therapy, with an estimated 40.1 million people living with diabetes in the United States alone as of 2023, alongside rising patient and payer interest in painless, at-home biologic administration formats that reduce clinical burden and improve treatment adherence.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of this market. This leading position is supported by the concentration of clinical-stage microneedle developers headquartered in the United States, including Vaxess Technologies and Micron Biomedical, together with an established combination-product regulatory framework at the U.S. Food and Drug Administration and continued public funding support through programs such as the Biomedical Advanced Research and Development Authority's incentive prize for patch-based vaccine delivery. The presence of large diversified device and materials manufacturers such as 3M Company and Becton, Dickinson and Company further reinforces the depth of the North American market.
Asia-Pacific
Fastest growthHowever, the Asia Pacific microneedle drug delivery systems market is expected to grow at the fastest rate from 2026 to 2036. The rapid growth of this market is driven by a dense manufacturing and technology development base across South Korea and Japan, home to established microneedle developers including Raphas Co., Ltd., CosMED Pharmaceutical Co., Ltd., Hisamitsu Pharmaceutical Co., Inc., and SNvia Co., Ltd. China and India are contributing substantial incremental demand through their large chronic disease patient populations and continued government investment in expanding immunization program reach, while Australia's Vaxxas Pty Ltd is advancing one of the most clinically mature microarray patch platforms globally from its Brisbane manufacturing base.
Europe
Europe represents a well-established base for microneedle drug delivery research and development, anchored by Germany's LTS Lohmann Therapie-Systeme AG, a leading transdermal and microneedle patch developer, and Switzerland's Debiotech SA, which brings deep expertise in precision microfabrication and drug delivery device engineering. The region's coordinated pharmaceutical regulatory framework and strong academic research base in transdermal drug delivery continue to support ongoing clinical translation of microneedle technology developed by European research institutions and device manufacturers.
Middle East & Africa
The Middle East and Africa region, along with Latin America, represent emerging markets for microneedle drug delivery, shaped primarily by public health sector interest in patch-based vaccination as a tool to improve immunization reach in lower-resource settings. Clinical trial activity supporting measles and rubella microarray patch development, including the Gambia-based trial that demonstrated comparable safety and immunogenicity to conventional injection, reflects the growing relevance of these regions to the future commercialization pathway for vaccine patch technology, even as commercial-scale adoption in the near term remains concentrated in North America, Europe, and Asia Pacific.
Competitive landscape
- 3M Company (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Hisamitsu Pharmaceutical Co., Inc. · Japan
- LTS Lohmann Therapie-Systeme AG · Germany
- Corium Innovations (U.S.)
- Vaxxas Pty Ltd. · Australia
- Micron Biomedical, Inc. (U.S.)
- Vaxess Technologies, Inc. (U.S.)
- NanoPass Technologies Ltd. · Israel
- Debiotech SA · Switzerland
- Raphas Co., Ltd. · South Korea
- CosMED Pharmaceutical Co., Ltd. · Japan
- Micropoint Technologies Pte Ltd. · Singapore
- SNvia Co., Ltd. · South Korea
- QuadMedicine Co., Ltd. · South Korea
Frequently asked questions
The global microneedle drug delivery systems market is expected to reach USD 4.15 billion by 2036 from an estimated USD 1.38 billion in 2026, at a CAGR of 11.6% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Microneedle Drug Delivery Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-2131). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/microneedle-drug-delivery-systems-market-6814