Controlled Release Drug Delivery Market (2026-2036)
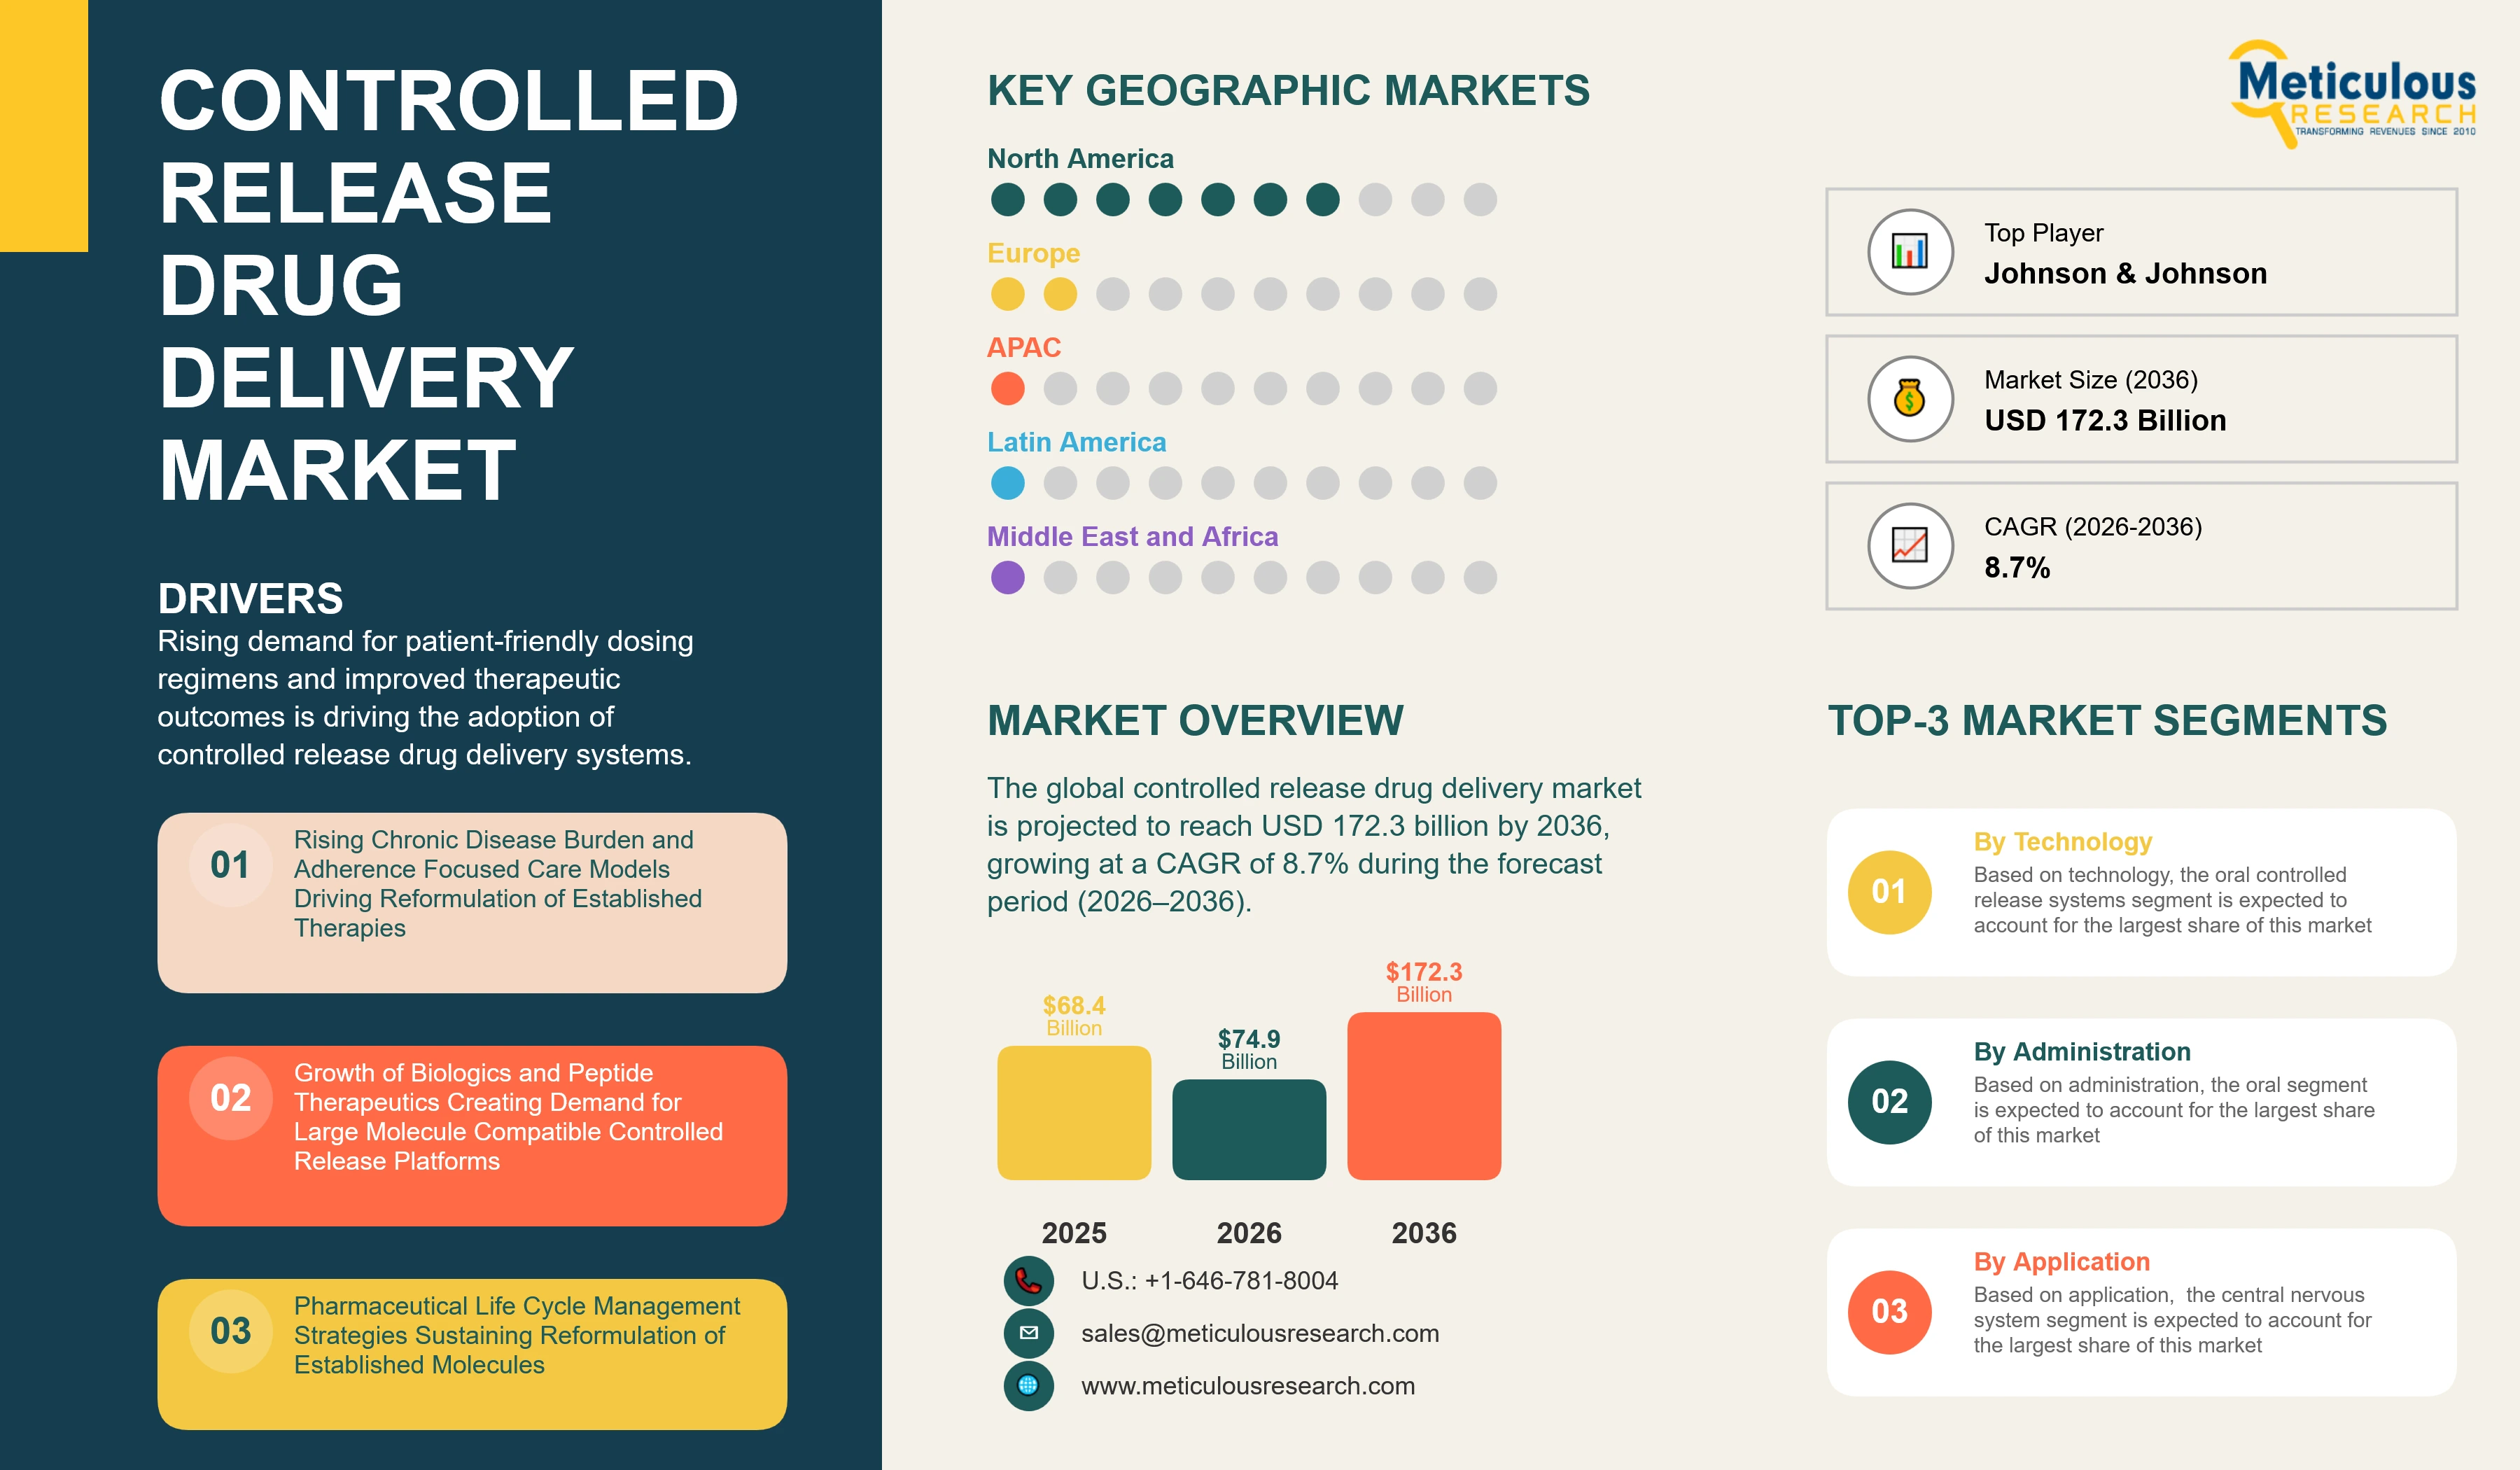
The global controlled release drug delivery market was valued at USD 68.4 billion in 2025. The market is projected to reach USD 172.3 billion by 2036, growing from USD 74.9 billion in 2026 at a CAGR of 8.7% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 298
- Format
- PDF + Excel
- Report ID
- MR-2141
- Base year
- 2025
- 2025 · BASELINE
- $68.40B
- 2036
- $172.3B
- CAGR 2026–2036
- 8.7%
2025 baseline · 2026–2036 forecast at 8.7% CAGR · hover a bar for the value
Key highlights
The global controlled release drug delivery market is projected to reach USD 172.3 billion by 2036.
The market is expected to grow at a CAGR of 8.7% during the forecast period 2026–2036.
The total controlled release drug delivery market was valued at USD 68.4 billion in 2025 and is estimated to reach USD 74.9 billion in 2026.
North America is expected to dominate this market with the largest revenue share in 2026, driven by the concentration of long acting injectable and transdermal product approvals by the U.S. Food and Drug Administration, a well established base of specialty pharmaceutical manufacturers, and broad payer coverage for extended dosing regimens across chronic disease categories.
Asia Pacific is projected to witness the fastest revenue growth during the forecast period, driven by expanding generic and specialty pharmaceutical manufacturing capacity across India, China, South Korea, and Japan, rising chronic disease burden tied to aging populations, and growing contract development and manufacturing investment by global drug delivery technology licensors.
By technology, the oral controlled release systems segment, comprising matrix, osmotic, and multiparticulate platforms, is expected to hold the largest share of the market in 2026, driven by its established regulatory pathway and broad applicability across cardiovascular, central nervous system, and pain management therapies.
By technology, the long acting injectable and implantable depot segment is projected to register the highest growth during the forecast period, driven by rapid adoption of monthly and multi month antipsychotic, opioid use disorder, and hormone therapy depot formulations that reduce daily dosing burden.
By route of administration, the oral segment is expected to account for the largest share of the market in 2026, reflecting the breadth of chronic oral therapies reformulated into extended release presentations.
By route of administration, the parenteral segment is projected to register the highest growth during the forecast period, driven by expanding long acting injectable pipelines in psychiatry, infectious disease, and endocrinology.
By application, the central nervous system segment is expected to account for the largest share in 2026, while the oncology segment is projected to register the highest CAGR during the forecast period.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 172.3 Billion |
| Market Size in 2026 | USD 74.9 Billion |
| Market Size in 2025 | USD 68.4 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 8.7% |
| Format | PDF, Excel & Cloud Portal · 298 pages |
| Dominating Technology | Oral Controlled Release Systems |
| Fastest Growing Technology | Long Acting Injectable and Implantable Depots |
| Dominating Route of Administration | Oral |
| Fastest Growing Route of Administration | Parenteral |
| Dominating Application | Central Nervous System Disorders |
| Fastest Growing Application | Oncology |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: technology, route of administration, application.
The global controlled release drug delivery market encompasses formulation technologies and delivery platforms designed to regulate the rate, timing, and duration of active pharmaceutical ingredient release, enabling therapeutic drug concentrations to be maintained over extended periods while reducing dosing frequency. The market includes oral matrix and osmotic tablets, multiparticulate pellet and bead systems, transdermal patches, long-acting injectable and implantable depots, in situ forming gels, subcutaneous implants, and ophthalmic inserts across therapeutic areas such as central nervous system disorders, cardiovascular disease, oncology, diabetes and endocrine disorders, pain management, opioid use disorder, infectious disease, and ophthalmology.
Rising chronic disease prevalence is a key market driver because long-term therapies benefit from dosage forms that reduce pill burden and support treatment adherence. According to the Centers for Disease Control and Prevention, 76.4% of U.S. adults, representing more than 194 million people, reported at least one chronic condition in 2023, while prevalence reached 93.0% among adults aged 65 years and older.
Technological and regulatory advances are further expanding controlled release applications. Long-acting injectable and implantable platforms are increasingly used in psychiatry, substance use disorder treatment, and infectious disease prevention. For example, the FDA-approved twice-yearly injectable lenacapavir for HIV pre-exposure prophylaxis demonstrates the potential of extended-duration delivery in infectious disease management. Globally, 40.8 million people were living with HIV in 2024, reinforcing the public health relevance of longer-acting treatment and prevention options.
Despite these opportunities, controlled release products face higher development and manufacturing costs, specialized polymer and formulation requirements, complex regulatory pathways, and additional sterile manufacturing or administration requirements for injectable and implantable systems. Growth opportunities are particularly strong in long-acting depots and platforms capable of delivering biologics and peptides over extended intervals.
Report infographic
Market dynamics
3 factors across 1 forceRising Chronic Disease Burden and Adherence Focused Care Models Driving Reformulation of Established Therapies
The growing prevalence of chronic conditions requiring sustained, long term pharmacological management represents the most structurally significant demand driver in the global controlled release drug delivery market. As documented by the Centers for Disease Control and Prevention, more than three quarters of American adults now live with at least one chronic condition, and more than half live with two or more, a burden that increases sharply with age. This population level shift toward multiple concurrent chronic conditions has made medication adherence a central concern for prescribers, payers, and health systems alike, since regimens requiring frequent daily dosing are disproportionately associated with missed doses and treatment discontinuation.
Pharmaceutical companies are responding by systematically reformulating high volume oral therapies for hypertension, diabetes, depression, and attention disorders into once daily or extended interval controlled release presentations that reduce pill burden without compromising therapeutic exposure. In parallel, payers and health systems in the United States and Europe are increasingly evaluating total cost of care rather than unit drug price alone, a shift that favors dosage forms demonstrated to improve adherence and reduce downstream hospitalization associated with uncontrolled chronic disease. This adherence economics argument is reinforcing controlled release reformulation as a standard life cycle management strategy across cardiovascular, central nervous system, and metabolic disease portfolios.
Long Acting Injectable and Implantable Depot Technology Expanding Beyond Psychiatry Into Infectious Disease and Endocrinology
The extension of long acting injectable and implantable depot technology beyond its historical concentration in antipsychotic and hormone therapy into infectious disease, endocrinology, and pain management represents the most significant technology level shift currently reshaping the global controlled release drug delivery market. Depot platforms developed by companies including Alkermes plc, Indivior plc, Camurus AB, Tolmar Inc., and Braeburn Inc. use polymer microsphere, in situ forming gel, and lipid liquid crystal technologies to sustain therapeutic drug levels for periods ranging from one week to six months following a single administration, fundamentally changing the treatment paradigm for conditions where daily adherence has historically been difficult to sustain.
The approval and commercial expansion of long acting injectable antiretroviral and pre exposure prophylaxis regimens for HIV, including options requiring administration as infrequently as twice yearly, illustrates how depot technology originally proven in psychiatry is now addressing public health priorities in infectious disease where dosing convenience directly influences population level prevention outcomes. Similarly, long acting buprenorphine depot injections for opioid use disorder, commercialized under agreements between companies such as Camurus AB and Braeburn Inc., are gaining formulary adoption as clinicians and payers recognize the reduced diversion risk and improved treatment retention associated with monthly rather than daily dosing. This broadening of depot technology into new therapeutic categories is drawing sustained investment from both branded pharmaceutical companies seeking differentiated life cycle extensions and specialized formulation developers licensing platform technology to third party sponsors.
Growth of Biologics and Peptide Therapeutics Creating New Demand for Large Molecule Compatible Controlled Release Platforms
The rapid expansion of biologic and peptide based therapeutics across oncology, metabolic disease, and autoimmune conditions is creating a distinct and fast growing demand segment within the controlled release drug delivery market, since conventional oral matrix and osmotic technologies developed for small molecule actives are not suitable for proteins and peptides that are degraded by gastrointestinal enzymes and require parenteral administration. Formulation developers including DURECT Corporation and Evonik Industries AG, whose Resomer polymer portfolio is widely used in injectable microsphere depot systems, are extending polymer and lipid based encapsulation platforms to protect sensitive biologic and peptide actives while enabling less frequent subcutaneous dosing than the daily or weekly injections such molecules would otherwise require.
Contract development and manufacturing organizations with sterile injectable and microsphere manufacturing capability, including Lonza Group AG, are positioned to benefit from this shift as branded pharmaceutical companies increasingly outsource complex long acting biologic formulation work rather than build internal sterile depot manufacturing capacity. This trend is also encouraging closer collaboration between drug delivery technology licensors and biologics developers earlier in the development cycle, since selecting an appropriate controlled release platform for a large molecule asset has direct implications for clinical trial design, cold chain logistics, and eventual commercial manufacturing strategy.
Table of contents
11 chapters · 123 sections · 298 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Technology | Oral Controlled Release Systems | Long acting injectable and implantable depot |
| By Route of Administration | Oral | Parenteral |
| By Application | Central Nervous System | Oncology |
By Technology
- The oral controlled release systems segment, comprising matrix tablets, osmotic pump systems, and multiparticulate pellet and bead formulations, is expected to account for the largest share of this market.
- The leading position of this segment is attributed to the established regulatory pathway for oral modified release products, the broad manufacturing infrastructure already in place across the generic and specialty pharmaceutical industry for tablet and capsule production, and the sheer breadth of chronic oral therapies across cardiovascular disease, central nervous system disorders, and pain management for which extended release reformulation offers a meaningful once daily or twice daily dosing advantage over immediate release alternatives.
- Formulation and coating technology providers including Colorcon Inc. and Adare Pharma Solutions, together with contract manufacturers such as Lonza Group AG, continue to support the segment's scale through established coating, pelletization, and matrix tableting platforms.
- However, the long acting injectable and implantable depot segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by expanding clinical and commercial adoption of monthly and multi month depot formulations in psychiatry, opioid use disorder treatment, and hormone dependent oncology, the extension of depot platforms into infectious disease prevention and treatment, and the favorable adherence and treatment retention profile that injectable depots offer over daily oral regimens in patient populations where consistent dosing has historically been difficult to sustain.
By Route of Administration
- The Oral Segment to Hold the Largest Share
- The oral segment is expected to account for the largest share of this market.
- The growth of this segment is driven by the continued dominance of oral dosing as the preferred administration route across the majority of chronic disease categories, the lower cost and simpler self administration profile of oral controlled release products relative to injectable and transdermal alternatives, and the extensive existing base of oral molecules across cardiovascular, central nervous system, and metabolic disease therapy areas that remain candidates for extended release reformulation.
- However, the parenteral segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the expanding pipeline of long acting injectable products in psychiatry, endocrinology, and infectious disease, growing physician and payer acceptance of depot injections as a means of improving treatment adherence in populations with historically poor daily medication compliance, and the parallel growth of biologic and peptide therapeutics that require parenteral administration and are increasingly being formulated into extended release depot presentations to reduce injection frequency.
By Application
- The central nervous system segment is expected to account for the largest share of this market, reflecting the long established use of extended release oral formulations and, increasingly, long acting injectable depots in the management of schizophrenia, bipolar disorder, depression, and attention deficit hyperactivity disorder, conditions in which medication non adherence is common and dosing convenience has a direct bearing on relapse prevention.
- The scale of central nervous system disease burden, combined with decades of commercial experience among manufacturers including Johnson & Johnson, Alkermes plc, and Indivior plc in developing and marketing long acting antipsychotic depot therapies, continues to anchor this segment's leading position.
- However, the oncology segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by increasing use of long acting hormone therapy depots in prostate and breast cancer management, growing interest in localized and implantable drug delivery systems for tumor site specific treatment, and the broader expansion of oncology drug development pipelines, an area that the U.S. Food and Drug Administration's Center for Drug Evaluation and Research continues to identify as one of the largest categories of new drug approval activity.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the market, supported by its advanced pharmaceutical and drug delivery infrastructure, high adoption of long-acting and extended-release therapies, strong presence of specialty pharmaceutical companies, and substantial chronic disease burden. Grand View Research estimates that North America accounted for 42.4% of the global controlled release drug delivery market in 2025. The U.S. also has a substantial population requiring long-term medication, with the Centers for Disease Control and Prevention reporting that 76.4% of U.S. adults, representing more than 194 million people, had at least one chronic condition in 2023.
Asia-Pacific
Fastest growthAsia Pacific is expected to register the fastest growth during 2026–2036, driven by expanding pharmaceutical manufacturing capacity, rising healthcare expenditure, increasing prevalence of chronic diseases, aging populations, and growing adoption of advanced drug delivery technologies across China, India, Japan, and South Korea. The region's expanding generic pharmaceutical industry is also supporting demand for oral extended-release and other controlled release formulations.
Europe
Europe represents a mature and well-established market, supported by advanced pharmaceutical research and manufacturing capabilities, established regulatory systems, and high adoption of innovative drug delivery technologies. Companies such as Camurus have strengthened the region's long-acting drug delivery landscape; its FluidCrystal-based Buvidal received European Commission approval and is commercially available across European markets.
Latin America
Latin America is supported by increasing chronic disease management needs and expanding pharmaceutical manufacturing, particularly in Brazil and Mexico.
Middle East & Africa
The Middle East and Africa is expected to experience steady growth as healthcare infrastructure expands, pharmaceutical access improves, and demand for chronic disease therapies increases across major markets such as Saudi Arabia, the UAE, and South Africa.
Competitive landscape
- Johnson & Johnson
- Pfizer Inc.
- Novartis AG
- Teva Pharmaceutical Industries Ltd.
Frequently asked questions
The global controlled release drug delivery market is expected to reach USD 172.3 billion by 2036 from an estimated USD 74.9 billion in 2026, at a CAGR of 8.7% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Controlled Release Drug Delivery Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-2141). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/controlled-release-drug-delivery-market-6824