Neoantigen Cancer Vaccine Market (2026-2036)
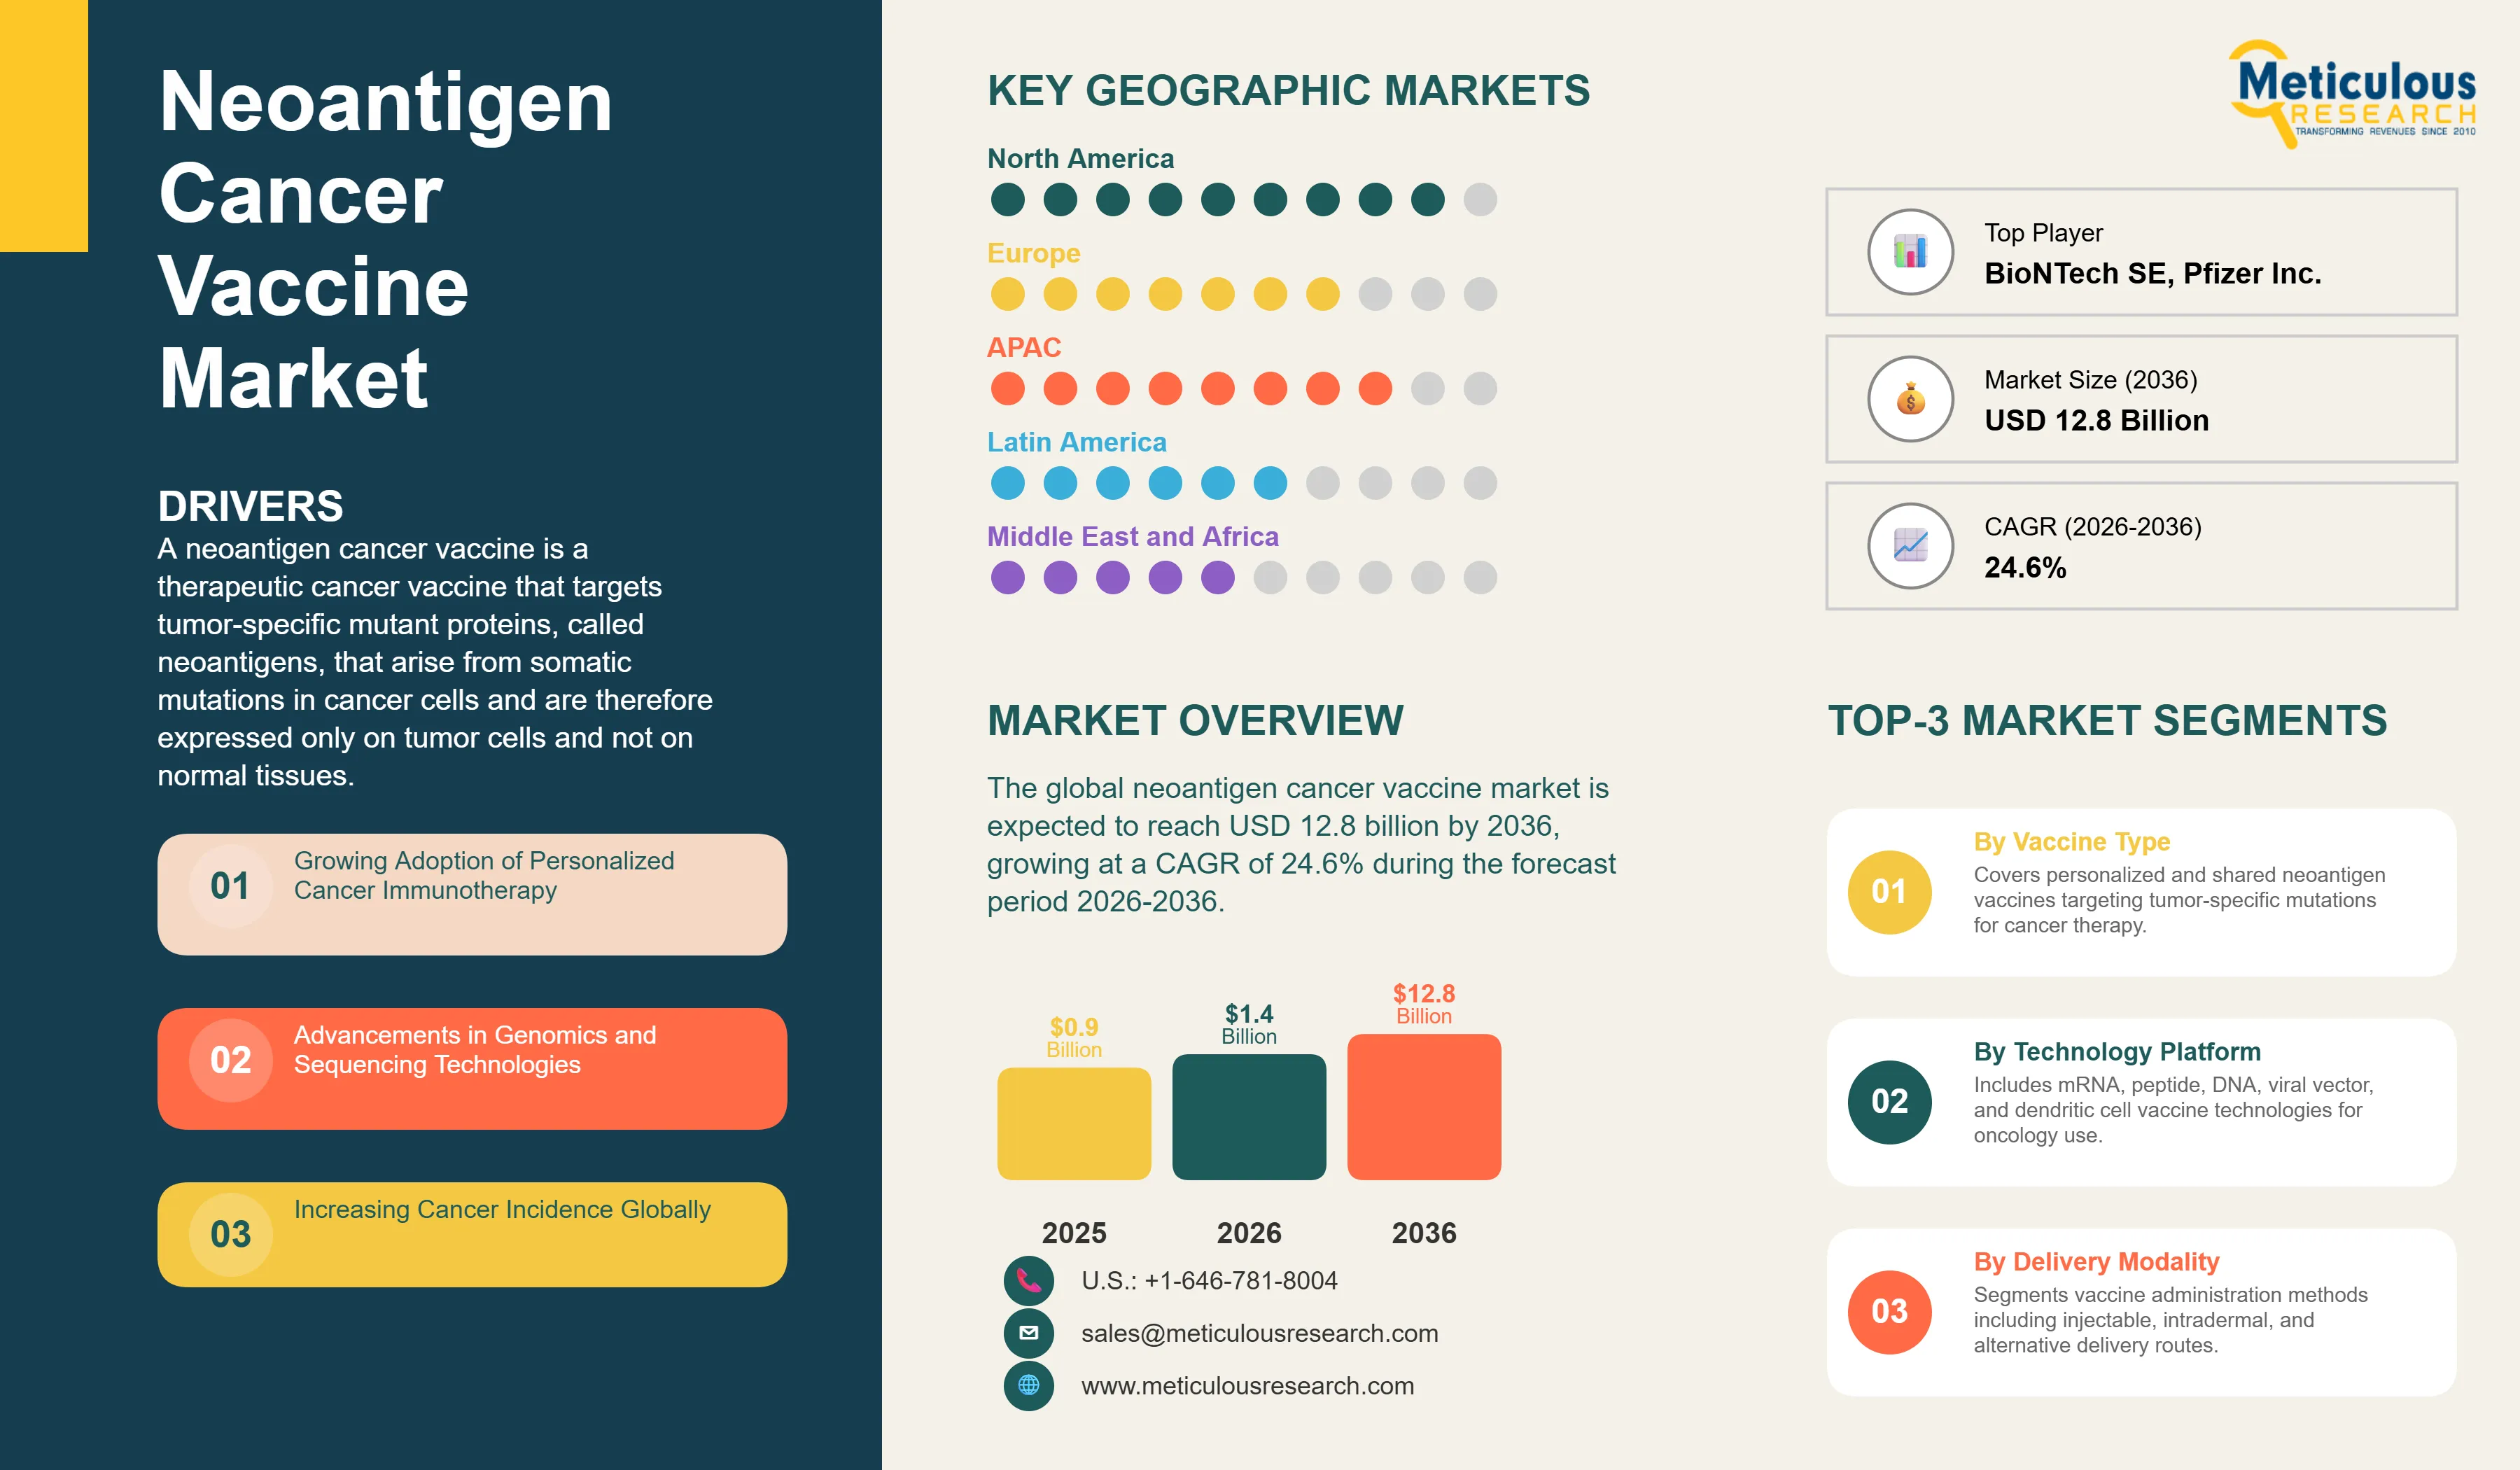
The global neoantigen cancer vaccine market was valued at USD 0.9 billion in 2025. This market is expected to reach USD 12.8 billion by 2036 from an estimated USD 1.4 billion in 2026, growing at a CAGR of 24.6% during the forecast period 2026-2036.
- Published
- May 2026
- Pages
- 289
- Format
- PDF + Excel
- Report ID
- MRHC - 1041979
- Base year
- 2025
- 2025 · BASELINE
- $900.0M
- 2036
- $12.80B
- CAGR 2026–2036
- 24.6%
2025 baseline · 2026–2036 forecast at 24.6% CAGR · hover a bar for the value
Key highlights
The global neoantigen cancer vaccine market is projected to reach USD 12.8 billion by 2036.
The market is expected to grow at a CAGR of 24.6% during the forecast period 2026-2036.
The global market for neoantigen cancer vaccine was valued at USD 0.9 billion in 2025 and is estimated to reach USD 1.4 billion in 2026.
North America is expected to dominate the global neoantigen cancer vaccine market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By vaccine type, the personalized neoantigen vaccines segment is expected to hold the largest share of the market in 2026, while the shared neoantigen vaccines segment is projected to register the highest CAGR during the forecast period.
By technology platform, the mRNA-based vaccines segment is expected to hold the largest share in 2026, while this segment is also projected to register the highest CAGR during the forecast period, driven by the Moderna-Merck mRNA-4157 clinical success.
By delivery modality, the injectable vaccines segment is expected to hold the largest share in 2026, while the intradermal delivery segment is projected to register the highest CAGR during the forecast period.
By clinical stage, the Phase I segment is expected to hold the largest share in 2026, while the Phase III segment is projected to register the highest CAGR during the forecast period.
By application, the solid tumors segment is expected to hold the largest share in 2026, while the combination therapies segment is projected to register the highest CAGR during the forecast period.
By end user, the biopharmaceutical companies segment is expected to hold the largest share in 2026, while the hospitals and cancer treatment centers segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 12.8 Billion |
| Market Size in 2026 | USD 1.4 Billion |
| Market Size in 2025 | USD 0.9 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 24.6% |
| Format | PDF, Excel & Cloud Portal · 289 pages |
| Dominating Vaccine Type | Personalized Neoantigen Vaccines |
| Fastest Growing Vaccine Type | Shared Neoantigen Vaccines |
| Dominating Technology Platform | mRNA-based Vaccines |
| Fastest Growing Technology Platform | AI-driven mRNA Vaccines |
| Dominating Delivery Modality | Injectable Vaccines |
| Fastest Growing Delivery Modality | Intradermal Delivery |
| Dominating Clinical Stage | Phase I |
| Fastest Growing Clinical Stage | Phase III |
| Dominating Application | Solid Tumors (Melanoma/Lung Cancer) |
| Fastest Growing Application | Combination Therapies with Checkpoint Inhibitors |
| Dominating End User | Biopharmaceutical Companies |
| Fastest Growing End User | Hospitals & Cancer Treatment Centers |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: vaccine type, delivery modality, application, end user.
The market's extraordinary growth rate reflects its position at the leading edge of cancer immunotherapy, where the landmark Phase 2b results of Moderna and Merck's mRNA-4157 (V940) individualized neoantigen vaccine combined with pembrolizumab demonstrated a 49% reduction in recurrence or death compared with pembrolizumab alone in resected Stage III-IV melanoma, reported at ASCO 2023 and further confirmed with updated data in 2024, establishing the clinical and commercial potential of personalized neoantigen vaccines for the first time in randomized controlled trial evidence.
A neoantigen cancer vaccine is a therapeutic cancer vaccine that targets tumor-specific mutant proteins, called neoantigens, that arise from somatic mutations in cancer cells and are therefore expressed only on tumor cells and not on normal tissues. This tumor-exclusivity is the defining clinical advantage of neoantigen vaccines over earlier cancer vaccine approaches that targeted tumor-associated antigens also expressed on normal cells: because neoantigens are absent from normal tissues, vaccines against them can stimulate a strong anti-tumor immune response without the autoimmune risk that limits the therapeutic window of vaccines against shared tumor-associated antigens. In a personalized neoantigen vaccine program, a patient's tumor is biopsied and whole-exome sequenced alongside matched normal tissue, the somatic mutations unique to the tumor are computationally identified, algorithms predict which mutant peptides will bind to the patient's specific HLA immune presentation molecules and generate T cell responses, and a custom vaccine containing these predicted neoantigens is manufactured and administered to the patient within a window of weeks.
The market entered a transformational phase in 2023 when Moderna and Merck reported Phase 2b results from the KEYNOTE-942 trial of mRNA-4157 individualized neoantigen vaccine combined with pembrolizumab in resected melanoma. The trial demonstrated a 49% reduction in recurrence or death compared with pembrolizumab alone, with updated 3-year follow-up data presented at major oncology congresses in 2024 showing a sustained and deepening benefit, confirming that the personalized vaccine was generating durable tumor-specific immune memory. According to Moderna's 2025 annual report, the company received FDA Breakthrough Therapy Designation for mRNA-4157 in melanoma and has advanced into a Phase 3 program. BioNTech simultaneously advanced its BNT111 and BNT122 neoantigen vaccine programs, with BNT122 combined with pembrolizumab progressing through Phase 2 clinical trials in colorectal cancer and melanoma per BioNTech's 2025 pipeline communications.
The combination of mRNA vaccine platform advantages including rapid and modular manufacturing, very large antigen coding capacity, and strong immunogenicity with the clinical validation from the KEYNOTE-942 trial has generated extraordinary commercial and scientific momentum. According to PhRMA's 2025 annual report, cancer vaccines represent one of the most active areas of new clinical trial initiation in the oncology pipeline, with the neoantigen vaccine category specifically attracting the most new program initiations among therapeutic cancer vaccine approaches. The clinical development programs of Gritstone bio, Nouscom, ISA Pharmaceuticals, Vaccibody, and multiple academic consortia are collectively building a broad evidence base for neoantigen vaccine efficacy across melanoma, lung cancer, colorectal cancer, and other tumor types.
Report infographic
Market dynamics
7 factors across 3 forcesGrowing Adoption of Personalized Cancer Immunotherapy
The paradigm of personalized cancer immunotherapy, in which each patient's treatment is tailored to the specific molecular characteristics of their individual tumor, is becoming the dominant approach in oncology and is creating the conceptual and commercial infrastructure for neoantigen vaccines. According to PhRMA's 2025 annual report, over 1,200 medicines are in clinical development in oncology, with precision immunotherapy representing the fastest-growing category. The clinical success of checkpoint inhibitors, which demonstrated that the immune system can eradicate advanced cancers when appropriately activated, established the immunotherapy framework that neoantigen vaccines are designed to complement and enhance by providing tumor-specific T cell targets to direct the checkpoint inhibitor-activated immune response. According to the American Society of Clinical Oncology's 2025 Clinical Cancer Advances report, neoantigen vaccines represent the most scientifically promising emerging category in cancer immunotherapy, with the KEYNOTE-942 results cited as the most significant proof-of-concept milestone in the field.
Advancements in Genomics and Sequencing Technologies
The feasibility of personalized neoantigen vaccine development is fundamentally dependent on the speed and cost of whole-exome sequencing of tumor and matched normal tissue to identify the somatic mutations that define each patient's unique set of neoantigens. According to the National Human Genome Research Institute's 2025 sequencing cost database, the cost of sequencing a human exome has fallen below USD 200, and the turnaround time for clinical whole-exome sequencing at major reference laboratories has been reduced to one to two weeks, making the sequencing step in the neoantigen vaccine workflow both cost-accessible and time-compatible with clinically meaningful vaccine delivery windows. Illumina's NovaSeq X platform, launched commercially in 2023 and becoming the standard for high-throughput clinical sequencing in 2024 and 2025, provides the sequencing throughput and quality needed for neoantigen vaccine programs at a cost and speed that supports commercial scaling.
Table of contents
14 chapters · 155 sections · 289 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Vaccine Type | Personalized Neoantigen Vaccines | Shared neoantigen vaccines |
| By Technology Platform | MRNA-based Vaccines | MRNA-based vaccines |
| By Delivery Modality | Injectable Vaccines | Intradermal delivery |
| By Clinical Stage | Phase I | Phase III |
| By Application | Solid Tumors | Combination therapies |
| By End User | Biopharmaceutical Companies | Hospitals and cancer treatment centers |
By Vaccine Type
- Personalized Neoantigen Vaccines to Hold the Largest Share
- The personalized neoantigen vaccines segment is expected to account for the largest share of the global neoantigen cancer vaccine market.
- Personalized vaccines, which are designed from each individual patient's tumor mutational profile, represent the scientific and clinical core of the neoantigen vaccine field, as individually unique somatic mutations are the highest-quality neoantigen targets due to their complete absence from normal tissues.
- The Moderna-Merck mRNA-4157 program, the most clinically advanced neoantigen vaccine globally, is a personalized vaccine approach, and BioNTech's BNT122 autogene cevumeran is also personalized.
- These two programs collectively define the commercial frontier of the personalized vaccine segment.
- However, the shared neoantigen vaccines segment is projected to register the highest CAGR during the forecast period.
- Shared neoantigens arise from mutations that occur recurrently across patients in the same tumor type, such as KRAS G12C in lung and colorectal cancer, and vaccines targeting these shared mutations can be manufactured as off-the-shelf products for all patients with that specific mutation, eliminating the complex and expensive personalized manufacturing requirement.
- The commercial appeal of shared neoantigen vaccines is their scalability: a single manufacturing run can produce vaccine doses for many patients, dramatically reducing per-patient costs compared with bespoke personalized manufacturing.
- Gritstone bio's SLATE program and several academic programs targeting recurrent cancer mutations represent this commercially scalable approach.
By Technology Platform
- MRNA-based Vaccines to Hold the Largest Share
- The mRNA-based vaccines segment is expected to account for the largest share of the global neoantigen cancer vaccine market and is also projected to register the highest growth during the forecast period, making it dominant on both measures. mRNA's advantages for neoantigen vaccines are profound: a single mRNA molecule can encode multiple neoantigens simultaneously up to the mRNA length limit, synthesis of customized mRNA sequences is highly automated and rapid, and lipid nanoparticle-formulated mRNA generates potent cellular immune responses including CD8+ cytotoxic T cells which are the primary anti-tumor effectors.
- The clinical validation from KEYNOTE-942 has cemented mRNA as the dominant platform, with Moderna and BioNTech's manufacturing infrastructure providing industrial-scale mRNA synthesis capability.
- Peptide-based vaccines, which present synthetic versions of neoantigen peptides combined with adjuvants, represent a more established but also more immunologically flexible approach used by ISA Pharmaceuticals, Nouscom, and multiple academic programs.
- Viral vector-based approaches from Gritstone bio use adenoviral vectors to deliver neoantigen sequences with potent innate immune activation, and dendritic cell-based vaccines from academic programs offer highly personalized T cell priming.
By Delivery Modality
- Injectable Vaccines to Hold the Largest Share
- The injectable vaccines segment is expected to account for the largest share of the global neoantigen cancer vaccine market.
- Intramuscular injection, which delivers mRNA-LNP formulations or adjuvanted peptides into muscle tissue for subsequent uptake by antigen-presenting cells, is the delivery route used in the Moderna-Merck mRNA-4157 program and in the majority of current neoantigen vaccine clinical trials.
- The established clinical infrastructure for intramuscular injection across oncology treatment settings makes this the most operationally accessible delivery approach.
- However, the intradermal delivery segment is projected to register the highest CAGR during the forecast period.
- Intradermal injection delivers vaccine directly into the dermis, which is extraordinarily rich in professional antigen-presenting dendritic cells, potentially enabling stronger T cell priming responses per vaccine dose compared with intramuscular delivery.
- Multiple clinical programs for peptide-based neoantigen vaccines including ISA Pharmaceuticals' programs use intradermal delivery specifically for this immunological advantage, and growing clinical evidence supports intradermal routes as potentially superior for T cell vaccine immunogenicity.
By Clinical Stage
- Phase I to Hold the Largest Share
- The Phase I segment is expected to account for the largest share of the global neoantigen cancer vaccine market by number of active programs, reflecting the field's current stage of development where most programs are still in early clinical evaluation.
- The large number of Phase I neoantigen vaccine trials globally, across diverse tumor types and vaccine platforms, reflects the extraordinary scientific interest and investment the KEYNOTE-942 results generated.
- According to ClinicalTrials.gov's 2025 database, the number of registered neoantigen vaccine clinical trials exceeded 80 active studies, the majority in Phase I.
- However, the Phase III segment is projected to register the highest CAGR during the forecast period, growing from a current base of one program, namely the Moderna-Merck mRNA-4157 melanoma Phase 3 study, to potentially several programs by 2036 as successful Phase 2 results mature into Phase 3 investments.
- According to Moderna's 2025 annual report, the mRNA-4157 Phase 3 program in melanoma is actively enrolling, and Moderna has disclosed plans to expand neoantigen vaccine Phase 2 programs in lung cancer and other tumor types that could advance to Phase 3 within the forecast period.
By Application
- Solid Tumors to Hold the Largest Share
- The solid tumors segment is expected to account for the largest share of the global neoantigen cancer vaccine market.
- Solid tumors have been the primary focus of neoantigen vaccine development because high tumor mutational burden tumors such as melanoma, non-small cell lung cancer, and microsatellite instability-high colorectal cancer provide the richest neoantigen landscapes for vaccine targeting, with the highest number of unique tumor-specific mutations available for vaccine design.
- According to the American Cancer Society’s 2025 Cancer Facts & Figures, about 212,200 new melanoma cases are expected in the United States in 2025, providing a large patient population for Moderna-Merck’s melanoma program.
- However, the combination therapies segment is projected to register the highest CAGR during the forecast period.
- The clinical validation of neoantigen vaccines in combination with pembrolizumab from the KEYNOTE-942 trial has established combination with checkpoint inhibitors as the standard development approach for neoantigen vaccines, with virtually every advanced clinical program now designed as a combination strategy.
- The commercial logic is that checkpoint inhibitors are already standard of care in many tumor types, meaning that adding a neoantigen vaccine to existing standard therapy is the most clinically and regulatorily accessible development pathway.
By End User
- Biopharmaceutical Companies to Hold the Largest Share
- The biopharmaceutical companies segment is expected to account for the largest share of the global neoantigen cancer vaccine market.
- Pharmaceutical companies are the primary funders, developers, and commercial deployers of neoantigen vaccine programs, with Moderna, BioNTech, Merck, Roche, AstraZeneca, and several specialist oncology companies each investing substantially in neoantigen vaccine development programs.
- The scale of biopharma investment is reflected in Moderna's 2025 annual report disclosing very significant R&D investment in its individualized neoantigen vaccine programs, and BioNTech's 2025 communications confirming oncology vaccines as the primary pipeline focus for its post-COVID commercial strategy.
- However, the hospitals and cancer treatment centers segment is projected to register the highest CAGR during the forecast period.
- As neoantigen vaccine programs advance toward potential commercial approval, cancer centers with advanced molecular oncology capabilities, tumor sequencing infrastructure, and academic-commercial research partnerships will become the primary clinical deployment points for neoantigen vaccines.
- Major cancer centers including Memorial Sloan Kettering, MD Anderson, and the Dana-Farber Cancer Institute are all active clinical trial sites for leading neoantigen vaccine programs and are building the clinical capabilities to become early adopters of approved neoantigen therapies.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global neoantigen cancer vaccine market. The United States is the center of global neoantigen vaccine development, home to Moderna, Merck, and Gritstone bio as the three most commercially advanced neoantigen vaccine organizations, and to the majority of global clinical trial activity in the field. According to Moderna's 2025 annual report, the mRNA-4157 Phase 3 program is based primarily in U.S. clinical centers, and the FDA's Breakthrough Therapy Designation provides additional regulatory support for U.S.-first commercial deployment. The U.S. National Cancer Institute is a significant funder of neoantigen vaccine research through its Cancer Immunotherapy Trials Network, and academic programs at Johns Hopkins, Memorial Sloan Kettering, Dana-Farber, and MD Anderson are conducting multiple early-phase neoantigen vaccine studies. According to the American Cancer Society's 2025 Cancer Facts and Figures, approximately 2 million new cancer cases are expected in the U.S. in 2025, providing the clinical population for ongoing and expanding neoantigen vaccine trial programs.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific neoantigen cancer vaccine market is expected to grow at the fastest CAGR during the forecast period. Asia-Pacific carries approximately 49% of global cancer cases per the WHO's World Cancer Report 2024, providing an enormous patient population that makes the region commercially critical for neoantigen vaccine development and eventual commercialization. China's biopharmaceutical industry has invested substantially in cancer vaccine development, with domestic companies including Zymeworks China, BioMap, and several oncology-focused biotechnology companies developing neoantigen vaccine programs. Japan's leading cancer centers and its national cancer genomics program are supporting early neoantigen vaccine clinical activities. South Korea's advanced biopharmaceutical industry is investing in cancer immunotherapy including vaccine approaches. According to BioNTech's 2025 communications, the company is expanding its clinical trial network into Asian cancer centers for its BNT122 and other cancer vaccine programs, reflecting the commercial importance of Asian patient populations for neoantigen vaccine clinical development.
Europe
Europe is a strong scientific and regulatory contributor to the neoantigen vaccine field. BioNTech SE, headquartered in Mainz, Germany, is one of the two global leaders in neoantigen vaccine development, and the company's European manufacturing infrastructure provides the mRNA synthesis and LNP formulation capability for its neoantigen vaccine programs. ISA Pharmaceuticals, headquartered in the Netherlands, is a leading peptide-based cancer vaccine company with multiple neoantigen vaccine programs in clinical development. Vaccibody, headquartered in Norway, is developing a DNA-based neoantigen vaccine platform. Nouscom, headquartered in Basel, Switzerland, is advancing a viral vector-based neoantigen vaccine program. The European Medicines Agency's engagement with neoantigen vaccine regulatory frameworks, and the EU's Cancer Mission research funding supporting cancer immunotherapy including vaccine approaches, provide the regulatory and funding infrastructure for European neoantigen vaccine development.
Competitive landscape
- Moderna Inc. (U.S.)
- BioNTech SE · Germany
- Genentech/Roche (U.S./Switzerland)
- Gritstone bio Inc. (U.S.)
- Neon Therapeutics (U.S.)
- CureVac N.V. · Germany
- AstraZeneca plc (UK)
- Merck & Co. Inc. (U.S.)
- Pfizer Inc. (U.S.)
- Immatics N.V. · Germany
- ISA Pharmaceuticals B.V. · Netherlands
- Vaccibody AS · Norway
- Nouscom AG · Switzerland
- Genocea Biosciences (U.S.)
- Advaxis Inc. (U.S.)
Frequently asked questions
The global neoantigen cancer vaccine market is expected to reach USD 12.8 billion by 2036 from an estimated USD 1.4 billion in 2026, at a CAGR of 24.6% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Neoantigen Cancer Vaccine Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1041979). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/neoantigen-cancer-vaccine-market-6662