Critical Minerals Market (2026-2036)
The global critical minerals market was valued at USD 318.50 billion in 2025. The market is expected to reach approximately USD 890.40 billion by 2036 from USD 375.20 billion in 2026, growing at a CAGR of 9.0% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 291
- Format
- PDF + Excel
- Report ID
- MR-1703
- Base year
- 2025
- 2025 · BASELINE
- $318.5B
- 2036
- $890.4B
- CAGR 2026–2036
- 9.0%
2025 baseline · 2026–2036 forecast at 9.0% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global critical minerals market is projected to reach USD 890.40 billion by 2036.
The market is expected to grow at a CAGR of 9.0% from 2026 to 2036.
Asia Pacific dominates the global critical minerals market with the largest market share in 2026, driven by China’s massive refining capacity, significant domestic consumption for EV manufacturing, and a robust ecosystem of battery technology innovators.
Latin America is expected to witness significant growth during the forecast period, supported by the rapid development of the “Lithium Triangle” in Argentina and Chile, and Brazil’s leadership in iron ore and graphite production.
By type, the lithium segment holds a significant market share in 2026, particularly due to the high demand for lithium-ion batteries in the automotive and energy storage sectors.
By application, the electric vehicles segment is expected to witness the fastest CAGR during the forecast period as automakers shift from internal combustion engines to battery-electric platforms.
By end-user, the industrial and commercial segments hold the largest share of the overall market in 2026, though the defense & aerospace segment is rapidly gaining ground due to the strategic importance of rare earth magnets and specialized alloys.
By region, North America is focusing on reshoring and diversifying its supply chain through initiatives like the Mineral Security Partnership (MSP), driving investments in domestic mining and recycling facilities.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 890.40 Billion |
| Market Size in 2026 | USD 375.20 Billion |
| Market Size in 2025 | USD 318.50 Billion |
| Market Growth Rate | CAGR of 9.0% (2026-2036) |
| Format | PDF, Excel & Cloud Portal · 291 pages |
| Dominating Region | Asia Pacific |
| Fastest Growing Region | Middle East & Africa |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Type, Application, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: type, application.
The growth of the overall critical minerals market is driven by the rapid acceleration of the global energy transition, the surging production of electric vehicle (EV) batteries, and the increasing integration of high-performance materials in defense and aerospace technologies. As governments and private enterprises seek to achieve net-zero targets and secure sovereign supply chains, the demand for essential materials like lithium, copper, and rare earth elements has become a cornerstone of modern industrial policy. The rapid expansion of the “Green Economy” sector, coupled with the increasing need for high-capacity energy storage systems to stabilize renewable grids, continues to fuel significant growth of this market across all major geographic regions.
Critical minerals represent a sophisticated domain of the global materials industry that utilizes advanced extraction, refining, and processing technologies to produce high-purity elements essential for modern technology. Unlike traditional commodities, modern critical minerals leverage AI-driven geological mapping, autonomous mining fleets, and sustainable hydrometallurgical refining to ensure the supply of materials that are vital for national security and economic stability. The market is defined by high-reliability supply chains that enable “clean energy manufacturing,” optimizing product performance and reducing the total cost of ownership (TCO) for end-users in the high-tech and automotive sectors.
The market includes a diverse range of materials, from high-purity lithium chemicals for battery cathodes to permanent magnets designed for wind turbines and stealth aircraft. These systems are increasingly integrated with advanced circular economy practices for mineral recovery and blockchain-based traceability to ensure ethical sourcing and mission success in a ESG-conscious environment. The ability to operate in complex geopolitical landscapes while maintaining stable, high-volume production has made critical minerals the strategic priority of the next generation of global industrial competition and decarbonization.
The global energy sector is pushing hard to modernize supply capabilities, aiming to enhance resource resilience and reduce the carbon footprint of extraction. This drive has increased the adoption of sustainable mining practices and the recycling of end-of-life batteries, with modular refining platforms helping to stabilize operational costs. At the same time, the rapid growth in the hydrogen economy and the push for deep-sea mining exploration is increasing the need for high-performance, specialized mineral processing equipment. By combining high-efficiency refining with robust supply chain logistics, these new systems support both environmental discovery and the burgeoning green economy.
Proliferation of Sovereign Supply Chains and Mineral Security Partnerships Governments are rapidly shifting toward localized and resilient supply chains, moving well beyond the traditional “globalized sourcing” model toward smarter regional logistics. The United States’ Inflation Reduction Act (IRA) and the EU’s Critical Raw Materials Act have already demonstrated successful incentives for domestic processing, while the Mineral Security Partnership (MSP) aims to deliver collective security and investment in LEO. The real game-changer comes with “smart” trade agreements featuring multi-lateral mineral alliances and AI-driven supply chain monitoring that can mitigate geopolitical risks in real-time. These advancements make high-efficiency mineral procurement practical and cost-effective for everyone from automotive giants to defense agencies chasing sustained technological dominance.
Innovation in Sustainable Extraction and Battery Recycling Innovation in mineral processing is rapidly driving the market as the global community scales up the circular economy. Technology suppliers are now designing autonomous recycling plants specifically for black mass processing, with tight control over chemical purity and waste mitigation to meet the challenges of environmental regulations. This often involves advanced solvent extraction and direct lithium extraction (DLE) stacks capable of processing low-grade ores without massive evaporation ponds. At the same time, growing focus on “In-Situ Recovery” (ISR) is pushing manufacturers to develop chemical solutions tailored to copper and uranium extraction. These systems help establish a sustainable mineral presence, extending the reach of resources instead of relying solely on traditional open-pit mines. By combining high-autonomy refining with robust environmental designs, these new systems support both economic discovery and the burgeoning recycling economy.
Drivers: Demand for Decarbonization and EV Proliferation A key driver of the critical minerals market is the rapid movement of the global economy toward decarbonization and the mitigation of carbon emissions. Global requirements for ensuring the long-term sustainability of the transport sector have created significant incentives for the adoption of electric vehicles (EVs) and energy storage technologies. The ability to manufacture high-density batteries and efficient electric motors drives operators toward scalable mineral solutions. It is estimated that as the number of electric vehicles triples through 2036, the need for lithium, cobalt, and nickel increases significantly; therefore, critical mineral systems, with their ability to enable high-performance green tech, are considered a crucial enabler of modern environmental strategies.
Opportunity: Expansion of the Green Hydrogen Economy and Renewable Grids The rapid growth of the green hydrogen economy provides great opportunities for the critical minerals market. Indeed, the global surge in renewable energy initiatives, such as the deployment of offshore wind and solar farms, has created a compelling demand for autonomous systems that can build and maintain resilient energy grids. These applications require high reliability, long operational life, and the ability to handle extreme environmental conditions, all attributes that are met with advanced platinum group metals (PGMs) and rare earth magnets. The energy storage market is set to expand significantly through 2036, with minerals poised for an expanding share as agencies seek to monetize resource extraction services. Furthermore, the transition from fossil fuels to commercial hydrogen platforms is stimulating demand for specialized catalysts that provide production flexibility and payload handling.
Report infographic
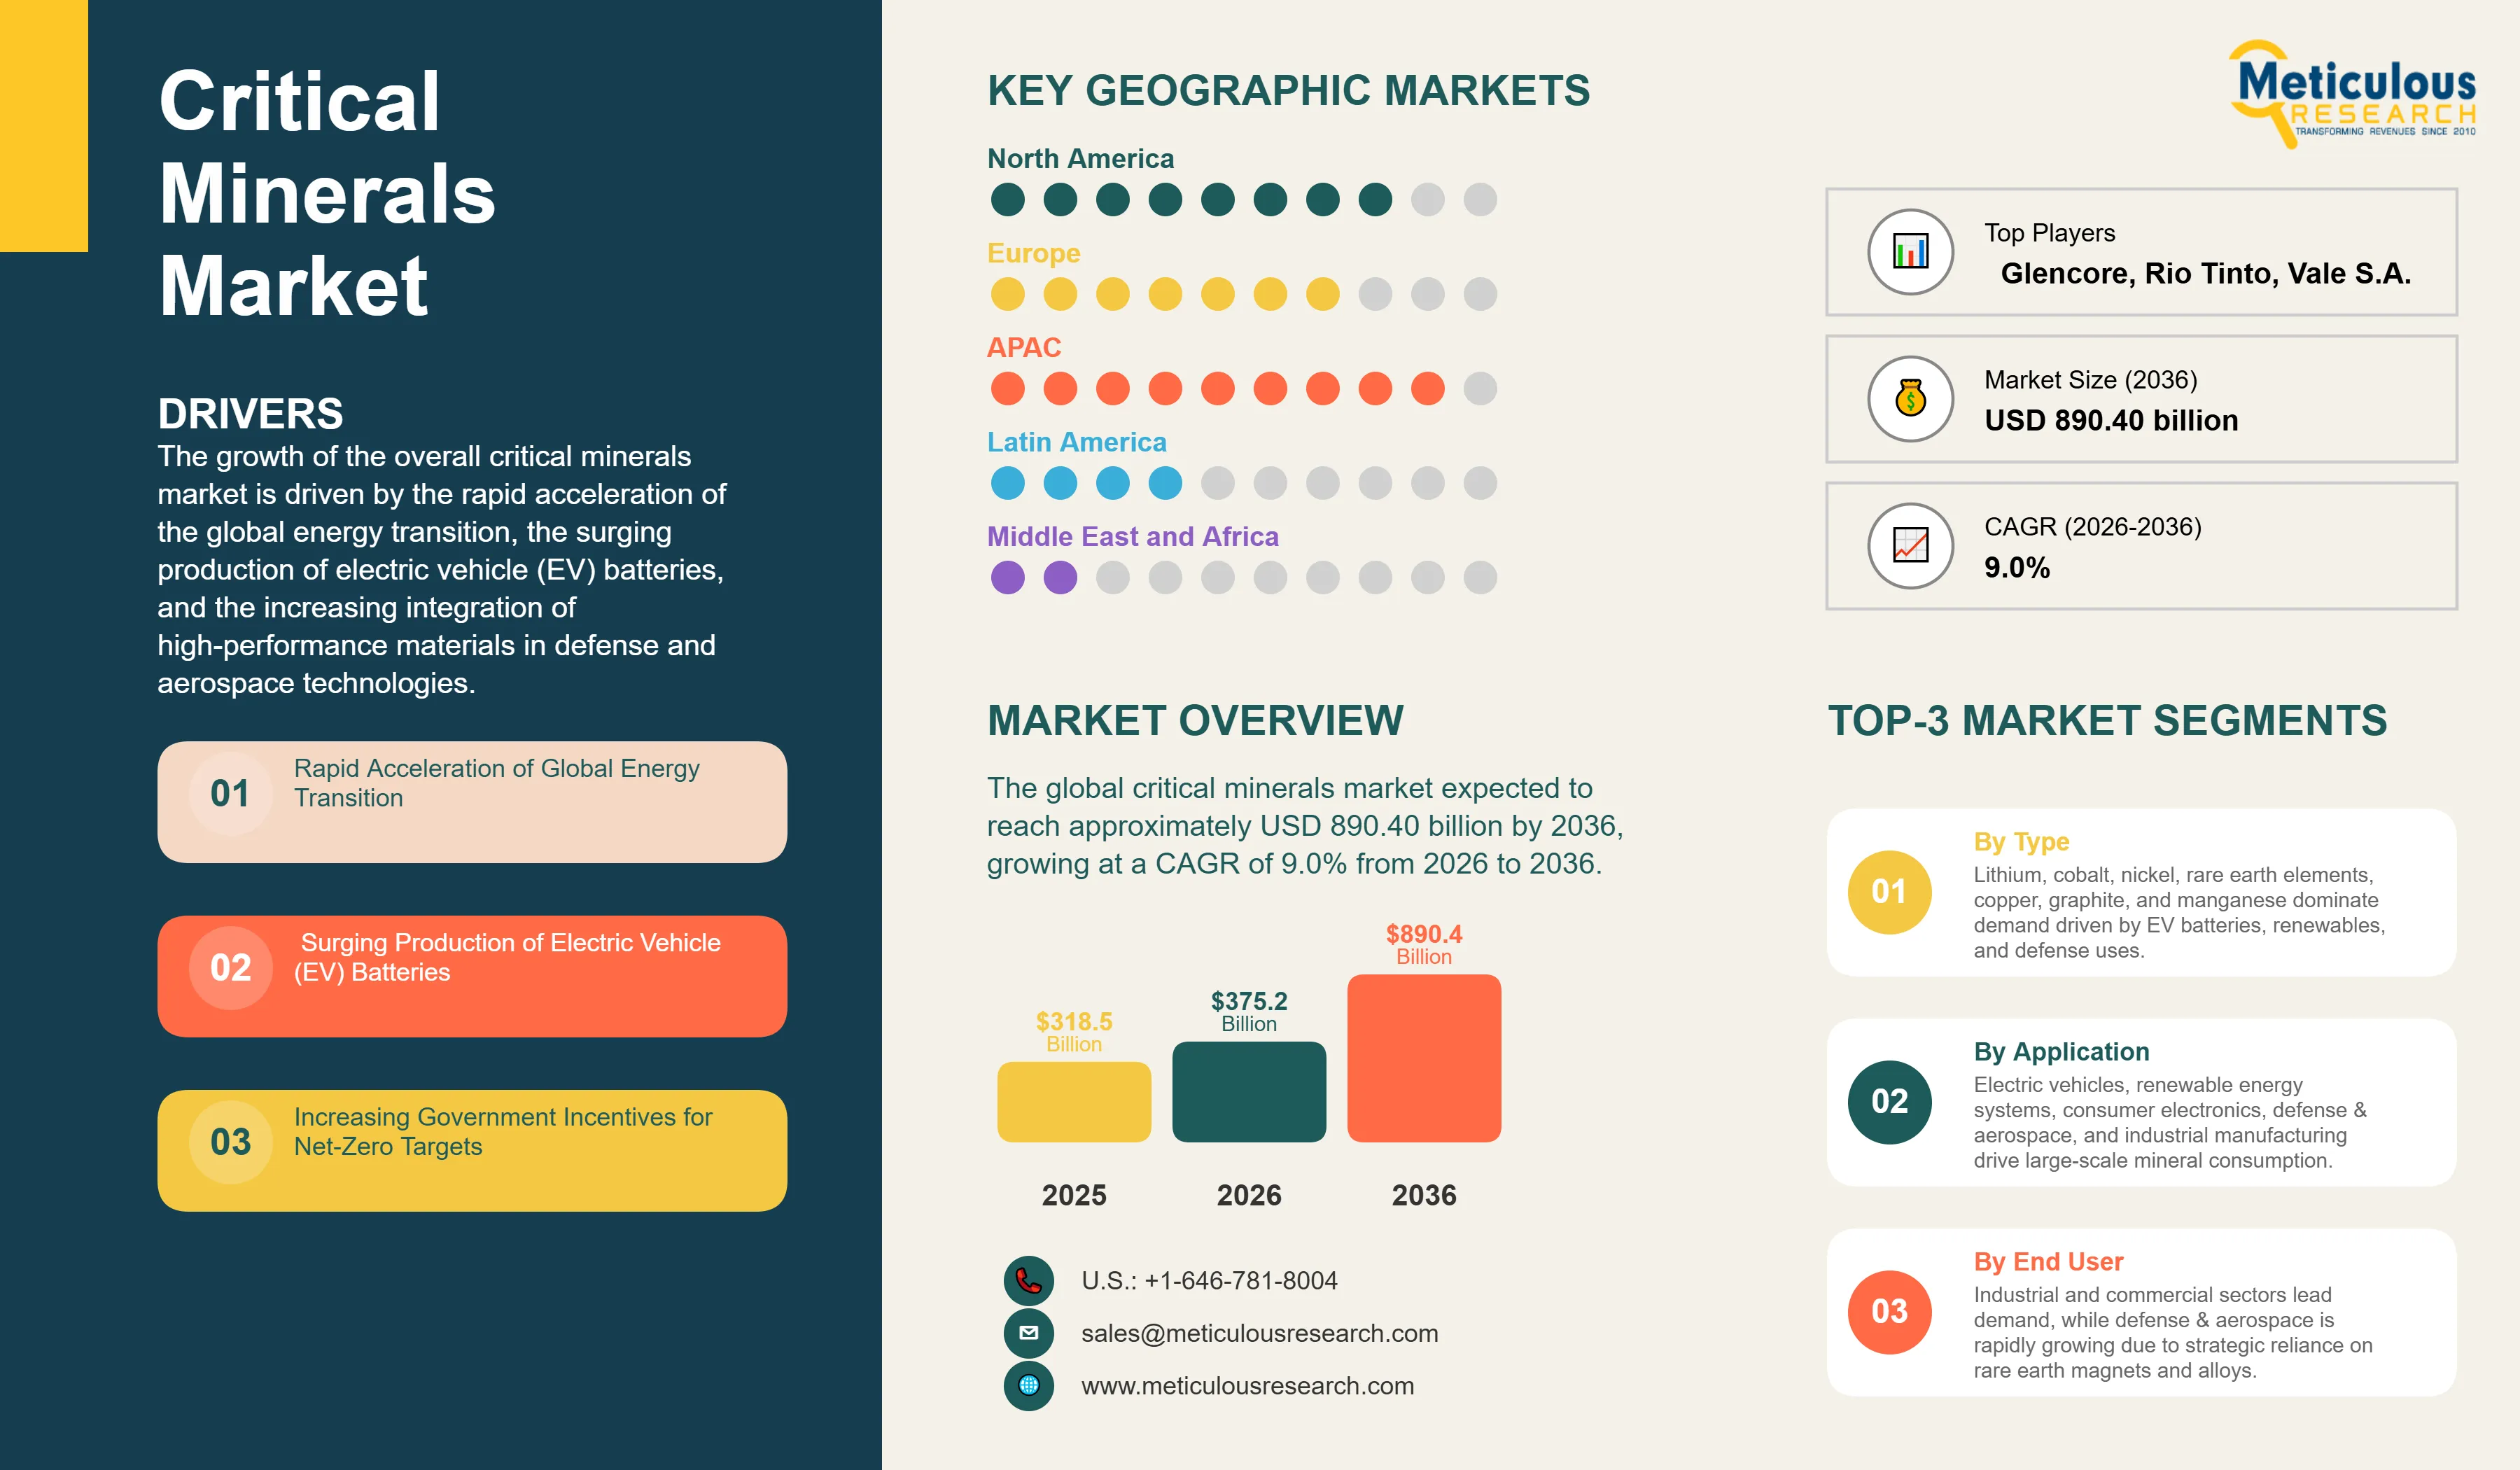
Table of contents
9 chapters · 134 sections · 291 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Type | Battery Minerals | — |
| By Application | Electric Vehicles | Electric vehicles |
By Type
- The battery minerals segment, comprising lithium, cobalt, and nickel, accounts for around 55-60% of the overall critical minerals market in 2026.
- This is mainly attributed to the primary use of these materials in mission-critical energy storage operations across the automotive and consumer electronics sectors.
- Lithium compounds, such as lithium hydroxide and carbonate, offer the most efficient way to manage high-energy density in battery packs.
- The government and commercial EV sectors alone consume the vast majority of these materials, with major projects in North America and Asia demonstrating the technology’s capability to handle high-value infrastructure management.
- However, the rare earth elements segment (including neodymium and dysprosium) is expected to grow at a significant CAGR during the forecast period, driven by the growing number of offshore wind projects and the rising demand for high-performance defense systems.
- The ability to provide “High-Coercivity Magnets” makes these solutions highly attractive for modern industrial operators.
By Application
- The electric vehicles segment holds the largest share of the overall market in 2026, accounting for around 45-50% of the overall market.
- From passenger cars to heavy-duty trucks, the use of critical minerals is central to modernizing global transport infrastructure.
- Current large-scale automotive projects are increasingly specifying high-nickel and low-cobalt chemistries for their ability to handle long-range travel with high efficiency and lower cost compared to traditional internal combustion engines.
- The renewable energy and defense segments continue to find critical applications in missions where the construction of large wind turbines and the manufacturing of precision-guided munitions are essential.
- However, the shift toward autonomous green logistics is pushing the requirement for standardized mineral traceability that allow businesses to scale their procurement capacity while minimizing their environmental footprint.
Geographic analysis
Asia-Pacific
Largest shareAsia Pacific holds the largest share of the global critical minerals market in 2026. The largest share of this region is primarily attributed to the massive investments in refining infrastructure and the presence of the world’s leading battery manufacturing companies, particularly in China. China alone accounts for a significant portion of global mineral processing, with its position as a leading hub for EV production and industrial modernization driving sustained growth. The presence of leading manufacturers like Ganfeng Lithium, Tianqi Lithium, and China Rare Earth Group, along with a well-developed supply chain ecosystem, provides a robust market for both standard and high-purity mineral solutions.
Middle East & Africa
Fastest growthMiddle East & Africa is expected to witness the fastest growth, driven by the need for economic diversification and the expansion of the mining and refining sectors. Countries like Saudi Arabia and the DRC are at the forefront, with significant focus on integrating critical minerals into their national industrial strategies.
Latin America
In Latin America, the leadership in lithium and copper production is driving the adoption of high-efficiency extraction systems. Brazil, Chile, and Argentina are leading the way, with a strong focus on the “Lithium Triangle” and the integration of sustainable mining into the region’s economic roadmap through players like SQM and Vale.
Competitive landscape
- Glencore plc
- BHP Group Limited
- Rio Tinto
- Vale S.A.
Frequently asked questions
The global critical minerals market is projected to reach approximately USD 890.40 billion by 2036, growing at a CAGR of 9.0% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Critical Minerals Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1703). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/critical-minerals-market-6386