Plasticizers Market (2025-2032)
The Plasticizers Market was valued at $17.9 billion in 2024. This market is expected to reach $26.9 billion by 2032 from an estimated $18.6 billion in 2025, at a CAGR of 5.4% during the forecast period 2025-2032. Plasticizers Market Size & Forecast The growth of the plasticizers market is primarily
- Published
- Oct 2024
- Pages
- 240
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041339
- Base year
- 2024
- 2024 · BASELINE
- $17.90B
- 2032
- $26.90B
- CAGR 2025–2032
- 5.4%
2024 baseline · 2025–2032 forecast at 5.4% CAGR · hover a bar for the value
Key highlights
The Plasticizers Market was valued at $17.9 billion in 2024.
This market is expected to reach $26.9 billion by 2032 from an estimated $18.6 billion in 2025, at a CAGR of 5.4% during the forecast period 2025-2032.
In 2025, Asia-Pacific is expected to account for the largest share of over 53% of the plasticizers market, followed by Europe, North America, Latin America, and the Middle East & Africa.
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 240 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 5.4% |
| Market Size (Value) | $26.9 Billion by 2032 |
| Segments Covered | By Type · Phthalate Plasticizers · Diethylhexyl Phthalate (DEHP) · Diisononyl Phthalate (DINP) · Diisodecyl Phthalate (DIDP) · Butyl Benzyl Phthalate (BBP) · Dioctyl Phthalate (DOP) · Other Phthalate Plasticizers · Non-phthalate Plasticizers · Adipates · Trimellitates · Benzoates · Epoxies · Phosphate Esters · Other Non-phthalate Plasticizers · Bio-based Plasticizers · Citrate Esters · Epoxidized Soybean Oil (ESBO) · Glycerol Esters · Other Bio-based Plasticizers · By End-use Industry · Building & Construction · Wires & Cables · Flooring & Wall Coverings · Roofing Membranes · Other Building & Construction Applications · Automotive · Interior & Exterior Parts · Automotive Sealers & Adhesives · Wire & Cable Insulation · Other Automotive Applications · Consumer Goods · Footwear · Sports & Leisure Products · Toys & Childcare Products · Other Consumer Goods Applications · Packaging · Flexible Packaging · Rigid Packaging · Other Packaging Applications · Medical Devices · Tubes & Bags · IV Containers · Other Medical Device Applications · Textiles · Coated Fabrics · Synthetic Leather · Other Textile Applications · Other End-use Industries |
| Countries Covered | Europe (Germany, U.K., Italy, France, Spain, Russia, Netherlands, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Thailand, Singapore, and Rest of Asia-Pacific), North America (U.S. and Canada), Latin America (Brazil, Argentina, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Saudi Arabia, South Africa, and Rest of Middle East & Africa) |
| Key Companies Profiled | UPC Technology Corporation (Taiwan), Exxon Mobil Corporation (U.S.), BASF SE (Germany), Perstorp AB (Sweden), Evonik Industries AG (Germany), Eastman Chemical Company (U.S.), Aekyung Chemical (South Korea), LG Chem, Ltd. (South Korea), DIC Corporation (Japan), Kao Corporation (Japan), Avient Corporation (U.S.), Polynt S.p.A. (Italy), KLJ Group (India), Arkema Group (France), The Dow Chemical Company (U.S.), and Nan Ya Plastics Corporation (Taiwan) |
Report overview
Segments covered: type, end-use industry. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
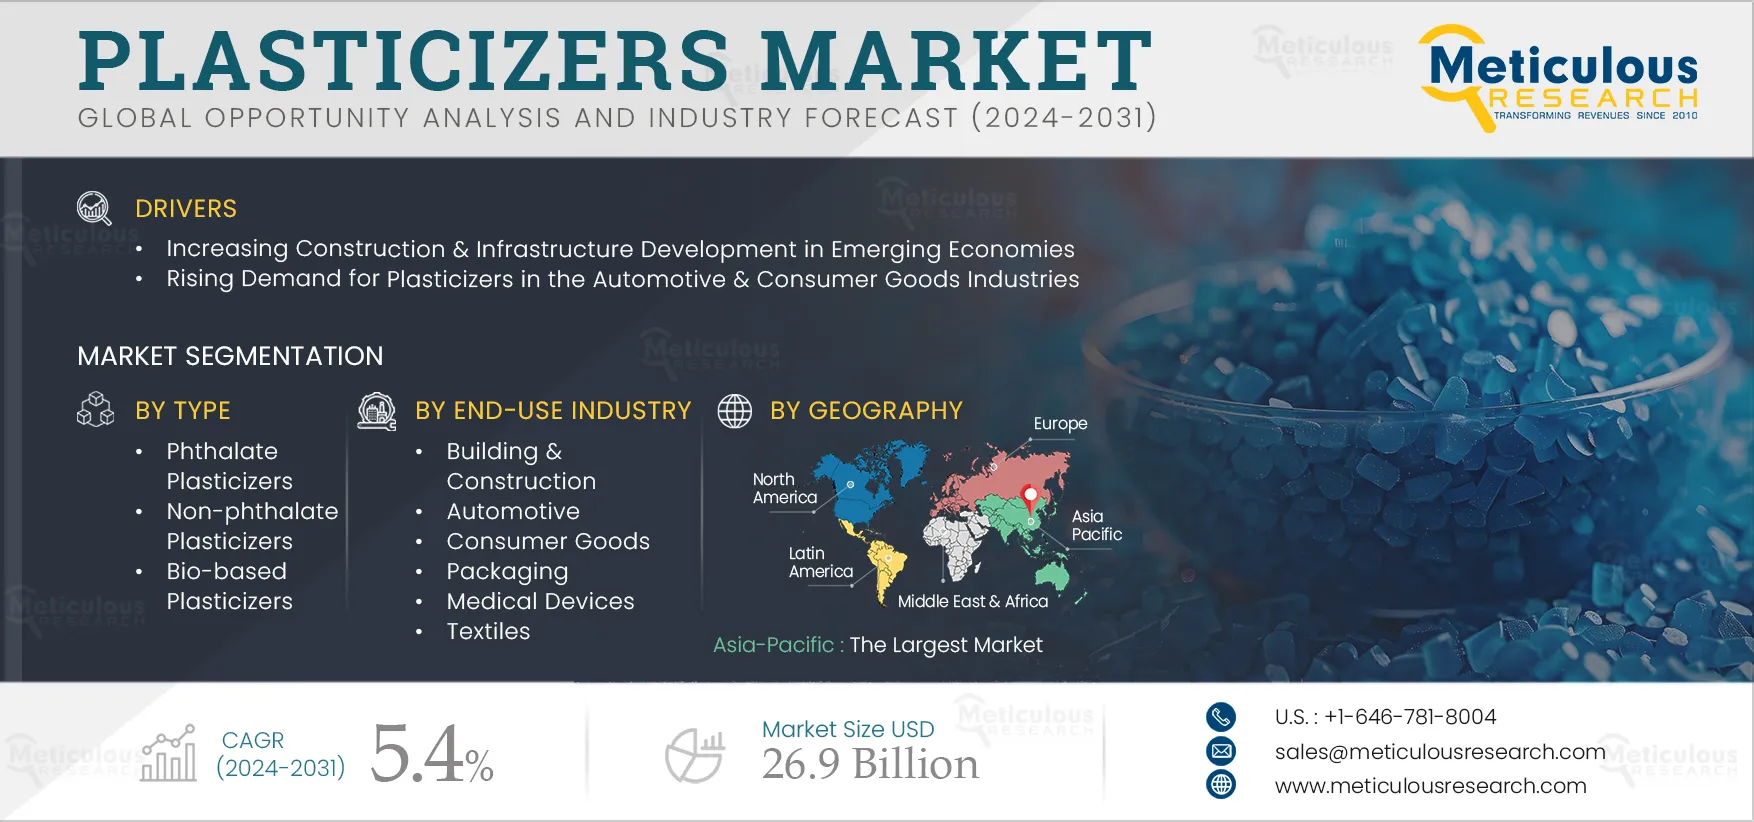
The growth of the plasticizers market is primarily driven by the increasing construction & infrastructure development in emerging economies and the rising demand for plasticizers in the automotive & consumer goods industries. However, volatile raw material prices restrain the growth of this market.
Additionally, the growing demand for eco-friendly plasticizers and the increasing utilization of plasticizers in the manufacture of packaging materials are expected to create growth opportunities for the players operating in the market. However, stringent government regulations pertaining to plastic products are a major challenge impacting market growth.
Report infographic
Market dynamics
4 factors across 2 forcesIncreasing Construction & Infrastructure Development in Emerging Economies
Rapid urbanization and industrialization are driving an increase in construction & infrastructure development projects in emerging economies, particularly in Asia-Pacific, Latin America, and the Middle East & Africa. Construction and infrastructure development refer to the building and expansion of physical structures and facilities, including residential and commercial buildings, bridges, highways, roads, mass transit facilities, airports, and utilities. Plasticizers are used in the construction and infrastructure sectors to enhance the flexibility, durability, and workability of materials, including concrete, asphalt, and PVC. They are used in applications such as wires & cables, flooring & wall coverings, roofing membranes, and piping systems.
Major players in this market are focusing on the development of bio-sourced admixture solutions to enhance the strength and workability of concrete and contribute to sustainability by reducing the carbon footprint of construction materials. For instance, in January 2024, Cemex, S.A.B. de C.V. (Mexico) launched a range of next-generation bio-sourced admixture solutions that utilize a natural, renewable, and locally sourced raw material to deliver a lower carbon footprint. These admixtures are added to concrete mixes to enhance attributes, including strength, workability, and water demand, which reduces the carbon footprint and promotes more sustainable practices in construction. Such developments, along with the growing demand for high-performance and cost-effective construction materials, increasing government investments in infrastructure, and the increasing use of plasticizers in construction materials to achieve the desired performance characteristics, are driving the growth of the plasticizers market.
Rising Demand for Plasticizers in the Automotive & Consumer Goods Industries
Companies in the automotive and consumer goods industries face several challenges related to product durability and performance, including the products’ ability to withstand extreme temperatures, vibrations, and wear, and product compliance with stringent government regulations. Hence, companies are using plasticizers to address these challenges. Automotive manufacturers use plasticizers to enhance the flexibility of materials, including PVC, to increase the durability of interior & exterior parts and wire & cable insulation, increase the adhesion & elasticity of sealers, prevent brittleness, and ensure reliable product performance under varying temperatures. In the consumer goods sector, plasticizers are used in applications, including footwear, sports equipment, toys, and childcare products, to improve the softness and flexibility of materials.
Major players in this market are focused on enhancing the performance and durability of their plasticizer products to ensure low volatility & high temperature resistance, meet the growing demand for advanced plasticizers, and support innovation in the automotive and consumer goods industries. For instance, in November 2022, Evonik Industries AG (Germany) signed a memorandum of understanding with DEZA, a.s. (Czech) for the production of the plasticizer tri-isononyl trimellitate (TINTM). TINTM is marketed under the brand name ELATUR® TM and is characterized by a particularly high temperature resistance, low volatility, and low migration behavior. It is suitable for applications including high-temperature cables and automotive interiors. Such developments, along with advances in the automotive sector, such as the increasing incorporation of lightweight and high-performance materials and rising consumer expectations in terms of product quality & performance, are boosting the adoption of plasticizers, driving the growth of this market.
Table of contents
10 chapters · 140 sections · 240 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Phthalate Plasticizers | Bio-based plasticizers |
| By End-use Industry | Building & Construction | Medical devices |
By Type
- Phthalate plasticizers are further segmented into Diethylhexyl Phthalate (DEHP), Diisononyl Phthalate (DINP), Diisodecyl Phthalate (DIDP), Butyl Benzyl Phthalate (BBP), Dioctyl Phthalate (DOP), and other phthalate plasticizers.
- Non-phthalate plasticizers are further segmented into adipates, benzoates, trimellitates, epoxies, phosphate esters, and other non-phthalate plasticizers.
- Bio-based plasticizers are further segmented into citrate esters, Epoxidized Soybean Oil (ESBO), glycerol esters, and other bio-based plasticizers.
- The phthalate plasticizers segment is expected to account for the largest share of over 47% of the plasticizers market.
- The segment’s large market share can be attributed to phthalate plasticizers’ effectiveness in improving the flexibility, durability, and workability of plastics and the growing use of phthalate plasticizers in products such as vinyl flooring, pipes, wiring insulation, and coatings.
- However, the bio-based plasticizers segment is projected to witness the highest growth rate during the forecast period 2025–2032.
- The growth of this segment is driven by increasing regulatory pressures and environmental awareness, the growing consumer preference for eco-friendly and sustainable products, and the increasing use of bio-based plasticizers in food & beverage packaging materials and medical tubing, among other applications.
By End-use Industry
- The building & construction segment is subsegmented into wires & cables, flooring & wall coverings, roofing membranes, and other building & construction applications.
- The automotive segment is subsegmented into interior & exterior parts, automotive sealers & adhesives, wire & cable insulation, and other automotive applications.
- The consumer goods segment is subsegmented into footwear, sports & leisure products, toys & childcare products, and other consumer goods applications.
- The packaging segment is subsegmented into flexible packaging, rigid packaging, and other packaging applications.
- The medical devices segment is subsegmented into tubes & bags, IV containers, and other medical device applications.
- The textile segment is subsegmented into coated fabrics, synthetic leather, and other textile applications.
- The building & construction segment is expected to account for the largest share of over 35% of the plasticizers market.
- The segment’s large market share can be attributed to rapid urbanization & infrastructure development, and the growing use of plasticizers in the production of vinyl flooring, pipes & tubing, wall coverings, and sealants & adhesives to enhance the flexibility, durability, and workability of these construction materials.
- However, the medical devices segment is projected to witness the highest growth rate during the forecast period 2025–2032.
- The growth of this segment is driven by the increasing demand for plasticizers due to advancements in healthcare, increasing medical needs, the shift toward non-toxic & biocompatible materials, and the growing use of plasticizers in the manufacture of diagnostic tools & equipment, medical tubing, implants, and disposable medical products including gloves, syringes, and blood bags to improve their functionality and ensure safe and reliable performance.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of over 53% of the plasticizers market, followed by Europe, North America, Latin America, and the Middle East & Africa. Asia-Pacific's large market share can be attributed to the ongoing industrialization in countries such as China, South Korea, and India, the increasing use of plasticizers to enhance the performance and flexibility of products across various industries, growing construction activities across APAC countries, the rapid expansion of the automotive industry, the increasing demand for advanced packaging solutions in the food processing sector, and the growing demand for consumer goods such as electronics and toys in the region. Moreover, Asia-Pacific is also slated to register the highest growth rate of over 6.5% during the forecast period. The growth of this regional market is driven by the growing consumer preference for products with enhanced durability, flexibility, and safety and increasing product safety and environmental regulations and standards driving the use of eco-friendly products, such as non-phthalate and bio-based plasticizers. Asia-Pacific to Dominate the Plasticizers Market in 2025
Competitive landscape
- August 2025
Eastman Chemical Company (U.S.) announced the launch of Benzoflex™ 172, a new plasticizer that can help manufacturers more efficiently reduce viscosity in their Polyvinyl Chloride (PVC) formulations.
- August 2025
BASF SE (Germany) signed a memorandum of understanding with UPC Technology Corporation (Taiwan) to strengthen strategic cooperation on plasticizer alcohols and catalysts for Phthalic Anhydride (PA) and Maleic Anhydride (MA), along with the development of sustainable solutions to reduce carbon emissions from operations and products.
- June 2024
KLJ Group (India) announced investing approximately $145.0 million in commissioning a new facility for plasticizer and phthalic anhydride production at the GIDC Jhagadia Industrial Estate, Bharuch, Gujarat. The facility can produce 300,000 MT of phthalate plasticizers, 100,000 MT of phthalic anhydride, 3,500 MT of maleic anhydride, and 700 MT of benzoic acid annually.
- UPC Technology Corporation · Taiwan
- Exxon Mobil Corporation (U.S.)
- BASF SE · Germany
- Evonik Industries AG · Germany
- Eastman Chemical Company (U.S.)
- Aekyung Chemical · South Korea
- LG Chem, Ltd. · South Korea
- DIC Corporation · Japan
- Kao Corporation · Japan
- Avient Corporation (U.S.)
- Polynt S.p.A · Italy
- KLJ Group · India
- Arkema Group · France
- Perstorp AB · Sweden
- Dow Chemical Company (U.S.)
- Nan Ya Plastics Corporation · Taiwan
Frequently asked questions
The plasticizers market study focuses on market assessment and opportunity analysis based on the sales of plasticizers across various regions, countries, and market segments. This study also includes a competitive analysis based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies adopted in the last three to four years.
Cite this report
Meticulous Research. (2024). Plasticizers Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRCHM - 1041339). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/plasticizers-market-6022