Construction Materials Market (2025-2032)
The Construction Materials Market is expected to reach $1,827.5 billion by 2032, at a CAGR of 3.4% from 2025 to 2032.
- Published
- Oct 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MR-1255
- Base year
- 2024
- 2032 · FORECAST
- $1.83T
- 2032
- $1.83T
- CAGR 2025–2032
- 3.4%
2024 baseline · 2025–2032 forecast at 3.4% CAGR · hover a bar for the value
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 3.4% |
| Market Size (Value) | $1,827.5 Billion by 2032 |
| Segments Covered | By Material · Bricks · Aggregates · Concrete · Cement · Metals · Stone · Sand · Plastic · Glass · Mud & Clay · Wood · Other Materials · By Application · Residential · Apartments & Buildings · Standalone Housing · Other Residential Applications · Commercial · Offices · Malls & Retail Stores · Hotels & Restaurants · Educational Institutes · Medical Facilities · Other Commercial Applications · Industrial · Warehouses · Data Centers · Manufacturing Facilities · Other Industrial Applications · Public Infrastructure · Bridges · Dams · Highways & Overbridges · Tunnels · Railways · Water Infrastructure · Sewers · Other Public Infrastructure Applications |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, U.K., France, Italy, Spain, Netherlands, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Australia & New Zealand, Thailand, and Rest of Asia-Pacific), Latin America (Mexico, Brazil, and Rest of Latin America), and the Middle East & Africa (UAE, Saudi Arabia, and Rest of Middle East & Africa) |
| Key Companies Profiled | CRH plc (Ireland), Cemex, S.A.B. de C.V. (Mexico), Heidelberg Materials AG (Germany), LIXIL Corporation (Japan), Ambuja Cements Ltd (India), Knauf Digital GmbH (Germany), China National Building Material Group Co., Ltd. (China), Boral Limited (Australia), Grasim Industries Limited (India), Holcim (Switzerland), BBMG Corporation (China), Anhui Conch Cement Co., Ltd. (China), Saint-Gobain Group (France), Sika AG (Switzerland), and ArcelorMittal (Luxembourg) |
Report overview
Segments covered: material, application. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the construction materials market is primarily driven by the increasing number of construction projects in developing economies, government initiatives to develop smart cities, and the increasing focus on sustainable building practices. Moreover, the adoption of smart technologies & sustainable materials and the introduction of 3D-printed construction materials are expected to offer growth opportunities for the players operating in this market.
Technological advancements are expanding the range of printable construction materials, resulting in the proliferation of 3D-printed buildings around the world. The use of 3D-printed construction materials is still in its early stages. However, these materials have the potential to revolutionize the construction industry. 3D printing technology offers the possibility of the on-site production of building components using mobile printers, which is revolutionary for buildings in remote locations or for rapid construction after natural disasters.
Concrete is the material most commonly used in 3D-printed construction. 3D printing allows for the precise deposition of materials, reducing waste compared to traditional construction methods. 3D printing helps automate many tasks involved in construction, leading to faster build times and lower labor costs. It also allows for the creation of complex shapes and structures that are difficult to create with traditional methods, allowing architects and engineers to design innovative building designs and construct a wider variety of structures. These benefits of 3D-printed construction materials are expected to generate growth opportunities for the players operating in the construction materials market.
Market dynamics
3 factors across 2 forcesIncreasing Number of Construction Projects in Developing Economies
With rapid urbanization, people are migrating to cities, driving the demand for housing, transportation networks, water & sanitation systems, and other essential infrastructure. Migration to urban areas is boosting the demand for new housing, commercial buildings, and infrastructure. Many developing economies are prioritizing infrastructure such as roads, bridges, dams, and power plants as part of their development plans. These projects require substantial amounts of construction materials such as bricks, steel, and cement, driving the construction materials market.
Government bodies in developing economies are promoting sustainable infrastructure development. For instance, in April 2024, the Chinese government invested $4.2 trillion (¥27 trillion) in new infrastructure under its 14th Five-Year Plan (2021-2025). The new plan aims to improve energy efficiency, accelerate green building development, retrofit over 350 million square meters of buildings, and construct over 50 million square meters of net-zero-energy-consumption buildings. Also, in April 2024, the Government of Germany invested $2.3 billion (€2.1 billion) in renovations and new office space for government employees. With the surging construction projects in developing economies, the demand for construction materials is increasing, driving the growth of this market.
Government Initiatives to Develop Smart Cities
Smart cities are urban ecosystems that integrate digital technologies, knowledge, and assets to provide residents with smart infrastructure, improve city services, and contribute to sustainability. The development of smart cities involves building new infrastructure, such as smart grids, intelligent transportation systems, and sustainable buildings, requiring a variety of construction materials. Also, governments around the globe are undertaking initiatives to manage the needs of rising urban populations.
Government initiatives to expand infrastructure for urban populations are driving the growth of the construction materials market. For instance, in March 2025, the U.S. government invested $50 million in 34 technology demonstration projects across the country through the Strengthening Mobility and Revolutionizing Transportation (SMART) Grants Program. Also, in November 2022, the Government of India announced plans to invest $840 billion (over the next 15 years) in developing urban infrastructure to effectively meet the needs of its rapidly growing urban population. Such government initiatives are driving the demand for construction materials, supporting market growth.
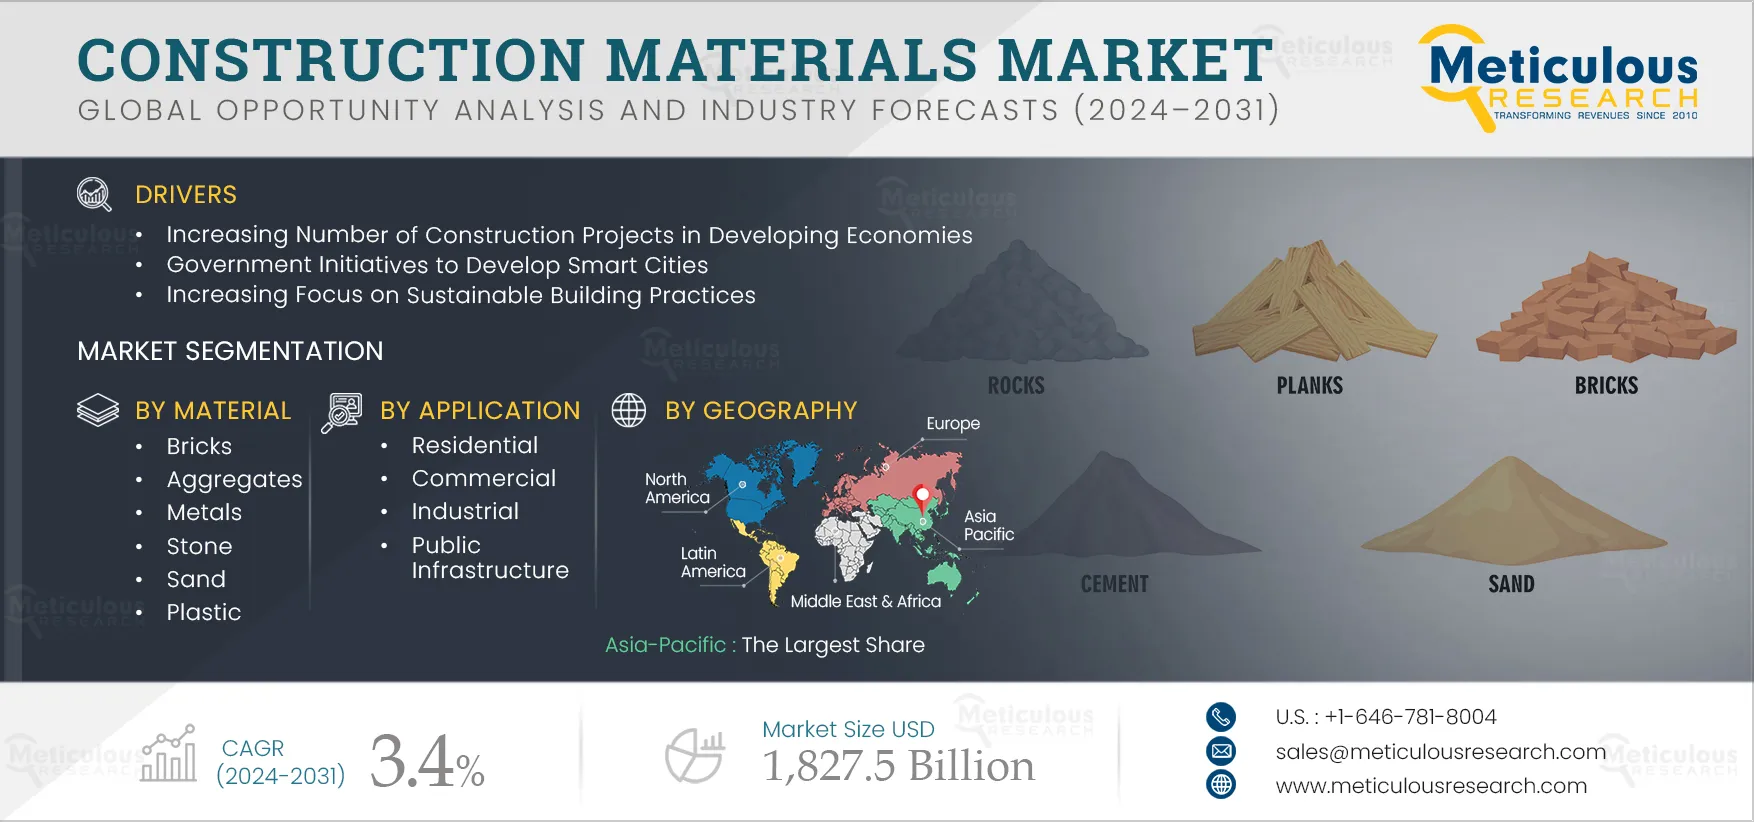
Table of contents
10 chapters · 128 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Material | Concrete & cement | Large market share of this |
| By Application | Commercial | Residential |
By Material
- The construction materials market is segmented into bricks, aggregates, concrete & cement, metals, stone, sand, plastic, glass, mud & clay, wood, and other materials.
- The concrete & cement segment is expected to account for the largest share of over 39% of the construction materials market.
- The large market share of this segment is attributed to the rapid growth of cities worldwide, the rising demand for concrete due to growth in high-rise buildings, commercial spaces, and urban infrastructure, and the development of new concrete formulations & construction techniques.
- The players in the concrete & cement market are focused on partnerships to introduce technologically advanced products.
- For instance, in November 2021, Ambuja Cements Ltd (India) partnered with the IITD (Indian Institute of Technology Delhi, India) to develop next-generation calcined clay cement, a low-carbon material, to promote sustainable construction.
- However, the metals segment is projected to register the highest CAGR during the period.
- The segment's growth is driven by increasing investments in infrastructure projects and advancements in high-strength steel and corrosion-resistant metals.
- For instance, in June 2024, Rio Tinto plc (U.K.) invested $1.1 billion in expanding its state-of-the-art AP60 aluminum smelter equipped with low-carbon technology at Complexe Jonquiere, Canada, to meet customers’ demand for low-carbon, high-quality aluminum for use in transportation, construction, electrical & consumer goods manufacturing.
By Application
- The construction materials market is segmented into residential, commercial, industrial, and public infrastructure.
- The commercial segment is expected to account for the largest share of over 28% of the construction materials market.
- The large market share of this segment is attributed to the increasing construction of new office spaces, retail stores, warehouses, and other commercial facilities due to growth in business, advancements in construction technologies, and the increasing use of sustainable building practices in the construction of commercial spaces.
- In November 2024, NCP Industries (U.S.) and Carbon Limit Limited (U.S.) launched their first commercial CCS concrete line with innovative CaptureCrete technology for the building industry.
- However, the residential segment is projected to register the highest CAGR during the period.
- The segment's growth is attributed to the rising global population, the increasing demand for high-rise apartments & condominiums, and government initiatives to develop affordable housing.
- In October 2024, Tata Housing Development Company (India) announced plans to launch 10 million sq. feet of residential projects over the next 2-3 years, aiming to meet the growing consumer demand.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of over 51% of the construction materials market. Market growth in Asia-Pacific is driven by the increasing government investments in infrastructure development projects, the rapid pace of urbanization in the region driving the demand for housing, commercial buildings, and related infrastructure, the increasing focus on sustainable building practices, and economic growth in Asian countries boosting investments in construction projects. In February 2025, the China Cement Association (CCA) signed an agreement with GCCA Inc. (U.K.) to work together on sustainability and low-carbon development of the cement & concrete industry. Asia-Pacific is also projected to record the highest CAGR of over 4.5% during the forecast period.
Competitive landscape
- April 2025
Univar Solutions LLC (U.S.) partnered with The Dow Chemical Company (U.S.) for construction silicone product distribution across Central and Eastern Europe (CEE).
- November 2024
Heidelberg Materials (Germany) launched evoZero, a carbon-captured net-zero cement for environmentally friendly construction projects in Europe.
- May 2024
The German government invested $5.44 million (€5 million) in building a demonstration production plant for a biomaterial start-up in Hamburg. The investment is aimed at replacing several thousand metric tons of conventional plastics with compostable biomaterial.
- CRH plc · Ireland
- Cemex
- S.A.B. de C.V · Mexico
- Heidelberg Materials AG · Germany
- LIXIL Corporation · Japan
- Ambuja Cements Ltd · India
- Knauf Digital GmbH · Germany
- China National Building Material Group Co., Ltd. · China
- Boral Limited · Australia
- Grasim Industries Limited · India
- Holcim · Switzerland
- BBMG Corporation · China
- Anhui Conch Cement Co., Ltd. · China
- Saint-Gobain Group · France
- Sika AG · Switzerland
- ArcelorMittal · Luxembourg
Frequently asked questions
The construction materials market study focuses on market assessment and opportunity analysis based on the sales of construction materials across various regions, countries, and market segments. This study also includes a competitive analysis based on an extensive assessment of the leading market players’ product portfolios, geographic presence, and key growth strategies adopted in the last 3 to 4 years.
Cite this report
Meticulous Research. (2024). Construction Materials Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MR-1255). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/construction-materials-market-5938