Proteogenomics Market (2026-2036)
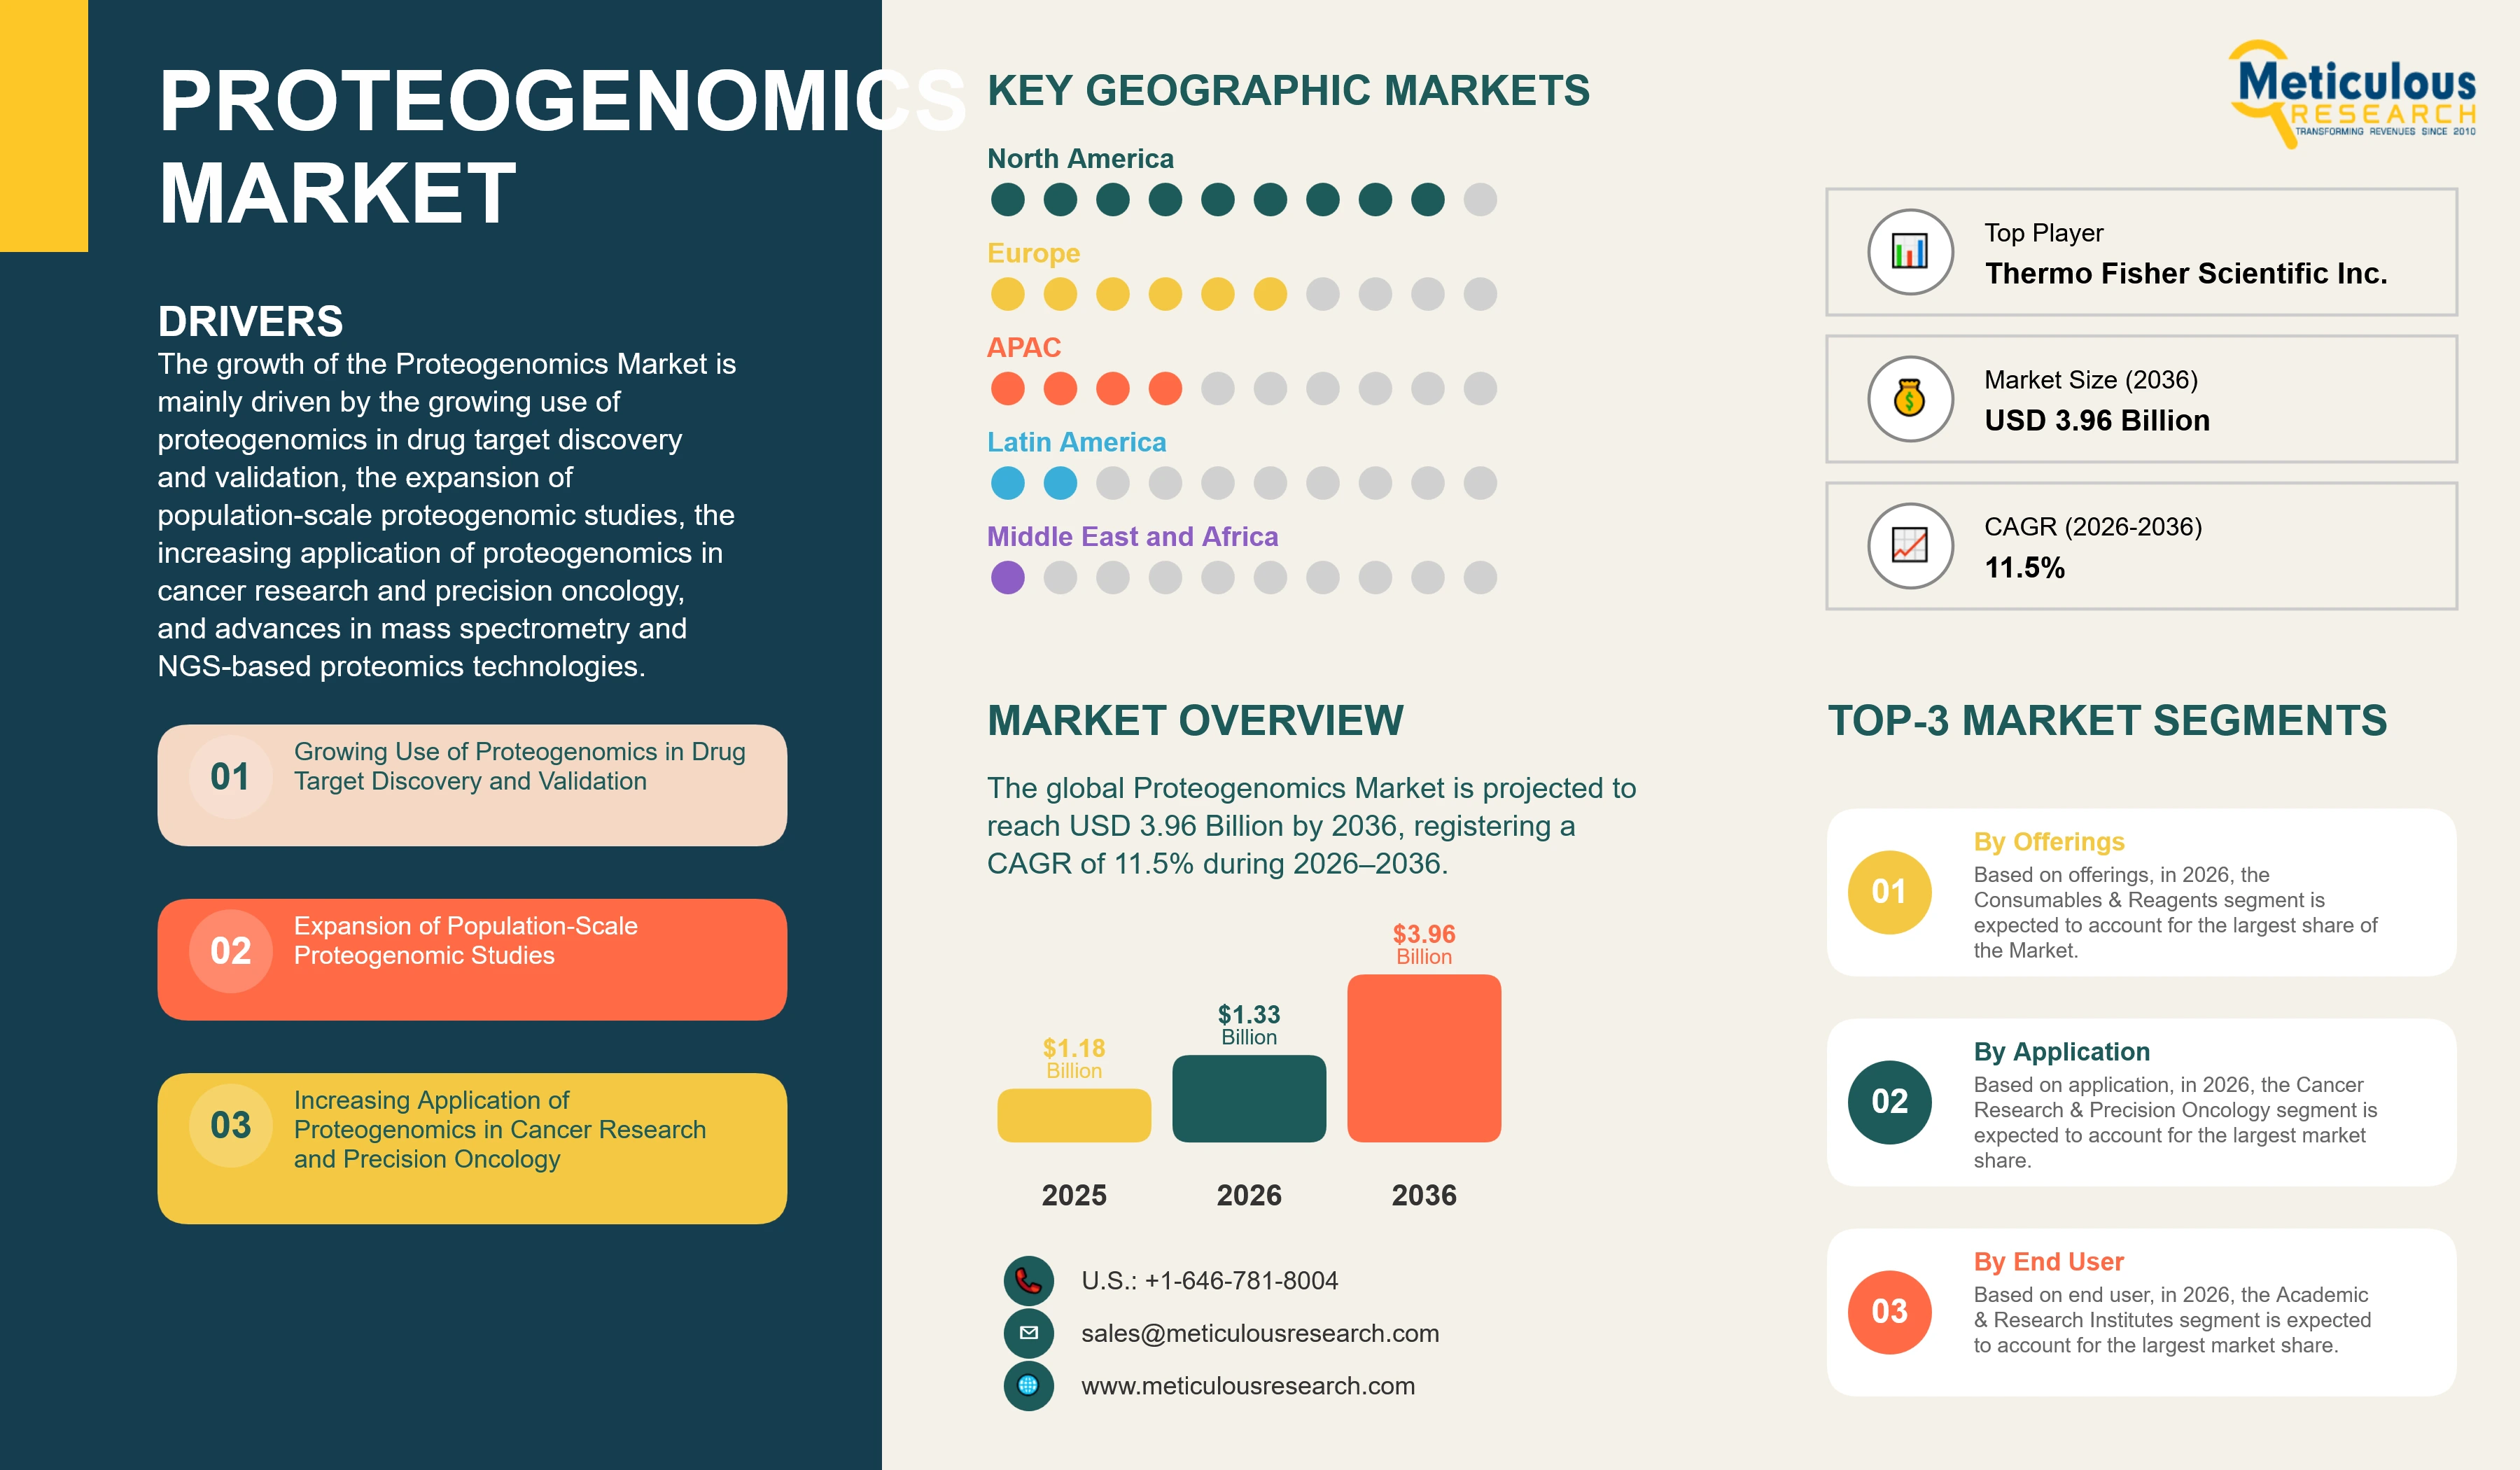
The global Proteogenomics Market was valued at USD 1.18 billion in 2025. This market is expected to reach USD 3.96 billion by 2036 from an estimated USD 1.33 billion in 2026, registering a CAGR of 11.5% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 317
- Format
- PDF + Excel
- Report ID
- MR-2340
- Base year
- 2025
- 2025 · BASELINE
- $1.18B
- 2036
- $3.96B
- CAGR 2026–2036
- 11.5%
2025 baseline · 2026–2036 forecast at 11.5% CAGR · hover a bar for the value
Key highlights
The global Proteogenomics Market is projected to reach USD 3.96 billion by 2036, driven by drug target discovery, population-scale studies, cancer proteogenomics, and advances in mass spectrometry and NGS-based proteomics.
North America is expected to account for the largest market share in 2026, while Asia-Pacific is projected to register the fastest growth during the forecast period. In Singapore, the PRECISE-SG100K population health study is generating large-scale proteomic data alongside genomic data, supported by a strategic collaboration between Thermo Fisher Scientific and Precision Health Research, Singapore, using the Orbitrap Astral mass spectrometer, while Seer and Nanyang Technological University are presenting early PRECISE-SG100K proteomics findings at HUPO 2026.
By technology, Mass Spectrometry-Based Proteogenomics is expected to account for the largest market share in 2026, whereas NGS-Based Affinity Proteogenomics is projected to witness the fastest growth through 2036. In January 2026, Illumina completed the acquisition of SomaLogic from Standard BioTools for USD 350 million in cash at closing, plus up to USD 75 million in near-term milestones and performance-based royalties, combining the SomaScan aptamer-based proteomics assay with the Illumina NGS ecosystem, DRAGEN software, and Illumina Connected Multiomics, and expects SomaLogic to contribute 1.5% to 2.0% to its fiscal 2026 revenue.
Population-scale proteogenomics is becoming a key resource for drug discovery. In January 2025, UK Biobank selected the Olink Explore platform of Thermo Fisher Scientific for the UK Biobank Pharma Proteomics Project, a collaboration with 14 biopharmaceutical companies that is measuring more than 5,400 proteins in up to 600,000 samples with linked genetic and health data, with staggered data releases beginning in 2026 and the full dataset expected in 2027.
By offering, Consumables & Reagents are expected to account for the largest market share in 2026, while Software & Bioinformatics are projected to grow the fastest, as researchers require advanced tools to integrate protein, genetic, and clinical data.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 11.5% |
| Format | PDF, Excel & Cloud Portal · 317 pages |
| Market Size (Value) in 2026 | USD 1.33 Billion |
| Market Size (Value) in 2036 | USD 3.96 Billion |
| Segments Covered | By Offering: Instruments (Mass Spectrometry Systems, NGS Systems, Single-Cell & Spatial Multiomics Platforms), Consumables & Reagents (Affinity Proteomics Assays & Kits, Sample Preparation & Enrichment Reagents, Library Preparation & Sequencing Reagents), Software & Bioinformatics, Services. By Technology: Mass Spectrometry-Based Proteogenomics, NGS-Based Affinity Proteogenomics, Single-Cell & Spatial Proteogenomics. By Application: Cancer Research & Precision Oncology, Drug Target Discovery & Validation, Biomarker Discovery, Population Health & Biobank Studies, Rare & Genetic Disease Research, Immunology & Infectious Disease Research, Other Applications. By End User: Academic & Research Institutes, Pharmaceutical & Biotechnology Companies, Biobanks & Population Health Programs, Contract Research Organizations, Hospitals & Clinical Research Centers. |
| Countries Covered | North America: U.S., Canada. Europe: U.K., Germany, France, Sweden, Switzerland, Netherlands, Denmark, Rest of Europe. Asia-Pacific: China, Japan, South Korea, Singapore, Australia, India, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Rest of Latin America. Middle East & Africa: Saudi Arabia, UAE, Qatar, Rest of Middle East & Africa. |
| Key Companies | Thermo Fisher Scientific Inc., Illumina, Inc., Danaher Corporation (SCIEX), Bruker Corporation, Waters Corporation, Alamar Biosciences, Inc., Seer, Inc., 10x Genomics, Inc., and Novogene Co., Ltd. |
Report overview
Segments covered: offering, technology, application, end user.
The growth of this market is mainly driven by the growing use of combined genomic and proteomic data to identify and validate drug targets, the expansion of population-scale proteogenomic studies linking protein measurements to genetic and health data, the increasing application of proteogenomics in cancer research and precision oncology, and continuous advances in mass spectrometry and NGS-based proteomics technologies. In addition, the consolidation of proteomics and genomics capabilities within leading life science tools companies, the growth of single-cell and spatial multiomics, and the use of artificial intelligence (AI) to integrate and interpret multiomic datasets are further supporting the growth of this market.
The Proteogenomics Market, also referred to as the integrated proteomics and genomics market, protein-genome multiomics market, or proteogenomic analysis market, comprises the instruments, consumables and reagents, software, and services used to generate, integrate, and interpret proteomic and genomic data from the same samples or individuals. Proteogenomics combines DNA and RNA sequencing with protein measurement to understand how genetic variation, mutations, and gene expression are translated into protein abundance, protein variants, and post-translational modifications. The market includes mass spectrometry systems and NGS platforms used in proteogenomic studies; affinity proteomics assays with NGS readouts, such as proximity extension, aptamer-based, and NULISA assays; sample preparation, enrichment, and library preparation reagents; single-cell and spatial multiomics platforms that measure proteins and RNA together; bioinformatics software for building sample-specific protein databases, identifying variant peptides, and integrating multiomic data; and proteogenomic analysis services. The market ecosystem extends from technology providers to research consortia, biobanks, pharmaceutical and biotechnology companies, contract research organizations, and academic and clinical research centers.
The market is experiencing strong growth as researchers recognize that genomic data alone cannot fully explain disease biology or predict drug response. Most drugs act on proteins, and protein levels often do not correlate directly with gene or RNA expression because of translational control, protein degradation, and post-translational modification. By measuring proteins in the context of genetic data, proteogenomics enables researchers to identify protein quantitative trait loci (pQTLs), establish causal links between genes, proteins, and disease, discover tumor-specific protein variants and neoantigens, and prioritize drug targets with stronger genetic evidence. These capabilities are making proteogenomics an important approach in drug discovery, cancer research, and precision medicine.
Large research programs are demonstrating the value of proteogenomics and creating demand for technologies and services. The Clinical Proteomic Tumor Analysis Consortium (CPTAC) of the U.S. National Cancer Institute released a pan-cancer proteogenomic resource covering more than 1,000 tumors across 10 cancer types, combining genomic, proteomic, imaging, and clinical data that are publicly available through the NCI Cancer Research Data Commons. In January 2025, UK Biobank selected the Olink Explore platform of Thermo Fisher Scientific for the UK Biobank Pharma Proteomics Project, a collaboration with 14 biopharmaceutical companies that is measuring more than 5,400 proteins in up to 600,000 samples with linked genetic and health data, with staggered data releases beginning in 2026 and the full dataset expected in 2027. A 2023 UK Biobank pilot that analyzed more than 54,000 samples, published in Nature, has been cited more than 400 times, illustrating the scientific impact of combining protein and genetic data at scale. Illumina Protein Prep measures up to 9,500 unique human protein targets in a single experiment with an NGS readout, and has been used by Genomics England to profile more than 7,800 rare disease participants of the 100,000 Genomes Project, allowing protein data to be analyzed alongside whole-genome sequences. In Singapore, the PRECISE-SG100K population health study is generating large-scale proteomic data alongside genomic data, supported by a strategic collaboration between Thermo Fisher Scientific and Precision Health Research, Singapore, using the Orbitrap Astral mass spectrometer, while Seer and Nanyang Technological University are presenting early PRECISE-SG100K proteomics findings at HUPO 2026.
The competitive landscape has changed significantly as genomics and analytical instrument companies build integrated proteomics and multiomics portfolios. Thermo Fisher Scientific acquired Olink in July 2024, combining NGS-based affinity proteomics with its Orbitrap mass spectrometry portfolio, and introduced the Orbitrap Tribrid Apex and Orbitrap Excedion mass spectrometers at the American Society for Mass Spectrometry (ASMS) conference in June 2026. In January 2026, Illumina completed the acquisition of SomaLogic from Standard BioTools for USD 350 million in cash at closing, plus up to USD 75 million in near-term milestones and performance-based royalties, combining the SomaScan aptamer-based proteomics assay with the Illumina NGS ecosystem, DRAGEN software, and Illumina Connected Multiomics, and expects SomaLogic to contribute 1.5% to 2.0% to its fiscal 2026 revenue. Bruker has built a multiomics portfolio through the acquisitions of PreOmics and Biognosys in proteomics and biocrates in metabolomics in June 2025, describing multiomics as the cornerstone for the future of life sciences. Waters completed its combination with the Biosciences and Diagnostic Solutions businesses of BD in February 2026, creating a Waters Biosciences division that includes single-cell multiomics.
Specialized technology providers are also contributing to market growth. Alamar Biosciences, which completed its initial public offering in April 2026, reported Q2 2026 revenue of USD 29.4 million, up 82% year over year, for its NULISA proteomics platform with an NGS readout. Seer offers the Proteograph product suite for deep plasma proteomics by mass spectrometry, which was used in an independent study published in Nature Genetics on plasma protein levels and disease risk in British South Asians. In single-cell and spatial biology, platforms that measure proteins and RNA in the same cells are enabling proteogenomic analysis at cellular resolution.
At the same time, the market faces challenges related to the complexity of integrating data from different technologies, the high cost of large-scale studies, and constraints on academic and government research funding. Seer reported that its Q2 2026 revenue declined 23% to USD 3.1 million due to pressure on academic and government funding and longer sales cycles. As a result, providers that can offer scalable workflows, integrated software, and strong evidence of biological and clinical value are expected to capture the largest share of growth over the forecast period.
Report infographic
Market dynamics
15 factors across 5 forcesGrowing Use of Proteogenomics in Drug Target Discovery and Validation
The growing use of proteogenomics in drug target discovery and validation is a major factor driving the Proteogenomics Market, as pharmaceutical companies seek genetic evidence linking proteins to disease to improve the success rates of drug development programs. By combining genome-wide genetic data with measurements of thousands of proteins, researchers can identify pQTLs and use genetic variation to infer whether changes in a protein cause disease, providing strong support for drug target selection. The participation of 14 biopharmaceutical companies in the UK Biobank Pharma Proteomics Project, and of GSK, Johnson & Johnson, and Novartis in proteomic studies with Illumina Protein Prep, reflects the strategic importance of proteogenomics to the pharmaceutical industry.
Illumina has also launched the Billion Cell Atlas, the first data product of its BioInsight business for AI-enabled drug discovery, with AstraZeneca, Merck, and Eli Lilly as its first pharmaceutical partners. These developments are increasing demand for high-plex proteomics, sequencing, and multiomic data analysis in pharmaceutical research.
Expansion of Population-Scale Proteogenomic Studies
The expansion of population-scale proteogenomic studies is significantly accelerating market growth, as biobanks and national health programs add protein measurements to existing genomic and health record data. In January 2025, UK Biobank selected the Olink Explore platform of Thermo Fisher Scientific for the UK Biobank Pharma Proteomics Project, a collaboration with 14 biopharmaceutical companies that is measuring more than 5,400 proteins in up to 600,000 samples with linked genetic and health data, with staggered data releases beginning in 2026 and the full dataset expected in 2027. Genomics England has profiled more than 7,800 rare disease participants with Illumina Protein Prep, and the PRECISE-SG100K study in Singapore is generating proteomic data using mass spectrometry and particle-based enrichment technologies.
These programs require high-throughput technologies, standardized workflows, and scalable data analysis infrastructure, and are creating reference datasets that support further research. As additional national programs follow these models, demand for proteogenomics instruments, consumables, and services is expected to grow steadily.
Increasing Application of Proteogenomics in Cancer Research and Precision Oncology
The increasing application of proteogenomics in cancer research is a key driver of the market, as tumors carry mutations, structural changes, and expression changes whose effects on proteins and signaling pathways cannot be determined from genomic data alone. The Clinical Proteomic Tumor Analysis Consortium (CPTAC) of the U.S. National Cancer Institute released a pan-cancer proteogenomic resource covering more than 1,000 tumors across 10 cancer types, combining genomic, proteomic, imaging, and clinical data that are publicly available through the NCI Cancer Research Data Commons. Proteogenomic studies have linked cancer driver mutations with protein patterns and identified protein modifications that regulate cell signaling, DNA repair, metabolism, and immunity, supporting the discovery of new therapeutic targets and biomarkers. Proteogenomics is also used to identify tumor-specific peptides and neoantigens for cancer vaccines and cell therapies, supporting demand from oncology research and drug development.
Advances in Mass Spectrometry and NGS-Based Proteomics Technologies
Continuous advances in proteomics technologies are making proteogenomic studies deeper, faster, and more scalable. Thermo Fisher Scientific introduced the Orbitrap Tribrid Apex and Orbitrap Excedion mass spectrometers in June 2026, and the Orbitrap Astral system is being used in the PRECISE-SG100K study. At the same time, NGS-based affinity proteomics technologies measure thousands of proteins in small sample volumes, with Olink Explore measuring more than 5,400 proteins and Illumina Protein Prep up to 9,500 protein targets. These technologies are enabling proteomics to be performed at a scale comparable to genomics, supporting the integration of proteomic and genomic data in large studies.
Table of contents
12 chapters · 148 sections · 317 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Offering | Consumables & Reagents | Software & Bioinformatics |
| By Technology | Mass Spectrometry-Based Proteogenomics | NGS-Based Affinity Proteogenomics |
| By Application | Cancer Research & Precision Oncology | Population Health & Biobank Studies |
| By End User | Academic & Research Institutes | Pharmaceutical & Biotechnology Companies |
By Offering
- Proteogenomics Market Analysis by Offering
- Instruments are further segmented into Mass Spectrometry Systems, NGS Systems, and Single-Cell & Spatial Multiomics Platforms.
- Consumables & reagents are further segmented into Affinity Proteomics Assays & Kits, Sample Preparation & Enrichment Reagents, and Library Preparation & Sequencing Reagents.
- The Consumables & Reagents segment is expected to account for the largest share of the global Proteogenomics Market.
- The large share of this segment is mainly due to the recurring use of affinity proteomics assays, sample preparation and enrichment reagents, and sequencing reagents in every proteogenomic study, and the scale of projects such as the UK Biobank Pharma Proteomics Project covering more than 5,400 proteins in up to 600,000 samples.
- However, the Software & Bioinformatics segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the increasing size and complexity of proteogenomic datasets, the need to integrate protein, genetic, and clinical data, and the growing use of AI-enabled platforms such as Illumina Connected Multiomics.
- The Instruments segment is expected to account for a significant share, supported by new mass spectrometry platforms introduced in 2026 and the use of high-throughput sequencers, while the Services segment is expected to grow as pharmaceutical companies and biobanks outsource large proteogenomic studies.
By Technology
- Proteogenomics Market Analysis by Technology
- The Mass Spectrometry-Based Proteogenomics segment is expected to account for the largest market share, due to the established use of mass spectrometry in cancer proteogenomics programs such as CPTAC, its ability to identify protein variants and post-translational modifications, and the continuous introduction of high-resolution platforms.
- However, the NGS-Based Affinity Proteogenomics segment is projected to register the highest CAGR during the forecast period, owing to its scalability for population studies, the acquisition of SomaLogic by Illumina, the selection of Olink for the UK Biobank Pharma Proteomics Project, and the rapid growth of NULISA technology, with Alamar Biosciences reporting 82% revenue growth in Q2 2026.
By Application
- Proteogenomics Market Analysis by Application
- The Cancer Research & Precision Oncology segment is expected to account for the largest market share, due to the extensive use of proteogenomics to study tumor biology, identify therapeutic targets and neoantigens, and develop biomarkers, supported by public resources such as the CPTAC pan-cancer dataset of more than 1,000 tumors.
- However, the Population Health & Biobank Studies segment is projected to register the highest CAGR during the forecast period, driven by projects such as the UK Biobank Pharma Proteomics Project, Genomics England, and PRECISE-SG100K.
- The Drug Target Discovery & Validation segment is also expected to record strong growth, as pharmaceutical companies use pQTL analysis to prioritize targets with genetic evidence.
By End User
- Proteogenomics Market Analysis by End User
- The Academic & Research Institutes segment is expected to account for the largest market share, as universities, research institutes, and government-funded consortia such as CPTAC conduct a large share of proteogenomic research.
- However, the Pharmaceutical & Biotechnology Companies segment is projected to register the highest CAGR during the forecast period, driven by the use of proteogenomics for target discovery, biomarker development, and clinical trial analysis, as reflected in pharmaceutical participation in the UK Biobank Pharma Proteomics Project and the Illumina Billion Cell Atlas.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Proteogenomics Market. The large share of this region is mainly attributed to strong research funding, the presence of leading research programs such as CPTAC at the National Cancer Institute, the concentration of pharmaceutical and biotechnology companies, and the presence of leading technology providers, including Thermo Fisher Scientific, Illumina, Alamar Biosciences, and Seer. The public availability of CPTAC proteogenomic data through the NCI Cancer Research Data Commons supports broad research use of proteogenomics in the U.S. However, constraints on academic and government research funding, as reported by Seer in 2026, may moderate growth in parts of the research sector. Canada is expected to contribute to regional growth, supported by academic research and genomics infrastructure.
Europe
Europe is expected to account for a significant share of the market, supported by population-scale studies, strong academic research, and the presence of major pharmaceutical companies. The U.K. is expected to account for the largest share within the region, as the UK Biobank Pharma Proteomics Project is measuring more than 5,400 proteins in up to 600,000 samples and Genomics England has profiled more than 7,800 rare disease participants with Illumina Protein Prep. Germany is an important center for proteomics technology, with major Bruker operations, while Sweden, the original home of Olink, and Switzerland, home to Biognosys, have strong proteomics research bases. France, the Netherlands, and Denmark are also expected to contribute to regional growth.
Asia-Pacific
Fastest growthAsia-Pacific is projected to register the highest CAGR during the forecast period. In Singapore, the PRECISE-SG100K population health study is generating large-scale proteomic data alongside genomic data, supported by a strategic collaboration between Thermo Fisher Scientific and Precision Health Research, Singapore, using the Orbitrap Astral mass spectrometer, while Seer and Nanyang Technological University are presenting early PRECISE-SG100K proteomics findings at HUPO 2026. China is expected to account for the largest share within Asia-Pacific, supported by large research investments, a strong genomics services industry, and growing proteomics research, while Japan and South Korea are expected to see strong growth, supported by academic research and pharmaceutical development. Korea University collaborators have presented preliminary data on AI-driven plasma proteomics for multi-cancer screening, reflecting the growing interest in proteomics-based precision medicine in the region. Australia and India are also expected to emerge as growing markets.
Latin America
Latin America and the Middle East & Africa are expected to account for smaller shares of the market.
Middle East & Africa
In the Middle East, national genomic medicine programs in Saudi Arabia, the UAE, and Qatar are expected to create demand for proteogenomic research, while in Latin America, demand is supported by academic research in Brazil and Mexico.
Competitive landscape
The global Proteogenomics Market is moderately consolidated, with a small number of large life science tools companies offering mass spectrometry, sequencing, and affinity proteomics technologies, alongside specialized proteomics and single-cell technology providers, bioinformatics companies, and service providers. Market participants compete primarily on proteome coverage and depth, sensitivity, sample throughput, integration with genomics workflows, software and data analysis capabilities, and the ability to support large-scale studies.
Leading companies are pursuing acquisitions, developing new mass spectrometry and affinity proteomics platforms, integrating proteomic and genomic data analysis, and partnering with biobanks, research consortia, and pharmaceutical companies. Recent examples include the acquisition of Olink by Thermo Fisher Scientific in July 2024, the selection of Olink for the UK Biobank Pharma Proteomics Project in January 2025, the acquisition of biocrates by Bruker in June 2025, the completion of the SomaLogic acquisition by Illumina in January 2026, the Waters combination with the BD Biosciences business in February 2026, the initial public offering of Alamar Biosciences in April 2026, and the new Orbitrap platforms introduced in June 2026.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Proteogenomics Market. The key players profiled in the report include Thermo Fisher Scientific Inc. (U.S.), Illumina, Inc. (U.S.), Danaher Corporation (SCIEX) (U.S.), Bruker Corporation (U.S.), Waters Corporation (U.S.), Alamar Biosciences, Inc. (U.S.), Seer, Inc. (U.S.), 10x Genomics, Inc. (U.S.), and Novogene Co., Ltd. (China).
- Thermo Fisher Scientific Inc.
- Illumina, Inc.
- Danaher Corporation (SCIEX)
- Bruker Corporation
- Waters Corporation
- Alamar Biosciences, Inc.
- Seer, Inc.
- 10x Genomics, Inc.
- Novogene Co., Ltd
Expert perspectives
The Proteogenomics Market is entering a period in which the integration of protein and genetic data, rather than the generation of either data type alone, is becoming the main source of value. With Thermo Fisher Scientific owning both Olink and Orbitrap technologies, Illumina combining SomaLogic with its sequencing ecosystem, and population-scale studies in the U.K. and Singapore linking protein data to genetic and health data, proteogenomics is moving from specialized research to a core approach in drug discovery and precision medicine. The binding constraint is shifting from the ability to measure proteins at scale to the ability to integrate, interpret, and act on very large multiomic datasets.
Three structural changes are expected to shape competitive positions through 2036. First, consolidation is concentrating proteomics and genomics capabilities within a small number of large providers, favoring integrated workflows and global reach. Second, NGS-based affinity proteomics is expanding the scale of proteogenomic studies, while mass spectrometry remains essential for protein variants and modifications, encouraging combined approaches. Third, AI-enabled data integration is expected to become a key differentiator, as pharmaceutical companies seek actionable target and biomarker insights rather than raw data.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in multiomic data integration software, proteogenomic services for pharmaceutical target discovery, neoantigen and immunopeptidomics workflows, and partnerships with national biobanks in Asia-Pacific and the Middle East. For established providers, the principal risks are research funding constraints, the complexity of data integration, and financial pressure on specialized technology providers.
Overall, the market is expected to grow strongly, with consumables, mass spectrometry, and cancer research providing the core of demand and software, NGS-based affinity proteogenomics, population health studies, and Asia-Pacific providing the fastest growth.
Customer perspectives
Insights gathered during primary interviews with translational scientists, proteomics and genomics core directors, and biobank leaders operating in this market highlight where procurement priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects the role of proteogenomics in pharmaceutical target selection.”
“This indicates the importance of mass spectrometry in cancer proteogenomics.”
“This points to the growing importance of data integration and software.”
Frequently asked questions
The global Proteogenomics Market is estimated at USD 1.33 billion in 2026.
Cite this report
Meticulous Research. (2026). Proteogenomics Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MR-2340). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/proteogenomics-market-7023