Computer Vision in Healthcare Market (2026-2036)
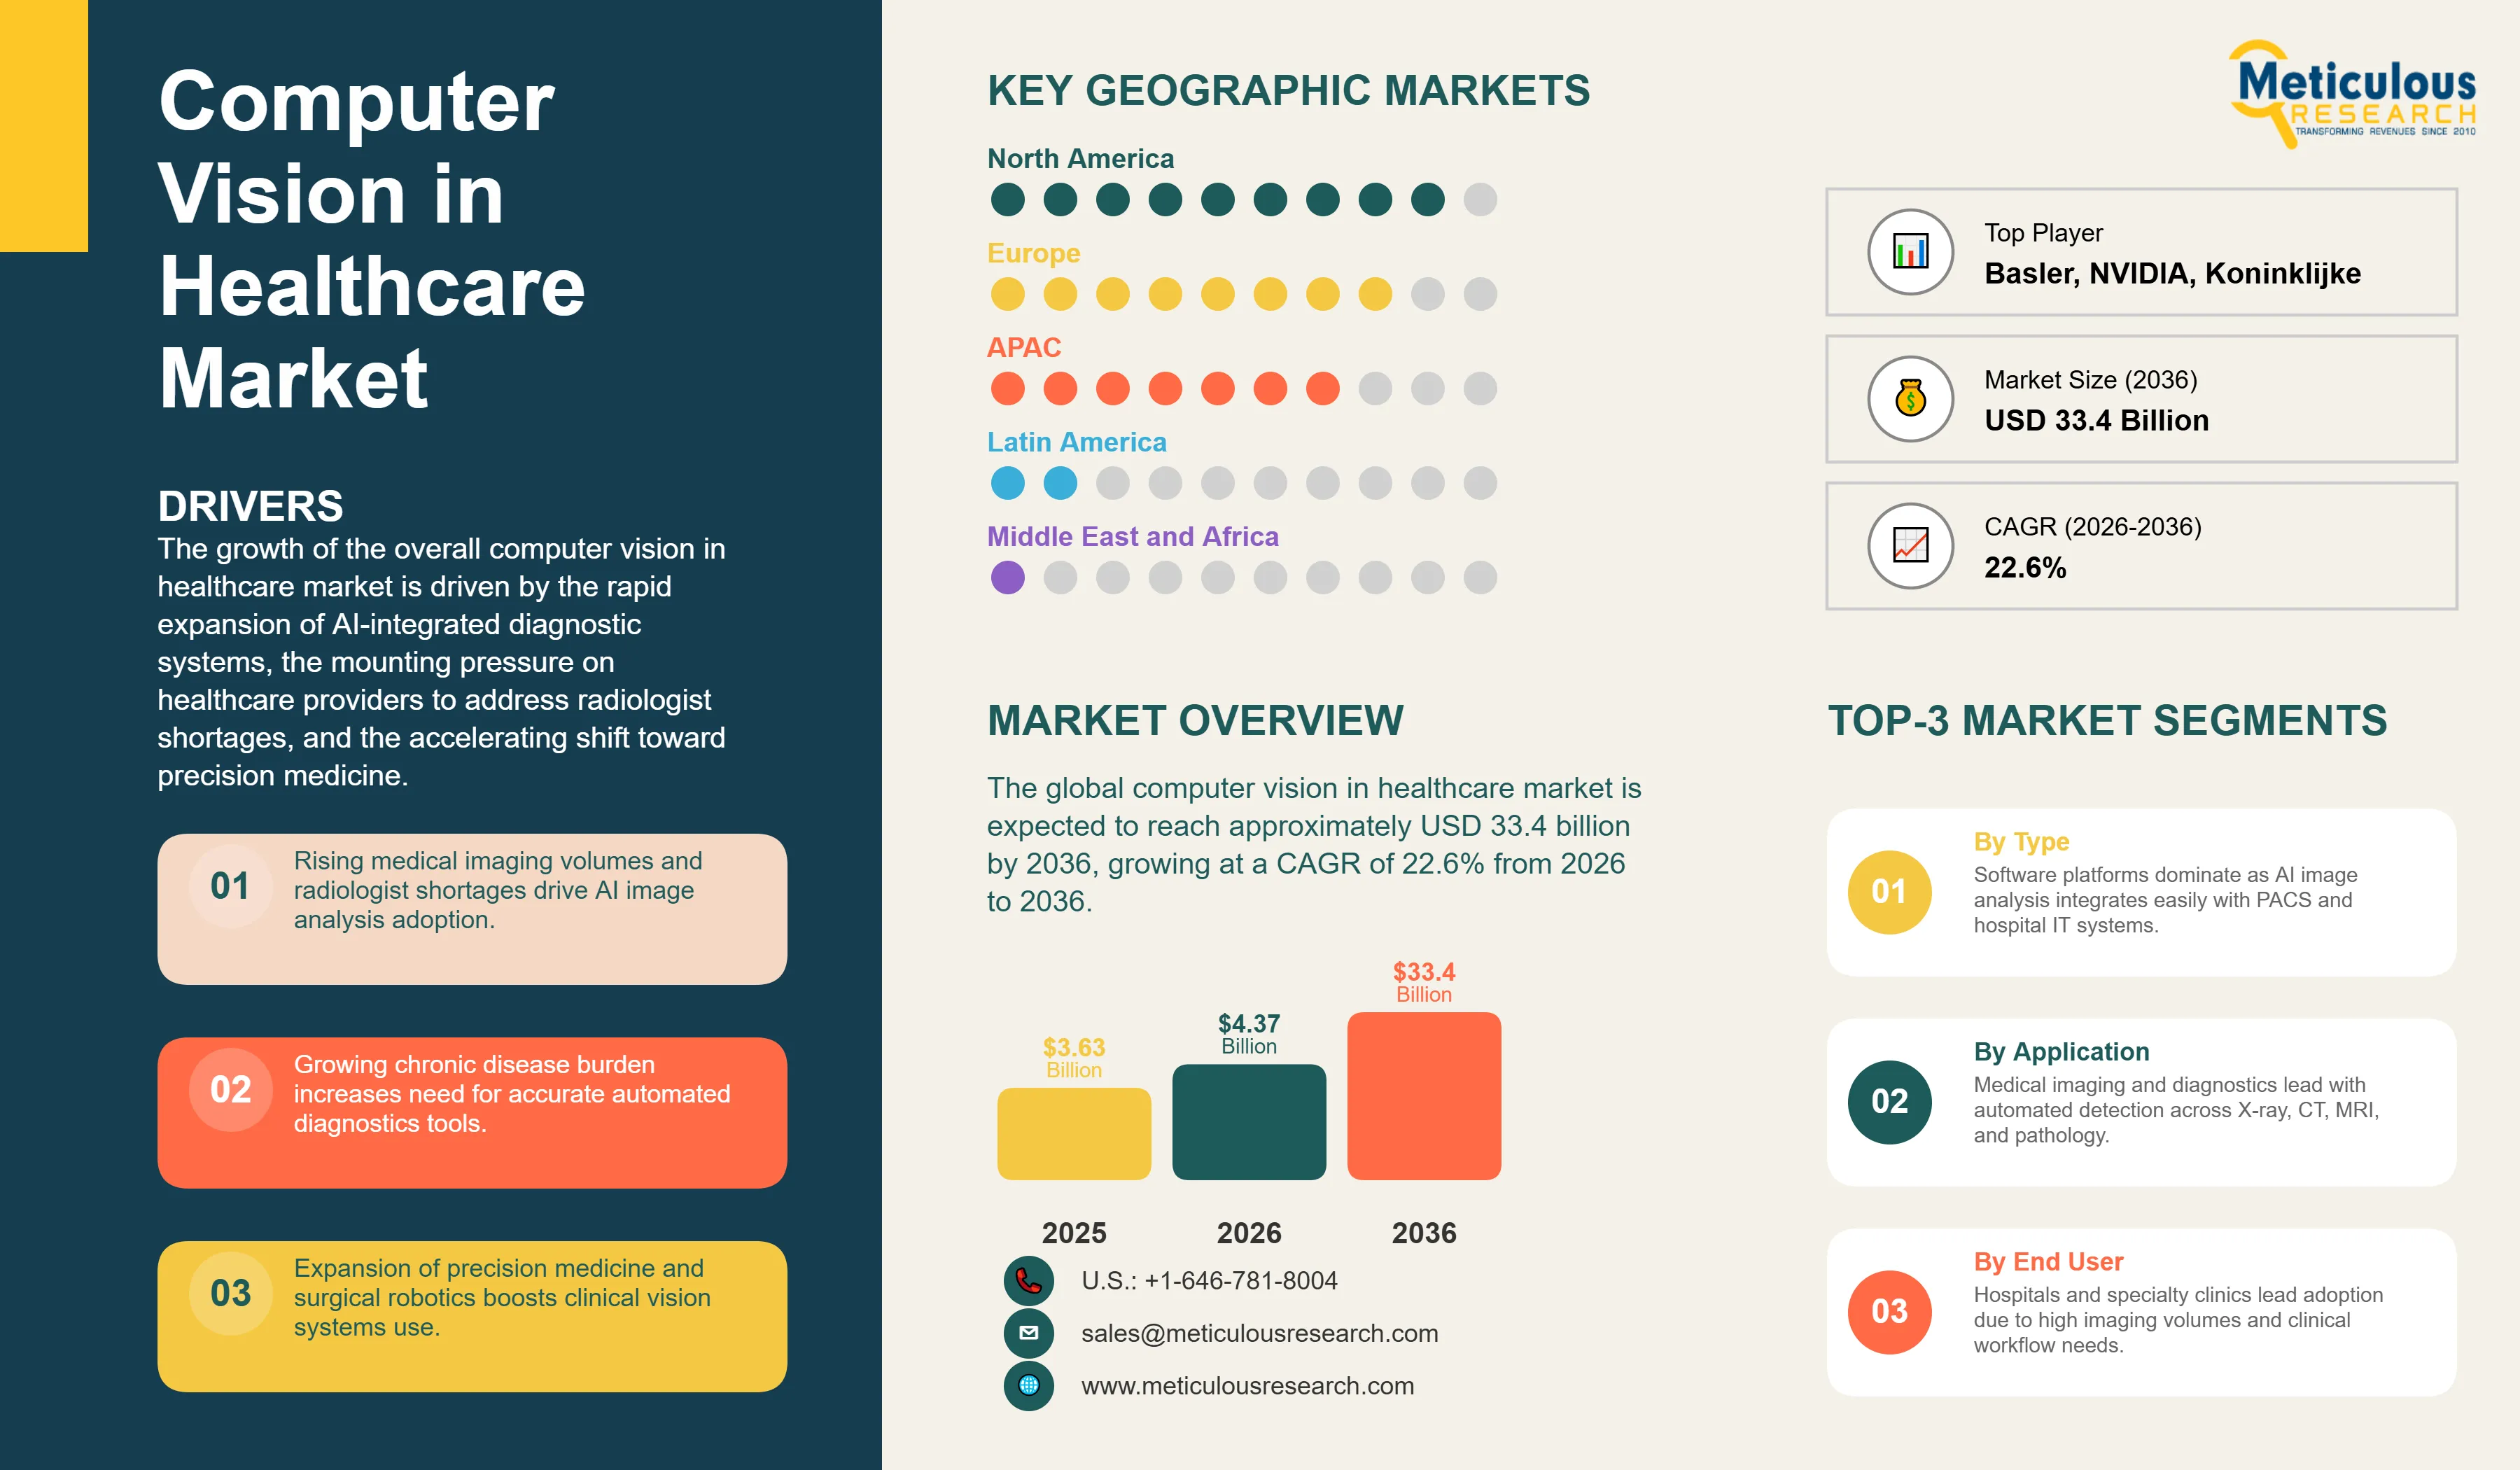
The global computer vision in healthcare market was valued at USD 3.63 billion in 2025. The market is expected to reach approximately USD 33.4 billion by 2036 from USD 4.37 billion in 2026, growing at a CAGR of 22.6% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 307
- Format
- PDF + Excel
- Report ID
- MR-1789
- Base year
- 2025
- 2025 · BASELINE
- $3.63B
- 2036
- $33.40B
- CAGR 2026–2036
- 22.6%
2025 baseline · 2026–2036 forecast at 22.6% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global computer vision in healthcare market is projected to reach USD 33.4 billion by 2036.
The market is expected to grow at a CAGR of 22.6% from 2026 to 2036.
North America dominates the global computer vision in healthcare market with the largest market share in 2026, driven by advanced healthcare infrastructure, high imaging volumes, regulatory pathways for AI-enabled medical devices, and strong venture investment into health technology companies in the U.S. and Canada.
Asia-Pacific is expected to witness the fastest growth during the forecast period, supported by rapid digital transformation of healthcare systems, expanding hospital networks, and significant government investments in AI-driven medical technology in China, India, Japan, and South Korea.
By component, the software segment holds the largest market share in 2026, driven by widespread cloud-based deployment, the scalability of AI platforms, and the ease of integrating image analysis software into existing clinical workflows without requiring significant hardware overhauls.
By application, the medical imaging & diagnostics segment holds the largest share of the overall market in 2026, owing to the massive volume of radiology, pathology, and other imaging data generated globally and the demonstrated clinical value of AI-driven image interpretation tools.
By end user, the hospitals & specialty clinics segment holds the largest share of the overall market in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 33.4 Billion |
| Market Size in 2026 | USD 4.37 Billion |
| Market Size in 2025 | USD 3.63 Billion |
| Market Growth Rate (2026-2036) | CAGR of 22.6% |
| Format | PDF, Excel & Cloud Portal · 307 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Component, Application, Imaging Modality, Deployment Mode, End User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: component, application, imaging modality, deployment mode, end user.
The growth of the overall computer vision in healthcare market is driven by the rapid expansion of AI-integrated diagnostic systems, the mounting pressure on healthcare providers to address radiologist shortages, and the accelerating shift toward precision medicine. As healthcare institutions increasingly integrate intelligent imaging and automation into their clinical workflows, computer vision has become a foundational technology for improving diagnostic accuracy, surgical safety, and patient monitoring across all care settings. The sustained rise in medical imaging volumes globally, the growing burden of chronic disease, and the rapid maturation of deep-learning algorithms continue to fuel significant growth across all major geographic regions.
Computer vision in healthcare refers to the application of artificial intelligence algorithms, particularly deep learning and machine learning, that enable computing systems to analyze, interpret, and derive clinically meaningful insights from visual data such as medical images, surgical video feeds, and patient monitoring streams. These systems range from AI-powered radiology platforms that automatically detect lesions on CT and MRI scans to real-time surgical intelligence tools that guide minimally invasive procedures and computer vision software that continuously monitors patients for falls, deterioration, or medication adherence. The market is defined by solutions that measurably reduce diagnostic error rates, accelerate clinical workflows, and allow healthcare providers to scale high-quality care delivery in environments facing persistent workforce shortages.
The market encompasses a broad spectrum of offerings, from standalone image analysis software and AI inference hardware to fully integrated clinical workflow platforms. Solutions are increasingly delivered via cloud-based deployment models that allow healthcare organizations to scale rapidly without heavy upfront infrastructure investment, while on-premise deployments remain critical in environments with stringent data privacy requirements. Manufacturers such as GE HealthCare and Siemens Healthineers have built expansive ecosystems where hardware imaging modalities and AI software layers operate as unified platforms, enabling seamless end-to-end intelligent diagnostics. At the same time, technology platform providers such as NVIDIA Corporation and Microsoft Corporation deliver the foundational computing infrastructure and developer ecosystems that power a wide range of healthcare-specific computer vision applications built by specialized software companies.
The global healthcare sector is navigating a period of profound transformation as providers grapple with aging populations, rising volumes of imaging examinations, and a chronic shortage of skilled radiologists and imaging technologists. According to data from the American Society of Radiologic Technologists, vacancy rates for radiographers and sonographers in the U.S. nearly tripled between 2021 and 2023, with 2023 vacancy rates reaching 18.1% for radiography and 16.7% for sonography. This structural challenge has created powerful institutional incentives to adopt computer vision solutions that automate time-consuming image review tasks, triage critical findings, and augment the capacity of existing clinical staff. Regulatory frameworks, including FDA clearance pathways for AI/ML-enabled medical devices, are providing clearer routes to market for software manufacturers, further encouraging investment and adoption.
Report infographic
Market dynamics
4 factors across 3 forcesSurging Medical Imaging Volumes and Chronic Workforce Shortages
A key driver of the computer vision in healthcare market is the widening gap between the global volume of medical imaging examinations and the availability of qualified personnel to interpret them. With more than 4.2 billion medical imaging examinations performed annually worldwide, and the prevalence of chronic conditions such as cardiovascular disease, cancer, and diabetes continuing to rise, the demand for faster and more accurate diagnostic interpretation has never been greater. Healthcare systems in mature markets face acute radiology staffing constraints, while providers in lower-income regions often have no reliable access to specialist interpretation at all. Computer vision solutions directly address this imbalance by automating routine image analysis tasks, intelligently triaging critical findings for priority review, and enabling remote or asynchronous diagnostic workflows. The FDA's ongoing framework for AI/ML-enabled medical device submissions provides the regulatory clarity that encourages software manufacturers to invest in clinical validation and commercialization, further accelerating adoption across hospital systems and diagnostic networks.
Table of contents
12 chapters · 122 sections · 307 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Software | — |
| By Application | Medical imaging & diagnostics | Surgical assistance & robotics |
| By Imaging Modality | X-ray | — |
| By End-User | Hospitals & Specialty Clinics | Diagnostic imaging centers |
By Component
- The software segment accounts for the largest share of the overall computer vision in healthcare market in 2026.
- This dominance reflects the healthcare industry's strong preference for deploying AI capabilities through cloud-based and hybrid software platforms that integrate with existing picture archiving and communication systems (PACS), radiology information systems (RIS), and electronic health record (EHR) platforms without requiring wholesale hardware replacement.
- Image analysis software and deep learning platforms allow healthcare organizations to adopt computer vision capabilities incrementally, update algorithms as clinical evidence evolves, and scale usage across multiple sites through enterprise licensing models.
- Major technology companies including Microsoft Corporation, through its Azure Health Data Services and Nuance AI-powered clinical documentation tools, and Google LLC, through its AI imaging capabilities deployed in NHS hospital systems for breast cancer detection, have established significant positions in this software layer.
- However, the hardware segment, encompassing imaging cameras, medical-grade sensors, and AI inference processors from manufacturers such as NVIDIA, Intel Corporation, and Advanced Micro Devices, Inc. (AMD), is expected to grow at a strong pace during the forecast period, driven by demand for edge-computing infrastructure and the integration of AI processing directly into new imaging modality hardware by manufacturers such as GE HealthCare and Siemens Healthineers.
By Application
- The medical imaging & diagnostics segment holds the largest share of the global computer vision in healthcare market in 2026.
- Medical images, including X-rays, CT scans, MRIs, ultrasounds, pathology slides, and retinal scans, account for approximately 90% of all healthcare data generated, creating the richest and most structured dataset for AI-driven visual analysis in any industry.
- Established manufacturers such as Siemens Healthineers, GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, and Hologic, Inc. have embedded AI-powered computer vision directly into their imaging platforms, enabling automated detection, segmentation, and quantification of clinical findings at the point of image acquisition.
- Specialized software companies including iCAD, Inc., which focuses on AI-based cancer detection, and Aidoc Medical Ltd., which provides AI triage and notification solutions for radiological emergencies, have built focused offerings within this segment that complement the broader platforms of major imaging equipment manufacturers.
- The surgical assistance & robotics segment is expected to grow at the fastest CAGR during the forecast period, as hospitals expand their robotic surgery programs and demand for real-time intraoperative imaging intelligence increases across surgical specialties.
By Imaging Modality
- The X-ray modality segment holds the largest share within the global computer vision in healthcare market in 2026.
- X-ray remains the most widely performed medical imaging examination globally, used extensively in chest screening, orthopaedics, emergency medicine, and pulmonology.
- The high volume, standardized image format, and well-established clinical protocols associated with X-ray imaging make it an ideal modality for AI automation, and manufacturers including GE HealthCare have prioritized autonomous X-ray as a key development frontier.
- The CT segment holds the second-largest share, driven by intensive AI development for oncology, neurological, and cardiovascular applications where multi-slice imaging data benefits substantially from automated analysis.
- The MRI segment is expected to grow steadily, supported by AI-powered image reconstruction technologies such as Siemens Healthineers' Deep Resolve and GE HealthCare's AIR Recon DL, which dramatically reduce scan acquisition times while maintaining diagnostic image quality.
By End-User
- The hospitals & specialty clinics segment commands the largest share of the global computer vision in healthcare market in 2026.
- These settings are the primary sites for advanced diagnostic imaging, surgical procedures, and complex patient monitoring, making them the central hubs for deploying and scaling computer vision technologies across radiology, cardiology, oncology, neurology, and ophthalmology departments.
- Hospitals typically have the IT infrastructure, budget authority, reimbursement access, and multi-specialty clinical expertise needed to evaluate and implement enterprise-scale AI solutions.
- The diagnostic imaging centers segment is expected to grow at the fastest CAGR during the forecast period, driven by the increasing outsourcing of imaging interpretation services and the growing adoption of AI-assisted reading platforms that allow independent imaging networks to manage higher scan volumes with lean radiologist teams.
Geographic analysis
North America
Largest shareNorth America holds the largest share of the global computer vision in healthcare market in 2026. The region's leadership is built on the combination of the world's most advanced healthcare IT infrastructure, the highest per-capita medical imaging volumes among major economies, a clear regulatory pathway through FDA clearance for AI-enabled medical devices, and deep venture capital ecosystems that fund AI health technology companies at scale. The United States is home to leading manufacturers and platform providers including GE HealthCare, NVIDIA Corporation, Microsoft Corporation, Intel Corporation, Google LLC, iCAD, Inc., and Hologic, Inc., all of which maintain significant research and commercial operations in the country. In January 2025, GE HealthCare signed an AI imaging services agreement valued at over USD 249 million with a 31-hospital system, illustrating the scale of enterprise adoption underway in the U.S. market. Canada is also demonstrating strong institutional commitment to AI-driven healthcare; in 2025, Siemens Healthineers secured a USD 560 million agreement with the Canadian government to upgrade imaging infrastructure across Alberta province, including the establishment of AI and machine learning centers of excellence.
Asia-Pacific
Fastest growthAsia-Pacific is expected to register the fastest growth rate in the global computer vision in healthcare market during the forecast period. The region benefits from a combination of large and rapidly growing patient populations, significant government investment in healthcare digitalization, and the presence of major technology manufacturers and an expanding base of AI health technology companies. China is a particularly dynamic market, with domestic manufacturers and platform providers developing AI imaging solutions tailored to the country's high-volume hospital environment, and government programs actively encouraging the integration of AI into national healthcare infrastructure. Japan and South Korea have well-established medical device manufacturing ecosystems, with companies such as Canon Medical Systems Corporation, KEYENCE CORPORATION, and Fujifilm Holdings Corporation advancing AI-enhanced imaging platforms for both domestic and global markets. India represents a significant emerging opportunity, where the scale of the country's unmet diagnostic imaging needs is driving rapid adoption of cloud-based and mobile computer vision solutions that can extend quality diagnostic services to populations in underserved regions.
Europe
Europe accounts for a substantial share of the global computer vision in healthcare market, with growth supported by strong regulatory frameworks, advanced national healthcare systems, and active investment in AI-driven medical technology by both the public sector and major industrial companies. Germany is home to Siemens Healthineers AG and Basler AG, two manufacturers with significant global footprints in AI-enabled medical imaging and industrial-grade healthcare cameras respectively. The European Society of Radiology has been actively engaging with manufacturers to promote AI adoption and establish best practices for integrating computer vision tools into radiology workflows, reflecting the continent's coordinated approach to technology-driven healthcare modernization. The United Kingdom's National Health Service has been among the most prominent early adopters of healthcare AI globally, including Google Health's deployment of AI-powered computer vision for breast cancer screening across NHS facilities.
Competitive landscape
- GE HealthCare Technologies, Inc.
- Siemens Healthineers AG
- Koninklijke Philips N.V.
- NVIDIA Corporation
- Microsoft Corporation
Frequently asked questions
The global computer vision in healthcare market is expected to grow from USD 4.37 billion in 2026 to USD 33.4 billion by 2036.
Cite this report
Meticulous Research. (2026). Computer Vision in Healthcare Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1789). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/computer-vision-in-healthcare-market-6472