CO₂-Derived Chemicals Market (2026-2036)
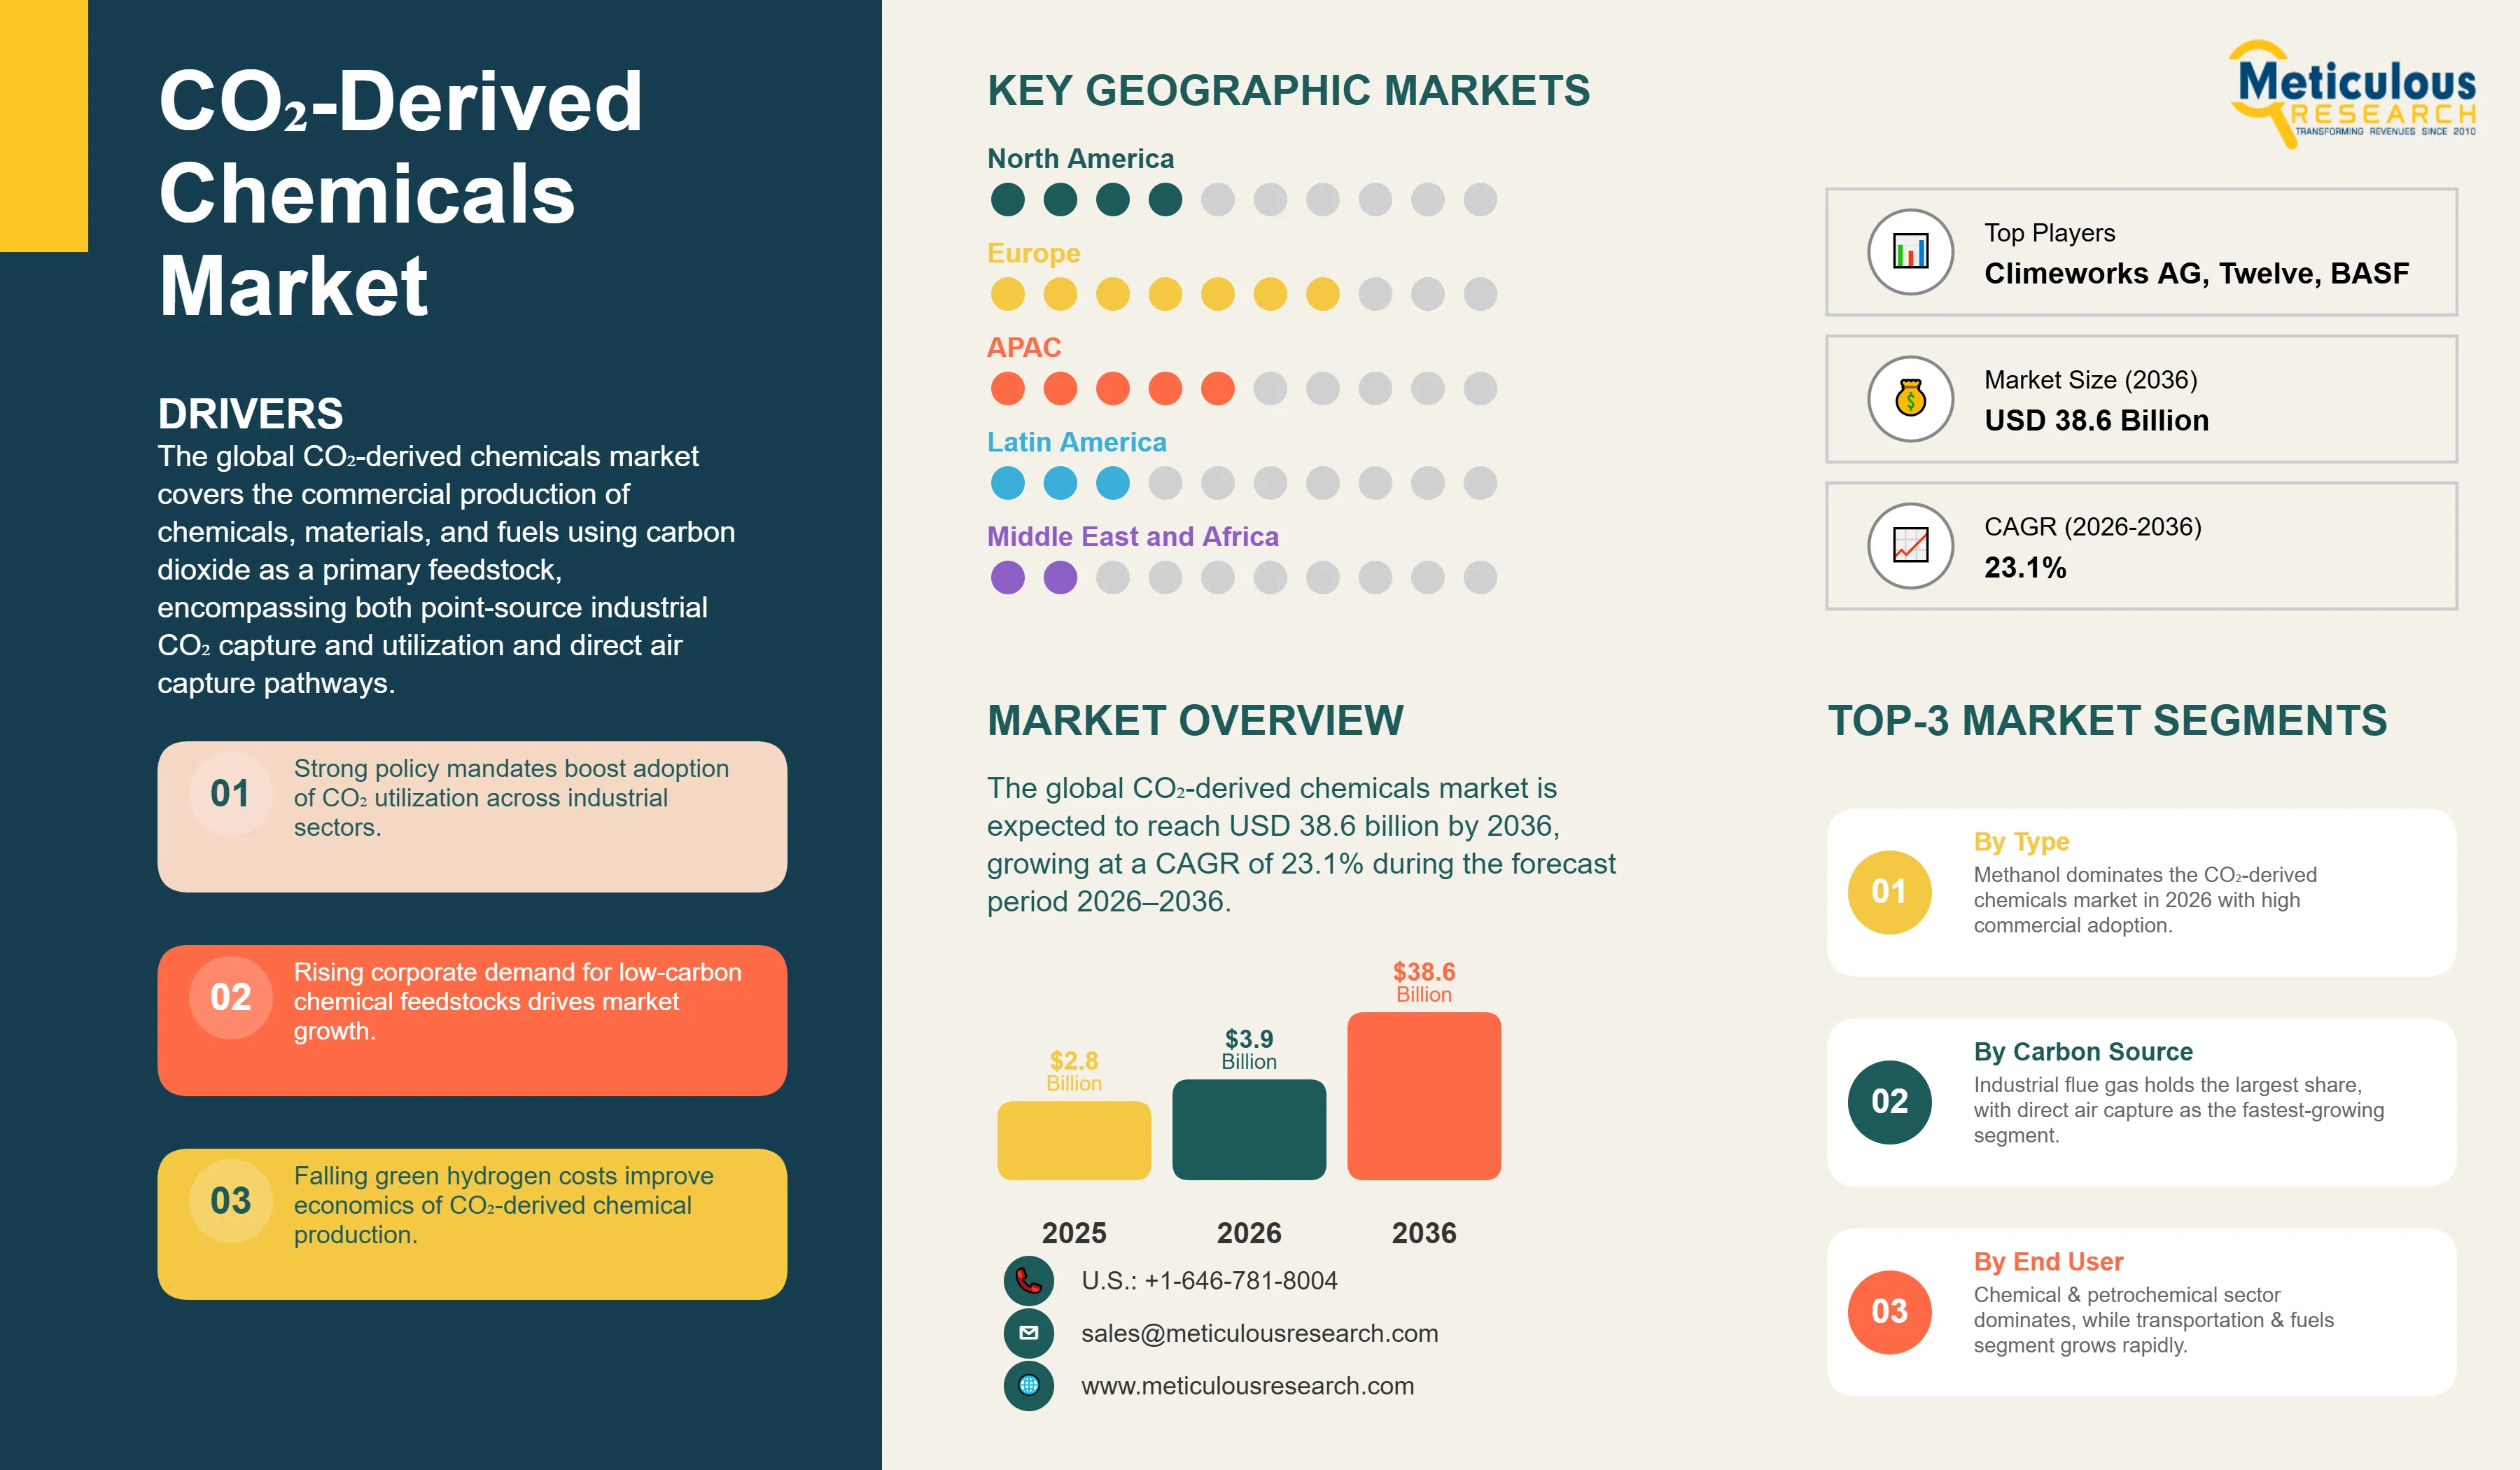
The global CO₂-derived chemicals market was valued at USD 2.8 billion in 2025. This market is expected to reach USD 38.6 billion by 2036 from an estimated USD 3.9 billion in 2026, growing at a CAGR of 23.1% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 288
- Format
- PDF + Excel
- Report ID
- MR-1881
- Base year
- 2025
- 2025 · BASELINE
- $2.80B
- 2036
- $38.60B
- CAGR 2026–2036
- 23.1%
2025 baseline · 2026–2036 forecast at 23.1% CAGR · hover a bar for the value
Key highlights
The global CO₂-derived chemicals market is projected to reach USD 38.6 billion by 2036.
The market is expected to grow at a CAGR of 23.1% during the forecast period 2026–2036.
The global CO₂-derived chemicals market was valued at USD 2.8 billion in 2025 and is estimated to reach USD 3.9 billion in 2026.
Europe is expected to dominate the global CO₂-derived chemicals market with the largest market share in 2026.
By product type, the methanol segment is expected to hold the largest share of the global CO₂-derived chemicals market in 2026.
By conversion technology, the catalytic hydrogenation segment is expected to hold the largest share in 2026.
By carbon source, the industrial flue gas (point-source capture) segment is expected to hold the largest share in 2026.
By end-use industry, the chemical & petrochemical segment is expected to hold the largest share in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 38.6 Billion |
| Market Size in 2026 | USD 3.9 Billion |
| Market Size in 2025 | USD 2.8 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 23.1% |
| Format | PDF, Excel & Cloud Portal · 288 pages |
| Dominating Product Type | Methanol |
| Fastest Growing Product Type | Synthetic Fuels (e-Fuels) |
| Dominating Conversion Technology | Catalytic Hydrogenation |
| Fastest Growing Technology | Electrochemical Reduction |
| Dominating Carbon Source | Industrial Flue Gas (Point-Source) |
| Fastest Growing Carbon Source | Direct Air Capture (DAC) |
| Dominating End-Use Industry | Chemical & Petrochemical |
| Fastest Growing End-Use Industry | Transportation & Fuels |
| Dominating Geography | Europe |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: product type, conversion technology, end-use industry, carbon source.
The global CO₂-derived chemicals market covers the commercial production of chemicals, materials, and fuels using carbon dioxide as a primary feedstock, encompassing both point-source industrial CO₂ capture and utilization and direct air capture pathways. The market spans the full spectrum of CO₂ conversion technologies, including catalytic hydrogenation, electrochemical reduction, biological fermentation, and mineralization, and the diverse portfolio of derivative products, including e-methanol, formic acid, urea and fertilizers, polycarbonates, synthetic aviation fuels, and construction aggregates, across the complete value chain from CO₂ capture and conditioning through synthesis, processing, and downstream end-use application.
The growth of the global CO₂-derived chemicals market is primarily driven by the accelerating policy imperative to decarbonize hard-to-abate industrial sectors, the escalating corporate demand for low-carbon chemical feedstocks and sustainable aviation fuel from major industrial offtakers, and the progressive cost reduction of green hydrogen as renewable electricity costs decline across major production regions. The European Union’s Carbon Border Adjustment Mechanism, the Inflation Reduction Act’s 45Q tax credit for carbon utilization in the United States, and the emerging carbon pricing frameworks in South Korea, Japan, and Canada are collectively creating the economic incentive structure required to commercialize CO₂ utilization at scale by improving the cost competitiveness of CO₂-derived products against their fossil-feedstock equivalents.
However, the market faces meaningful constraints. The production cost of CO₂-derived methanol, formic acid, and synthetic fuels remains substantially higher than fossil-derived equivalents in the absence of carbon pricing, creating a green premium that currently limits offtake to sustainability-committed industrial buyers and regulated applications such as sustainable aviation fuel blending mandates. The energy intensity of electrochemical CO₂ reduction processes and the efficiency losses inherent in CO₂ hydrogenation chemistry impose fundamental thermodynamic costs that must be offset by low-cost, low-carbon electricity and hydrogen to achieve commercially viable production economics.
Despite these challenges, the market outlook is strongly positive. The falling levelized cost of green hydrogen from renewable electrolysis, combined with the expanding commercial scale of direct air capture and the growing availability of concentrated industrial CO₂ streams from cement, steel, and fertilizer production, is progressively improving the production economics of the leading CO₂-derived chemicals. The strategic entry of major chemical companies including BASF, LanzaTech, Covestro, and Siemens Energy into CO₂ utilization technology platforms, combined with the landmark commercial projects being advanced by Carbon Recycling International, Haldor Topsøe, and Carbon Engineering, is driving rapid technology maturation and cost reduction across the CO₂ utilization value chain.
Report infographic
Market dynamics
8 factors across 3 forcesAccelerating Policy Mandates for Carbon Utilization and Industrial Decarbonization
The primary structural driver of the global CO₂-derived chemicals market is the rapidly strengthening policy and regulatory environment across major economies that is creating binding demand for low-carbon chemicals, fuels, and materials and providing financial incentives for CO₂ capture and utilization technology deployment. The European Union’s Carbon Border Adjustment Mechanism, which entered its transitional phase in October 2023 and will impose full carbon costs on imports of cement, steel, aluminum, fertilizers, hydrogen, and electricity from 2026, is creating a powerful financial incentive for industrial operators in both European and non-European markets to reduce the embodied carbon content of their products through CO₂ utilization and other decarbonization measures. The U.S. Inflation Reduction Act’s Section 45Q tax credit provides USD 60 per tonne of CO₂ utilized in non-EOR applications, substantially improving the economics of commercial CO₂ utilization projects across the United States. Japan’s Green Innovation Fund, South Korea’s carbon neutrality roadmap, and the EU Innovation Fund are collectively mobilizing several billion euros of co-funding for CO₂ utilization technology demonstration and commercial deployment.
Growing Corporate Demand for Sustainable Chemical Feedstocks
The escalating corporate sustainability commitments and science-based emissions reduction targets adopted across major chemical, materials, and consumer goods companies are generating growing demand for low-carbon and CO₂-derived chemical feedstocks that is creating commercial offtake pull for CO₂ utilization projects at commercial scale. Major chemical companies including BASF, Covestro, and Borealis have announced product lines incorporating CO₂ as a feedstock, including Covestro’s cardyon polyol technology that uses CO₂ as a partial replacement for fossil-derived propylene oxide in polyurethane production. IKEA’s commitment to sourcing renewable and recycled materials, Unilever’s carbon footprint reduction targets for cleaning product surfactants, and the automotive industry’s demand for CO₂-derived polycarbonates and polymers for vehicle lightweighting are collectively expanding the addressable market for CO₂-derived chemicals across multiple downstream industrial verticals.
Table of contents
12 chapters · 169 sections · 288 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Methanol | Synthetic fuels (e-fuels) |
By Product Type
- Methanol to Dominate
- The global CO₂-derived chemicals market is segmented into methanol, formic acid, urea and fertilizers, polycarbonates and polymers, synthetic fuels (e-fuels), and other CO₂-derived chemicals.
- The methanol segment is expected to account for the largest share of the global CO₂-derived chemicals market.
- The large share of this segment is attributed to methanol’s status as the most technically mature and commercially advanced CO₂-derived chemical, the established global methanol market providing clear offtake pathways for green methanol production, the accelerating demand from the maritime shipping sector for methanol as a low-carbon marine fuel, and the multiple commercial and near-commercial e-methanol production projects operating or under construction in Iceland, Denmark, Germany, and South Korea that are establishing production reference points and commercial pricing benchmarks for the broader market.
- However, the synthetic fuels (e-fuels) segment is poised to register the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the binding SAF blending mandates being implemented across European Union member states and the anticipated expansion of global SAF regulations, the aviation industry’s structural inability to fully decarbonize through electrification or hydrogen fuel cells on medium and long-haul routes, and the committed investment programs by oil majors, aerospace companies, and independent e-fuel developers in power-to-liquid production infrastructure that is advancing commercial-scale synthesis capacity toward the end of the forecast period.
- Catalytic Hydrogenation to Hold the Largest Share
- The global CO₂-derived chemicals market is segmented into catalytic hydrogenation, electrochemical reduction, biological/fermentation, mineralization and carbonation, and thermochemical conversion.
- The catalytic hydrogenation segment is expected to account for the largest share of the global CO₂-derived chemicals market.
- This dominance reflects the technological maturity and commercial validation of CO₂ hydrogenation chemistry for methanol, formic acid, and synthetic fuel production, the substantial installed base of pilot and commercial catalytic hydrogenation reactors already generating revenue from CO₂-derived methanol sales, and the strong pipeline of commercial catalytic hydrogenation projects in advanced development across Europe, the Middle East, and Asia-Pacific.
- However, the electrochemical reduction segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the potential of electrochemical reduction to produce a broader range of CO₂-derived chemicals with higher atom economy than hydrogenation pathways, the falling cost of renewable electricity that underpins electrochemical process economics, and the significant venture capital and corporate R&D investment in eCO₂R technology platforms that is accelerating technology readiness level advancement and reducing capital costs for electrolyzer stack manufacturing.
- Industrial Flue Gas to Hold the Largest Share
- The global CO₂-derived chemicals market is segmented into industrial flue gas (point-source capture), direct air capture, and biogenic CO₂.
- The industrial flue gas segment is expected to account for the largest share of the global CO₂-derived chemicals market.
- This dominance reflects the substantially lower cost of CO₂ capture from concentrated industrial point sources such as cement kilns, steel blast furnaces, and ammonia plants—where CO₂ capture costs range from USD 15 to 50 per tonne—relative to direct air capture costs of USD 200 to 600 per tonne that remain prohibitive for most commercial CO₂-derived chemicals applications at current scale.
- The geographic concentration of large industrial CO₂ emitters in regions with developing CO₂ utilization industries, including the Rhine-Ruhr industrial corridor, the Benelux chemical cluster, and the South Korean and Japanese industrial coastal zones, provides accessible CO₂ feedstock supply for the current generation of commercial CO₂-derived chemicals projects.
- However, the direct air capture segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the accelerating commercial scale-up of DAC technology by Climeworks, Carbon Engineering, and emerging DAC developers, the strategic imperative to produce CO₂-derived chemicals with a net-negative carbon footprint for the most demanding sustainability certification standards, and the projected rapid reduction in DAC costs from current levels toward USD 100 to 150 per tonne by 2030 as technology matures and deployment scales.
Geographic analysis
Europe
Largest shareIn 2026, Europe is expected to account for the largest share of the global CO₂-derived chemicals market. The largest share of this region is mainly due to Europe’s first-mover advantage in CO₂ utilization policy, technology development, and commercial deployment, anchored by the European Union’s comprehensive regulatory framework for carbon capture and utilization, the Carbon Border Adjustment Mechanism providing ongoing financial incentive for industrial decarbonization, and the strong pipeline of commercial CO₂ utilization projects in Germany, the Netherlands, Denmark, Norway, and Iceland. The European Commission’s Innovation Fund, which has committed over EUR 3.4 billion to large-scale innovative low-carbon technology projects across multiple rounds, has specifically supported CO₂ utilization projects including e-methanol synthesis, CO₂-to-chemicals electrochemical platforms, and power-to-liquid e-fuel production facilities. Germany’s Carbon Management Strategy, the Netherlands’ SDE++ subsidy program for CO₂ utilization, and the Nordic nations’ green hydrogen and e-fuel strategies collectively constitute the world’s most developed commercial CO₂-derived chemicals policy ecosystem.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific CO₂-derived chemicals market is expected to grow at the fastest CAGR during the forecast period. The region’s rapid growth is driven by Japan’s ambitious Green Innovation Fund commitment of JPY 2 trillion (approximately USD 15 billion) for hydrogen and carbon recycling technology scale-up, including commercial CO₂-derived methanol and synthetic fuels programs; South Korea’s Carbon Neutrality and Green Growth Strategy that establishes specific targets for CO₂ utilization technology deployment in the Korean petrochemical and steel industries; China’s national CO₂ capture, utilization, and storage roadmap that is advancing commercial CO₂-to-methanol projects at coal chemical and cement industrial clusters; and Australia’s strategic positioning as a low-cost green hydrogen production hub with CO₂ utilization as a value-added export pathway. The strong domestic chemical and refining industry presence in Japan, South Korea, and China provides both the CO₂ point-source feedstock and the downstream chemical offtake infrastructure required to support large-scale CO₂-derived chemicals manufacturing.
North America
North America is establishing a growing CO₂-derived chemicals commercial pipeline, primarily concentrated in the United States where the Inflation Reduction Act’s 45Q tax credit for carbon utilization has materially improved project economics and stimulated significant developer interest. LanzaTech’s commercial ethanol and chemical production from industrial waste gas CO and CO₂ streams using proprietary gas fermentation technology represents the most commercially mature U.S. CO₂ utilization platform, with multiple operational plants supplying sustainable aviation fuel blendstock and chemical feedstocks to industrial offtakers. The U.S. Department of Energy’s Carbon Utilization Program and the Regional Direct Air Capture Hubs initiative are funding technology demonstration and scale-up projects across multiple CO₂ utilization pathways that are building the commercial reference base for the next generation of investment decisions.
Competitive landscape
- Carbon Recycling International · Iceland
- Haldor Topsøe A/S · Denmark
- LanzaTech (U.S.)
- Covestro AG · Germany
- Siemens Energy AG · Germany
- BASF SE · Germany
- Evonik Industries AG · Germany
- Air Liquide S.A. · France
- Linde plc (Ireland/U.S.)
- Johnson Matthey (U.K.)
- Climeworks AG · Switzerland
- Carbon Engineering Ltd. · Canada
- Twelve Benefit Corporation (U.S.)
- Electrochaea GmbH · Germany
- Sunfire GmbH · Germany
- Opus 12 Inc. (U.S.)
- CarbonCure Technologies · Canada
- Verdox Inc. (U.S.)
Frequently asked questions
The global CO?-derived chemicals market is expected to reach USD 38.6 billion by 2036 from an estimated USD 3.9 billion in 2026, at a CAGR of 23.1% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). CO₂-Derived Chemicals Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1881). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/co₂-derived-chemicals-market-6564