Chemical Recycling Market (2026-2036)
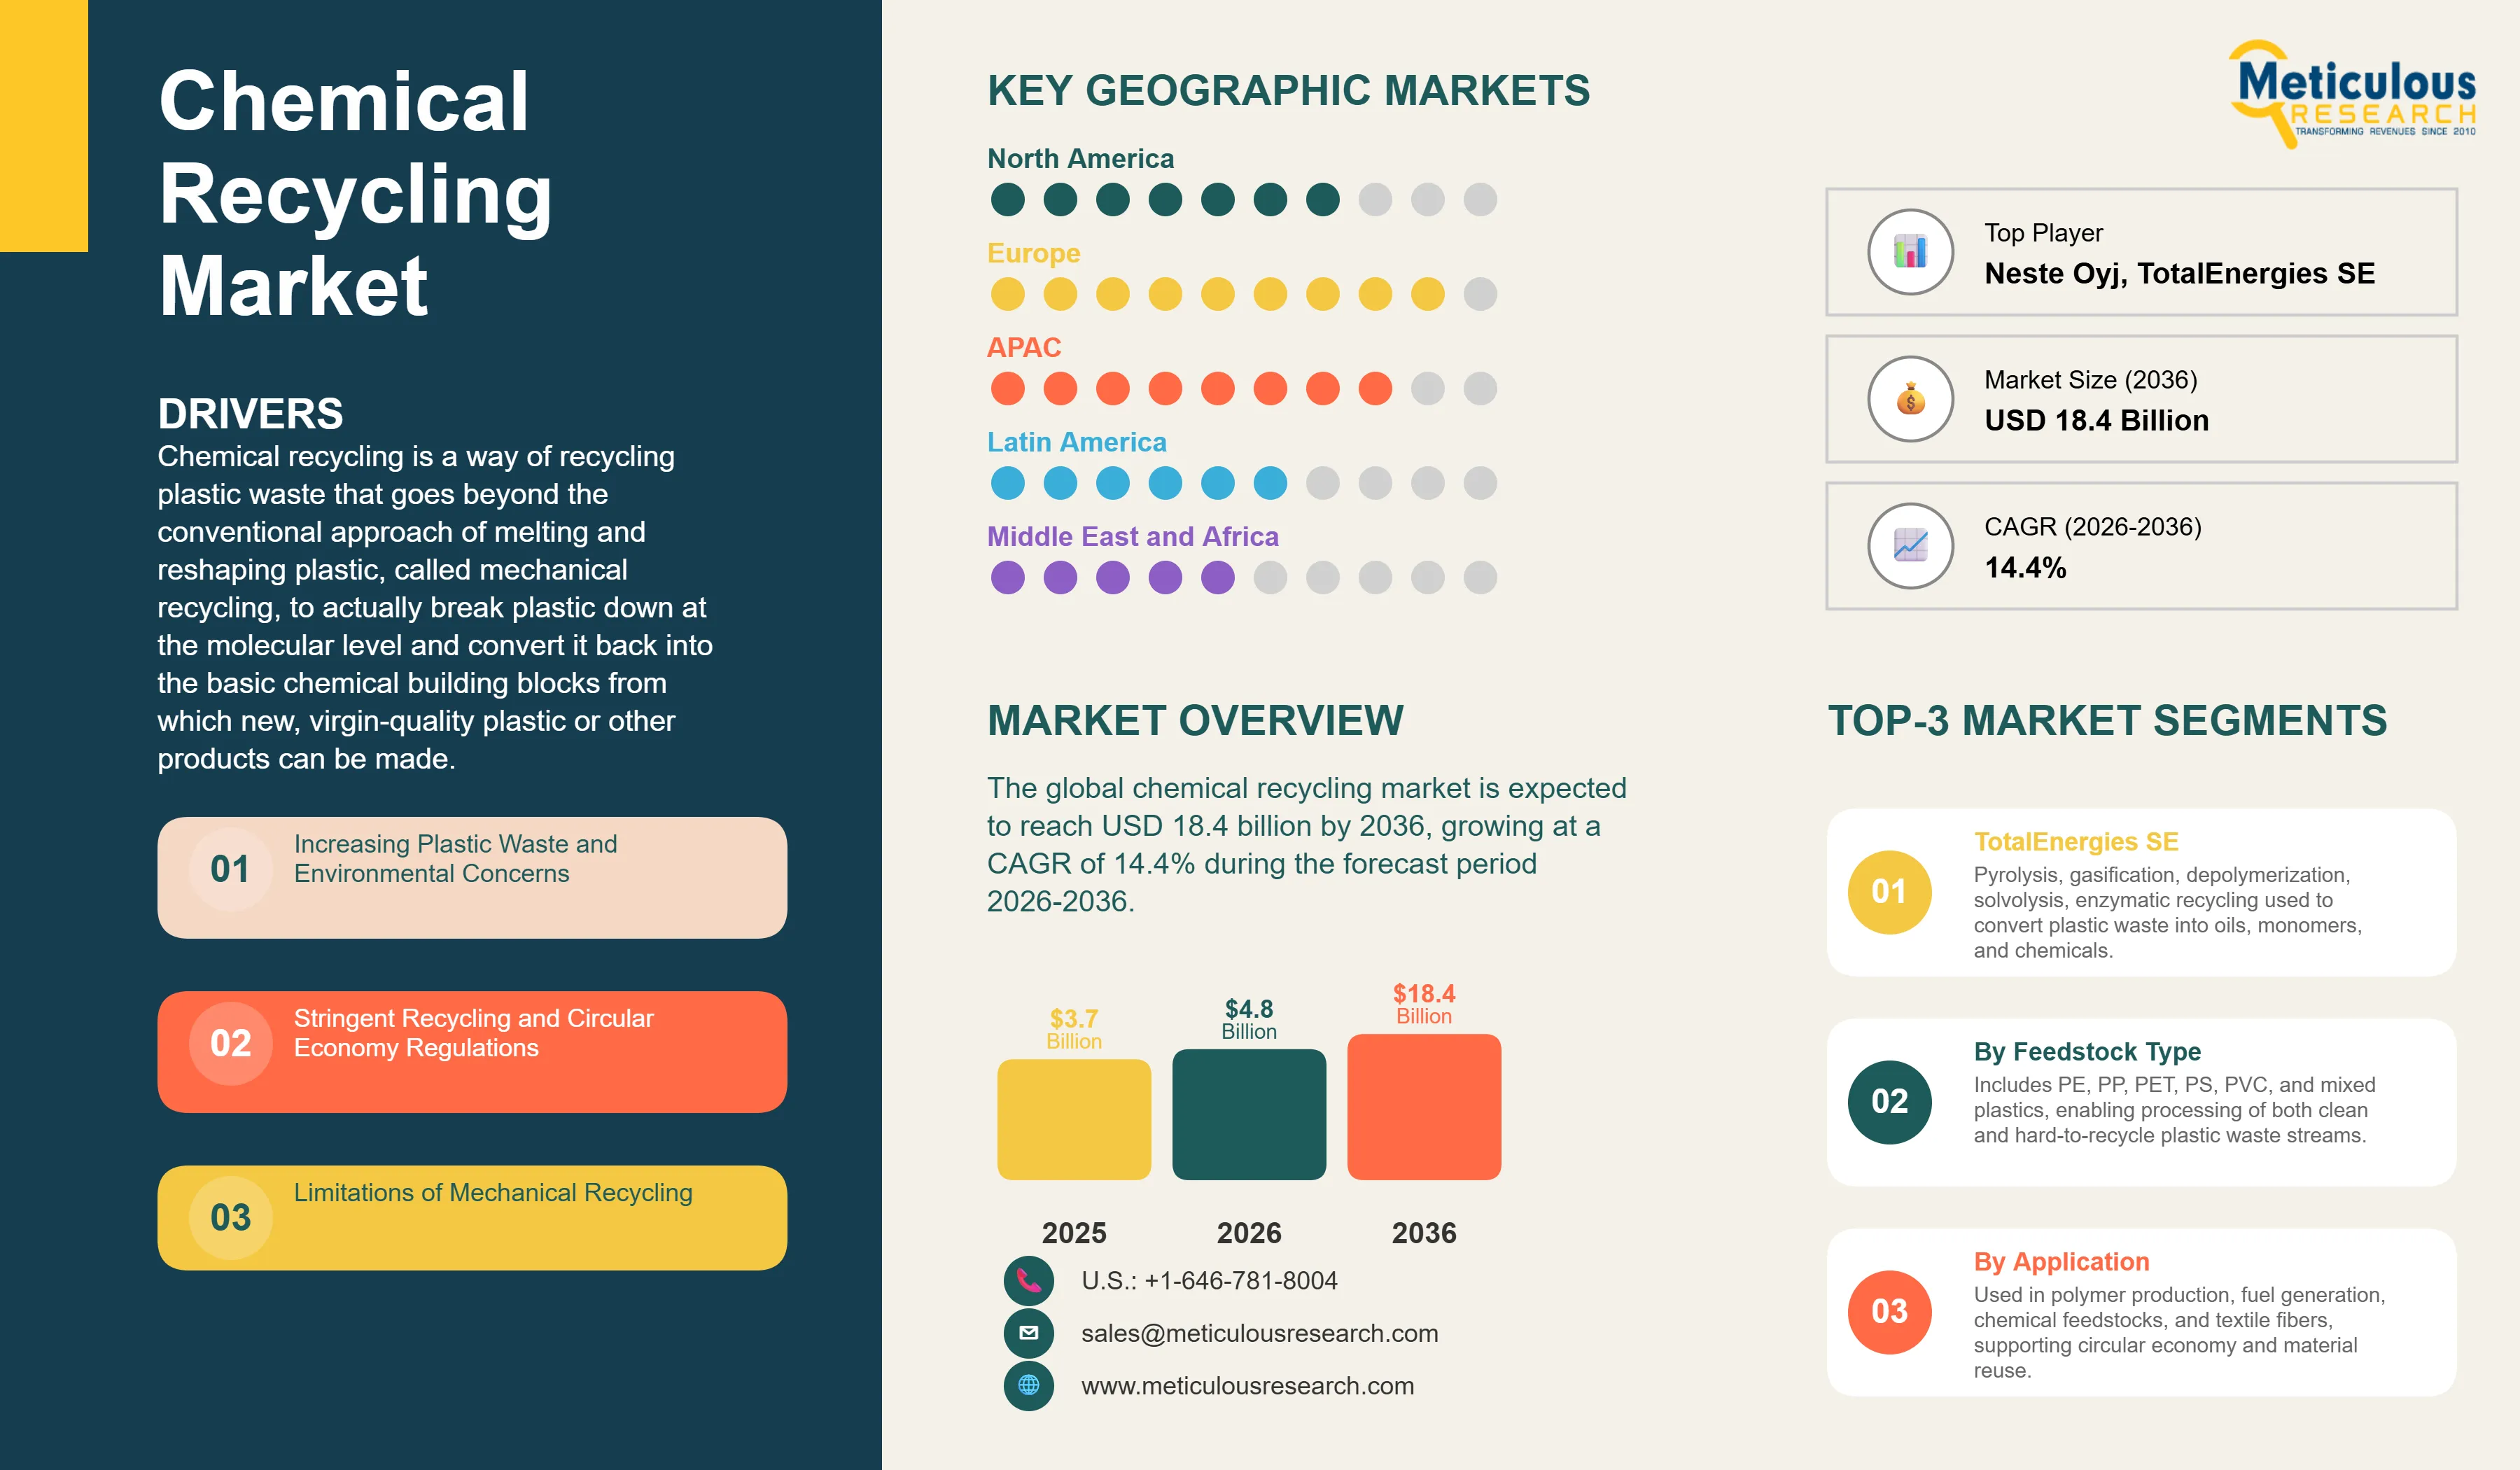
The global chemical recycling market was valued at USD 3.7 billion in 2025. This market is expected to reach USD 18.4 billion by 2036 from an estimated USD 4.8 billion in 2026, growing at a CAGR of 14.4% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 277
- Format
- PDF + Excel
- Report ID
- MR-1931
- Base year
- 2025
- 2025 · BASELINE
- $3.70B
- 2036
- $18.40B
- CAGR 2026–2036
- 14.4%
2025 baseline · 2026–2036 forecast at 14.4% CAGR · hover a bar for the value
Key highlights
The global chemical recycling market is projected to reach USD 18.4 billion by 2036.
The market is expected to grow at a CAGR of 14.4% during the forecast period 2026-2036.
The global market was valued at USD 3.7 billion in 2025 and is estimated to reach USD 4.8 billion in 2026.
Europe is expected to dominate the global chemical recycling market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By technology type, the pyrolysis segment is expected to hold the largest share of the market in 2026, while the enzymatic recycling segment is projected to register the highest CAGR during the forecast period.
By feedstock type, the PET segment is expected to hold the largest share in 2026, while the mixed plastics segment is projected to register the highest CAGR during the forecast period.
By application, the polymer and plastic production segment is expected to hold the largest share in 2026, while the chemical feedstock production segment is projected to register the highest CAGR during the forecast period.
By end-use industry, the packaging industry segment is expected to hold the largest share in 2026, while the automotive industry segment is projected to register the highest CAGR during the forecast period.
By product output, the recycled polymers segment is expected to hold the largest share in 2026, while the chemical intermediates segment is projected to register the highest CAGR during the forecast period.
By process stage, the conversion processes segment is expected to hold the largest share in 2026, while the pre-treatment and sorting segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 18.4 Billion |
| Market Size in 2026 | USD 4.8 Billion |
| Market Size in 2025 | USD 3.7 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 14.4% |
| Format | PDF, Excel & Cloud Portal · 277 pages |
| Dominating Technology Type | Pyrolysis |
| Fastest Growing Technology Type | Enzymatic Recycling |
| Dominating Feedstock Type | Polyethylene Terephthalate (PET) |
| Fastest Growing Feedstock Type | Mixed Plastics |
| Dominating Application | Polymer and Plastic Production |
| Fastest Growing Application | Chemical Feedstock Production |
| Dominating End-Use Industry | Packaging Industry |
| Fastest Growing End-Use Industry | Automotive Industry |
| Dominating Product Output | Recycled Polymers |
| Fastest Growing Product Output | Chemical Intermediates |
| Dominating Process Stage | Conversion Processes |
| Fastest Growing Process Stage | Pre-Treatment and Sorting |
| Dominating Geography | Europe |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: technology type, feedstock type, application, end-use industry.
Chemical recycling is a way of recycling plastic waste that goes beyond the conventional approach of melting and reshaping plastic, called mechanical recycling, to actually break plastic down at the molecular level and convert it back into the basic chemical building blocks from which new, virgin-quality plastic or other products can be made. When you put a plastic bottle in a recycling bin, it typically goes through mechanical recycling where it is shredded, melted, and reformed into lower-grade plastic products like park benches or fleece clothing. Chemical recycling takes a fundamentally different approach by using heat, chemical reactions, or biological enzymes to break the polymer chains in plastic back down into simpler chemicals called monomers or into liquid oils that can be fed directly into chemical and refinery plants as raw material. The key advantage of this approach is that the output material is functionally identical to virgin plastic derived from fossil fuels, which means it can be used in demanding applications like food packaging that requires the highest purity standards and that mechanical recycling typically cannot meet.
The market is growing strongly because the global plastic waste problem has reached a scale that conventional recycling approaches simply cannot solve. Globally, only about 9% of plastic waste is actually recycled, with the rest going to landfill, incineration, or ending up in the natural environment. The primary reason that mechanical recycling cannot handle more plastic is that most real-world plastic waste is a complex mixture of different plastic types, colors, and contaminants that cannot be cleanly sorted and separately recycled, and many plastic types including flexible packaging and multilayer films cannot be mechanically recycled at all because they are too complex or too contaminated. Chemical recycling can in principle accept this mixed, contaminated, and otherwise unrecyclable plastic waste and convert it into useful outputs, addressing the large fraction of plastic waste that the current recycling system simply cannot handle.
Two significant near-term opportunities are driving investment and growth. The European Union's Single-Use Plastics Directive and its packaging regulation require increasingly high levels of recycled content in plastic packaging over the coming years, and companies selling packaged goods in Europe are facing legally binding obligations to include chemically recycled plastic in their packaging if mechanical recycling alone cannot provide sufficient supply of sufficiently high quality recycled material. This regulatory pressure is creating a strong and growing commercial demand signal for chemical recycling output. In addition, the very large food and beverage industry's need for food-grade recycled plastic, which conventional mechanical recycling cannot reliably produce at the required purity level, is creating premium-priced demand for chemically recycled PET and other food-contact plastics that justifies the higher cost of chemical recycling processes compared with mechanical alternatives.
Report infographic
Market dynamics
7 factors across 3 forcesLimitations of Mechanical Recycling
The fundamental constraint of mechanical recycling, which can only process clean, sorted, single-type plastic waste and produces recycled plastic of lower quality than the original material, means that the majority of real-world plastic waste cannot be recycled through existing infrastructure regardless of how many collection bins are provided or how much consumer participation is achieved. Mixed plastic packaging, multilayer films, contaminated containers, and plastic types that are not commercially viable to sort and mechanically recycle separately collectively represent a very large fraction of all plastic waste generated. Chemical recycling addresses this limitation directly because pyrolysis and gasification processes can accept mixed, contaminated, and otherwise unrecyclable plastic feedstocks and convert them into valuable outputs, and depolymerization processes can produce higher-purity outputs from more homogeneous feedstocks. The recognized inadequacy of mechanical recycling alone to meet the plastic recycling targets mandated by EU and national regulations is creating a policy and commercial consensus that chemical recycling must be deployed at significant scale to complement mechanical recycling, which is the most important structural driver of the chemical recycling market.
Rising Demand for Recycled Feedstock
The growing commitments of major consumer goods companies, branded packaging manufacturers, and plastic product companies to increase the recycled content in their products is creating genuine commercial demand for chemically recycled plastic feedstocks that goes beyond regulatory compliance to include brand differentiation and customer expectation. Companies including Danone, Unilever, Coca-Cola, PepsiCo, and L'Oreal have made public commitments to increase the recycled plastic content in their packaging to 25%, 50%, or even higher percentages by 2025 or 2030. These commitments, whether driven by regulatory requirements, investor pressure, or customer preference, are translating into active procurement programs for recycled plastic feedstocks and, where sufficient supply is not available from mechanical recycling, direct investment in or offtake agreements with chemical recycling facilities. The combination of regulatory mandates and voluntary corporate commitments is creating a large and growing demand for recycled plastic feedstocks that exceeds what the current recycling infrastructure can supply, making the expansion of chemical recycling capacity a commercially necessary response to this demand gap.
Table of contents
14 chapters · 181 sections · 277 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Technology Type | Pyrolysis | Enzymatic recycling |
| By Feedstock Type | PET | Mixed plastics |
| By Application | Polymer and Plastic Production | Chemical feedstock production |
| By End-Use Industry | Packaging Industry | Automotive industry |
By Technology Type
- Pyrolysis to Dominate
- The pyrolysis segment is expected to account for the largest share of the global chemical recycling market.
- Pyrolysis, which heats plastic waste in the absence of oxygen to break it down into a mixture of oils, gases, and char, is the most commercially deployed chemical recycling technology globally, with the largest number of operating commercial facilities and the most mature technology base.
- Pyrolysis is particularly well-suited to mixed and contaminated plastic waste that other chemical recycling methods struggle to process, making it the most flexible technology for accepting the diverse real-world plastic waste streams that chemical recyclers must work with.
- Companies including Plastic Energy, Brightmark, Agilyx, and Licella have operated commercial or demonstration pyrolysis plants, and the major oil and petrochemical companies including ExxonMobil, Shell, and TotalEnergies are building large-scale pyrolysis capacity integrated with their existing refinery and petrochemical infrastructure.
- However, the enzymatic recycling segment is projected to register the highest CAGR during the forecast period.
- Carbios's commercial breakthrough with its engineered PETase enzyme, combined with the significant commercial interest from major brands and the licensing agreement with Indorama Ventures for large-scale commercial plant development, is driving rapid investment and development activity in enzymatic recycling.
- The superior output purity achievable through enzymatic depolymerization compared with thermal processes like pyrolysis, and the specific fit of enzymatic recycling for the high-value food-grade PET recycling application, makes this the highest-growth technology segment in the market.
By Feedstock Type
- PET to Hold the Largest Share
- The PET segment is expected to account for the largest share of the overall market.
- PET is the most commercially valuable chemical recycling feedstock because it is widely collected through bottle deposit and curbside recycling systems in developed markets, has well-established depolymerization chemistry through both glycolysis and emerging enzymatic routes, and produces monomer outputs that can directly replace virgin PET at full food-grade quality.
- The large global PET bottle and packaging market, the strong regulatory push for recycled PET content in food and beverage packaging, and the commercial viability of PET depolymerization at current technology costs collectively make PET the dominant feedstock type by revenue.
- However, the mixed plastics segment is projected to register the highest CAGR during the forecast period.
- Mixed plastics represent the largest volume of currently unrecyclable plastic waste that chemical recycling can address, and the pyrolysis and gasification technologies capable of processing mixed plastic waste feedstocks are scaling up rapidly.
- As the volume of plastic waste that needs to be diverted from landfill and incineration grows and as the chemical recycling capacity to process mixed plastics expands, this feedstock segment is expected to grow very rapidly from its current smaller base.
By Application
- Polymer and Plastic Production to Hold the Largest Share
- The polymer and plastic production segment is expected to account for the largest share of the overall market.
- Converting chemically recycled plastic back into new polymer materials, particularly for packaging applications where recycled content requirements are most stringent, is the highest-value application for chemical recycling output and the application that drives the most investment and commercial activity.
- The combination of regulatory mandates requiring recycled content in packaging and the premium pricing achievable for certified recycled polymers makes polymer production the dominant application by revenue value.
- However, the chemical feedstock production segment is projected to register the highest CAGR during the forecast period.
- The conversion of plastic waste into monomers and petrochemical intermediates that can be used as raw materials across the entire chemicals manufacturing value chain, not just for plastic production, represents a larger and more diversified market opportunity than packaging polymer production alone.
- As the pyrolysis and cracking capacity integrated with large petrochemical complexes scales up, the production of chemical intermediates from recycled plastic feedstocks is expected to grow rapidly.
By End-Use Industry
- Packaging Industry to Hold the Largest Share
- The packaging industry segment is expected to account for the largest share of the global chemical recycling market.
- Packaging is both the largest application for plastic globally and the industry facing the most direct and binding regulatory pressure to increase recycled content, making it the primary driver of demand for chemical recycling output.
- The EU Packaging and Packaging Waste Regulation, the UK Plastic Packaging Tax, Canada's draft recycled content regulations, and similar measures in multiple other markets are creating commercially mandatory demand for recycled content in packaging that is directly translating into procurement commitments and investment in chemical recycling capacity.
- However, the automotive industry segment is projected to register the highest CAGR during the forecast period.
- Automakers are under growing pressure to reduce the carbon footprint of their vehicles and to increase the use of recycled materials in vehicle production, and the automotive sector is increasingly adopting recycled polymer materials for interior components, under-hood parts, and structural applications.
- The transition to electric vehicles, which use more plastic components per vehicle than conventional vehicles in battery housings, interior trims, and thermal management systems, is expanding the automotive sector's total plastic consumption and its interest in sustainable recycled material sources.
Geographic analysis
Europe
Largest shareIn 2026, Europe is expected to account for the largest share of the global chemical recycling market. Europe leads the global chemical recycling market because it has the most comprehensive and binding regulatory framework for plastic recycling of any region, creating the strongest and clearest commercial demand signal for recycled plastic that drives investment in chemical recycling capacity at a pace not matched elsewhere. The EU Packaging and Packaging Waste Regulation's mandatory recycled content requirements, the EU's Single-Use Plastics Directive, and the individual national legislation of member states collectively create a regulatory environment where every major consumer goods company and packaging manufacturer operating in the European market must secure supply of high-quality recycled plastic, including chemically recycled material, or face non-compliance. The Netherlands, Belgium, Germany, and France are particularly active chemical recycling development markets, with numerous pilot and commercial-scale facilities operating or under construction. The Netherlands' Rotterdam port area hosts a concentration of chemical and petrochemical infrastructure that makes it a natural hub for chemical recycling facilities integrated with the existing petrochemical value chain. Carbios in France, Plastic Energy in Spain and the UK, and the European programs of BASF, Shell, and TotalEnergies represent the leading commercial chemical recycling activities in the region.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific chemical recycling market is expected to grow at the fastest CAGR during the forecast period. Asia generates the largest volume of plastic waste of any region globally, with China, India, Indonesia, and other developing Asian countries facing severe plastic pollution challenges that are driving national policy action and creating large-scale demand for advanced recycling solutions. China's dual carbon goals and its growing emphasis on circular economy development are driving investment in chemical recycling technology and capacity, with several Chinese companies developing pyrolysis and depolymerization facilities at commercial scale. Japan has a long history of thermal recycling of plastic waste and is now transitioning toward chemical recycling approaches that produce higher-value outputs as the regulatory environment for chemical recycling certification improves. South Korea's government has committed to significant chemical recycling capacity targets as part of its plastic waste management strategy. India's growing awareness of plastic pollution and its expanding regulatory framework for extended producer responsibility is creating the policy foundation for chemical recycling market development, and Indonesia, Thailand, and Vietnam are beginning to invest in chemical recycling infrastructure as international brands pressure their regional packaging suppliers to provide recycled content options.
North America
North America is a large and rapidly growing chemical recycling market, primarily driven by the United States where the combination of state-level recycled content mandates in California, Washington, and other states is creating growing demand for high-quality recycled plastic alongside the large corporate sustainability commitments of major U.S. consumer goods companies. ExxonMobil's large-scale chemical recycling investments at its Baytown Texas facility, which targets processing 500 million pounds of plastic waste annually, represent one of the most ambitious commercial chemical recycling programs in the world. Canada's draft national recycled content standards and British Columbia's extended producer responsibility program for packaging are creating growing policy-driven demand in Canada, and Mexico's growing manufacturing sector is beginning to address plastic waste through chemical recycling initiatives supported by international brand partnerships.
Competitive landscape
- BASF SE · Germany
- Eastman Chemical Company (U.S.)
- Plastic Energy Ltd. (UK)
- Agilyx Corporation (U.S.)
- Neste Oyj · Finland
- Loop Industries Inc. · Canada
- SABIC · Saudi Arabia
- TotalEnergies SE · France
- ExxonMobil Corporation (U.S.)
- Shell plc (UK/Netherlands)
- Veolia Environnement S.A. · France
- Indorama Ventures Public Company Limited · Thailand
- Carbios · France
- Brightmark LLC (U.S.)
- Licella Holdings Ltd. · Australia
Frequently asked questions
The global chemical recycling market is expected to reach USD 18.4 billion by 2036 from an estimated USD 4.8 billion in 2026, at a CAGR of 14.4% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Chemical Recycling Market - Global Opportunity Analysis And Industry Forecasts (2026-2036) (Report No. MR-1931). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/chemical-recycling-market-6614