Transformer Bushings Market
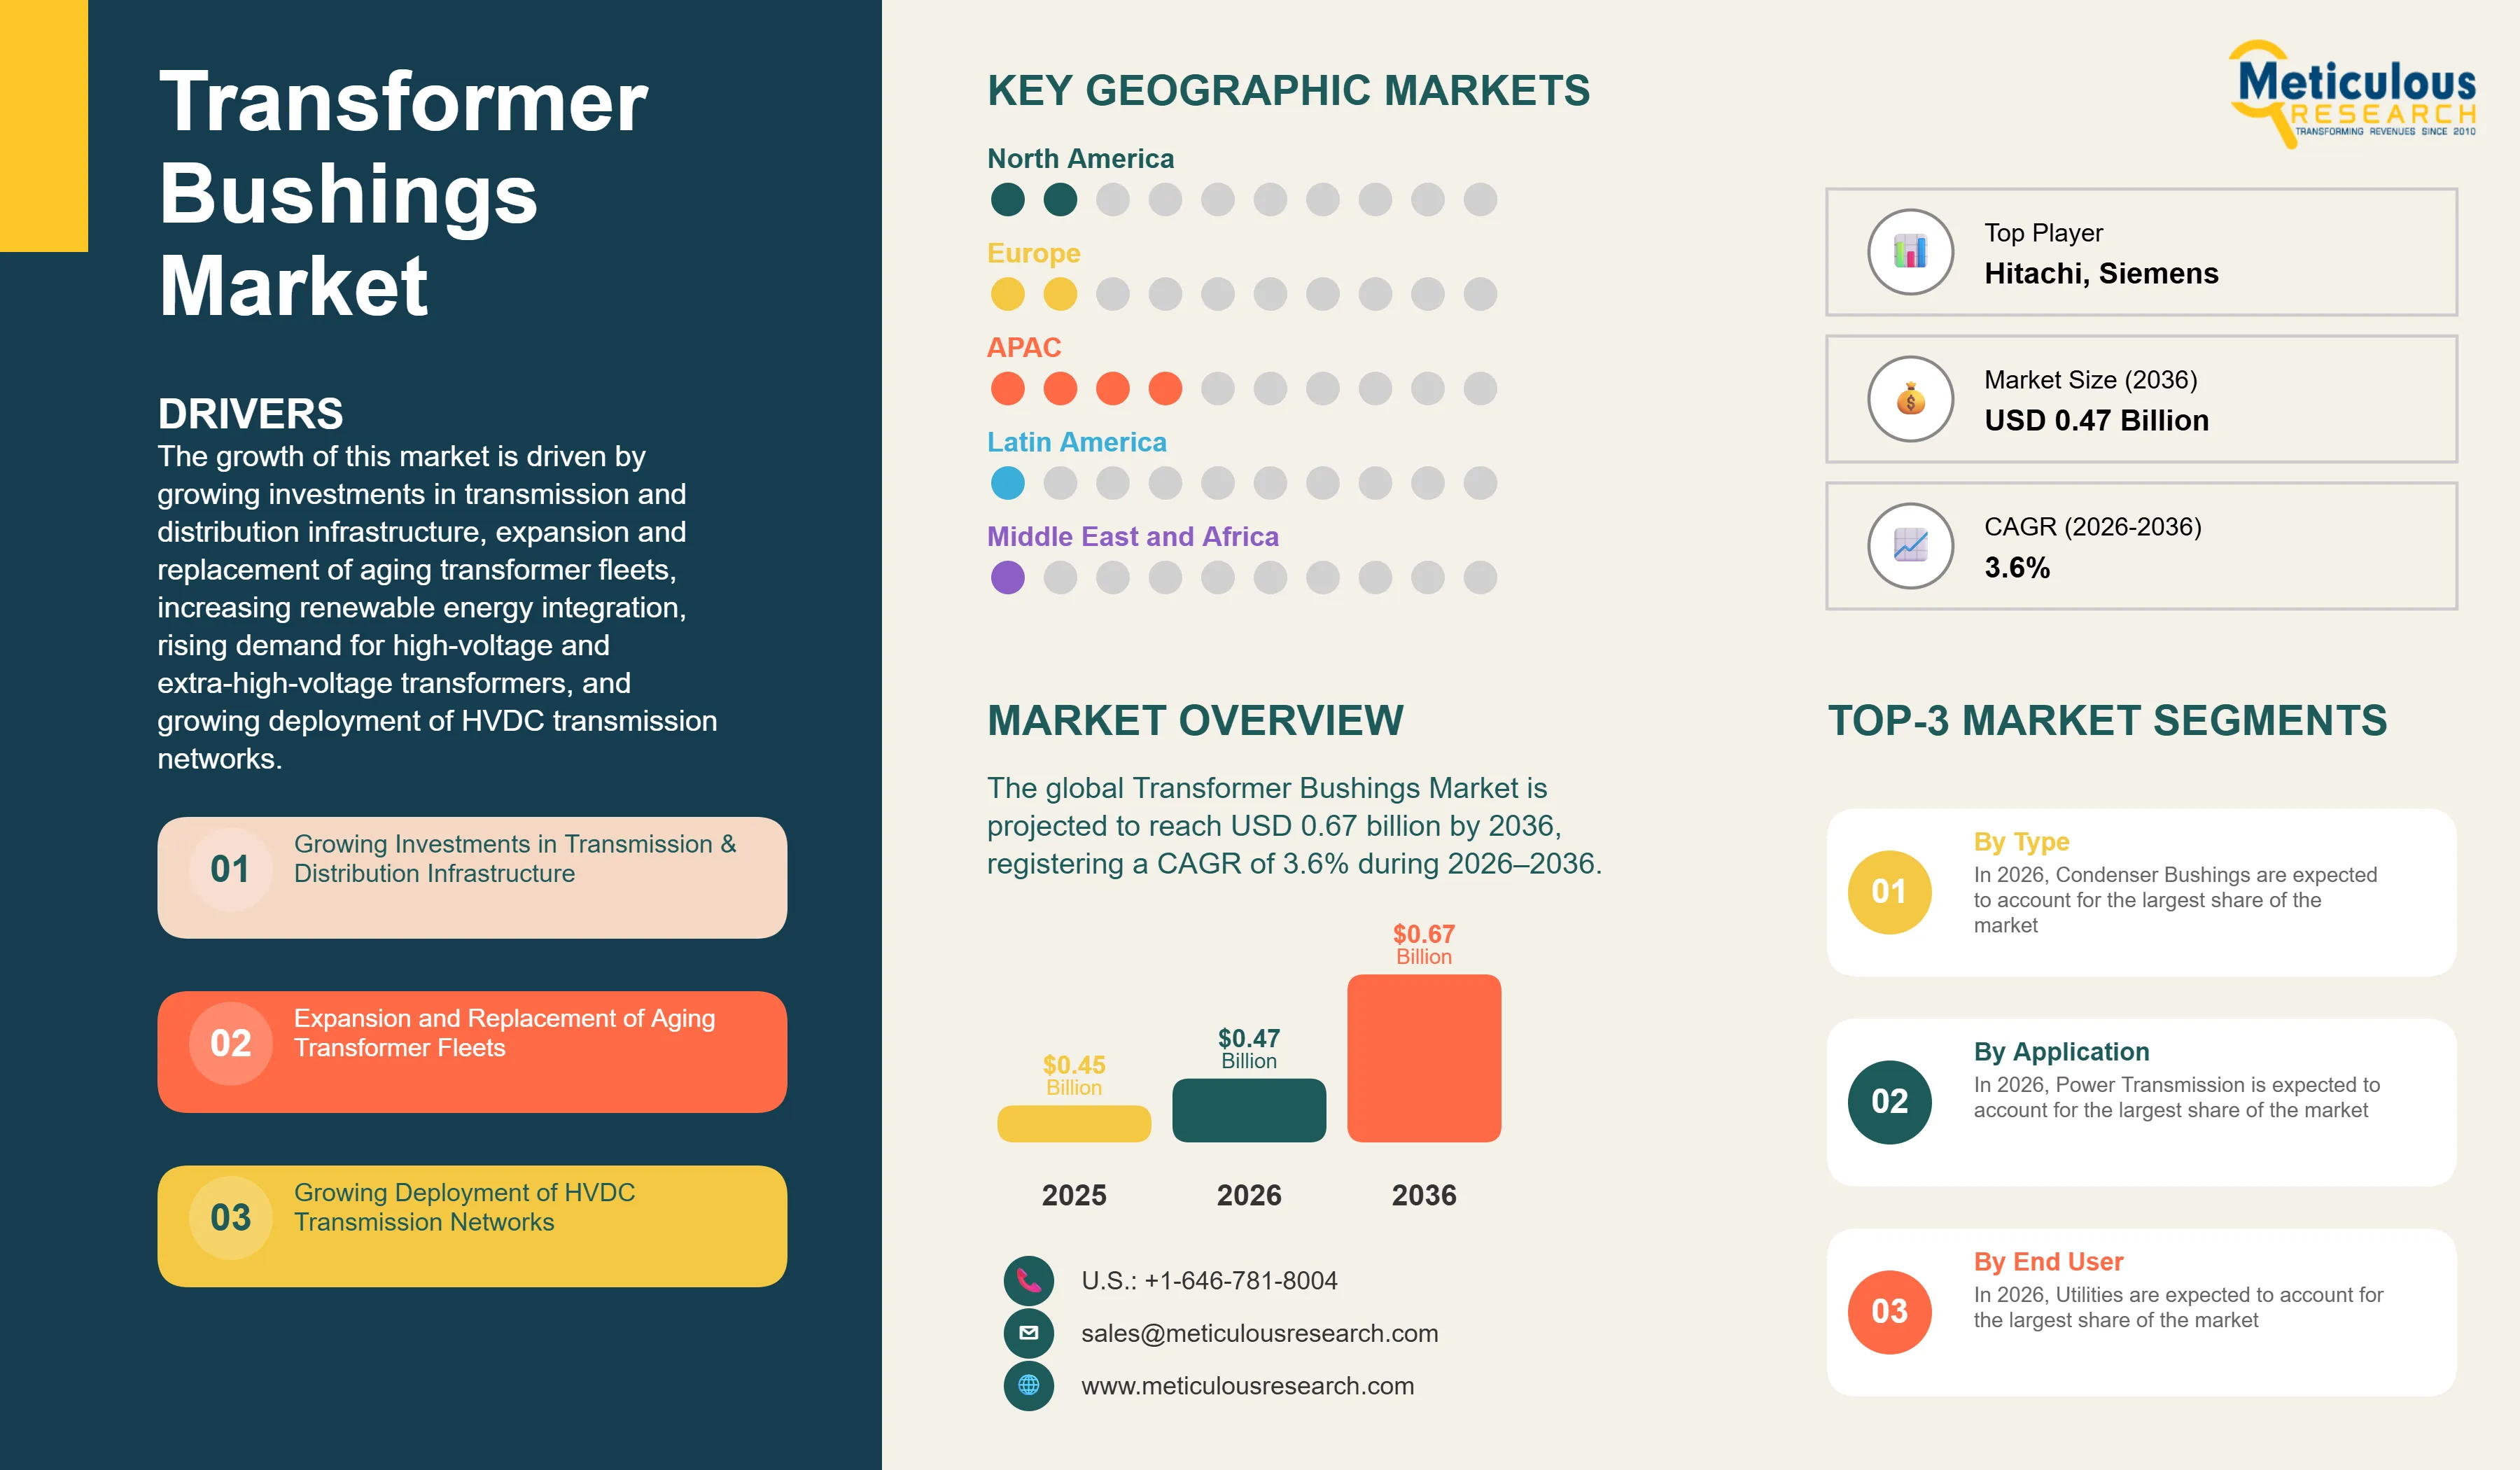
The global Transformer Bushings Market is estimated to be valued at USD 0.47 billion in 2026 and is projected to reach USD 0.67 billion by 2036, registering a CAGR of 3.6% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 310
- Format
- PDF + Excel
- Report ID
- MR-2129
- Base year
- 2025
- 2026 · ESTIMATED
- $470.0M
- 2036
- $670.0M
- CAGR 2026–2036
- 3.6%
2025 baseline · 2026–2036 forecast at 3.6% CAGR · hover a bar for the value
Key highlights
The global Transformer Bushings Market is projected to reach USD 0.67 billion by 2036, supported by investments in transmission and distribution infrastructure, transformer fleet replacement, renewable energy integration, and HVDC network expansion.
Asia-Pacific is expected to account for the largest market share in 2026, supported by substantial investments in power transmission, renewable energy, grid expansion, and transformer manufacturing.
By type, Condenser Bushings are expected to account for the largest market share, owing to their widespread application in medium-, high-, and extra-high-voltage transformer systems.
By insulation technology, Oil-Impregnated Paper (OIP) is expected to maintain a significant market position, while Resin-Impregnated Paper (RIP) and Resin-Impregnated Synthetic (RIS) technologies are gaining importance in modern high-voltage applications.
By voltage rating, 246–550 kV is expected to represent a major market segment, while Above 550 kV is projected to witness strong growth as ultra-high-voltage and HVDC transmission networks expand.
Growing investments in smart and sensor-enabled bushings, offshore wind transmission, HVDC converter transformers, and replacement of aging transformer fleets are creating new opportunities for bushing manufacturers.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 3.6% |
| Format | PDF, Excel & Cloud Portal · 310 pages |
| Market Size (Value) in 2026 | USD 0.47 Billion |
| Market Size (Value) in 2036 | USD 0.67 Billion |
| Segments Covered | By Type: Condenser Bushings, Non-Condenser Bushings, Oil-Filled Bushings, Gas-Insulated Bushings, Dry-Type Bushings. · By Insulation Technology: Oil-Impregnated Paper (OIP), Resin-Impregnated Paper (RIP), Resin-Impregnated Synthetic (RIS), Oil-Filled Insulation, Gas Insulation, Solid & Composite Insulation. · By Voltage Rating: Up to 72.5 kV, 72.6–145 kV, 146–245 kV, 246–550 kV, Above 550 kV. · By Transformer Type: Power Transformers, Distribution Transformers, Specialty Transformers. · By Bushing Configuration: Transformer Tank-Mounted Bushings, Turret-Mounted Bushings, Cover-Mounted Bushings, Conservator-Mounted Bushings. · By Conductor Type: Copper Conductors, Aluminum Conductors. · By Application: Power Generation, Power Transmission, Power Distribution, Industrial Power Systems. · By Installation: New Transformer Installations, Replacement & Retrofit, Maintenance & Emergency Replacement. · By End User: Utilities, Transmission System Operators, Distribution System Operators, Transformer Manufacturers, Industrial Facilities, Renewable Energy Developers, EPC Contractors. |
| Countries Covered | North America: U.S., Canada. · Europe: Germany, U.K., France, Italy, Spain, Sweden, Norway, Netherlands, Rest of Europe. · Asia-Pacific: China, Japan, India, South Korea, Australia, Taiwan, Singapore, Indonesia, Rest of Asia-Pacific. · Latin America: Brazil, Mexico, Argentina, Chile, Colombia, Rest of Latin America. · Middle East & Africa: Saudi Arabia, UAE, South Africa, Egypt, Turkey, Rest of Middle East & Africa. |
| Key Companies | Hitachi Energy Ltd., Siemens Energy AG, Maschinenfabrik Reinhausen GmbH, GE Vernova Inc., ABB Ltd., Trench Group, HSP Hochspannungsgeräte GmbH, Nanjing Rainbow Electric Co., Ltd., Jiangsu Shengda Electric Co., Ltd., Xi'an XD Transformer Co., Ltd., Megger Group Limited, Weidmann Electrical Technology AG, RHM International, Gipro Group, and Pfisterer Holding AG. |
Report overview
Segments covered: type, insulation technology, voltage rating, transformer type, bushing configuration, conductor type, application, installation, end user.
The Transformer Bushings Market comprises insulated components that enable electrical conductors to pass safely through grounded transformer tanks or other electrical barriers while maintaining electrical insulation and mechanical integrity. Transformer bushings are critical components of power transformers, distribution transformers, converter transformers, and other specialty transformer systems. The market includes condenser bushings, non-condenser bushings, oil-filled bushings, gas-insulated bushings, and dry-type bushings, utilizing insulation technologies such as OIP, RIP, RIS, oil-filled, gas, and solid/composite insulation.
Demand for transformer bushings is closely linked to the expansion and modernization of global electricity infrastructure. According to the International Energy Agency (IEA), more than 80 million kilometers of electricity grids must be added or refurbished globally by 2040, while annual grid investment needs to increase from around US$400 billion currently to more than US$600 billion by 2030. This massive expansion is increasing demand for transformers and associated high-voltage components, including transformer bushings. The growing pressure on transformer supply chains is also evident in the United States, where demand for generator step-up transformers has increased by approximately 274% since 2019 and demand for substation transformers has risen by 116%, according to 2026 industry reporting.
The replacement of aging transformer fleets is another important market driver. Utilities and transmission system operators are increasingly upgrading aging grid assets to improve reliability, increase transmission capacity, and accommodate variable renewable generation. Transformer bushings represent critical reliability components because bushing degradation or failure can contribute to transformer outages and costly grid disruptions. The current transformer supply shortage is further increasing the incentive to extend the operating life of existing assets through condition monitoring, preventive maintenance, refurbishment, and component replacement. In the U.S., large transformer lead times can now extend to as much as four years, creating additional interest in maintaining and upgrading existing transformer fleets rather than relying solely on new transformer installations.
The increasing deployment of HVDC transmission networks and converter transformers is also creating demand for specialized high-voltage bushings. HVDC projects require high-performance bushing technologies capable of operating under demanding electrical and environmental conditions. In July 2025, the IEC published the second edition of IEC/IEEE 65700-19-03:2025 for DC application bushings, covering bushings used with liquid-filled converter transformers and smoothing reactors and explicitly incorporating both line-commutated converter (LCC) and voltage-source converter (VSC) technologies. This update reflects the increasing technical requirements associated with modern HVDC infrastructure and supports demand for specialized DC bushing technologies.
Market dynamics
13 factors across 5 forcesGrowing Investments in Transmission & Distribution Infrastructure
Increasing investments in electricity transmission and distribution infrastructure are among the primary factors driving demand for transformer bushings. Electricity grids are being expanded and modernized to accommodate rising electricity consumption, renewable energy generation, electrification, and increasingly decentralized power systems. According to the International Energy Agency (IEA), annual global investment in electricity grids needs to increase from approximately US$400 billion today to more than US$600 billion by 2030 to support rising electricity demand and clean-energy deployment. The IEA also estimates that more than 80 million kilometers of electricity grids worldwide must be added or refurbished by 2040—roughly equivalent to the entire existing global grid network. New substations and transformer installations require multiple high-voltage bushings, while upgrades to existing substations create additional replacement demand.
The IEA highlights the urgency of expanding and modernizing electricity transmission infrastructure and notes that increasing infrastructure requirements are already putting pressure on supply chains for critical grid components. The IEA estimates that the number of grid connections required for new renewable and electrification projects is increasing rapidly, with more than 1,500 GW of renewable projects already waiting in grid connection queues worldwide. This combination of large-scale grid investment, transmission expansion, and substantial connection backlogs is expected to sustain demand for transformers and associated components, including high-voltage and extra-high-voltage transformer bushings, throughout the forecast period.
Expansion and Replacement of Aging Transformer Fleets
Aging transformer fleets across developed electricity markets are creating a substantial replacement and retrofit opportunity for transformer bushing manufacturers. Utilities increasingly replace deteriorated bushings as part of transformer refurbishment programs or install upgraded bushing technologies to improve reliability and monitoring capabilities.
The replacement market is particularly important because transformer bushings operate under continuous electrical, thermal, and mechanical stress. Aging insulation, moisture ingress, thermal deterioration, and electrical faults can compromise bushing performance and increase the risk of transformer failure. Consequently, utilities are placing greater emphasis on preventive maintenance, condition assessment, and replacement of critical transformer components.
Table of contents
17 chapters · 215 sections · 310 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Type | Condenser Bushings | — |
| By Insulation Technology | — | — |
| By Voltage Rating | 246–550 kV | — |
| By Transformer Type | Power Transformers | — |
| By Bushing Configuration | Transformer Tank-Mounted Bushings | — |
| By Conductor Type | — | — |
| By Application | Power Transmission | — |
| By Installation | New Transformer Installations | — |
| By End User | Utilities | — |
By Type
- Condenser Bushings are expected to account for the largest share of the global Transformer Bushings Market, supported by their extensive use in high-voltage and extra-high-voltage transformer applications.
- The Gas-Insulated Bushings and Dry-Type Bushings segments are expected to benefit from increasing demand for compact, reliable, and environmentally preferable insulation solutions, particularly across specialized transformer and grid applications.
By Insulation Technology
- Oil-Impregnated Paper (OIP) is expected to account for a significant share of the market due to its established installed base and extensive use in conventional transformer bushing applications.
- However, Resin-Impregnated Paper (RIP) and Resin-Impregnated Synthetic (RIS) technologies are expected to gain traction during the forecast period as utilities and transformer manufacturers increasingly seek advanced insulation technologies for modern high-voltage applications.
By Voltage Rating
- The 246–550 kV segment is expected to account for a significant market share, supported by continued investments in high-voltage transmission infrastructure and large power transformer installations.
- The Above 550 kV segment is expected to witness strong growth as utilities expand ultra-high-voltage transmission networks and countries invest in long-distance electricity transmission and HVDC infrastructure.
By Transformer Type
- Power Transformers are expected to account for the largest market share because of their extensive deployment across transmission networks and large substations.
- The Specialty Transformers segment is expected to benefit from increasing deployment of converter, furnace, traction, and phase-shifting transformers, particularly as HVDC systems, industrial electrification, and specialized grid applications expand.
By Bushing Configuration
- Transformer Tank-Mounted Bushings are expected to account for the largest market share due to their widespread use across conventional transformer configurations.
- Demand across different configurations is influenced by transformer design, voltage class, installation requirements, mechanical arrangement, and manufacturer specifications.
By Conductor Type
- Copper Conductors are expected to maintain a significant market position because of their high electrical conductivity and established use in high-performance electrical applications.
- However, aluminum conductors remain important in applications where lower weight and material cost are prioritized, creating continued demand for both conductor types across the transformer bushing market.
By Application
- Power Transmission is expected to account for the largest share of the global Transformer Bushings Market.
- The segment's dominance is supported by continued investments in transmission substations, high-voltage transformer installations, HVDC converter stations, and cross-border electricity interconnection projects.
- The increasing need to expand and modernize transmission infrastructure is expected to sustain demand for high-voltage and extra-high-voltage transformer bushings.
- The Power Generation segment is also expected to represent a significant market opportunity, supported by continued investments in conventional power generation, hydropower, nuclear power, and renewable energy projects.
- The growing integration of renewable generation into transmission networks is creating additional demand for transformers and associated high-voltage components.
By Installation
- New Transformer Installations are expected to account for the largest market share, supported by expansion of transmission and distribution infrastructure, new power generation capacity, renewable energy projects, and increasing deployment of high-voltage substations.
- However, Replacement & Retrofit represents an increasingly important growth opportunity as utilities and transmission system operators address aging transformer fleets.
- Replacement programs allow operators to upgrade aging bushings with newer insulation, monitoring, and reliability technologies while extending the operating life of existing transformers.
By End User
- Utilities are expected to account for the largest market share.
- Utilities operate extensive transmission and distribution assets and are therefore major purchasers of transformers, transformer bushings, replacement components, and maintenance services.
- Transmission System Operators and Distribution System Operators are also important market participants because of their responsibility for maintaining grid reliability and replacing aging high-voltage equipment.
- Increasing investments in grid modernization and network expansion are expected to support demand from these end users.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Transformer Bushings Market. The region's position is supported by large-scale investments in transmission and distribution infrastructure, rapid electricity demand growth, renewable energy deployment, extensive transformer manufacturing capacity, and ongoing grid modernization across China, India, Japan, South Korea, and Southeast Asia. China and India are particularly important markets because of their large electricity networks, expanding transmission capacity, and continued investment in renewable energy integration. The region also has a substantial installed base of transformers, creating opportunities for replacement and retrofit of aging bushings.
Europe
Europe is expected to remain a significant market, supported by grid modernization, offshore wind development, cross-border electricity interconnectors, and replacement of aging transmission infrastructure. Increasing deployment of renewable energy and HVDC transmission networks is particularly relevant to demand for high-voltage and specialized transformer bushings.
North America
North America is supported by replacement of aging grid infrastructure, transformer fleet modernization, renewable generation expansion, and increasing investment in transmission capacity. The region also represents an important aftermarket opportunity because utilities are increasingly focused on asset reliability and lifecycle management.
Latin America
Latin America and the Middle East & Africa are expected to benefit from new transmission and distribution projects, renewable energy development, electrification initiatives, and investments in grid infrastructure.
Competitive landscape
The global Transformer Bushings Market includes established electrical equipment manufacturers, specialized bushing manufacturers, transformer component suppliers, and grid equipment companies. Competition is primarily influenced by product reliability, voltage capability, insulation technology, manufacturing quality, testing and certification capabilities, customization, price, and after-sales support.
Leading companies are increasingly focusing on advanced RIP and RIS technologies, composite insulation, high-voltage and ultra-high-voltage bushings, smart monitoring capabilities, and HVDC-compatible solutions. Investments in grid modernization and transformer capacity expansion are also encouraging manufacturers to strengthen production capabilities and develop specialized solutions for renewable energy and HVDC applications. The attached ToC identifies grid modernization, transformer capacity expansion, renewable energy integration, HVDC investments, and digital transformer monitoring as key industry trends.
The report profiles the leading companies operating in the global Transformer Bushings Market, including Hitachi Energy Ltd., Siemens Energy AG, Maschinenfabrik Reinhausen GmbH, GE Vernova Inc., ABB Ltd., Trench Group, HSP Hochspannungsgeräte GmbH, Nanjing Rainbow Electric Co., Ltd., Jiangsu Shengda Electric Co., Ltd., Xi'an XD Transformer Co., Ltd., Megger Group Limited, Weidmann Electrical Technology AG, RHM International, Gipro Group, and Pfisterer Holding AG.
- Hitachi Energy Ltd.
- Siemens Energy AG
- Maschinenfabrik Reinhausen GmbH
- GE Vernova Inc.
- ABB Ltd.
- Trench Group
- HSP Hochspannungsgeräte GmbH
- Nanjing Rainbow Electric Co., Ltd.
- Jiangsu Shengda Electric Co., Ltd.
- Xi'an XD Transformer Co., Ltd.
- Megger Group Limited
- Weidmann Electrical Technology AG
- RHM International
- Gipro Group
- Pfisterer Holding AG
Frequently asked questions
The market is estimated at USD 0.47 billion in 2026.
Cite this report
Meticulous Research. (2026). Transformer Bushings Market- Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2129). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/transformer-bushings-market-6812