Space Robotics and Autonomous Systems Market (2026-2036)
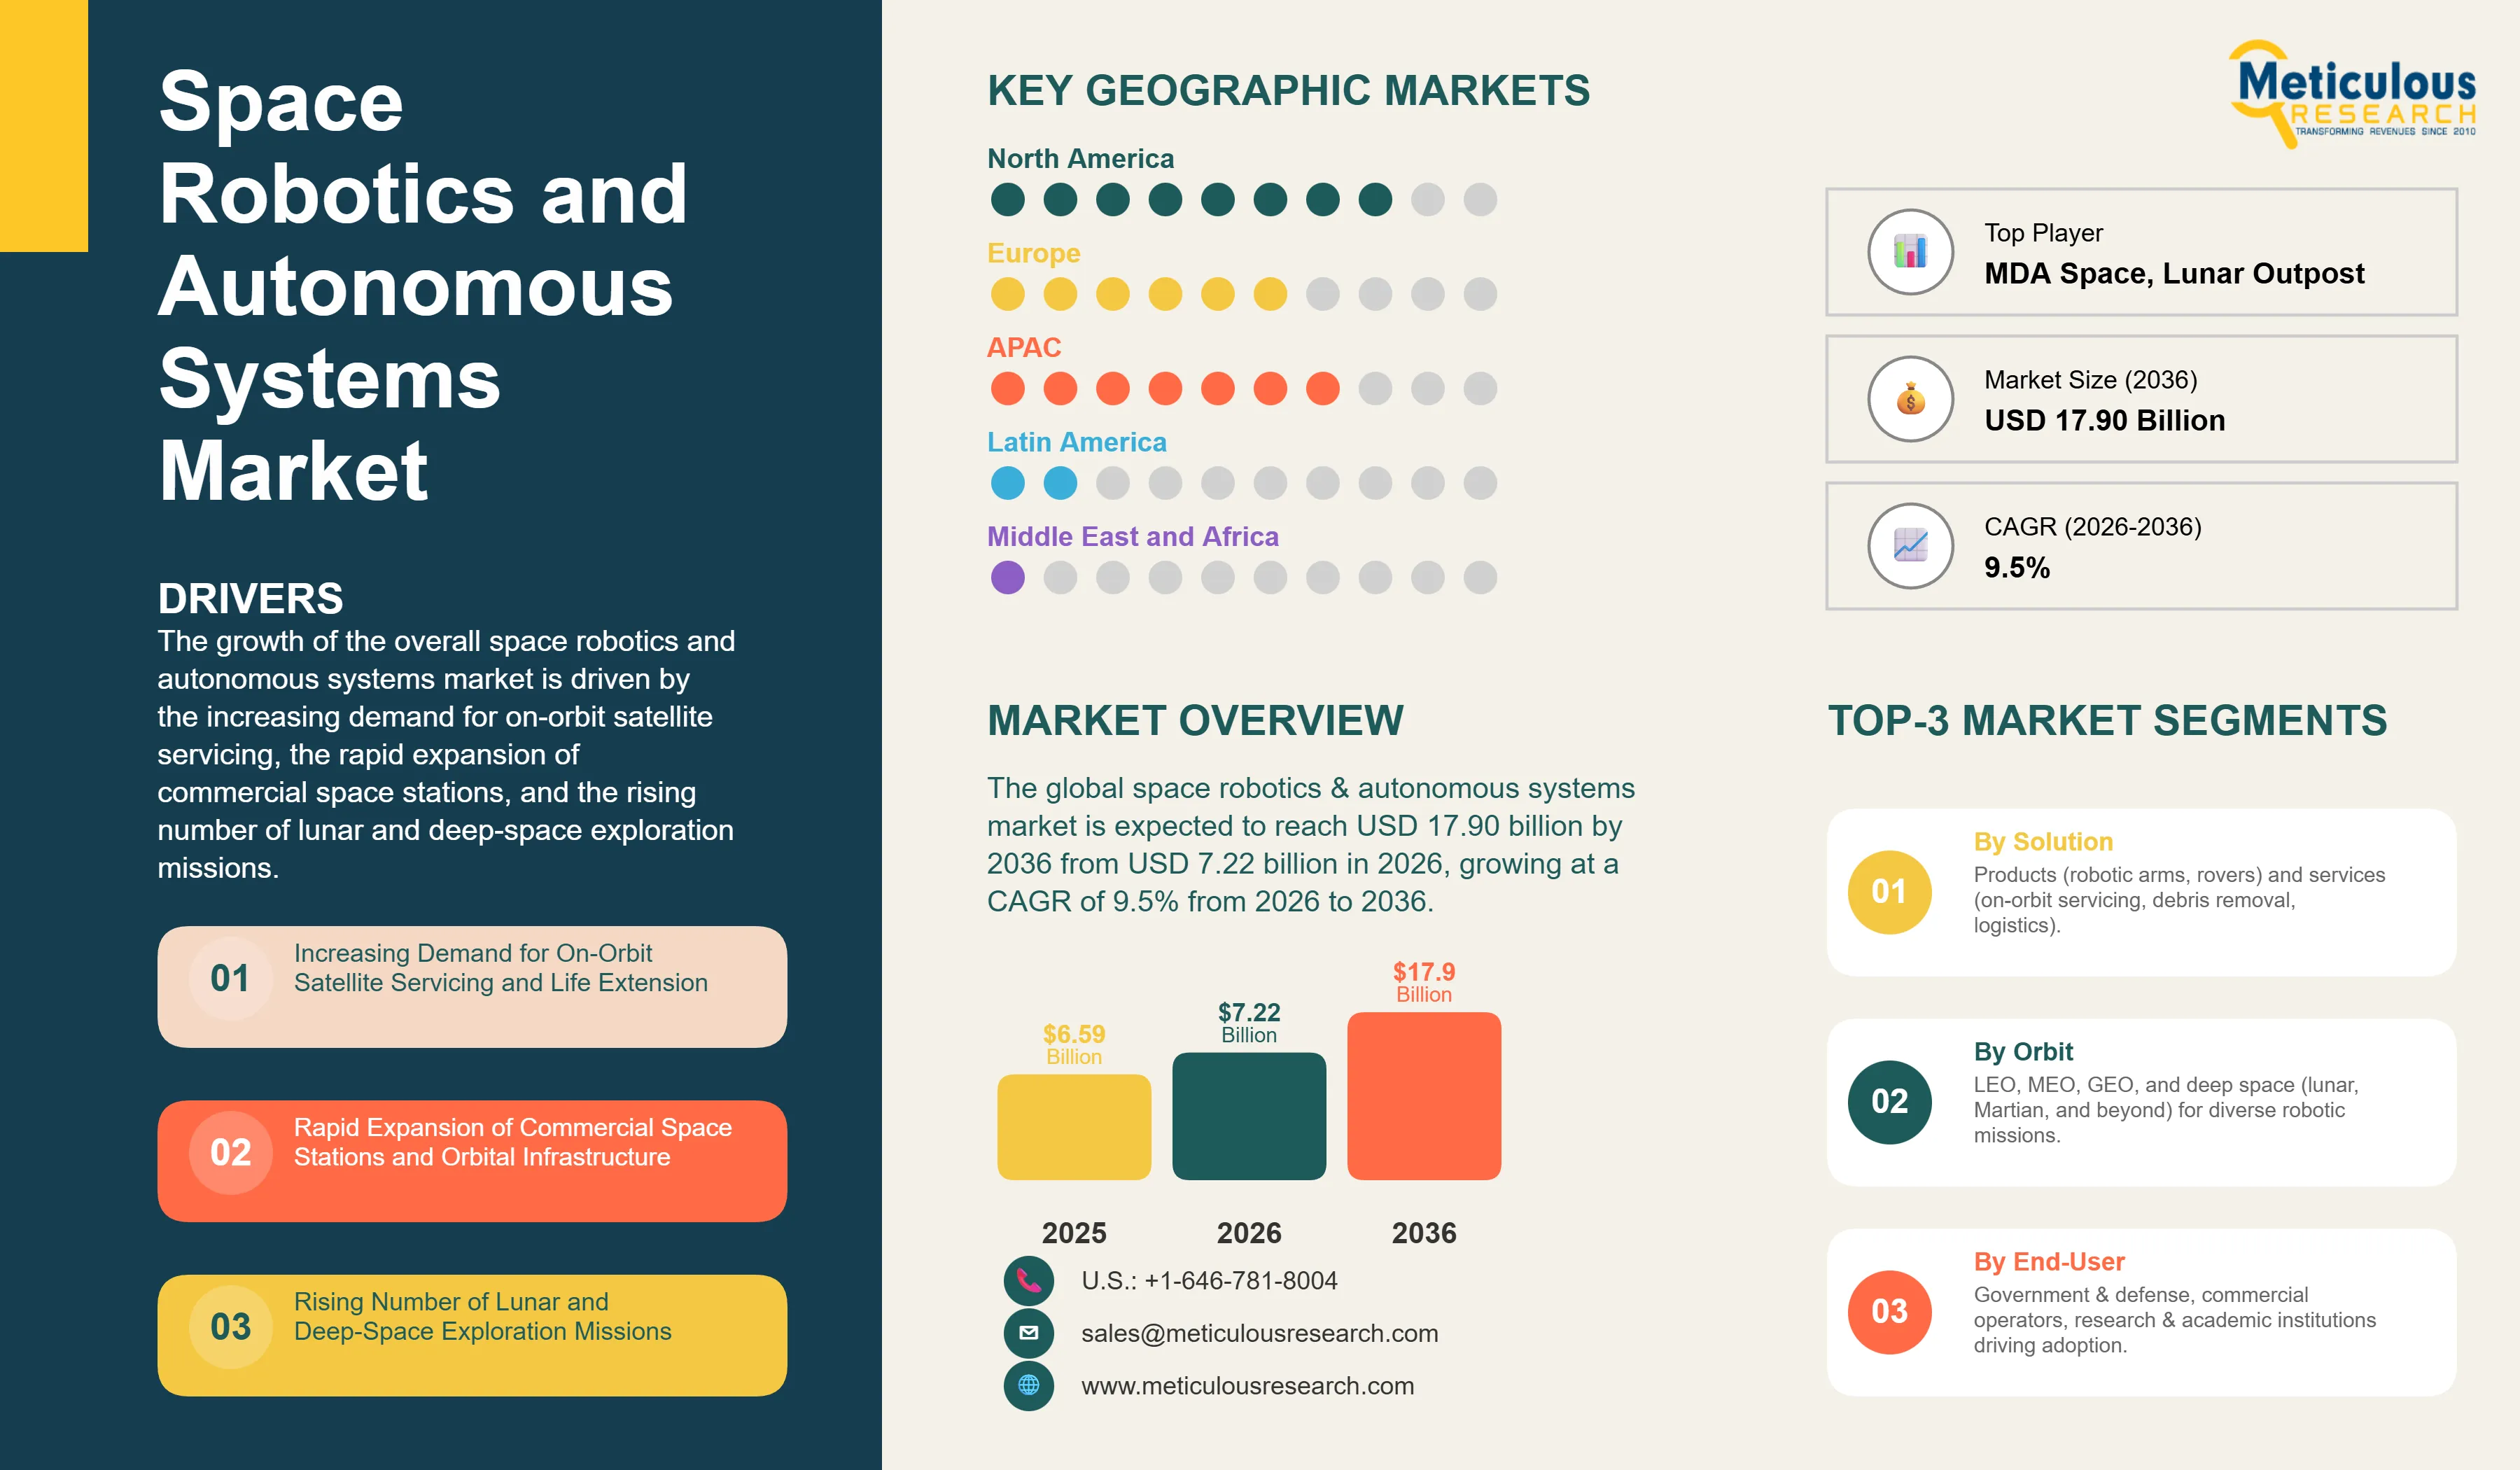
The global space robotics and autonomous systems market was valued at USD 6.59 billion in 2025. The market is expected to reach approximately USD 17.90 billion by 2036 from USD 7.22 billion in 2026, growing at a CAGR of 9.5% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 275
- Format
- PDF + Excel
- Report ID
- MR-1699
- Base year
- 2025
- 2025 · BASELINE
- $6.59B
- 2036
- $17.90B
- CAGR 2026–2036
- 9.5%
2025 baseline · 2026–2036 forecast at 9.5% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global space robotics and autonomous systems market is projected to reach USD 17.90 billion by 2036.
The market is expected to grow at a CAGR of 9.5% from 2026 to 2036.
North America dominates the global space robotics and autonomous systems market with the largest market share in 2026, driven by NASA’s Artemis program, significant private investments from companies like SpaceX and Maxar, and a robust ecosystem of technology innovators.
Asia Pacific is expected to witness the fastest growth during the forecast period, supported by the rapid advancement of China’s Tiangong space station, India’s Gaganyaan and lunar missions, and Japan’s leadership in orbital debris removal technologies.
By solution, the products segment (including robotic arms and rovers) holds the largest market share in 2026, particularly due to the high demand for manipulator systems on the International Space Station (ISS) and upcoming commercial platforms.
By application, the satellite servicing segment is expected to witness the fastest CAGR during the forecast period as operators shift from satellite replacement to life-extension and refueling strategies.
By end-user, the government & defense segment holds the largest share of the overall market in 2026, though the commercial segment is rapidly gaining ground.
By orbit, Low Earth Orbit (LEO) holds the largest share of the overall market in 2026 due to the proliferation of mega-constellations and orbital infrastructure.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 17.90 Billion |
| Market Size in 2026 | USD 7.22 Billion |
| Market Size in 2025 | USD 6.59 Billion |
| Market Growth Rate (2026-2036) | CAGR of 9.5% |
| Format | PDF, Excel & Cloud Portal · 275 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Solution, Application, End-User, Orbit, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: solution, application, end-user, orbit.
The growth of the overall space robotics and autonomous systems market is driven by the increasing demand for on-orbit satellite servicing, the rapid expansion of commercial space stations, and the rising number of lunar and deep-space exploration missions. As space agencies and private enterprises seek to extend the operational life of orbital assets and establish sustainable lunar bases, autonomous robotic systems have become essential for complex assembly, maintenance, and resource extraction tasks. The rapid expansion of the “NewSpace” sector, coupled with the increasing need for active debris removal to ensure orbital sustainability, continues to fuel significant growth of this market across all major geographic regions.
Space robotics and autonomous systems represent a sophisticated domain of aerospace engineering that utilizes robotic manipulators, rovers, and autonomous spacecraft to perform tasks in the harsh environment of space. Unlike traditional pre-programmed satellites, modern autonomous systems leverage AI-driven navigation, computer vision, and machine learning to execute complex operations such as docking with non-cooperative targets, assembling large-scale structures in orbit, and navigating treacherous lunar terrain without real-time human intervention. The market is defined by high-reliability technologies that enable “in-space servicing, assembly, and manufacturing” (ISAM), optimizing mission architectures and reducing the total cost of ownership (TCO) for orbital and planetary assets.
The market includes a diverse range of systems, from high-precision robotic arms for space station maintenance to autonomous rovers designed for regolith sampling on the Moon and Mars. These systems are increasingly integrated with advanced haptic feedback for teleoperation and edge computing for real-time decision-making to ensure mission success in communication-constrained environments. The ability to operate in extreme thermal gradients and high-radiation zones while maintaining sub-millimeter precision has made space robotics the technology of choice for the next generation of orbital logistics and planetary colonization.
The global space sector is pushing hard to modernize orbital capabilities, aiming to enhance mission resilience and reduce the accumulation of space debris. This drive has increased the adoption of autonomous systems for active debris removal (ADR) and the repair of high-value satellites, with modular robotic platforms helping to stabilize operational costs. At the same time, the rapid growth in the lunar economy and the push for Mars exploration is increasing the need for high-performance, autonomous robotic explorers and resource extraction equipment.
Satellite operators are rapidly shifting toward life-extension services, moving well beyond the traditional “launch and replace” model toward smarter orbital logistics. Northrop Grumman’s Mission Extension Vehicles (MEV) have already demonstrated successful docking and life extension for geostationary satellites, while Maxar’s upcoming OSAM-1 mission aims to deliver refueling and assembly capabilities in LEO. The real game-changer comes with “smart” servicing vehicles featuring multi-arm robotic systems and AI-driven proximity operations that can repair and upgrade satellites in-situ. These advancements make high-efficiency orbital maintenance practical and cost-effective for everyone from telecommunication giants to defense agencies chasing sustained orbital dominance.
Innovation in planetary robotics is rapidly driving the market as the global community scales up lunar exploration. Equipment suppliers are now designing autonomous rovers and excavators specifically for the lunar south pole, with tight control over power management and dust mitigation to meet the challenges of the lunar night. This often involves advanced mobility systems and autonomous navigation stacks capable of traversing unmapped terrain without GPS. At the same time, growing focus on “In-Situ Resource Utilization” (ISRU) is pushing manufacturers to develop robotic solutions tailored to water-ice extraction and regolith processing. These systems help establish a sustainable human presence on the Moon, extending the reach of exploration instead of relying solely on Earth-based supplies. By combining high-autonomy navigation with robust mechanical designs, these new systems support both scientific discovery and the burgeoning lunar economy.
Report infographic
How Does Satellite Servicing Lead the Market?
Based on application, the satellite servicing segment holds the largest share of the overall market in 2026, accounting for around 40-45% of the overall market. From refueling and battery replacement to structural repair, the use of robotic systems is central to modernizing orbital infrastructure. Current large-scale projects are increasingly specifying autonomous docking and manipulator systems for their ability to handle non-cooperative targets with high efficiency and lower risk compared to human-led missions.
The planetary exploration and in-space manufacturing segments continue to find critical applications in missions where the construction of large antennas and the extraction of lunar resources are essential. However, the shift toward autonomous orbital logistics is pushing the requirement for standardized robotic interfaces that allow businesses to scale their servicing capacity while minimizing their operational footprint.
Market dynamics
2 factors across 2 forcesDemand for Orbital Sustainability and Life Extension
A key driver of the space robotics market is the rapid movement of the global space industry toward orbital stewardship and the mitigation of space debris. Global requirements for ensuring the long-term sustainability of LEO have created significant incentives for the adoption of active debris removal (ADR) and satellite servicing technologies. The ability to de-orbit defunct satellites and repair aging assets drives operators toward scalable robotic solutions. It is estimated that as the number of active satellites triples through 2036, the need for autonomous traffic management and robotic intervention increases significantly; therefore, space robotic systems, with their ability to extend asset life by up to 5-10 years, are considered a crucial enabler of modern space strategies.
Table of contents
12 chapters · 126 sections · 275 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Solution | Products segment (including robotic arms and rovers) | Services segment (including on-orbit servicing and debris removal) |
| By End-user | Government & defense | — |
| By Application | — | Commercial |
| By Orbit | Low Earth Orbit (LEO) | — |
By Solution
- The products segment, comprising robotic arms, rovers, and landers, accounts for around 65-70% of the overall space robotics market in 2026.
- The products segment, comprising robotic arms, rovers, and landers, accounts for around 65-70% of the overall space robotics market in 2026.
- This is mainly attributed to the primary use of these hardware systems in mission-critical operations across space stations and planetary missions.
- Robotic arms, such as the Canadarm3 and European Robotic Arm (ERA), offer the most efficient way to manage external maintenance and payload transfers.
- The government and commercial space station sectors alone consume the vast majority of these systems, with major projects in North America and Europe demonstrating the technology’s capability to handle high-value infrastructure management.
- However, the services segment (including on-orbit servicing and debris removal) is expected to grow at the fastest CAGR during the forecast period, driven by the growing number of commercial satellite constellations and the rising regulatory pressure for orbital cleanup.
- The ability to provide “Robotics-as-a-Service” (RaaS) makes these solutions highly attractive for modern satellite operators.
By End-user
- The government & defense segment holds the largest share of the overall market in 2026, accounting for around 65-70% of the overall market.
- This dominance is primarily driven by substantial investments from national space agencies (e.g., NASA, ESA, CNSA) in large-scale exploration missions, such as lunar infrastructure development and deep-space probes.
- Additionally, military and defense organizations increasingly leverage space robotics for surveillance, reconnaissance, and in-orbit asset protection.
- These high-value, long-term programs necessitate robust, space-qualified robotic systems, ensuring a sustained demand from this segment.
By Application
- However, the commercial segment is expected to witness the fastest CAGR during the forecast period, fueled by the rapid growth of private space ventures, satellite operators, and emerging lunar logistics companies.
- The increasing adoption of commercial satellite servicing and the development of private space stations are key drivers for this accelerated growth.
- However, the deep space segment (including lunar, Martian, and beyond) is expected to grow at the fastest CAGR during the forecast period, driven by ambitious international and commercial missions targeting the Moon and Mars.
- The need for autonomous rovers, landers, and robotic construction systems for planetary exploration and potential resource utilization is a major catalyst for this growth.
By Orbit
- The Low Earth Orbit (LEO) segment holds the largest share of the overall market in 2026, accounting for around 55-60% of the overall market.
- This is primarily due to the proliferation of mega-constellations for broadband internet (e.g., Starlink, OneWeb) and the increasing deployment of Earth observation satellites.
- The high density of assets in LEO drives significant demand for robotic solutions related to active debris removal, in-orbit servicing, and satellite inspection to ensure the long-term sustainability and safety of this critical orbital region.
Geographic analysis
North America
Largest shareNorth America holds the largest share of the global space robotics and autonomous systems market in 2026. The largest share of this region is primarily attributed to the massive investments in the Artemis program and the presence of the world’s leading commercial space companies, particularly in the United States. The U.S. alone accounts for a significant portion of global space robotics consumption, with its position as a leading hub for lunar exploration and military space modernization driving sustained growth. The presence of leading manufacturers like Northrop Grumman, MDA Space, Maxar Technologies, and Redwire, along with a well-developed NewSpace ecosystem, provides a robust market for both standard and high-capacity robotic solutions.
Asia-Pacific
Fastest growthAsia Pacific is expected to witness the fastest growth, driven by the need for sovereign space capabilities and the expansion of the lunar and orbital infrastructure sectors. Countries like China and India are at the forefront, with significant focus on integrating autonomous robotics into their space station and lunar landing environments.
Europe
In Europe, the leadership in robotic arm innovation and the push for orbital sustainability are driving the adoption of high-efficiency servicing systems. Germany, France, and the UK are leading the way, with a strong focus on active debris removal and the integration of robotics into the ESA’s exploration roadmap through players like Airbus and Leonardo.
Competitive landscape
- Northrop Grumman Corporation
- MDA Space
- Maxar Technologies
- Redwire Space
Frequently asked questions
The global space robotics and autonomous systems market is projected to reach a valuation of USD 17.90 billion by 2036, expanding from USD 7.22 billion in 2026. This significant growth trajectory is underpinned by a robust Compound Annual Growth Rate (CAGR) of 9.5% over the forecast period, reflecting the technology’s transition from experimental missions to mainstream orbital and lunar logistics.
Cite this report
Meticulous Research. (2026). Space Robotics and Autonomous Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1699). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/space-robotics-and-autonomous-systems-market-6382