Smart Meter Market (2025-2035)
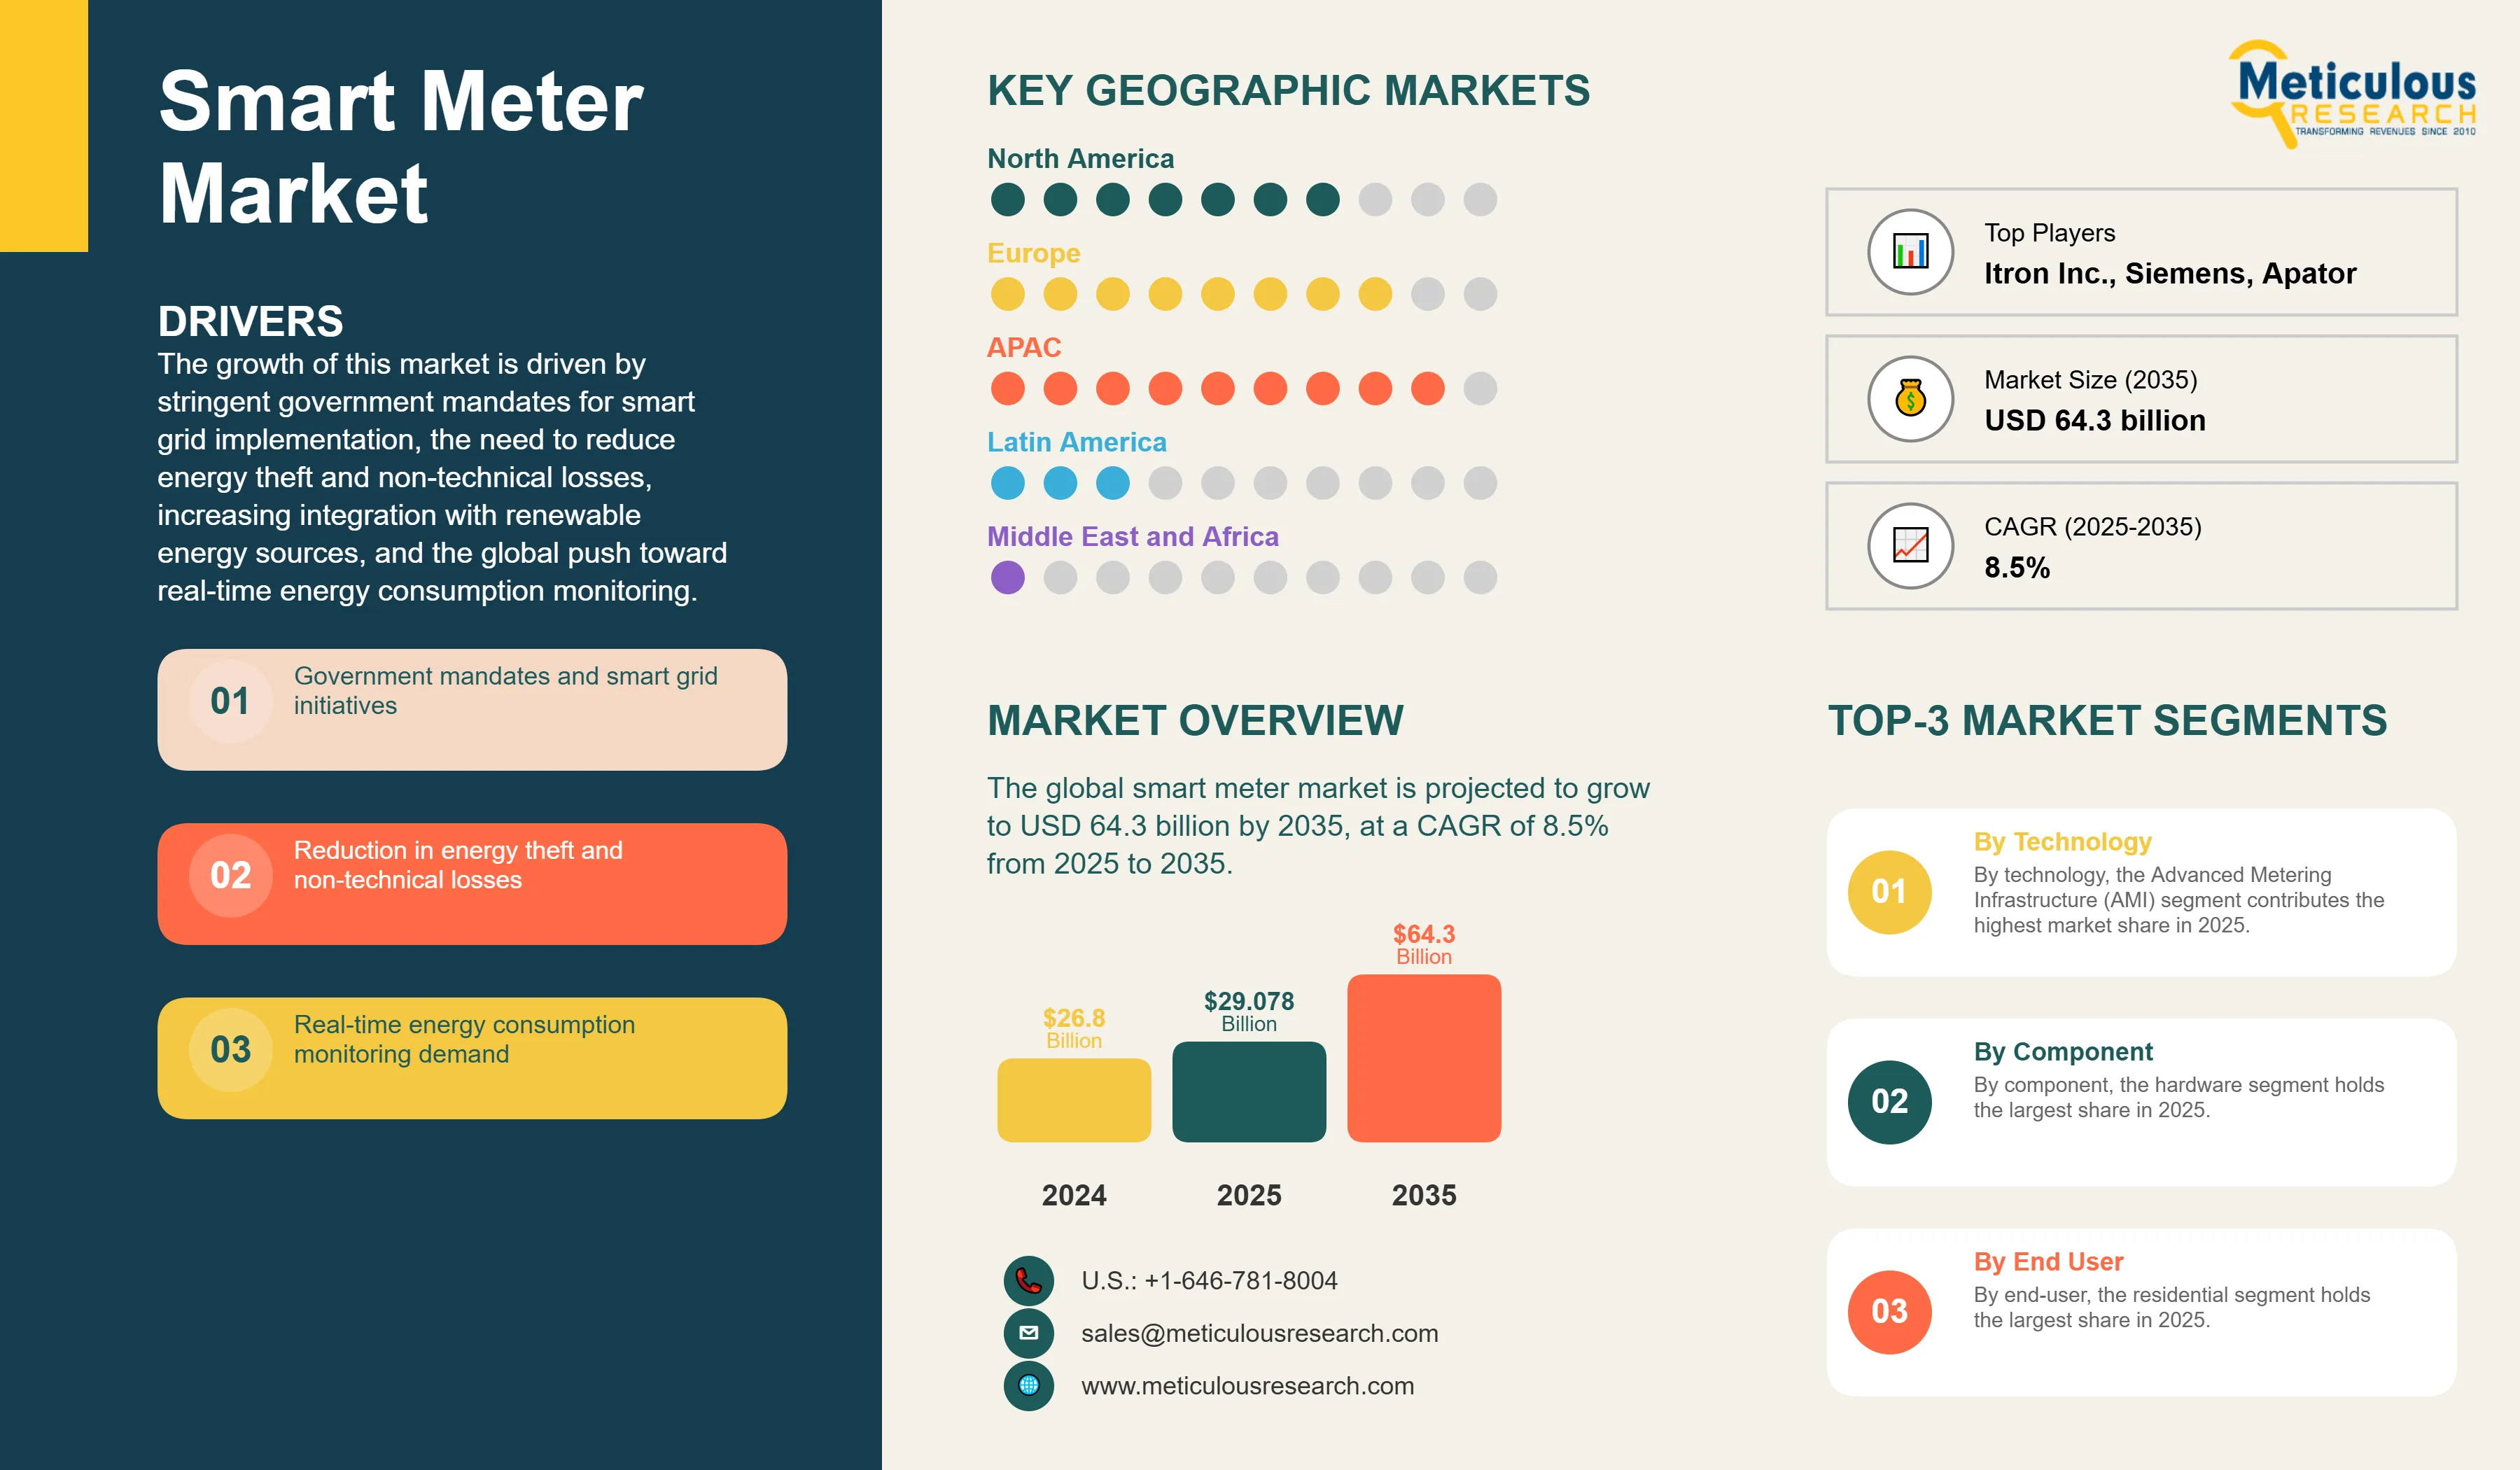
The global smart meter market was valued at USD 26.8 billion in 2024. This market is projected to grow to USD 64.3 billion by 2035, at a CAGR of 8.5% from 2025 to 2035.
- Published
- Oct 2025
- Pages
- 228
- Format
- PDF + Excel
- Report ID
- MREP - 1041611
- Base year
- 2024
- 2024 · BASELINE
- $26.80B
- 2035
- $64.30B
- CAGR 2025–2035
- 8.5%
2024 baseline · 2025–2035 forecast at 8.5% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global smart meter market is valued at approximately USD 28.5 billion in 2025 and is projected to reach USD 64.3 billion by 2035.
The market is expected to grow at a CAGR of 8.5% from 2025 to 2035.
Asia Pacific dominates the global smart meter market with the largest market share in 2025.
Europe is expected to witness the fastest CAGR during the forecast period.
By meter type, the smart electricity meters segment holds the largest market share in 2025.
By meter type, the smart water meters segment is expected to witness the fastest CAGR from 2025 to 2035.
By technology, the Advanced Metering Infrastructure (AMI) segment contributes the highest market share in 2025.
By technology, the Smart Meter Data Management (MDM) segment is expected to witness significant growth through 2035.
By communication technology, the radio frequency (RF) segment holds the largest market share in 2025.
By communication technology, the cellular (including 5G and NB-IoT) segment is expected to witness the fastest CAGR from 2025 to 2035.
By component, the hardware segment holds the largest share in 2025.
By component, the software segment is expected to witness the fastest CAGR during the forecast period.
By phase, the single-phase meters segment holds the largest share in 2025.
By end-user, the residential segment holds the largest share in 2025.
By end-user, the utilities segment is expected to witness substantial growth from 2025 to 2035.
Report summary
| Particulars | Details |
|---|---|
| Report Coverage | Details |
| Market Size by 2035 | USD 64.3 Billion |
| Market Size in 2025 | USD 28.5 Billion |
| Market Size in 2024 | USD 26.8 Billion |
| Market Growth Rate from 2025 to 2035 | CAGR of 8.5% |
| Format | PDF, Excel & Cloud Portal · 228 pages |
| Dominating Region | Asia Pacific |
| Fastest Growing Region | Europe |
| Base Year | 2024 |
| Forecast Period | 2025 to 2035 |
| Segments Covered | Meter Type, Technology, Communication Technology, Component, Phase, End-User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: meter type, technology, communication technology, component, phase, end-user.
The growth of this market is driven by stringent government mandates for smart grid implementation, the need to reduce energy theft and non-technical losses, increasing integration with renewable energy sources, and the global push toward real-time energy consumption monitoring. The rapid deployment of Advanced Metering Infrastructure (AMI) across utilities, coupled with declining hardware costs and enhanced data analytics capabilities, is accelerating the adoption of smart meters worldwide.
The smart meter market involves the design, production, and management of digital meters that allow two-way data exchange between energy providers and consumers. Unlike traditional analog meters that need manual readings, smart meters automatically and continuously send data on electricity, gas, or water usage. They use technologies like radio frequency (RF), power line communication (PLC), cellular networks, and Low Power Wide Area Networks (LPWAN).
This market includes both hardware, such as meters, communication modules, data concentrators, and network infrastructure, and software, including Meter Data Management Systems (MDMS), Head-End Systems (HES), Customer Information Systems (CIS), and analytics platforms. Services involve installation, system integration, consulting, maintenance, and managed support.
Smart meters give utilities better grid monitoring, fault detection, prevention of energy theft, load management, and flexible pricing options. Consumers benefit from tracking their energy use in real time, which helps them participate in demand response programs and energy-saving efforts.
Market growth largely comes from government requirements for smart meter installations and the need to modernize grids to support distributed energy resources. Automated meter reading lowers utility costs and increases billing accuracy, while real-time data sharing boosts customer engagement. The integration of IoT platforms, AI-driven predictive analytics, and blockchain for peer-to-peer energy trading is creating new opportunities and speeding up market growth.
Artificial intelligence is transforming the smart meter market by making energy management smarter and more efficient. AI analyzes large amounts of meter data to find problems, detect energy theft, predict equipment failures, and improve grid operations in real time. Machine learning helps with demand forecasting by recognizing consumption patterns, which allows utilities to manage load distribution better and lower peak demand charges.
AI systems can identify unusual usage that may indicate meter tampering or unauthorized connections, helping utilities recover lost revenue. For consumers, AI provides personalized energy-saving tips, suggests the best times to use appliances, and alerts users to sudden increases in consumption. Natural language processing lets consumers interact with their smart meters through voice assistants and chatbots, making energy management easy and accessible.
Dynamic pricing models driven by AI predict grid conditions in real time. This encourages load shifting to off-peak hours with flexible rates. Computer vision improves maintenance by automatically spotting infrastructure faults during installation and servicing. Deep learning enhances forecasting accuracy by considering weather, historical data, grid status, and user behavior, leading to more efficient energy generation and distribution. Overall, AI is making smart meters more intelligent, responsive, and user-friendly. This is driving faster adoption and smarter energy systems.
A key trend in the smart meter market is the growing connection between smart meters and distributed energy resources like rooftop solar panels, battery storage, and electric vehicle charging stations. Modern smart meters can track energy flow in both directions. This allows for accurate measurement of energy production, consumption, and export. This ability supports programs such as net metering, time-of-use tariffs, and peer-to-peer energy trading. Utilities are using advanced meters with better features to manage the increasing number of prosumers, who are consumers that also generate energy. They also aim to keep the grid stable as the use of renewable energy rises.
A key trend creating new market opportunities is the development of multi-utility smart metering solutions that measure electricity, gas, and water consumption on integrated platforms. By sharing communication networks, reducing installation costs, and offering unified data management, these converged systems deliver significant savings. Utilities across energy, gas, and water sectors are adopting this multi-utility approach to streamline operations, improve customer service with consolidated billing, and leverage cross-commodity analytics for better resource monitoring. This trend is especially prominent in smart city initiatives, where integrated utility management forms the backbone of modern urban infrastructure.
Europe is expected to grow at the fastest CAGR between 2025 and 2035. This growth is fueled by strong EU regulations. The Energy Efficiency Directive and Clean Energy Package require member states to install smart meters in at least 80% of households by 2025 if it is cost-effective. Many countries are aiming even higher. Italy has completed its rollout ahead of schedule and is upgrading to next-generation meters. Countries like Finland, Sweden, Spain, the UK, France, Germany, and the Netherlands are implementing major rollout plans.
The push for net-zero emissions by 2050 in the European Green Deal makes smart meters vital for integrating renewable energy, managing electric vehicle charging, and supporting demand-response programs. Strict data privacy laws, such as GDPR, have led to robust security measures that increase consumer trust. Europe also benefits from top technology firms, research institutions, and strong ties with smart city projects. Financially stable utilities, skilled employees, and regulatory support for cost recovery through tariffs further promote the region’s smart meter growth.
Research and Development This stage focuses on advancing smart meter technology through development of next-generation metering devices with enhanced accuracy, security, and communication capabilities, including improving measurement precision, extending battery life for gas and water meters, developing multi-utility meter platforms, and creating advanced firmware for new functionality.
Key Players: Landis+Gyr, Itron, Siemens, Schneider Electric
This stage involves producing specialized components including measurement chips, communication modules, power supplies, displays, and enclosures that meet stringent quality and regulatory standards, requiring precision manufacturing and extensive testing.
Key Players: Texas Instruments, STMicroelectronics, NXP Semiconductors, Renesas Electronics
This stage encompasses assembling components into complete smart meter devices, including extensive testing for accuracy, communication functionality, and compliance with industry standards (IEC, ANSI), as well as firmware installation and calibration.
Key Players: Landis+Gyr Group AG
Itron Inc.
Honeywell International Inc. (includes Elster)
Siemens AG
Schneider Electric SE
Sagemcom SAS
Osaki Electric Co., Ltd. (EDMI Limited)
Badger Meter Inc.
Wasion Group Holdings Limited
Aclara Technologies LLC (Hubbell Incorporated)
Kamstrup A/S
Xylem Inc. (includes Sensus)
Iskraemeco d.d.
Genus Power Infrastructures Limited
Holley Technology Ltd.
Diehl Metering GmbH
Zenner International GmbH & Co. KG
Apator S.A.
Secure Meters Limited
Neptune Technology Group Inc.
Tantalus Systems Corp.
Trilliant Holdings Inc.
This stage focuses on developing and maintaining software systems including Meter Data Management (MDM), Head-End Systems (HES), Customer Information Systems (CIS), and analytics platforms that process, store, and analyze meter data for utility operations and customer service.
Key Players: Oracle, SAP, IBM, Itron, Landis+Gyr
This stage involves installing smart meters, deploying communication infrastructure, integrating systems with existing utility platforms, configuring networks, and conducting field testing to ensure proper operation of the complete end-to-end solution.
Key Players: Capgemini, Accenture, Wipro, TCS, Infosys
This stage encompasses providing and maintaining communication networks that connect meters to utilities, including RF mesh networks, cellular connectivity, PLC infrastructure, and LPWAN solutions, along with network management and optimization services.
Key Players: Cisco Systems, Ericsson, Nokia, Huawei, Sierra Wireless
This stage includes maintenance, technical support, data management, system upgrades, and managed services that ensure continued operation and optimization of smart meter infrastructure throughout its lifecycle.
Key Players: Landis+Gyr, Itron, Schneider Electric, Siemens, Honeywell
Report infographic
Market dynamics
13 factors across 3 forcesGovernment Mandates and Smart Grid Initiatives
The smart meter market is driven by strong government regulations and global smart grid modernization plans. Countries are setting mandatory rollout targets to improve energy efficiency and cut carbon emissions. For example, the EU requires at least 80% smart meter coverage by 2025. The U.S. supports infrastructure upgrades through the Smart Grid Investment Grant program. China's 14th Five Year Plan and India's National Smart Meter Program also promote widespread smart meter adoption. These initiatives provide funding, regulations, and guidelines that support market growth. Additionally, integrating renewables and implementing demand response programs make smart meters crucial for utilities to meet regulatory demands.
Reduction in Energy Theft and Non-Technical Losses
A major reason for smart meter adoption in emerging markets is the need to lower revenue losses from energy theft and other non-technical problems. Traditional meters are easy to tamper with, and they can lead to unauthorized connections and billing mistakes. These issues result in substantial financial losses for utilities. Smart meters come with features like tamper detection, real-time monitoring, and remote disconnect capabilities. These tools help utilities quickly identify and address theft. Immediate alerts significantly reduce response times compared to manual readings done periodically. In regions with high theft rates, utilities have managed to cut non-technical losses by 10-15% after installing smart meters. Remote disconnects also lower field visit costs and enhance payment collection. Moreover, automated readings prevent billing errors, which cuts down on disputes and improves customer satisfaction and revenue.
Table of contents
14 chapters · 159 sections · 228 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2035) |
|---|---|---|
| By End-User | Why | At the same time, the utilities |
By End-User
- The residential segment holds the largest share of the overall smart meter market because of the large number of households around the world.
- Governments often focus on smart meter installation in homes due to the significant potential for energy savings, load management, and operational efficiency.
- Smart meters provide consumers with detailed usage data through apps and portals, which encourages energy-saving habits and allows for shifting consumption to off-peak times to save money.
- Utilities benefit from reduced manual readings, more accurate billing, fewer truck rolls, and easier remote management.
- National campaigns in countries like the U.S., UK, Germany, China, and India have driven strong demand in the residential sector.
- New smart home solutions, such as energy management systems, solar integration, EV charging, and home automation, are making residential smart meters even more attractive.
- At the same time, the utilities segment is growing at the fastest CAGR through 2035 as electric, gas, and water providers view smart meters as essential for modernizing their operations.
- Beyond helping customers, smart meters enhance grid management, outage detection, asset optimization, and renewable energy integration.
- They give utilities real-time visibility into system conditions, which enables predictive maintenance, better capital planning, and improved reliability.
- Smart meters are also installed on transformers and substations, creating networks for comprehensive grid monitoring.
- Regulatory drives, efficiency targets, and the move toward distributed renewables are spurring strong growth in this utility-focused segment.
Geographic analysis
Asia-Pacific
Largest shareThe Asia Pacific region holds the largest share of the global smart meter market in 2025, largely because of China's rollout of hundreds of millions of meters through smart grid projects. China’s State Grid Corporation has invested heavily in smart grid upgrades. This allows for renewable integration and modernization. Japan has nearly 100% smart meter coverage in urban areas because of utility mandates. South Korea’s smart grid initiatives, such as the Jeju Test-Bed, provide solid market support. India’s ambitious Smart Meter National Programme aims to replace 250 million traditional meters, creating significant growth opportunities. The region benefits from competitive hardware production, government policies, financial incentives, and increasing urban electricity demand. Moreover, cutting technical and commercial losses, especially in India and Southeast Asia, drives strong smart meter adoption. By Region Australia Rest of Asia-Pacific (RoAPAC)
Europe
U.K. Germany France Italy Spain Netherlands Rest of Europe (RoE)
Middle East & Africa
Saudi Arabia United Arab Emirates (UAE) Rest of Middle East & Africa (RoMEA)
Competitive landscape
- September 2025
— Landis+Gyr Group AG announced the divestiture of its entire Europe, Middle East and Africa (EMEA) operations to AURELIUS for an enterprise value of USD 215 million.
- August 2025
— Honeywell International acquired three utility platforms from SparkMeter Inc. to expand its Smart Energy portfolio. The acquisition includes Praxis (data platform for utility insights and analytics), GridScan (software for distribution grid performance monitoring), and GridFin (financial management application for energy supply costs).
- July 2025
— Schneider Electric announced the acquisition of the remaining 35% stake in Schneider Electric India Private Limited (SEIPL) from Temasek for €5.5 billion all-cash consideration.
Frequently asked questions
The smart meter market is expected to increase from USD 28.5 billion in 2025 to USD 64.3 billion by 2035.
Cite this report
Meticulous Research. (2025). Smart Meter Market - Global Opportunity Analysis and Industry Forecast (2025-2035) (Report No. MREP - 1041611). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/smart-meter-market-6294