Precision Motion Control Market
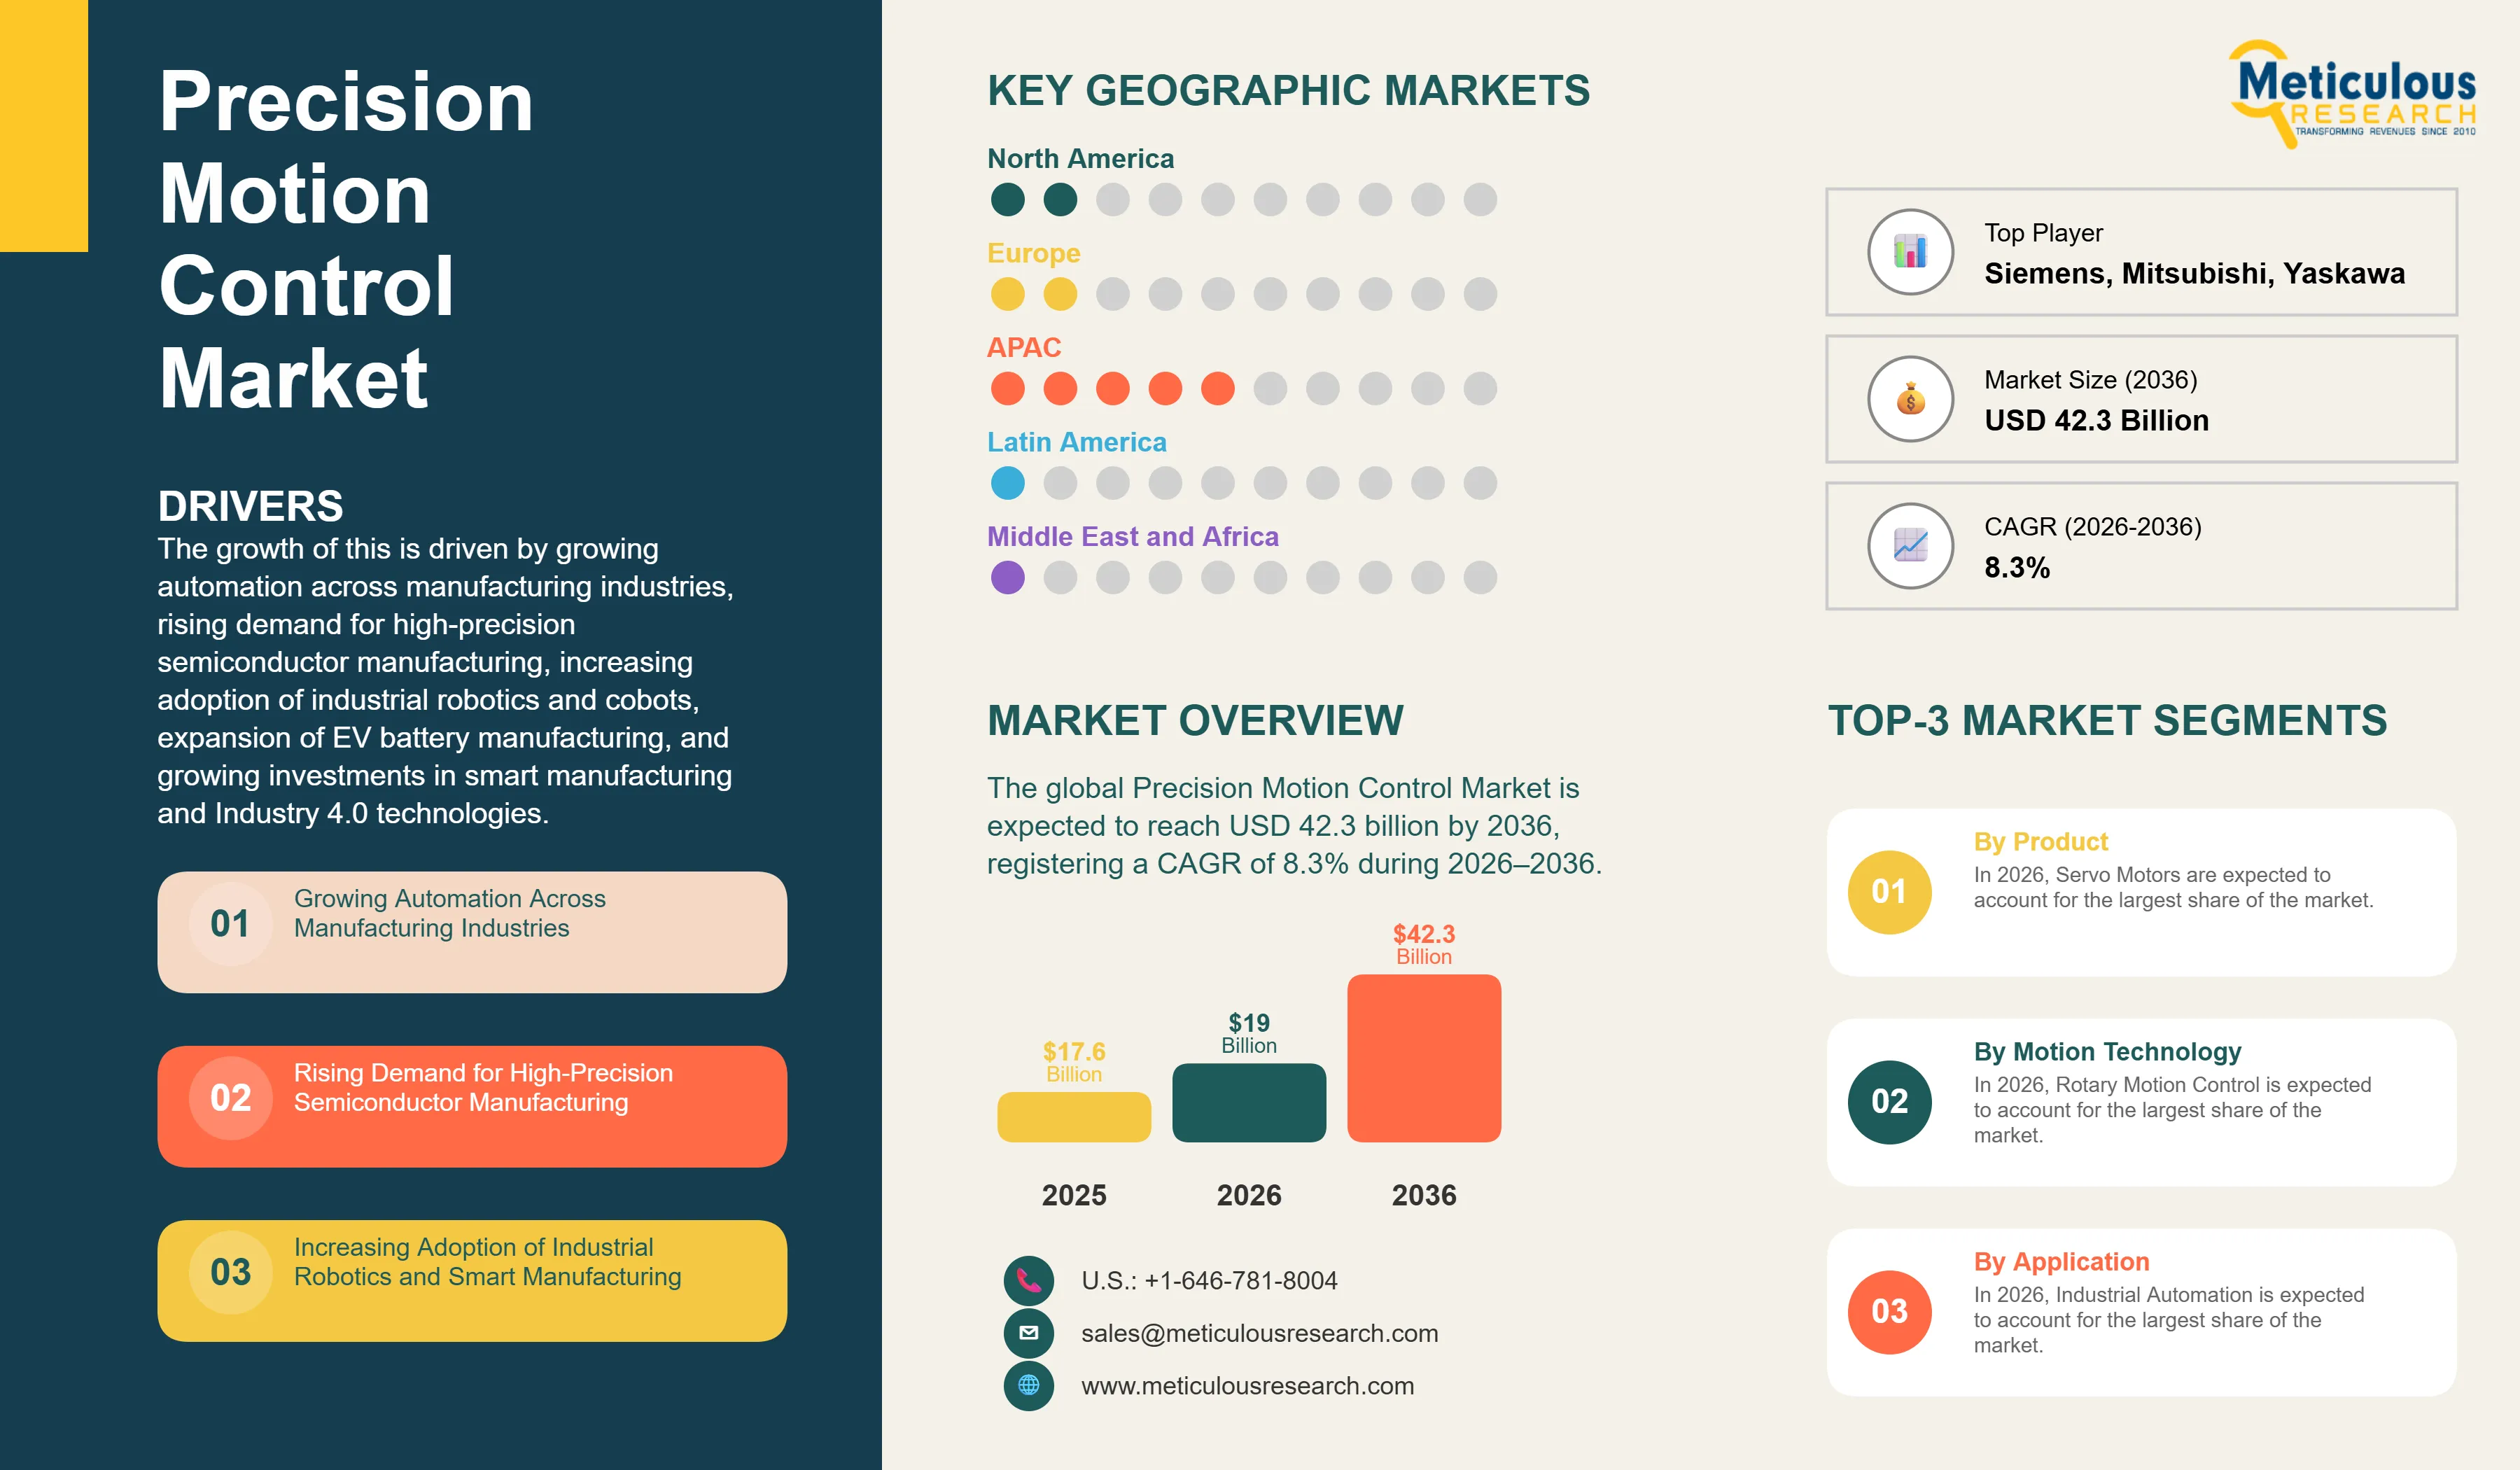
The global Precision Motion Control Market was valued at USD 17.6 billion in 2025 and is projected to reach USD 19.0 billion in 2026. The market is expected to reach USD 42.3 billion by 2036, registering a CAGR of 8.3% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 310
- Format
- PDF + Excel
- Report ID
- MR-2121
- Base year
- 2025
- 2025 · BASELINE
- $17.60B
- 2036
- $42.30B
- CAGR 2026–2036
- 8.3%
2025 baseline · 2026–2036 forecast at 8.3% CAGR · hover a bar for the value
Key highlights
The global Precision Motion Control Market is projected to reach USD 42.3 billion by 2036, driven by increasing industrial automation, rapid expansion of semiconductor manufacturing, growing adoption of robotics, and rising investments in smart factories.
Asia-Pacific is expected to account for the largest market share in 2026, while North America is projected to register the fastest growth during the forecast period.
By product, Servo Motors are expected to account for the largest market share, whereas Motion Control Software is projected to witness the fastest growth through 2036.
By motion technology, Rotary Motion Control is expected to dominate the market, while Multi-Axis Motion Control is projected to register the fastest growth during the forecast period.
Increasing adoption of AI-enabled motion control, digital twins, industrial Ethernet, and real-time communication technologies is accelerating market growth.
Rising investments in semiconductor fabrication, EV battery manufacturing, industrial robotics, and precision medical equipment are expected to create significant long-term growth opportunities.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 8.3% |
| Format | PDF, Excel & Cloud Portal · 310 pages |
| Market Size (Value) in 2026 | USD 19.0 Billion |
| Market Size (Value) in 2036 | USD 42.3 Billion |
| Segments Covered | By Product: Motion Controllers (Standalone Motion Controllers, PLC-Based Motion Controllers, PC-Based Motion Controllers, CNC Motion Controllers), Servo Motors (AC Servo Motors, DC Servo Motors, Linear Servo Motors), Servo Drives (Single-Axis Servo Drives, Multi-Axis Servo Drives), Linear Motion Systems (Linear Stages, Linear Actuators, Linear Guides, Ball Screws & Lead Screws), Feedback Devices (Optical Encoders, Magnetic Encoders, Linear Encoders, Rotary Encoders, Resolvers), Motion Control Software, Services (System Design & Engineering, Integration & Commissioning, Maintenance & Support). · By Motion Technology: Rotary Motion Control, Linear Motion Control, Multi-Axis Motion Control, Direct Drive Motion Systems, Piezoelectric Motion Systems, Voice Coil Motion Systems. · By Control Architecture: Open-Loop Systems, Closed-Loop Systems, Distributed Motion Control Systems, Centralized Motion Control Systems. · By Application: Semiconductor Manufacturing (Wafer Processing Equipment, Lithography Systems, Inspection & Metrology, Advanced Packaging), Industrial Automation (Assembly Automation, Material Handling, Packaging Automation, Machine Tools), Robotics (Industrial Robots, Collaborative Robots, Autonomous Mobile Robots), Electronics Manufacturing, Medical Devices & Laboratory Automation, EV & Battery Manufacturing, Aerospace & Defense, Precision Measurement & Scientific Instruments. · By End User: Semiconductor Manufacturers, Electronics Manufacturers, Automotive Manufacturers, Medical Device Companies, Aerospace & Defense Companies, Industrial Machinery Manufacturers, Research Institutions. |
| Countries Covered | North America: U.S., Canada. · Europe: Germany, U.K., France, Italy, Switzerland, Netherlands, Sweden, Rest of Europe. · Asia-Pacific: China, Japan, South Korea, Taiwan, India, Singapore, Malaysia, Australia, Rest of Asia-Pacific. · Latin America: Brazil, Mexico, Argentina, Chile, Colombia, Rest of Latin America. · Middle East & Africa: UAE, Saudi Arabia, South Africa, Turkey, Rest of Middle East & Africa. |
| Key Companies | Siemens AG, Mitsubishi Electric Corporation, Yaskawa Electric Corporation, FANUC Corporation, Rockwell Automation, Inc., Bosch Rexroth AG, Schneider Electric SE, ABB Ltd., Beckhoff Automation GmbH & Co. KG, Omron Corporation, Parker Hannifin Corporation, Kollmorgen Corporation, HIWIN Technologies Corp., Aerotech Inc., and THK Co., Ltd. |
Report overview
Segments covered: product, motion technology, control architecture, application, end user, smart manufacturing application.
The Precision Motion Control Market comprises hardware, software, and integrated systems used to achieve highly accurate control of motion, positioning, speed, and torque in industrial machinery and automated equipment. The market includes motion controllers, servo motors, servo drives, linear motion systems, feedback devices, motion control software, and engineering services that enable precise, synchronized movement across manufacturing and industrial applications. These technologies are widely used in semiconductor manufacturing, industrial automation, robotics, electronics manufacturing, medical devices, EV battery production, aerospace, and scientific instruments, where micron-level positioning accuracy and repeatability are essential.
The market is experiencing strong growth as manufacturers increasingly adopt smart automation to improve productivity, product quality, and operational efficiency. According to the International Federation of Robotics (IFR) World Robotics 2025, a record 4.28 million industrial robots are operating in factories worldwide, while annual installations exceeded 540,000 units, marking the fourth consecutive year with more than half a million new robots installed globally. Asia accounts for nearly 70% of all new industrial robot installations, led by China, Japan, and South Korea. Modern industrial robots rely on high-performance servo motors, motion controllers, and feedback systems to achieve precise positioning, synchronized movement, and high-speed operation, driving demand for advanced precision motion control solutions.
The rapid expansion of semiconductor manufacturing is another major growth driver. According to SEMI, global semiconductor fabrication capacity continues to expand as governments and manufacturers invest billions of dollars in new wafer fabrication plants. Advanced semiconductor manufacturing processes, including lithography, wafer inspection, and advanced packaging, require nanometer-level positioning accuracy and ultra-high-speed motion control systems. In addition, increasing investments in EV battery manufacturing, collaborative robots (cobots), and Industry 4.0 technologies are accelerating adoption of AI-enabled motion control, digital twins, and Industrial Ethernet-based control systems, creating significant opportunities across the market.
Market dynamics
10 factors across 5 forcesGrowing Automation Across Manufacturing Industries
The increasing adoption of industrial automation is one of the primary factors driving the Precision Motion Control Market. Manufacturers across automotive, electronics, food & beverage, pharmaceutical, packaging, and industrial machinery sectors are investing in automated production lines to improve productivity, reduce labor costs, and enhance manufacturing precision. According to the International Federation of Robotics (IFR) World Robotics 2025, a record 4.28 million industrial robots are operating in factories worldwide, with annual installations exceeding 540,000 units for the fourth consecutive year. In addition, Asia accounted for nearly 70% of all new industrial robot installations, reflecting the rapid expansion of factory automation across the region. Precision motion control systems enable highly accurate positioning, synchronized multi-axis movement, and real-time machine control, making them essential for modern automated manufacturing. As smart factories continue to expand globally and manufacturers accelerate digital transformation and Industry 4.0 initiatives, demand for advanced motion control technologies is expected to increase steadily.
Rising Demand for High-Precision Semiconductor Manufacturing
The rapid growth of the semiconductor industry is significantly increasing demand for precision motion control systems. Semiconductor manufacturing equipment such as lithography machines, wafer processing tools, metrology systems, and advanced packaging equipment requires extremely accurate positioning with high repeatability and minimal vibration. According to SEMI, global investments in semiconductor manufacturing continue to grow as new fabrication facilities are established across Asia, North America, and Europe. This expansion is driving strong demand for high-performance servo systems, linear motion technologies, and advanced motion controllers capable of supporting next-generation semiconductor production.
Table of contents
13 chapters · 209 sections · 310 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product | Servo Motors | Motion Control Software |
| By Motion Technology | Rotary Motion Control | Multi-Axis Motion Control |
| By Control Architecture | Closed-Loop Systems | Distributed Motion Control Systems |
| By Application | Industrial Automation | Semiconductor Manufacturing |
| By End User | Industrial Machinery Manufacturers | Semiconductor Manufacturers |
By Product
- The Servo Motors segment is expected to account for the largest share of the global Precision Motion Control Market.
- The large share of this segment is mainly due to their widespread use in industrial robots, semiconductor equipment, machine tools, packaging systems, and automated production lines requiring highly accurate motion control.
- However, the Motion Control Software segment is projected to register the fastest growth during the forecast period.
- The rapid growth of this segment is attributed to increasing adoption of AI-enabled control algorithms, digital twin platforms, predictive maintenance software, and Industry 4.0 solutions.
By Motion Technology
- Rotary Motion Control is expected to account for the largest market share because it is extensively used across industrial automation, robotics, machine tools, and conveyor systems.
- However, Multi-Axis Motion Control is projected to register the highest CAGR during the forecast period owing to increasing demand for synchronized motion in semiconductor manufacturing, robotics, EV battery production, and high-speed automation.
By Control Architecture
- Closed-Loop Systems are expected to account for the largest market share due to their superior positioning accuracy, continuous feedback capability, and widespread use in high-precision industrial applications.
- However, Distributed Motion Control Systems are projected to register the highest CAGR during the forecast period because they offer greater scalability, improved machine flexibility, and enhanced real-time communication for smart factories.
By Application
- Industrial Automation is expected to account for the largest market share due to increasing automation across manufacturing industries and continuous investments in smart factories.
- However, Semiconductor Manufacturing is projected to register the highest CAGR during the forecast period owing to rapid global expansion of semiconductor fabrication facilities and increasing demand for nanometer-level precision manufacturing equipment.
By End User
- Industrial Machinery Manufacturers are expected to account for the largest market share because precision motion control systems are widely integrated into machine tools, packaging equipment, material handling systems, and factory automation machinery.
- However, Semiconductor Manufacturers are projected to register the highest CAGR during the forecast period due to increasing investments in wafer fabrication, advanced packaging technologies, and next-generation semiconductor manufacturing facilities.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Precision Motion Control Market. The region's leadership is driven by its strong manufacturing base, rapid expansion of semiconductor fabrication facilities, increasing adoption of industrial automation, and leadership in robotics manufacturing. Countries such as China, Japan, South Korea, and Taiwan are among the world's leading producers of industrial robots, semiconductor equipment, electronics, and precision manufacturing machinery. According to the International Federation of Robotics (IFR) World Robotics 2025, Asia accounted for nearly 70% of global industrial robot installations, while China alone represented approximately 51% of all new industrial robot installations worldwide. China also continues to have the world's largest operational stock of industrial robots, exceeding 2 million units. Furthermore, SEMI's World Fab Forecast 2025 indicates that Asia accounts for more than 60% of global semiconductor manufacturing capacity and remains the primary destination for new wafer fabrication investments. In addition, ongoing investments in semiconductor fabrication, EV battery production, electronics manufacturing, and smart factories are significantly increasing demand for precision motion control systems across the region.
North America
Fastest growthHowever, North America is projected to register the highest CAGR during the forecast period. The region is witnessing increasing investments in semiconductor manufacturing, advanced robotics, aerospace, medical device manufacturing, and smart manufacturing initiatives. Government incentives supporting domestic semiconductor production, together with growing adoption of collaborative robots, AI-enabled automation, and digital manufacturing technologies, are expected to accelerate demand for advanced motion control solutions. The rapid expansion of EV battery manufacturing and precision medical equipment production is also contributing to market growth across North America.
Competitive landscape
The global Precision Motion Control Market is moderately consolidated, with competition among automation companies, motion control specialists, servo motor manufacturers, industrial robotics suppliers, and precision linear motion technology providers. Companies compete primarily on positioning accuracy, system reliability, motion speed, AI-enabled control capabilities, product integration, software functionality, energy efficiency, and after-sales technical support.
Leading market participants are investing in AI-based motion optimization, digital twin technologies, Industrial Ethernet communication, advanced servo systems, and intelligent motion control software to strengthen their competitive position. Strategic partnerships with machine builders, semiconductor equipment manufacturers, robotics companies, and industrial OEMs, along with product innovation, acquisitions, and manufacturing expansion, remain the key strategies adopted by major vendors. Companies are also focusing on developing highly integrated motion platforms capable of supporting Industry 4.0, autonomous manufacturing, and next-generation semiconductor production.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Precision Motion Control Market. The key players profiled in the report include Siemens AG, Mitsubishi Electric Corporation, Yaskawa Electric Corporation, FANUC Corporation, Rockwell Automation, Inc., Bosch Rexroth AG, Schneider Electric SE, ABB Ltd., Beckhoff Automation GmbH & Co. KG, Omron Corporation, Parker Hannifin Corporation, Kollmorgen Corporation, HIWIN Technologies Corp., Aerotech Inc., and THK Co., Ltd.
- Siemens AG
- Mitsubishi Electric Corporation
- Yaskawa Electric Corporation
- FANUC Corporation
- Rockwell Automation, Inc.
- Bosch Rexroth AG
- Schneider Electric SE
- ABB Ltd.
- Beckhoff Automation GmbH & Co. KG
- Omron Corporation
- Parker Hannifin Corporation
- Kollmorgen Corporation
- HIWIN Technologies Corp.
- Aerotech Inc.
- THK Co., Ltd
Frequently asked questions
The global Precision Motion Control Market is estimated at USD 19.0 billion in 2026.
Cite this report
Meticulous Research. (2026). Precision Motion Control Market - Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2121). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/precision-motion-control-market-6804