Precision Manufacturing Equipment for AI Infrastructure Market
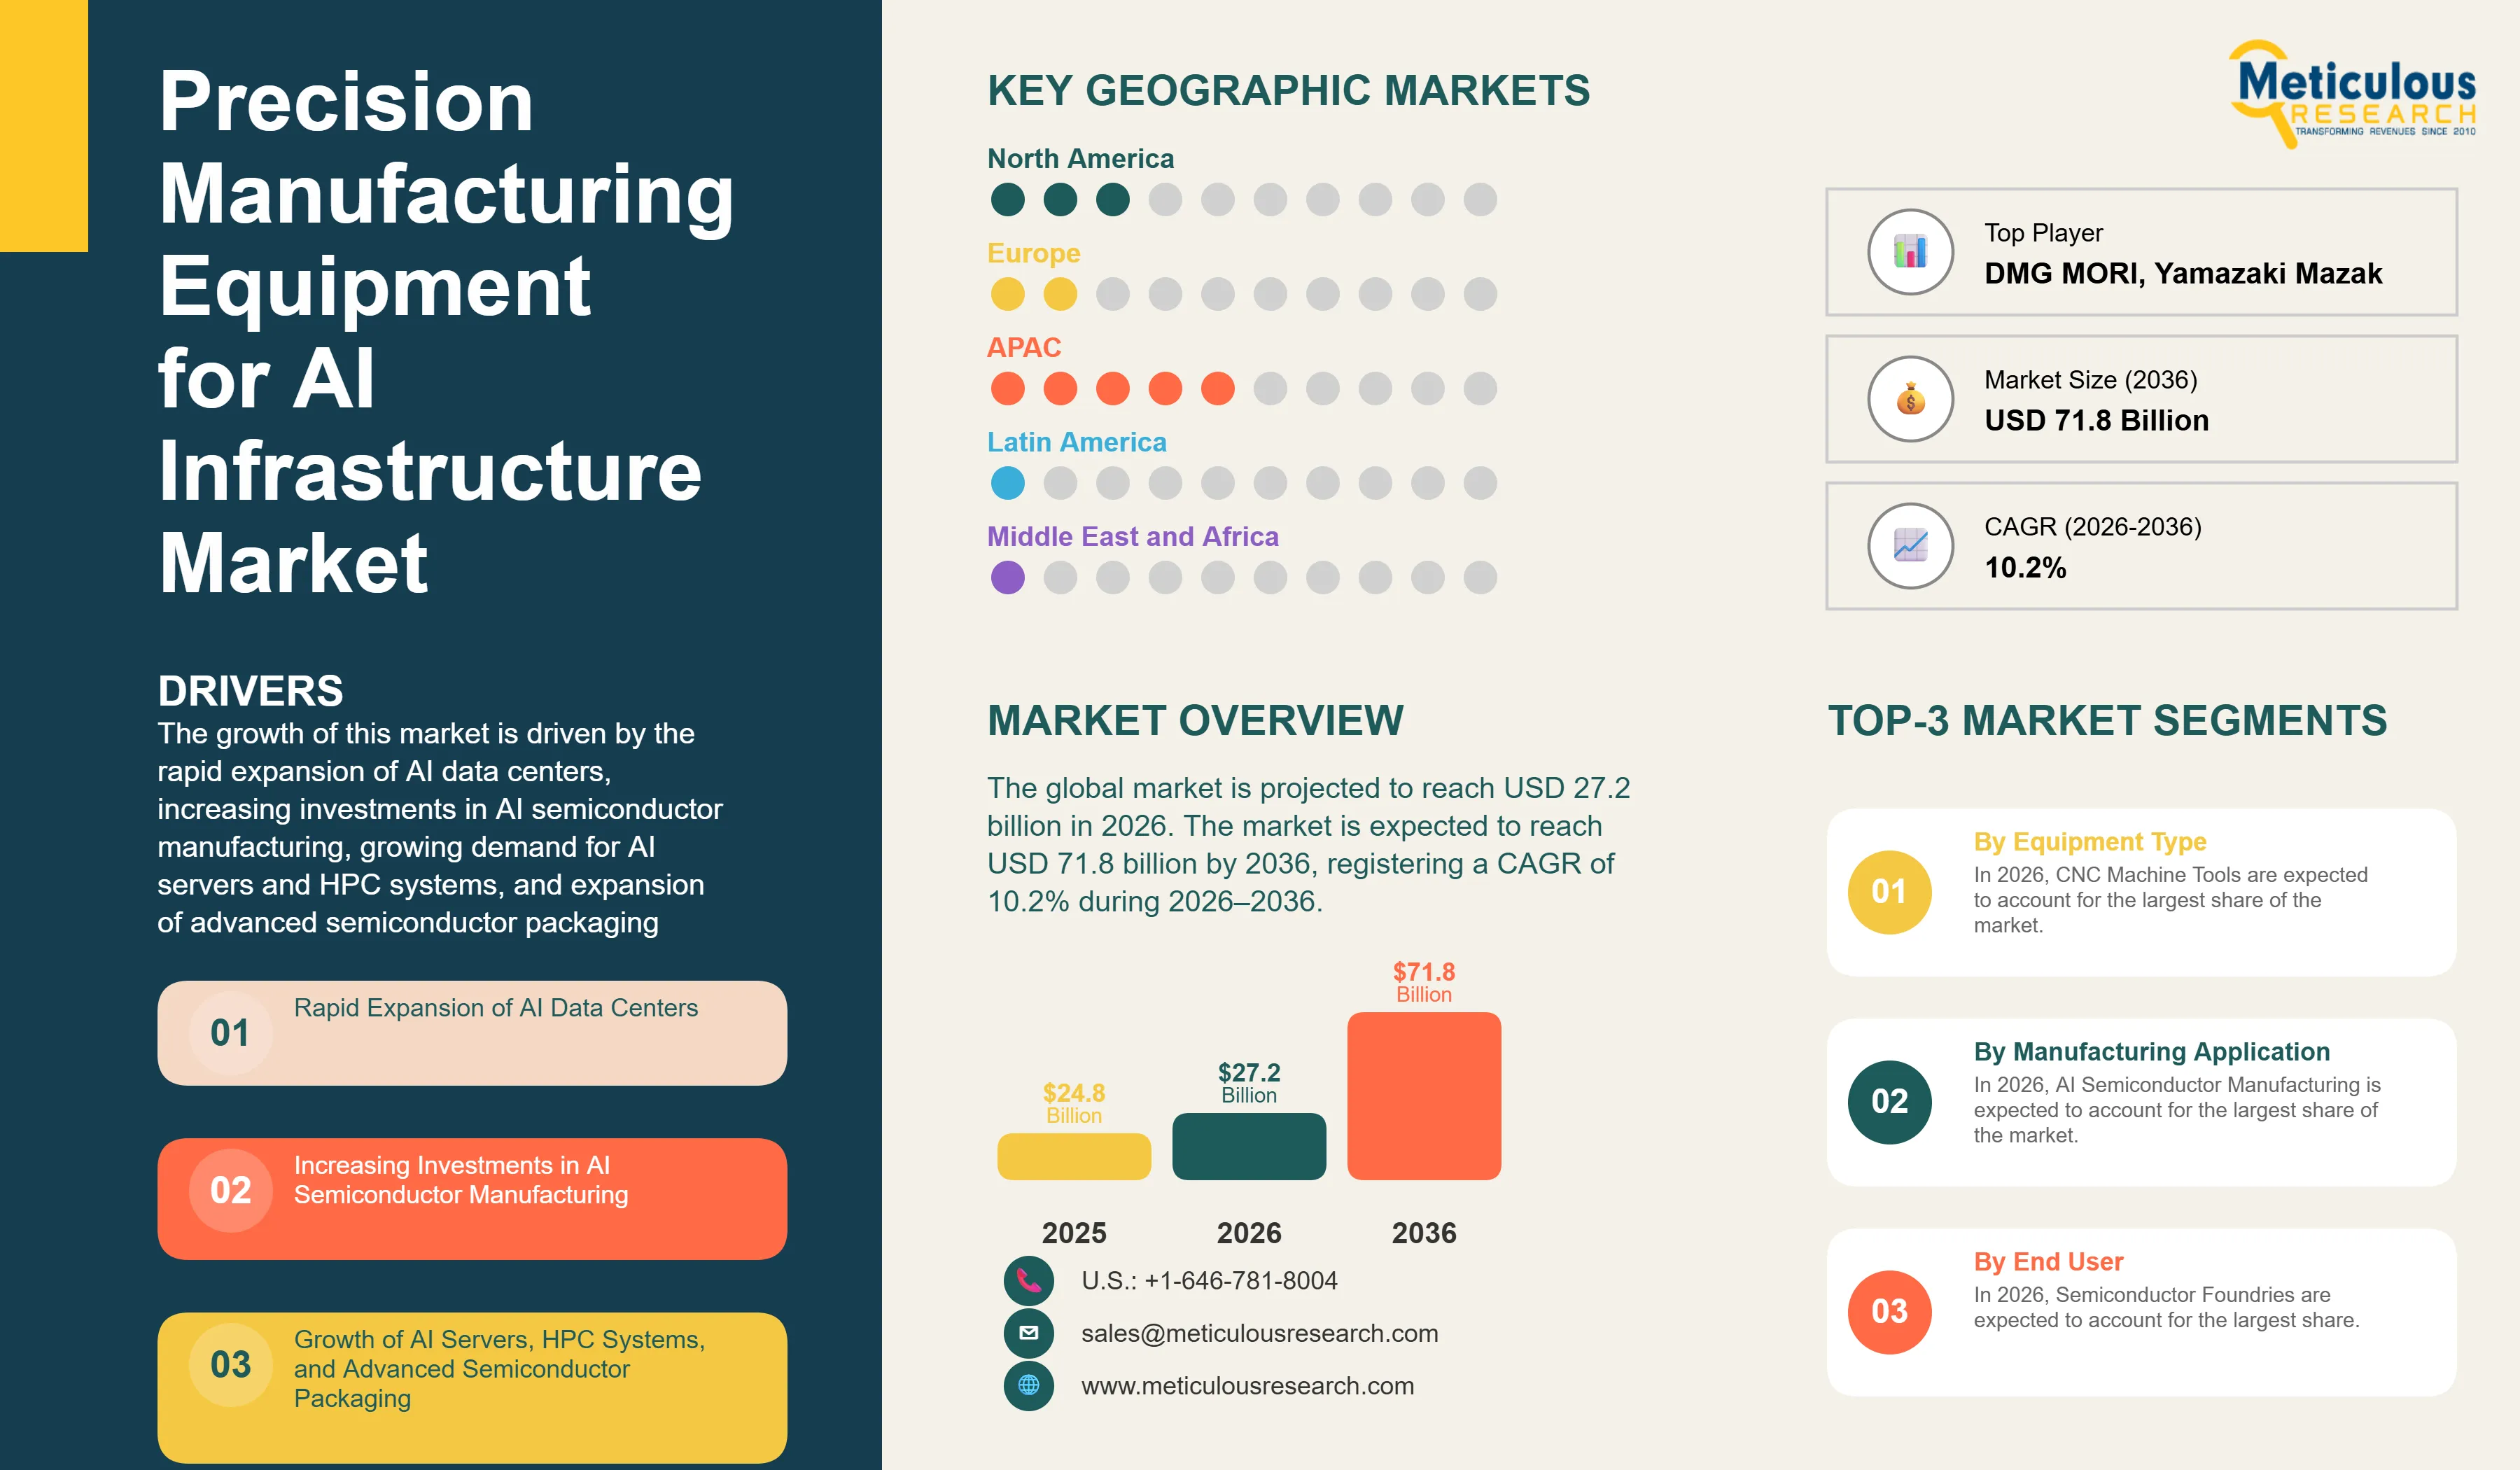
The global Precision Manufacturing Equipment for AI Infrastructure Market was valued at USD 24.8 billion in 2025 and is projected to reach USD 27.2 billion in 2026. The market is expected to reach USD 71.8 billion by 2036, registering a CAGR of 10.2% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 305
- Format
- PDF + Excel
- Report ID
- MR-2122
- Base year
- 2025
- 2024 · HISTORICAL
- $153.0B
- 2036
- $71.80B
- CAGR 2026–2036
- 10.2%
2024–2025 baseline · 2026–2036 forecast at 10.2% CAGR · hover a bar for the value
Key highlights
The global Precision Manufacturing Equipment for AI Infrastructure Market is projected to reach USD 71.8 billion by 2036, driven by rapid expansion of AI data centers, increasing investments in AI semiconductor manufacturing, and growing production of AI servers and high-performance computing (HPC) systems.
Asia-Pacific is expected to account for the largest market share in 2026, while North America is projected to register the fastest growth during the forecast period.
By equipment type, CNC Machine Tools are expected to account for the largest market share, whereas Precision Automation & Robotics is projected to witness the fastest growth through 2036.
By manufacturing application, AI Semiconductor Manufacturing is expected to dominate the market, while Advanced Semiconductor Packaging is projected to register the highest CAGR during the forecast period.
Increasing adoption of AI-based manufacturing process control, digital twins, ultra-precision machining, and smart manufacturing technologies is accelerating market growth.
Rising investments in chiplet packaging, liquid cooling infrastructure, optical interconnect manufacturing, and AI gigafactories are expected to create significant long-term growth opportunities.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 10.2% |
| Format | PDF, Excel & Cloud Portal · 305 pages |
| Market Size (Value) in 2026 | USD 27.2 Billion |
| Market Size (Value) in 2036 | USD 71.8 Billion |
| Segments Covered | By Equipment Type: CNC Machine Tools, Precision Grinding Equipment, Electrical Discharge Machining (EDM) Equipment, Laser Processing Equipment, Precision Surface Finishing Equipment, Precision Metrology & Inspection Equipment, Precision Motion Control Equipment, Precision Automation & Robotics. · By Manufacturing Application: AI Semiconductor Manufacturing, Advanced Semiconductor Packaging, AI Server Manufacturing, High-Speed Optical Interconnect Manufacturing, Liquid Cooling Equipment Manufacturing, High-Density Rack Manufacturing, Power Distribution Equipment Manufacturing, Data Center Mechanical Infrastructure Manufacturing. · By Manufacturing Process: Precision Machining, Precision Grinding, Laser Micromachining, Electrical Discharge Machining, Precision Surface Finishing, Precision Measurement & Inspection. · By Automation Level: Standalone Equipment, Semi-Automated Systems, Fully Automated Manufacturing Cells, Smart Manufacturing Systems (Industry 4.0 Enabled). · By End User: Semiconductor Foundries, Outsourced Semiconductor Assembly & Test (OSAT) Providers, AI Server Manufacturers, Optical Networking Equipment Manufacturers, Liquid Cooling Equipment Manufacturers, Data Center Infrastructure Manufacturers, Electronics Manufacturing Services (EMS) Providers |
| Countries Covered | North America: U.S., Canada. · Europe: Germany, Switzerland, Italy, U.K., France, Netherlands, Rest of Europe. · Asia-Pacific: China, Japan, Taiwan, South Korea, Singapore, Malaysia, India, Vietnam, Rest of Asia-Pacific. · Latin America: Brazil, Mexico, Argentina, Rest of Latin America. · Middle East & Africa: UAE, Saudi Arabia, Israel, South Africa, Rest of Middle East & Africa. |
| Key Companies | DMG MORI Co., Ltd., Yamazaki Mazak Corporation, Makino Milling Machine Co., Ltd., GF Machining Solutions, Okuma Corporation, FANUC Corporation, Siemens AG, Bosch Rexroth AG, THK Co., Ltd., HIWIN Technologies Corp., Renishaw plc, Hexagon AB, Mitutoyo Corporation, ABB Ltd., and Aerotech Inc. |
Report overview
Segments covered: equipment type, manufacturing application, manufacturing process, automation level, end user.
The Precision Manufacturing Equipment for AI Infrastructure Market comprises advanced manufacturing equipment, precision machining systems, automation technologies, metrology solutions, and process control platforms used to manufacture critical components supporting AI infrastructure. The market includes CNC machine tools, precision grinding equipment, electrical discharge machining (EDM) systems, laser processing equipment, precision surface finishing equipment, metrology & inspection systems, precision motion control equipment, and precision automation & robotics. These technologies are essential for manufacturing AI semiconductors, advanced semiconductor packaging, AI servers, optical networking equipment, liquid cooling systems, power distribution equipment, and high-density data center infrastructure.
The market is witnessing robust growth as global investments in artificial intelligence infrastructure continue to accelerate. According to IDC, worldwide AI infrastructure spending reached US$318 billion in 2025, more than doubling from US$153 billion in 2024, and is projected to increase to approximately US$487 billion in 2026. Server infrastructure accounted for nearly 98% of AI infrastructure spending, reflecting strong demand for AI compute platforms. These investments are significantly increasing demand for ultra-precision machining systems, semiconductor manufacturing equipment, metrology solutions, and advanced automation technologies required to manufacture AI processors, networking equipment, cooling infrastructure, and power systems with micron- and sub-micron-level accuracy.
The rapid expansion of advanced semiconductor manufacturing is another major growth driver. According to SEMI's World Fab Forecast 2025, global front-end semiconductor fab equipment spending is expected to reach US$130 billion in 2026, driven primarily by AI accelerators, high-bandwidth memory (HBM), and data center semiconductor demand. In addition, SEMI projects global 300 mm fab equipment investment to total US$374 billion during 2026–2028 as manufacturers expand capacity to support AI-related chip production. At the same time, increasing adoption of chiplet architectures, 2.5D and 3D packaging, silicon photonics, and liquid cooling technologies is creating strong demand for high-precision manufacturing equipment. Growing deployment of AI-driven manufacturing analytics, digital twins, and precision robotics is further improving production efficiency and supporting long-term market expansion.
Market dynamics
10 factors across 5 forcesRapid Expansion of AI Data Centers
The rapid deployment of AI data centers worldwide is significantly increasing demand for precision manufacturing equipment. AI facilities require advanced servers, GPUs, networking equipment, liquid cooling systems, high-density racks, and precision-engineered power infrastructure, all of which depend on highly accurate manufacturing processes. According to Cloudscene, more than 11,700 data centers were operational worldwide as of May 2026, with the United States hosting 5,427 facilities (approximately 46% of the global total), followed by Germany (529), the United Kingdom (523), China (449), and Canada (337). In addition, Synergy Research estimates that the number of hyperscale data centers worldwide reached approximately 1,360 by the end of 2025, reflecting the rapid expansion of AI and cloud infrastructure. This rapid infrastructure expansion is driving demand for ultra-precision machining, metrology systems, laser processing equipment, and advanced manufacturing automation required to manufacture AI servers, advanced semiconductor packages, optical networking equipment, liquid cooling components, and high-density power infrastructure.
Increasing Investments in AI Semiconductor Manufacturing
Growing production of AI accelerators, GPUs, custom AI processors, and high-bandwidth memory (HBM) is creating substantial demand for advanced precision manufacturing equipment. Semiconductor fabrication requires nanometer-scale machining, precision inspection, and highly automated production systems capable of maintaining exceptional process accuracy. Governments across the U.S., Europe, Japan, South Korea, and Taiwan continue to invest billions of dollars in semiconductor manufacturing through industrial policies and incentive programs. These investments are expected to significantly increase demand for CNC machining centers, precision metrology systems, motion control equipment, and semiconductor manufacturing automation.
Table of contents
4 chapters · 212 sections · 305 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Equipment Type | CNC Machine Tools | Precision Automation & Robotics |
| By Manufacturing Application | AI Semiconductor Manufacturing | Advanced Semiconductor Packaging |
| By Manufacturing Process | Precision Machining | Precision Measurement & Inspection |
| By Automation Level | Semi-Automated Systems | Smart Manufacturing Systems (Industry 4.0 Enabled) |
| By End User | Semiconductor Foundries | Outsourced Semiconductor Assembly & Test (OSAT) Providers |
By Equipment Type
- The CNC Machine Tools segment is expected to account for the largest share of the global Precision Manufacturing Equipment for AI Infrastructure Market.
- The large share of this segment is mainly due to its widespread use in manufacturing semiconductor equipment, AI server components, precision cooling systems, and optical networking hardware requiring high dimensional accuracy and repeatability.
- However, the Precision Automation & Robotics segment is projected to register the fastest growth during the forecast period.
- The rapid growth of this segment is attributed to increasing adoption of fully automated production lines, AI-driven manufacturing, collaborative robots, and automated material handling systems in semiconductor and AI hardware manufacturing.
By Manufacturing Application
- Market Analysis by Manufacturing Application
- AI Semiconductor Manufacturing is expected to account for the largest market share due to increasing global production of AI accelerators, GPUs, custom AI processors, and high-bandwidth memory devices.
- However, Advanced Semiconductor Packaging is projected to register the highest CAGR during the forecast period owing to rapid adoption of chiplet architectures, heterogeneous integration, and advanced packaging technologies for AI computing.
By Manufacturing Process
- Precision Machining is expected to account for the largest market share because it forms the foundation of manufacturing highly accurate semiconductor equipment, server components, and precision infrastructure hardware.
- However, Precision Measurement & Inspection is projected to register the highest CAGR during the forecast period due to increasing quality requirements, shrinking semiconductor geometries, and growing adoption of AI-enabled inspection technologies.
By Automation Level
- Semi-Automated Systems are expected to account for the largest market share due to their widespread deployment across existing precision manufacturing facilities balancing automation with operational flexibility.
- However, Smart Manufacturing Systems (Industry 4.0 Enabled) are projected to register the highest CAGR during the forecast period owing to increasing integration of AI, digital twins, industrial IoT, machine vision, and predictive manufacturing analytics.
By End User
- Semiconductor Foundries are expected to account for the largest market share owing to massive investments in AI chip fabrication, wafer processing, and advanced semiconductor manufacturing capacity.
- However, Outsourced Semiconductor Assembly & Test (OSAT) Providers are projected to register the highest CAGR during the forecast period due to increasing demand for advanced semiconductor packaging, chiplet integration, and high-performance AI processor assembly.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Precision Manufacturing Equipment for AI Infrastructure Market. The region's leadership is driven by its dominant semiconductor manufacturing ecosystem, strong electronics production base, and extensive investments in AI hardware manufacturing. Countries such as Taiwan, China, Japan, South Korea, and Singapore are global leaders in semiconductor fabrication, advanced packaging, precision machine tools, and electronics manufacturing. According to SEMI, Asia accounts for the majority of the world's semiconductor fabrication capacity, while Taiwan, South Korea, and China continue to expand investments in advanced AI chip production and high-bandwidth memory (HBM) manufacturing. The rapid expansion of AI server production, optical interconnect manufacturing, and liquid cooling equipment manufacturing is further increasing demand for ultra-precision machining, metrology, automation, and inspection equipment across the region.
North America
Fastest growthHowever, North America is projected to register the highest CAGR during the forecast period. The region is witnessing unprecedented investments in AI infrastructure, semiconductor manufacturing, and advanced computing technologies. Government initiatives such as the U.S. CHIPS and Science Act, together with multi-billion-dollar investments by leading AI chip manufacturers, hyperscale cloud providers, and AI infrastructure companies, are accelerating domestic manufacturing capacity. Growing construction of AI gigafactories, increasing deployment of advanced packaging facilities, and expansion of high-performance computing infrastructure are expected to drive strong demand for precision manufacturing equipment throughout the forecast period.
Competitive landscape
The global Precision Manufacturing Equipment for AI Infrastructure Market is moderately consolidated, with competition among machine tool manufacturers, precision automation companies, metrology specialists, motion control providers, robotics companies, and industrial automation vendors. Companies compete primarily on machining accuracy, production throughput, automation capability, AI-enabled manufacturing intelligence, system integration, reliability, precision measurement capabilities, and global service support.
Leading market participants are investing in ultra-precision machining technologies, AI-based manufacturing process control, digital twin platforms, advanced metrology systems, precision robotics, and smart manufacturing solutions to strengthen their competitive position. Strategic collaborations with semiconductor manufacturers, OSAT providers, AI server manufacturers, and data center infrastructure companies, along with investments in manufacturing capacity expansion, product innovation, and software-enabled automation, remain the primary growth strategies adopted across the industry. Companies are also focusing on enabling micron- and sub-micron-level manufacturing precision to support next-generation AI semiconductor and infrastructure production.
- DMG MORI Co., Ltd.
- Yamazaki Mazak Corporation
- Makino Milling Machine Co., Ltd.
- GF Machining Solutions
- Okuma Corporation
- FANUC Corporation
- Siemens AG
- Bosch Rexroth AG
- THK Co., Ltd.
- HIWIN Technologies Corp.
- Renishaw plc
- Hexagon AB
- Mitutoyo Corporation
- ABB Ltd.
- Aerotech Inc
Frequently asked questions
The global Precision Manufacturing Equipment for AI Infrastructure Market is estimated at USD 27.2 billion in 2026.
Cite this report
Meticulous Research. (2026). Precision Manufacturing Equipment for AI Infrastructure Market - Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2122). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/precision-manufacturing-equipment-for-ai-infrastructure-market-6805