Offshore Wind Turbine Installation Vessels Market (2026-2036)
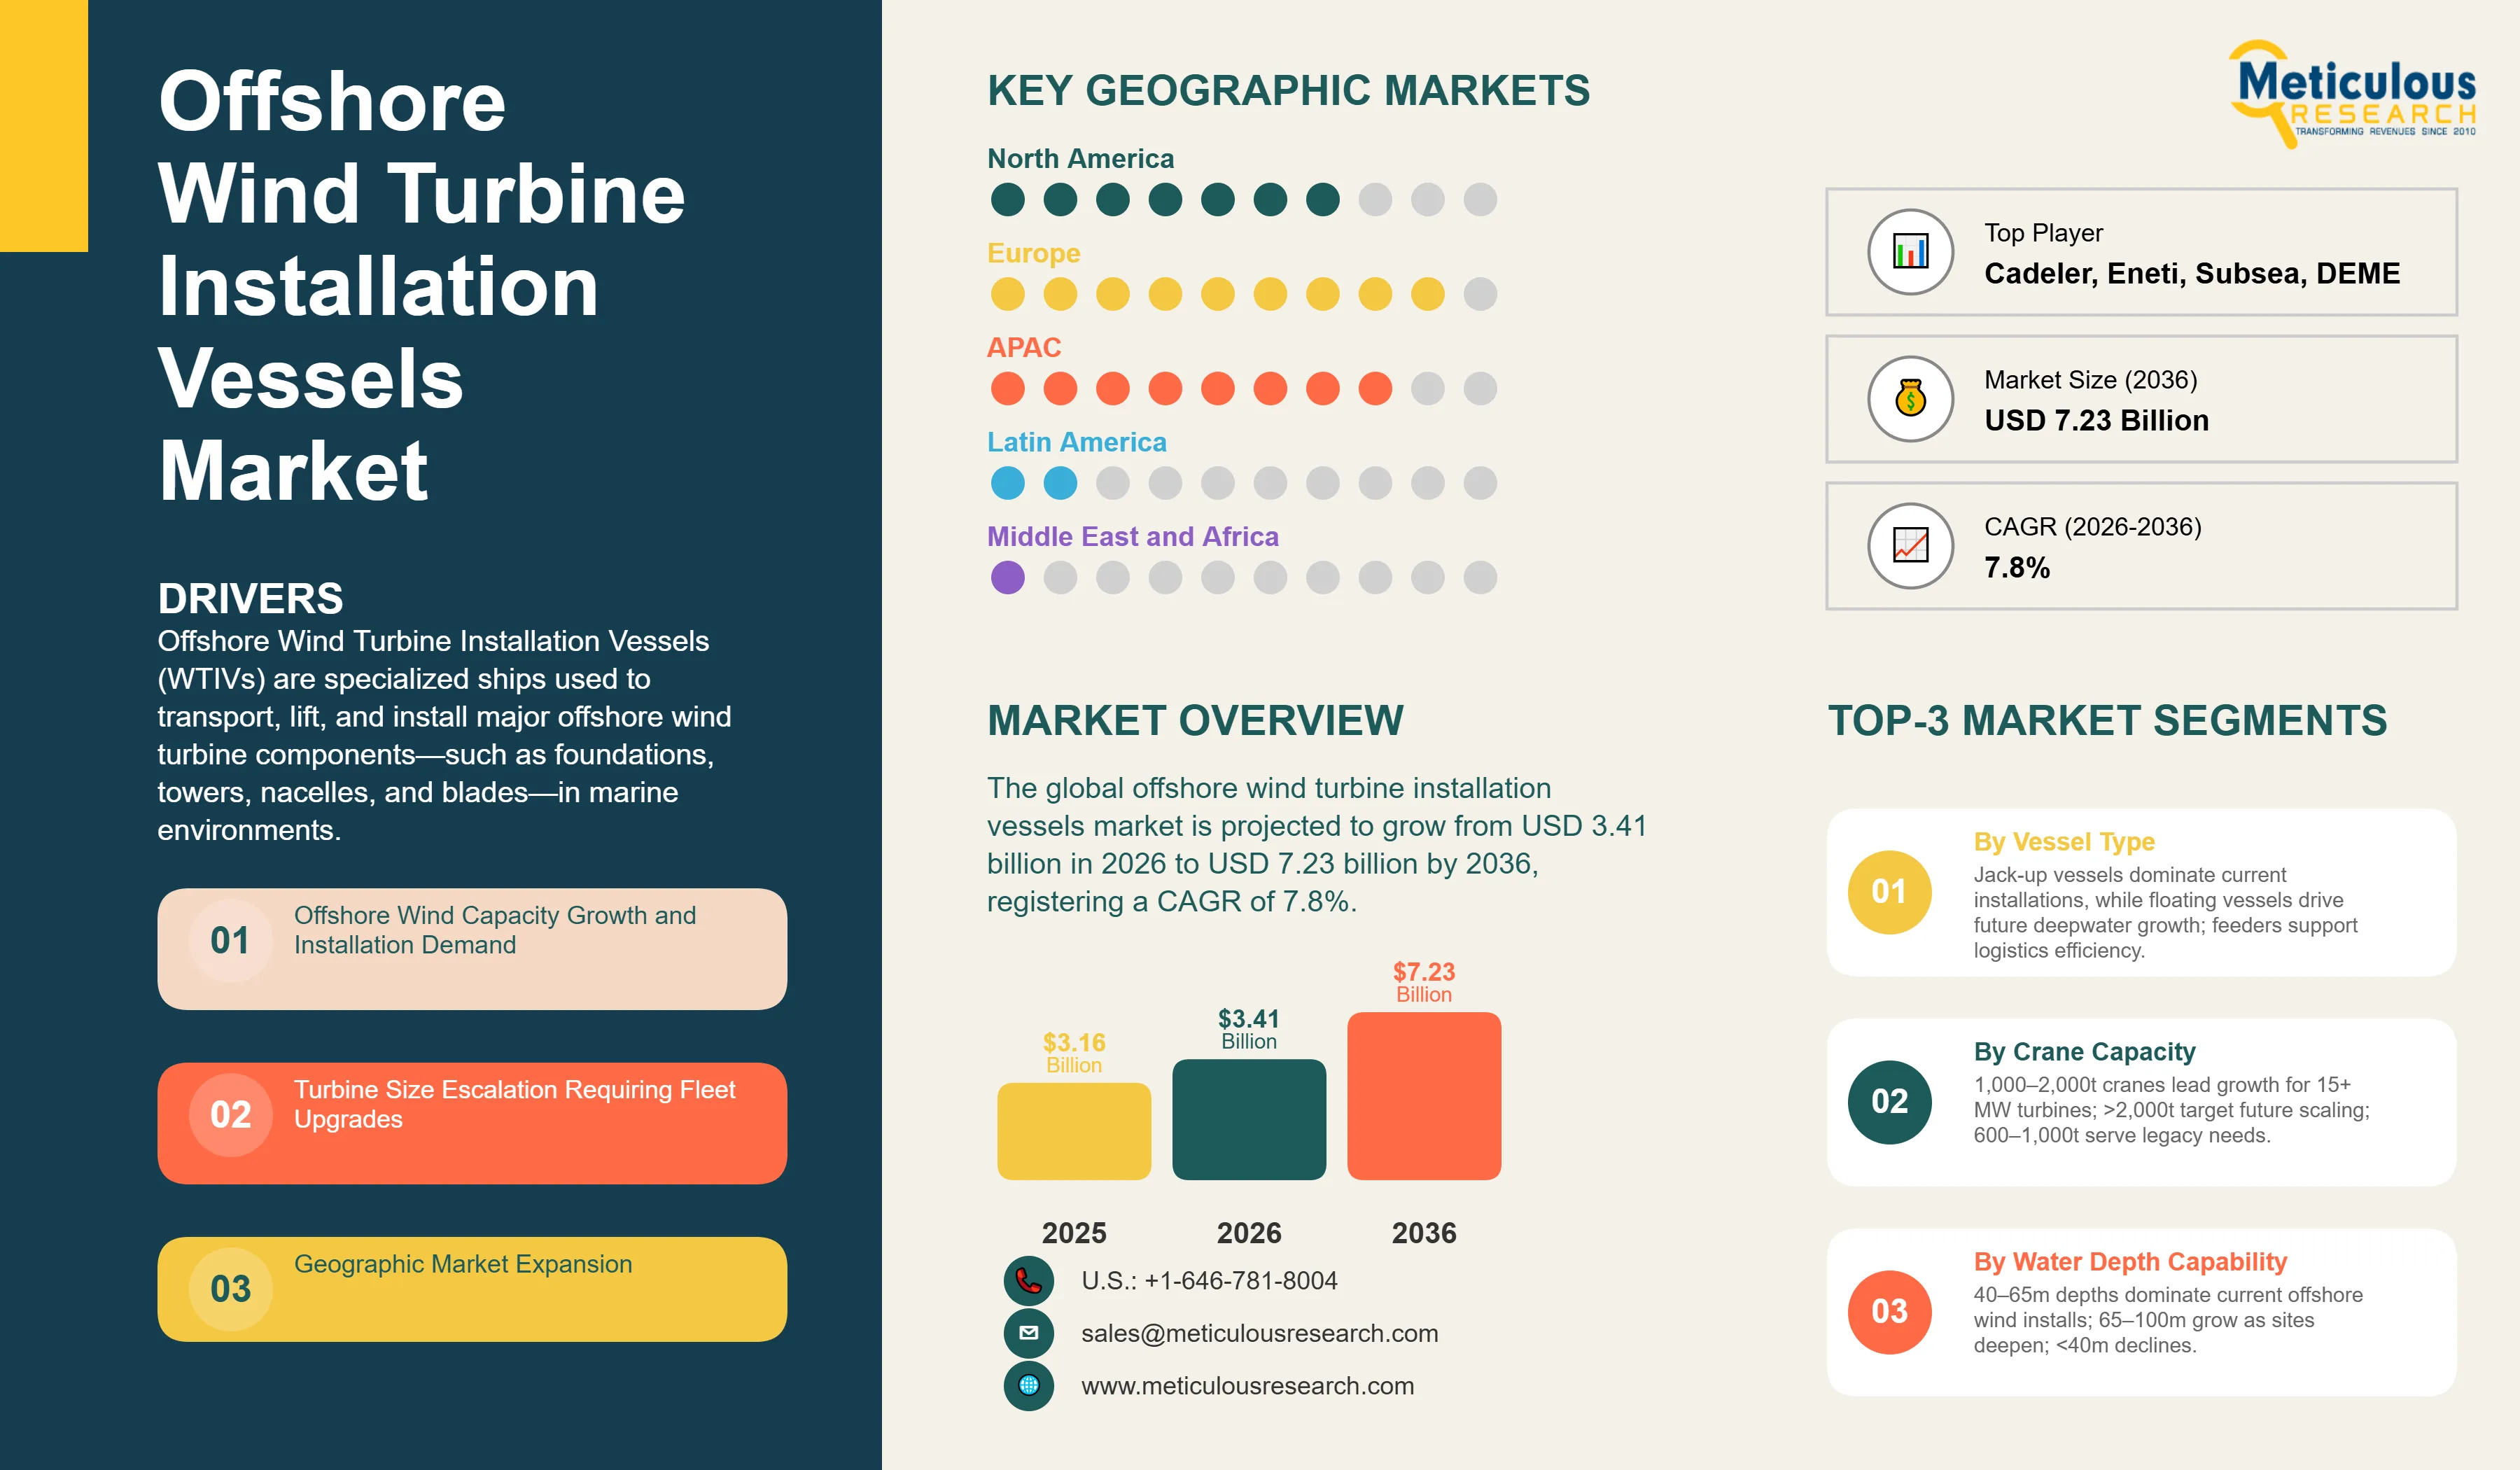
The global offshore wind turbine installation vessels market is expected to reach USD 7.23 billion by 2036 from USD 3.41 billion in 2026, at a CAGR of 7.8% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 291
- Format
- PDF + Excel
- Report ID
- MREP - 1041692
- Base year
- 2025
- 2026 · ESTIMATED
- $3.41B
- 2036
- $7.23B
- CAGR 2026–2036
- 7.8%
2025 baseline · 2026–2036 forecast at 7.8% CAGR · hover a bar for the value
Key highlights
In 2026, Europe is estimated to account for the largest share of the global offshore wind turbine installation vessels market, driven by the most mature offshore wind industry, extensive North Sea and Baltic Sea projects, large existing WTIV fleet, and aggressive offshore wind expansion targets under European Green Deal.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by massive offshore wind capacity additions in China and Taiwan, growing markets in Japan, South Korea, and Vietnam, government offshore wind targets, and expanding domestic WTIV construction capabilities.
Based on vessel type, the jack-up installation vessels segment is estimated to hold the largest share of the market in 2026, driven by suitability for majority of current offshore wind water depths (0-65 meters), proven technology with extensive operational track record, and large existing fleet deployed globally.
Based on crane capacity, the 1, 000-2,000 tonne segment is expected to witness the highest growth during the forecast period, driven by turbine size growth requiring larger lifting capacity, next-generation turbines (15-20 MW) demanding higher-capacity cranes, and fleet modernization replacing older vessels.
Based on water depth capability, the 40-65 meter depth segment dominates the market in 2026, representing the predominant offshore wind installation depth range for current European and Asian projects and jack-up vessel operational sweet spot.
The floating installation vessels segment is expected to grow at a significant CAGR during the forecast period, driven by deepwater offshore wind development beyond jack-up operational limits, floating wind technology advancement, and projects in Pacific deep waters off Japan, U.S. West Coast, and Mediterranean.
The >2,000 tonne crane capacity segment is experiencing rapid growth, driven by ultra-large turbines exceeding 18 MW requiring extreme heavy-lift capabilities and new-generation WTIVs being purpose-built for future turbine sizes.
The U.S. offshore wind turbine installation vessels market is projected to grow at a CAGR of around 15% during the forecast period 2026 to 2036, driven by East Coast offshore wind development exceeding 30 GW planned capacity, Jones Act requirements driving domestic WTIV construction, and government Inflation Reduction Act incentives.
China is expected to lead the Asia-Pacific offshore wind turbine installation vessels market, driven by the world's largest offshore wind capacity (50+ GW installed, 100+ GW targeted by 2030), extensive domestic WTIV fleet development, and government support for maritime equipment manufacturing.
In 2026, the Netherlands is projected to account for significant share of the European WTIV market, driven by major vessel operators including Van Oord and Boskalis, strategic North Sea position, and role as offshore wind installation hub for European projects.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 3.41 Billion |
| Revenue Forecast in 2036 | USD 7.23 Billion |
| Growth Rate | CAGR of 7.8% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 291 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, trends |
| Segments Covered | Vessel Type, Crane Capacity, Deck Space, Water Depth Capability, Application, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Netherlands, Belgium, Denmark, Norway, China, Taiwan, Japan, South Korea, Vietnam, India, Brazil, Australia |
| Key Companies Profiled | Van Oord, Jan De Nul Group, DEME Offshore, Fred. Olsen Windcarrier, Seajacks UK Limited, Cadeler A/S, COSCO Shipping Heavy Industry, China State Shipbuilding Corporation (CSSC), Huisman Equipment B.V., Heerema Marine Contractors, GeoSea (DEME), Sapura Energy Berhad, Pacific Orca Energy, Great Lakes Dredge & Dock, Keppel Offshore & Marine, Lamprell plc, Sembcorp Marine, Eneti Inc., Maersk Supply Service, Subsea 7 |
Report overview
Segments covered: vessel type, crane capacity, water depth capability, deck space, water depth capability-.
Offshore Wind Turbine Installation Vessels (WTIVs) are specialized maritime vessels designed and equipped to transport, lift, and install large offshore wind turbine components including foundations, transition pieces, towers, nacelles, and rotor blades in marine environments. These sophisticated vessels incorporate advanced capabilities including heavy-lift crane systems with capacities exceeding 1,000-3,000 tonnes for next-generation turbines, dynamic positioning systems maintaining precise vessel positioning in deep water, jack-up legs enabling self-elevating platforms creating stable work platforms above wave action in shallow to medium depths, large deck spaces accommodating multiple turbine sets (foundations, towers, nacelles, blades), motion compensation systems allowing safe lifting operations in moderate sea states, and accommodation facilities housing 60-150+ personnel including installation crews, client representatives, and support staff. By providing stable offshore platforms for precision heavy-lift operations, these vessels enable the offshore wind industry to install increasingly large turbines in progressively deeper waters farther from shore, addressing the fundamental challenge that offshore wind components—modern turbines exceed 15 MW with rotor diameters over 240 meters and total weights exceeding 2,000 tonnes—cannot be installed using conventional marine equipment, requiring purpose-built vessels representing investments of $200-500 million each.
Offshore Wind Turbine Installation Vessels represent critical enabling infrastructure for the global offshore wind industry, addressing the fundamental engineering challenge that wind turbines installed in ocean environments—often 20-100 kilometers from shore in water depths of 20-60 meters—require specialized heavy-lift capabilities far exceeding conventional marine construction equipment. These purpose-built vessels serve as mobile offshore construction platforms, transporting turbine components weighing hundreds to thousands of tonnes, positioning precisely at installation sites, elevating themselves above wave action to create stable work platforms, and executing precision lifts placing components with millimeter accuracy despite challenging marine conditions. The vessels' capabilities directly enable or constrain offshore wind deployment—insufficient WTIV availability or capability creates bottlenecks limiting installation pace, while advanced vessels enable larger turbines in deeper waters expanding developable offshore wind resources.
Several transformative trends are reshaping the WTIV market, including the relentless scaling of offshore wind turbines from 6-8 MW in 2015 to 15-18 MW today and 20+ MW under development requiring continuously upgraded vessel capabilities, the expansion into deeper waters beyond traditional jack-up operational limits driving floating vessel and floating turbine development, the globalization of offshore wind beyond European heartland to U.S. East Coast, Asia-Pacific, and emerging markets creating demand in new regions, the emergence of Jones Act-compliant U.S. vessel construction addressing domestic content requirements, and the integration of advanced technologies including dynamic positioning, motion compensation, and digital twins optimizing installation operations. The convergence of offshore wind industry explosive growth—global capacity projected to exceed 380 GW by 2030 from 70 GW in 2023—turbine size escalation, geographic market expansion, and technology advancement has elevated WTIVs from specialized niche equipment to strategic assets commanding day rates of $150,000-300,000+ and representing multi-hundred-million-dollar investments.
The WTIV market is experiencing rapid evolution driven by turbine scaling requiring continuously upgraded vessel capabilities. Modern offshore wind turbines have grown from 4-6 MW with 120-meter rotor diameters in early 2010s to 15-18 MW with 240+ meter rotors today, with 20+ MW turbines under development. This relentless scaling drives WTIV requirements including crane capacities increasing from 600-800 tonnes to 1,500-3,000+ tonnes to lift heavier nacelles and foundation components, deck space expanding from 2,000-3,000 m² to 5,000+ m² accommodating larger components, leg length and depth capability increasing to support installation in deeper waters, and jacking systems and structural reinforcement handling increased vessel and cargo weights. The industry faces continuous upgrade cycle as existing vessels become undersized for next-generation turbines, driving newbuild vessel construction and creating market opportunities for shipyards and vessel operators.
Jack-up installation vessels remain dominant technology for majority of offshore wind installations, employing self-elevating platforms with retractable legs that extend to seabed, jacking the vessel hull above water creating stable elevated platform immune to wave motion. This technology suits shallow to medium water depths typically 10-65 meters covering majority of current offshore wind sites including North Sea, Baltic Sea, U.S. East Coast, and Asian shallow waters. Modern jack-up WTIVs represent engineering marvels including leg lengths exceeding 100-120 meters, lifting capacities of 1,000-3,000 tonnes, deck areas of 4,000-6,000+ m², and capabilities to operate in sea states up to significant wave heights of 1.5-2.5 meters. Leading vessels include Van Oord's Aeolus (50m depth, 1,600t crane), Jan De Nul's Voltaire (80m depth, 3,000t crane), and CSSC's newbuilds for Chinese market. The technology limitations include water depth constraints (practical maximum ~65-70m), seabed soil requirements (legs must penetrate and stabilize), and weather sensitivity during jacking operations.
Floating installation vessels are emerging technology addressing deepwater installations beyond jack-up operational limits. These vessels employ either specialized crane vessels with dynamic positioning or purpose-designed heavy-lift vessels, maintaining position through GPS-controlled thrusters rather than seabed contact. Floating vessels enable installations in water depths exceeding 60-70 meters where jack-ups become impractical, critical for projects including floating offshore wind in Pacific deep waters, fixed-bottom turbines in transitional depths 60-80 meters, and locations with challenging seabed conditions unsuitable for jack-up legs. The technology faces challenges including motion compensation requirements for safe heavy-lift operations from floating platform, weather window restrictions to acceptable sea states, and typically lower productivity than jack-ups requiring more installation time per turbine. However, for deep-water locations—increasingly important as prime shallow-water sites are utilized—floating installation capabilities are essential. Key players developing floating WTIV capabilities include Huisman, Heerema, and Asian yards constructing specialized vessels.
Crane capacity escalation represents critical WTIV specification trend. Early offshore wind installation employed cranes of 400-600 tonnes adequate for 3-4 MW turbines. Current-generation vessels feature 1,000-1,600 tonne cranes serving 12-15 MW turbines. Next-generation vessels under construction incorporate 2,000-3,000 tonne cranes anticipating 18-25 MW turbines under development. Jan De Nul's Voltaire (3,000t crane capacity) and CSSC's newbuilds (2,000-2,500t) exemplify this trend. The crane capacity requirements are driven by nacelle weights exceeding 600-800 tonnes for 15+ MW turbines, foundation components reaching 1,500+ tonnes for larger monopiles or jackets, and transition piece assemblies weighing 500-700 tonnes. The escalation creates technical challenges including crane structural design supporting extreme loads while minimizing weight, vessel stability maintaining safe operations with heavy lifts at significant heights (100+ meters), and construction costs as crane systems represent 25-35% of vessel capital expense.
Geographic market expansion is driving WTIV demand growth and fleet redeployment. Historically concentrated in European waters (North Sea, Baltic Sea, Irish Sea), offshore wind is expanding to U.S. East Coast (30+ GW planned), China (100+ GW targeted), Taiwan (15+ GW), Japan (deepwater floating projects), South Korea, Vietnam, and other markets. This geographic expansion creates opportunities and challenges including regional vessel demand supporting multiple simultaneous projects in new markets, mobilization economics as vessels transit between markets (Europe to Asia: 6-8 weeks transit), regulatory requirements including Jones Act in U.S. mandating domestic-built vessels for domestic waters creating U.S. WTIV construction industry, and local content requirements in various markets favoring regional vessel operators and construction. The globalization trend is driving WTIV fleet expansion from approximately 30-35 active vessels globally in 2020 to 50+ projected by 2027-2028 as newbuilds deliver.
Report infographic
Market dynamics
4 factors across 2 forcesOffshore Wind Capacity Growth and Installation Demand
The explosive global growth of offshore wind capacity creates fundamental demand for installation vessels, with project pipelines translating directly to vessel utilization and day rate revenues. Global offshore wind capacity exceeded 70 GW in 2023 with projections indicating 380+ GW by 2030, requiring installation of thousands of large offshore turbines annually. Each gigawatt of offshore wind capacity typically requires 50-70 turbine installations (depending on turbine size), with installation campaigns employing WTIVs for 6-18 months depending on project scale and offshore conditions. The European offshore wind pipeline exceeds 100 GW through 2030, U.S. East Coast projects exceed 30 GW, Asian markets (China, Taiwan, Japan, Korea, Vietnam) represent 150+ GW, creating sustained multi-year demand for WTIV services.
Turbine Size Escalation Requiring Fleet Upgrades
The continuous increase in offshore wind turbine size and weight creates imperative for vessel fleet modernization, as older vessels become inadequate for next-generation turbines. The industry has transitioned from 6-8 MW turbines in 2015 to 15-18 MW today, with 20+ MW turbines under development. Each turbine generation requires upgraded vessel capabilities—crane capacity, deck space, and structural strength—rendering earlier-generation vessels obsolete for latest projects. This drives newbuild vessel orders as operators compete for contracts installing next-generation turbines commanding premium day rates, creates secondary markets as older vessels serve smaller turbines or enter other markets, and necessitates continuous capital investment maintaining competitive capabilities.
Table of contents
15 chapters · 183 sections · 291 pages · click to expandGeographic analysis
Europe
Largest shareIn 2026, Europe is estimated to account for the largest share of the global WTIV market, driven by most mature offshore wind industry with over 30 GW installed capacity and 100+ GW pipeline through 2030, extensive North Sea and Baltic Sea development with dozens of active projects, large existing WTIV fleet including major operators (Van Oord, Jan De Nul, DEME, Cadeler, Fred. Olsen Windcarrier), established maritime infrastructure and expertise in Netherlands, Belgium, Denmark, Norway, and UK, and aggressive offshore wind expansion targets under European Green Deal and national energy strategies. The Netherlands serves as European offshore wind installation hub with major vessel operators headquartered and vessels registered. The region benefits from deep maritime expertise, supportive regulatory environment, and continuous project flow supporting vessel utilization.
Asia-Pacific
Fastest growthAsia-Pacific is expected to grow at the highest CAGR during the forecast period, driven by China's massive offshore wind capacity exceeding 50 GW installed and targeting 100+ GW by 2030, extensive domestic WTIV fleet development with Chinese shipyards (COSCO, CSSC) constructing 20+ vessels, Taiwan's 15+ GW offshore wind pipeline requiring substantial installation capacity, Japan's floating offshore wind development in deep Pacific waters, South Korea's 12 GW offshore wind targets, Vietnam's emerging sector, and government support for maritime equipment manufacturing. China dominates regional market through domestic capacity and vessel construction, while Taiwan, Japan, and Korea represent growing opportunities. The region benefits from shipyard capacity, government support, and project pipelines creating sustained demand.
North America
North America represents rapidly growing market driven by U.S. East Coast offshore wind exceeding 30 GW planned capacity across federal lease areas from Massachusetts to North Carolina, Jones Act requirements mandating U.S.-built vessels creating domestic WTIV construction industry, first U.S. Jones Act WTIV (Dominion's Charybdis) operational with additional vessels under construction, Inflation Reduction Act incentives supporting offshore wind and vessel investment, and Canadian offshore wind potential particularly in Atlantic provinces. The region faces WTIV shortage in near-term requiring foreign-flagged vessels for some projects (with Jones Act workarounds) while domestic fleet develops, but long-term presents substantial opportunities for vessel operators and shipyards.
Competitive landscape
- Van Oord · Netherlands
- Jan De Nul Group · Belgium
- DEME Offshore · Belgium
- Fred. Olsen Windcarrier · Norway
- Seajacks UK Limited (Eneti Inc.)
- Cadeler A/S · Denmark
- COSCO Shipping Heavy Industry · China
- China State Shipbuilding Corporation/CSSC · China
- Huisman Equipment B.V. · Netherlands
- Heerema Marine Contractors · Netherlands
- GeoSea/DEME · Belgium
- Sapura Energy Berhad · Malaysia
- Pacific Orca Energy (U.S.)
- Great Lakes Dredge & Dock (U.S.)
- Keppel Offshore & Marine · Singapore
- Lamprell plc (UAE)
- Sembcorp Marine · Singapore
- Eneti Inc. · Monaco
- Maersk Supply Service · Denmark
- Subsea 7 (UK)
Frequently asked questions
The offshore wind turbine installation vessels market is expected to grow from USD 3.41 billion in 2026 to USD 7.23 billion by 2036.
Cite this report
Meticulous Research. (2026). Offshore Wind Turbine Installation Vessels Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MREP - 1041692). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/offshore-wind-turbine-installation-vessels-market-6375