Hollow-Core Fiber Market (2026-2036)
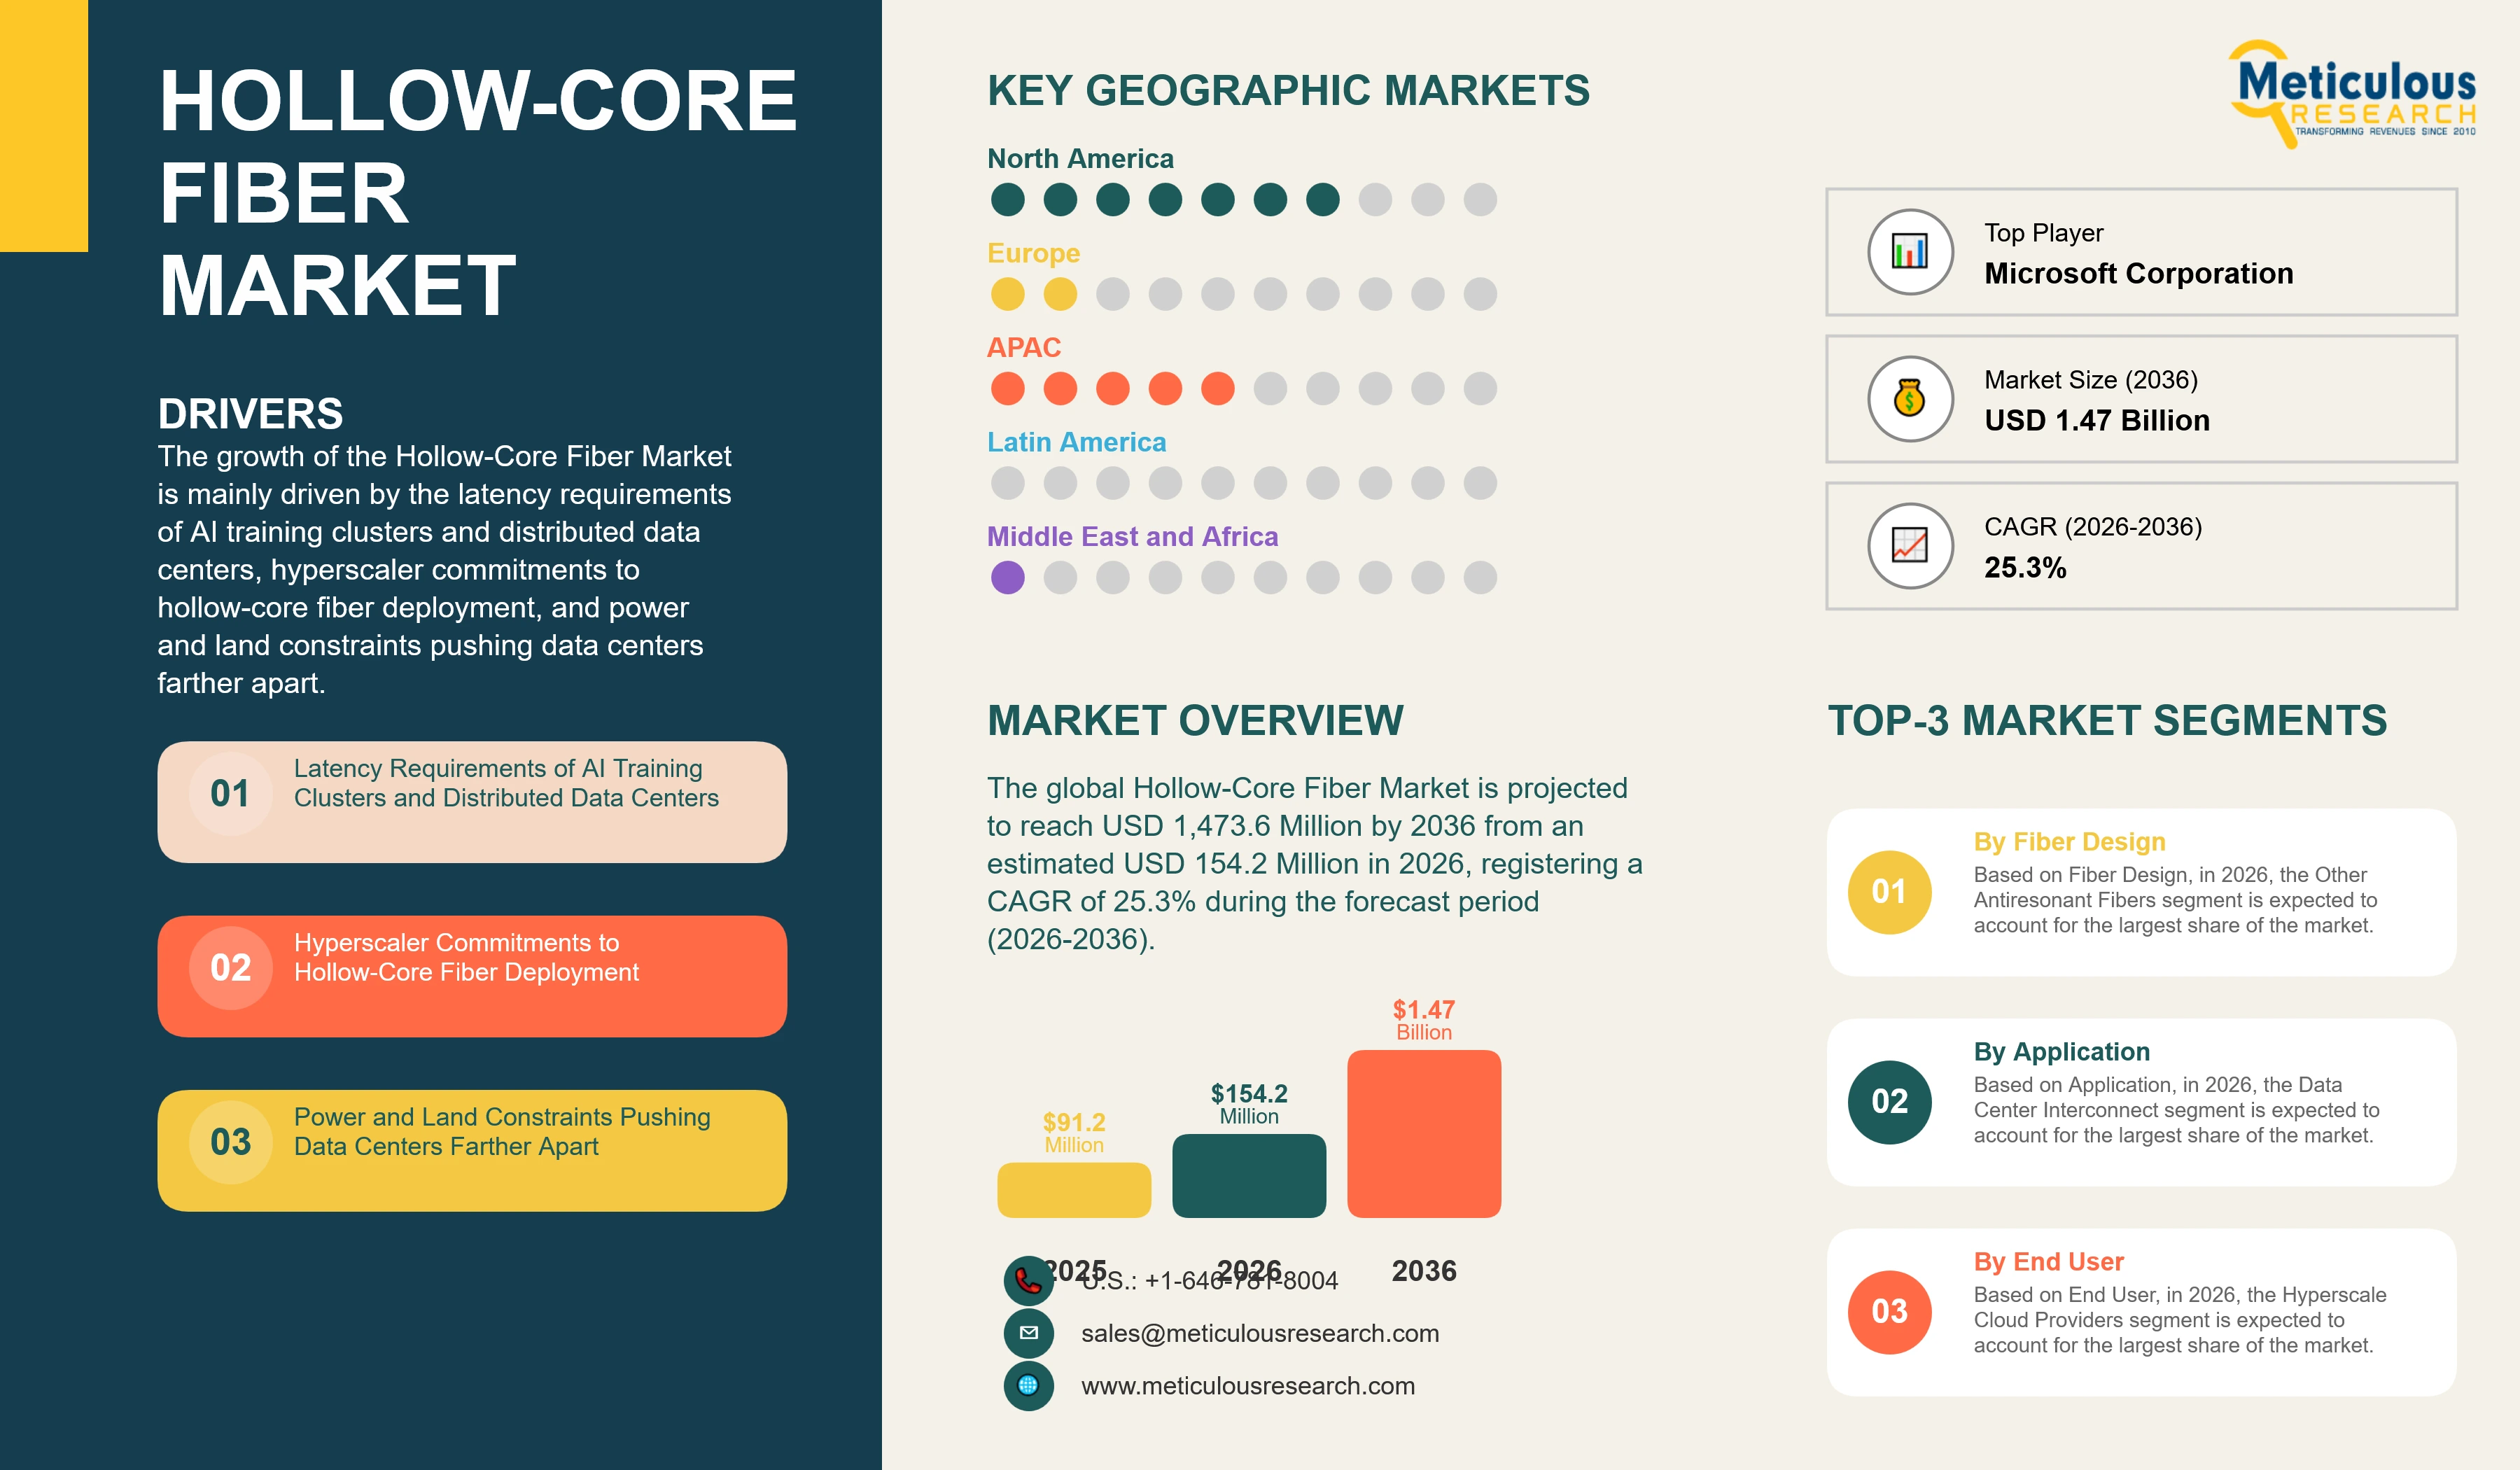
The global Hollow-Core Fiber Market was valued at USD 92.2 million in 2025. This market is expected to reach USD 1,473.6 million by 2036 from an estimated USD 154.2 million in 2026, at a CAGR of 25.3% during the forecast period (2026-2036).
- Published
- Nov 2026
- Pages
- 345
- Format
- PDF + Excel
- Report ID
- MRICT - 1042273
- Base year
- 2025
- 2024 · HISTORICAL
- $40.3M
- 2036
- $1.47B
- CAGR 2026–2036
- 25.3%
2024–2025 baseline · 2026–2036 forecast at 25.3% CAGR · hover a bar for the value
Key highlights
The global Hollow-Core Fiber Market is projected to reach USD 1, 473.6 million by 2036 from an estimated USD 154.2 million in 2026, at a CAGR of 25.3%. The market grew from USD 40.3 million in 2024 to USD 92.2 million in 2025, led by the Microsoft deployment program and by the move of Chinese operators from trials to commercial tenders.
Microsoft announced at Ignite in November 2024 that it would deploy 15, 000 km of hollow-core fiber over 24 months across its Azure network, and it had about 1,200 km in live service by September 2025. Industry estimates quoted by RCR Wireless in July 2026 put hollow-core fiber prices at about USD 3,000 to 5,000 per fiber-km, compared with less than USD 15 for standard fiber.
By fiber design, the other antiresonant fibers segment is expected to account for the largest share of 50.0% of the market in 2026. The double nested antiresonant nodeless fiber (DNANF) segment is projected to register the highest CAGR of 29.0% and to become the largest fiber design by 2036.
By product, the hollow-core cables segment is expected to account for the largest share of 54.0% of the market in 2026 and to register the highest CAGR of 27.0%. Within connectivity & interconnection, splicing & fusion solutions account for 60.0% of the segment, while connectors & interconnect assemblies grow faster, at a CAGR of 25.8%.
By application, the data center interconnect segment is expected to account for the largest share of 56.0% of the market in 2026. The intra-data center & AI cluster interconnect segment is projected to register the highest CAGR of 45.7%, as AI training clusters spread across several buildings.
By end user, the hyperscale cloud providers segment is expected to account for the largest share of 49.0% of the market in 2026. The telecommunications operators segment is projected to register the highest CAGR of 28.2%, led by commercial tenders in China.
North America is expected to account for the largest share of 47.8% of the market in 2026, led by the U.S. Asia-Pacific is projected to register the highest CAGR of 27.2% and to become the largest region by 2036. India is projected to grow at a CAGR of 40.4%, one of the highest among all countries.
Microsoft Corporation led the market in 2025 with an estimated share of 34.6%, followed by Yangtze Optical Fibre and Cable Joint Stock Limited Company (16.3%) and Hamamatsu Photonics K.K. (5.4%). The 16 profiled companies announced 36 verified growth developments between January 2024 and November 2026, led by 14 partnerships.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Historical Years | 2024-2025 |
| CAGR (2026-2036) | 25.3% |
| Format | PDF, Excel & Cloud Portal · 345 pages |
| Market Size in 2025 | USD 92.2 Million |
| Market Size in 2026 | USD 154.2 Million |
| Market Size in 2036 | USD 1,473.6 Million |
| Segments Covered | By Fiber Design: Double Nested Antiresonant Nodeless Fiber (DNANF), Other Antiresonant Fibers, Photonic Bandgap Fibers. By Product: Hollow-Core Fiber, Hollow-Core Cables, Connectivity & Interconnection (Splicing & Fusion Solutions, Connectors & Interconnect Assemblies), Test & Measurement. By Application: Data Center Interconnect, Intra-Data Center & AI Cluster Interconnect, Long-Haul & Metro Networks, Low-Latency Trading, Mobile Fronthaul & Backhaul, Sensing & Specialty (Fiber Sensing & Gyroscopes, High-Power Laser Delivery, Quantum & Research Applications). By End User: Hyperscale Cloud Providers, Telecommunications Operators, Financial Services Firms, Data Center Operators, Research, Defense & Industrial Users. |
| Countries Covered | North America: U.S., Canada. Europe: U.K., Germany, France, Netherlands, Spain, Italy, Nordic Countries, Rest of Europe. Asia-Pacific: China, Japan, South Korea, India, Singapore, Australia, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Chile, Rest of Latin America. Middle East & Africa: UAE, Saudi Arabia, Israel, South Africa, Rest of Middle East & Africa. |
| Key Companies | Microsoft, YOFC, Hamamatsu Photonics, Furukawa Electric, Relativity Networks, FiberHome, Corning, Heraeus, Hengtong, ZTT, Prysmian, HUBER+SUHNER, STL, GLOphotonics, VIAVI, and EXFO. |
Report overview
Segments covered: fiber design, product, application, end user.
The growth of this market is mainly driven by the latency requirements of AI training clusters and distributed data centers, hyperscaler commitments to hollow-core fiber deployment, and power and land constraints pushing data centers farther apart. However, high manufacturing costs and low production yields, an immature splicing, connectivity, and installation ecosystem, and the installed base and low cost of conventional single-mode fiber (SMF) restrain the growth of this market.
Furthermore, long-haul and unrepeatered links with ultralow loss, low-latency networks for financial trading and edge computing, and mobile fronthaul, sensing, and specialty applications are expected to offer growth opportunities for the stakeholders in this market. However, the lack of industry standards, the limited number of qualified suppliers, and the need to ensure long-term reliability in field conditions remain major challenges impacting the growth of this market. Additionally, manufacturing partnerships between hyperscalers and fiber makers, high-density hollow-core cables, records in loss, distance, and capacity, new test and measurement methods, and rising development activity in China and the rest of Asia are prominent trends in this market.
The Hollow-Core Fiber Market covers sales of optical fiber that guides light through a central core filled with air rather than through solid glass, together with the cables, connectivity products, and test equipment built for it. A microstructure of thin glass membranes around the core keeps light inside the hollow core. Market value is measured at manufacturer selling prices and attributed to the country where products are bought and installed, and fiber that Microsoft makes for its own network is valued at a market-equivalent price. Standard and multicore fiber, transceivers and amplifiers, installation labor, and the lasers and sensors that use hollow-core fiber are excluded.
Light travels about 47% faster in air than in silica glass, so hollow-core fiber cuts latency by about one-third compared with standard single-mode fiber. Standard fiber adds about 4.9 microseconds of one-way delay per km, while hollow-core fiber adds about 3.3 microseconds. CCTV News reported in November 2026 that a 1,007 km trial by the China Telecom Research Institute, YOFC, and ZTE had a one-way delay of only 3.43 milliseconds, close to the physical value.
Loss has fallen quickly, which has moved the technology from research to commercial networks. Lumenisity fiber had a loss of about 2.5 dB/km when Microsoft acquired the company in 2022, while Microsoft reported 0.091 dB/km in Nature Photonics in September 2025 and YOFC reported 0.032 dB/km in September 2026. Both values are below the record of about 0.14 dB/km for silica-core fiber, which opens long-haul uses that were not possible with earlier designs.
Competition is concentrated, as only a few companies can make low-loss hollow-core fiber at scale. Microsoft deploys fiber in its own network and has contracted Corning and Heraeus Covantics to make more, while YOFC, FiberHome, Hengtong, and ZTT supply Chinese operators. Furukawa Electric, through Lightera, and Relativity Networks sell cable to other buyers, and VIAVI and EXFO supply test equipment adapted to hollow-core fiber.
This reflects the fast growth of telecommunications operators and the long-haul opportunity from ultralow loss.
This reflects the restraint from high manufacturing costs and the challenge of missing industry standards.
Field Operations Manager, Fiber Installation Contractor, U.K.
This highlights the immature installation ecosystem as a restraint and the demand for splicing, connectivity, and test products.
Report infographic
Market dynamics
14 factors across 4 forcesLatency Requirements of AI Training Clusters and Distributed Data Centers
AI training has made latency between sites more important, as large models are trained across thousands of GPUs and a single cluster is now limited by the power and space of one building. Cloud providers increasingly spread training across several buildings or nearby sites, which must stay within strict latency limits to work as one system. A one-way latency budget of 500 microseconds reaches about 102 km over standard fiber and about 150 km over hollow-core fiber. Microsoft reported in a March 2025 Azure blog that hollow-core fiber carried live customer traffic in several Azure regions, and it said in September 2025 that about 1,200 km was in live service. ZTT reported in May 2026 the first use in China of O-band antiresonant hollow-core fiber for links inside a data center.
Hyperscaler Commitments to Hollow-Core Fiber Deployment
Microsoft announced at Ignite in November 2024 that it would deploy 15,000 km of hollow-core fiber over 24 months across its Azure network, the largest single commitment outside China. It signed manufacturing agreements with Corning and Heraeus Covantics in September 2025, and HUBER+SUHNER announced an investment in hollow-core cable capacity in April 2026. Amazon Web Services is also deploying hollow-core fiber to connect about 10 data centers, according to Fierce Network. Relativity Networks received a USD 40 million follow-on order from a hyperscale customer in August 2026. According to The Motley Fool, Microsoft, Alphabet, Amazon, and Meta spent a combined USD 413 billion on capital expenditure in 2025. Cloud providers can therefore pay a premium for fiber that improves the use of much more costly GPU clusters.
Power and Land Constraints Pushing Data Centers Farther Apart
According to the International Energy Agency (IEA), data centers used about 415 TWh of electricity in 2024, and this is projected to more than double to about 945 TWh by 2030. The IEA also finds that nearly half of U.S. data center capacity sits in five regional clusters, which strains local grids first. Large hubs such as Northern Virginia, Frankfurt, Amsterdam, Dublin, and Singapore face limits on grid power and land, so new AI campuses move to sites far from existing hubs. Hollow-core fiber reaches about 1.5 times as far within a given latency budget, which more than doubles the area in which sites can be placed. Singapore shows this effect, as new capacity moves to Johor in Malaysia and Batam in Indonesia.
Table of contents
12 chapters · 158 sections · 345 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Fiber Design | Other Antiresonant Fibers | DNANF |
| By Product | Hollow-Core Cables | Hollow-core cables |
| By Application | Data Center Interconnect | Intra-Data Center & AI Cluster Interconnect |
| By End User | Hyperscale Cloud Providers | Telecommunications Operators |
By Fiber Design
- The Other Antiresonant Fibers segment is expected to account for the largest share of 50.0% of the market.
- The large share of this segment is mainly due to the large quantities of tubular and nested antiresonant fiber that Chinese makers supply to China Mobile, China Telecom, and China Unicom.
- YOFC alone reported more than 10, 000 fiber-km of cumulative hollow-core delivery by September 2026, and China Telecom Guangdong awarded a CNY 159 million tender to YOFC in August 2026.
- However, the DNANF segment is projected to register the highest CAGR of 29.0% during the forecast period.
- This growth is mainly driven by Microsoft, which uses this design across its Azure network, and by new DNANF capacity at Corning and Heraeus Covantics.
- Microsoft reported a loss of 0.091 dB/km for its DNANF in Nature Photonics in September 2025, below the record for silica-core fiber.
- DNANF is expected to overtake other antiresonant fibers and become the largest fiber design by 2036.
- Photonic bandgap fibers grow at the slowest rate, at a CAGR of 13.4%, as their higher loss limits their use to short links and specialty applications.
- Specialty makers such as NKT Photonics, which Hamamatsu Photonics acquired in May 2024, supply photonic bandgap fiber for lasers, gyroscopes, gas sensing, and research.
By Product
- The Hollow-Core Cables segment is expected to account for the largest share of 54.0% of the market.
- The large share of this segment is mainly due to the fact that most hollow-core fiber reaches buyers as finished or hybrid cable.
- Cloud providers deploy finished cable on their routes, and Chinese operators buy hollow-core fiber through cable tenders, mostly as hybrid cables with a few hollow-core fibers next to many standard fibers.
- This segment is also projected to register the highest CAGR of 27.0% during the forecast period.
- This growth is mainly driven by high-count and small-diameter designs, such as the 24-fiber, 10 mm cable that Prysmian and Relativity Networks tested in July 2026, and by the hybrid cable that STL launched in India in March 2026.
- Within connectivity & interconnection, splicing & fusion solutions account for 60.0% of the segment in 2026, while connectors & interconnect assemblies grow faster, at a CAGR of 25.8%, as pre-terminated assemblies become the preferred option inside data centers.
- Bare hollow-core fiber grows at a CAGR of 23.7%, slightly below the market average, as most fiber reaches buyers inside finished cable.
- Test & measurement grows at the slowest rate, at a CAGR of 16.9%, as installers and operators buy instruments once and reuse them across many routes.
By Application
- The Data Center Interconnect segment is expected to account for the largest share of 56.0% of the market.
- The large share of this segment is mainly due to the use of hollow-core fiber by Microsoft and Amazon Web Services to link data centers within cloud regions, where it extends the distance between sites without breaking latency limits.
- HKT also announced in July 2026 a 3.2 Tbps AI DCI route in Hong Kong using hollow-core cable from YOFC.
- However, the Intra-Data Center & AI Cluster Interconnect segment is projected to register the highest CAGR of 45.7% during the forecast period.
- This growth is mainly driven by AI training clusters that spread across several buildings on one campus.
- ZTT reported in May 2026 the first use in China of hollow-core fiber for links inside a data center, which shows that the technology is moving into shorter, high-capacity links.
- Long-haul & metro networks form the second-largest application and grow at a CAGR of 29.5%, led by Chinese operators.
- Within sensing & specialty, high-power laser delivery accounts for the largest share of 40.0% in 2026, while fiber sensing & gyroscopes grow the fastest, at a CAGR of 16.7%.
- Mobile fronthaul & backhaul grows from a small base, at a CAGR of 37.2%, as prices fall.
By End User
- The Hyperscale Cloud Providers segment is expected to account for the largest share of 49.0% of the market.
- The large share of this segment is mainly due to the size of the Microsoft deployment program and the growing use of hollow-core fiber by other U.S. cloud providers.
- Relativity Networks received a USD 40 million follow-on order from a hyperscale customer in August 2026, and VIAVI stated in January 2026 that its test solution had been validated with three hyperscale customers.
- However, the Telecommunications Operators segment is projected to register the highest CAGR of 28.2% during the forecast period.
- This growth is mainly driven by Chinese operators, which awarded commercial tenders in 2025 and 2026, and by trials at e&, Colt, and other operators.
- Data center operators grow at a CAGR of 26.8%, as companies such as Digital Realty and Scala Data Centers test hollow-core links between their sites.
- Research, defense & industrial users grow at the slowest rate, at a CAGR of 15.0%, as their demand is tied to specialty fiber rather than network buildouts.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of 47.8% of the global Hollow-Core Fiber Market. The large share of this region is mainly due to the hyperscale programs of Microsoft and Amazon Web Services, which were the first to deploy hollow-core fiber at scale. Data center electricity use in the U.S. reached 176 TWh in 2023, according to the U.S. Department of Energy and Lawrence Berkeley National Laboratory, which pushes new AI campuses away from crowded hubs. The U.S. accounts for 96.0% of the regional market in 2026, supported by a growing supply base that includes Corning, Relativity Networks, VIAVI, and the new capacity of Heraeus Covantics. Canada grows faster, at a CAGR of 28.2%, supported by its Sovereign AI Compute Strategy. Mexico grows the fastest, at a CAGR of 28.5%, after AWS opened its Mexico (Central) region in Querétaro in January 2025. North America
Europe
Europe is expected to account for a share of 12.6% of the market in 2026 and to grow at a CAGR of 26.7%. Europe is the birthplace of modern hollow-core fiber, as the DNANF design was developed at the Optoelectronics Research Centre of the University of Southampton. The region also hosts key suppliers, as Prysmian draws fiber in Eindhoven, HUBER+SUHNER is adding cable capacity in Switzerland, and NKT Photonics and GLOphotonics supply specialty fibers. The U.K. is the largest market in the region, led by early trading routes of euNetworks, while Italy grows the fastest, at a CAGR of 29.5%. New cloud investments, such as the EUR 15.7 billion that AWS plans to invest in Spain through 2033, add future demand. Europe
Asia-Pacific
Fastest growthAsia-Pacific is expected to account for a share of 37.8% of the market in 2026 and to register the highest CAGR of 27.2% during the forecast period. China accounts for 86.0% of the regional market, as operators moved from trials to commercial hollow-core tenders in 2025 and 2026 and YOFC, FiberHome, Hengtong, and ZTT supply most demand. China is also building eight national computing hubs under its East Data, West Computing project, which link distant data centers to eastern demand. India grows at a CAGR of 40.4%, supported by the IndiaAI Mission, and Asia-Pacific is expected to become the largest region by 2036. Asia-Pacific
Latin America
Latin America is expected to account for a share of 0.8% of the market in 2026 and to grow at a CAGR of 26.4% during the forecast period. Scala Data Centers, Lightera, and Nokia completed a hollow-core proof of concept in São Paulo in November 2025 and reported a 32% reduction in latency. Brazil is the largest market in the region, supported by the REDATA tax regime for data center equipment. Latin America
Middle East & Africa
The Middle East & Africa is expected to account for a share of 1.0% of the market in 2026 and to grow at a CAGR of 26.2% during the forecast period. e& and ZTT completed the first hollow-core fiber field trial in the Middle East in December 2025 and reported a latency reduction of up to 30%. Large AI programs support future demand. Stargate UAE plans a 1 GW cluster in Abu Dhabi, and HUMAIN targets 1.9 GW of data center capacity in Saudi Arabia by 2030. The UAE is the largest market in the region, while Saudi Arabia grows the fastest, at a CAGR of 28.3%. Middle East & Africa
Competitive landscape
The global Hollow-Core Fiber Market is concentrated, as only a few companies can make low-loss hollow-core fiber at scale, alongside a growing group of cable, connectivity, and test suppliers. In 2025, Microsoft Corporation held an estimated share of 34.6%, followed by Yangtze Optical Fibre and Cable Joint Stock Limited Company (16.3%), Hamamatsu Photonics K.K. (5.4%), Furukawa Electric Co., Ltd. (5.1%), Relativity Networks, Inc. (4.9%), and FiberHome Telecommunication Technologies Co., Ltd. (3.5%), while other players accounted for 30.2%.
Between January 2024 and November 2026, the 16 companies profiled in the report announced 36 verified growth developments related to hollow-core fiber. Partnerships (14) were the most common approach, followed by agreements and contracts (10), product launches (7), expansions (2), investments (2), and acquisitions (1). Partnerships focused on field trials and supply chains, while agreements marked the move to commercial supply, led by the Microsoft manufacturing agreements with Corning and Heraeus Covantics in September 2025. Major deals also include the acquisition of NKT Photonics by Hamamatsu Photonics in May 2024 and the CNY 159 million tender that China Telecom Guangdong awarded to YOFC in August 2026.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Hollow-Core Fiber Market. The key players profiled in the report include Microsoft Corporation (U.S.), Yangtze Optical Fibre and Cable Joint Stock Limited Company (China), Hamamatsu Photonics K.K. (Japan), Furukawa Electric Co., Ltd. (Japan), Relativity Networks, Inc. (U.S.), FiberHome Telecommunication Technologies Co., Ltd. (China), Corning Incorporated (U.S.), Heraeus Holding GmbH (Germany), Jiangsu Hengtong Optic-Electric Co., Ltd. (China), Jiangsu Zhongtian Technology Co., Ltd. (China), Prysmian S.p.A. (Italy), HUBER+SUHNER AG (Switzerland), Sterlite Technologies Limited (India), GLOphotonics SAS (France), VIAVI Solutions Inc. (U.S.), and EXFO Inc. (Canada).
- Microsoft
- YOFC
- Hamamatsu Photonics
- Furukawa Electric
- Relativity Networks
- FiberHome
- Corning
- Heraeus
- Hengtong
- ZTT
- Prysmian
- HUBER+SUHNER
- STL
- GLOphotonics
- VIAVI
- EXFO
Expert perspectives
Hollow-core fiber is moving from early commercial use to large-scale deployment, as cloud providers and Chinese operators place repeat orders. Value is moving from short pilot routes to high-count cables for data center and AI cluster links. Annual growth of 67.2% in 2026 is expected to ease to 14.0% by 2036, as prices per fiber-km fall and the market grows from a larger base.
DNANF is projected to raise its share from 37.0% in 2026 to 49.5% in 2036, and hollow-core cables from 54.0% to 61.6%. Intra-data center & AI cluster interconnect raises its share from 4.0% to 18.0%, and telecommunications operators from 29.0% to 36.5%. Asia-Pacific is projected to raise its share from 37.8% to 44.0%, while the share of North America falls from 47.8% to 40.0%.
For suppliers, the most attractive positions are likely to belong to companies that combine record loss with high yields and long draw lengths. Hybrid and high-count cables, low-loss splicing and connectivity, and published reliability data also offer strong positions. The main risks are slow progress on standards, the small number of qualified suppliers, trade barriers between China and other regions, and price erosion as new capacity starts up.
Customer perspectives
Insights gathered during primary interviews with network architects and procurement managers at cloud providers, telecommunications operators, data center operators, and trading firms highlight where priorities are shifting. Executives at fiber, cable, connectivity, and test equipment makers and at installation contractors were also interviewed. The following perspectives reflect recurring themes raised across these discussions.
Director of Network Architecture, Hyperscale Cloud Provider, U.S.
This reflects the latency requirements of AI clusters and the power and land constraints as drivers, and the large share of data center interconnect.
Cite this report
Meticulous Research. (2026). Hollow-Core Fiber Market - Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRICT - 1042273). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/hollow-core-fiber-market-6956