Geothermal Energy Systems Market (2026-2036)
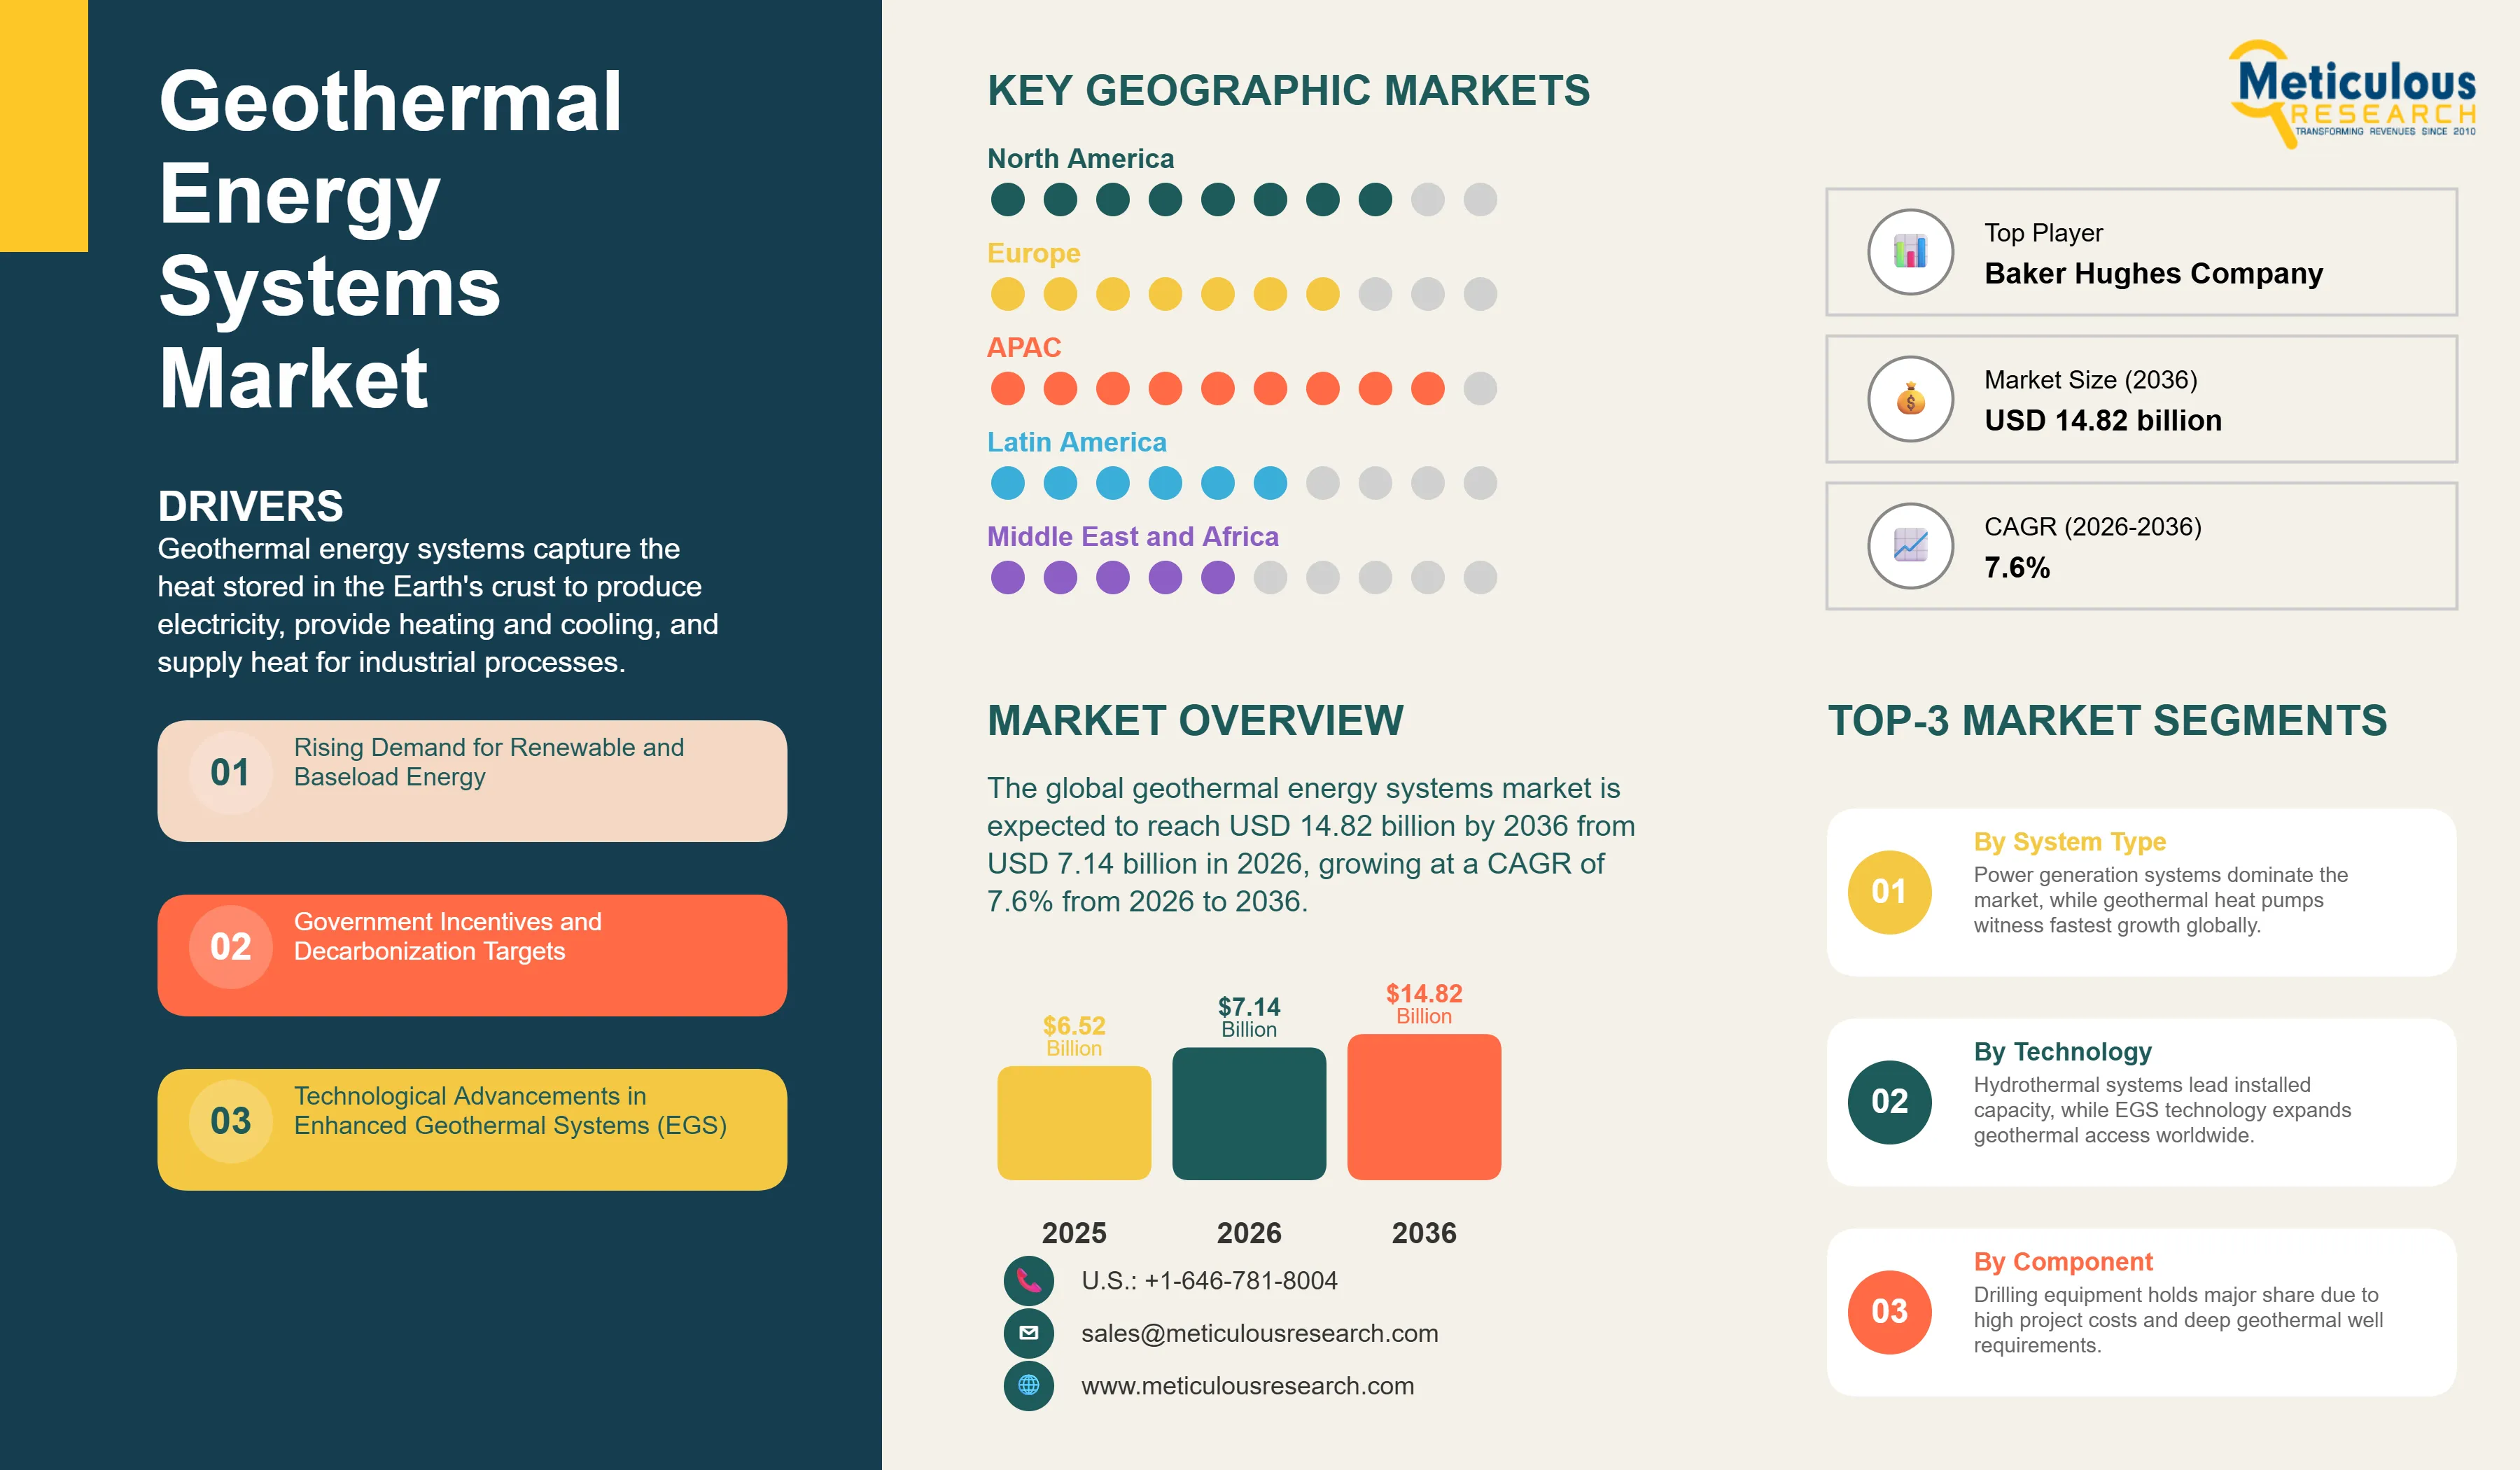
The global geothermal energy systems market was valued at USD 6.52 billion in 2025. This market is expected to reach USD 14.82 billion by 2036 from USD 7.14 billion in 2026, growing at a CAGR of 7.6% from 2026 to 2036.
- Published
- May 2026
- Pages
- 320
- Format
- PDF + Excel
- Report ID
- MR-1989
- Base year
- 2025
- 2025 · BASELINE
- $6.52B
- 2036
- $14.82B
- CAGR 2026–2036
- 7.6%
2025 baseline · 2026–2036 forecast at 7.6% CAGR · hover a bar for the value
Key highlights
The global geothermal energy systems market was valued at USD 6.52 billion in 2025.
This market is expected to reach USD 14.82 billion by 2036 from USD 7.14 billion in 2026, growing at a CAGR of 7.6% from 2026 to 2036.
The power generation systems segment is expected to hold the largest share of the geothermal energy systems market.
The hydrothermal systems segment is expected to have the largest share of the geothermal energy systems market by technology.
The drilling equipment segment is expected to have the largest share of the geothermal energy systems market by component.
The large-scale utility-scale segment is expected to have the largest share of the geothermal energy systems market by deployment mode.
The power generation segment is expected to hold the largest share of the geothermal energy systems market by application.
The utilities and power companies segment is expected to hold the largest share of the geothermal energy systems market.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 14.82 Billion |
| Market Size in 2026 | USD 7.14 Billion |
| Market Size in 2025 | USD 6.52 Billion |
| Market Growth Rate (2026-2036) | CAGR of 7.6% |
| Format | PDF, Excel & Cloud Portal · 320 pages |
| Dominating Region | Asia-Pacific |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | System Type, Technology, Component, Deployment Mode, Application, End User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: system type, technology, component, end user.
In terms of revenue, the global geothermal energy systems market is projected to reach USD 14.82 billion by 2036.
The market is expected to grow at a CAGR of 7.6% from 2026 to 2036.
Asia-Pacific is expected to dominate the global geothermal energy systems market with the largest market share in 2026, driven by Indonesia and the Philippines operating among the world's largest geothermal power fleets, Japan's active geothermal development program supported by policy reform, and the region collectively representing approximately 15% of global EGS technical potential according to the IEA, led by Indonesia and the Philippines.
Asia-Pacific is also expected to witness the fastest growth during the forecast period, driven by IEA projections in its Renewables 2025 report that annual geothermal capacity additions are expected to reach a historic high in 2030, triple the 2024 increase, with Indonesia, Japan, and the Philippines among the key growth markets alongside the United States, Turkey, and Kenya.
By system type, the power generation systems segment is expected to hold the largest share of the overall geothermal energy systems market in 2026, as geothermal power plants represent the highest capital value component of the market and the primary commercial product category across the leading geothermal markets in the United States, Indonesia, Philippines, Kenya, and Italy.
By system type, the geothermal heat pumps segment is expected to witness the fastest growth during the forecast period, driven by the expanding application of shallow ground-source heat pump systems for residential and commercial building heating and cooling across Europe, North America, and Asia, where heating decarbonization policy is accelerating adoption independently of high-temperature geothermal resource availability.
By technology, the hydrothermal systems segment is expected to hold the largest share of the overall geothermal energy systems market in 2026, as conventional hydrothermal resources in high-enthalpy geothermal regions represent the majority of currently installed global geothermal power capacity of 15.4 GW reported by IRENA at end-2024.
By technology, the enhanced geothermal systems segment is expected to witness the fastest growth during the forecast period, as advancing drilling technology and growing government and private investment in EGS demonstration and commercial projects is unlocking geothermal resources in countries and regions previously unable to access conventional hydrothermal energy.
By application, the power generation segment is expected to hold the largest share of the overall geothermal energy systems market in 2026, reflecting the dominant share of geothermal power plant capital equipment and engineering services in total market revenue.
By end user, the utilities and power companies segment is expected to hold the largest share of the overall geothermal energy systems market in 2026, as electric utilities and independent power producers are the primary developers and operators of geothermal power plants and district heating systems globally.
Geothermal energy systems capture the heat stored in the Earth's crust to produce electricity, provide heating and cooling, and supply heat for industrial processes. These resources range from shallow, near-surface temperatures accessible through ground-source heat pumps at depths of just a few meters to a few hundred meters. They also include intermediate hydrothermal reservoirs at depths of 1 to 3 kilometers, where hot water or steam can be extracted for use in flash steam or binary cycle power plants. Additionally, there are deep, high-temperature resources at depths of 5 to 10 kilometers that next-generation enhanced geothermal systems aim to reach. The IEA's report, The Future of Geothermal Energy (2024), states that the global technical potential for enhanced geothermal system (EGS) electricity generation from resources within 8 kilometers of depth is more than 600 terawatts. This potential is almost 600 times greater than that of conventional hydrothermal geothermal and surpasses all renewable electricity sources except solar PV. The United States has the world's largest EGS technical potential at over 70 terawatts, which is about one-eighth of the global total, followed by China with approximately 50 terawatts.
The commercial geothermal energy market is built around five main system types. Power generation systems change geothermal steam or hot water into electricity using dry steam, flash steam, or binary cycle power plant setups. Installed capacities often range from a few megawatts to over 100 megawatts per plant. Direct use systems apply geothermal heat directly for space heating, greenhouse cultivation, aquaculture, industrial drying, and wellness applications without converting it into electricity. District heating systems distribute geothermal hot water through insulated pipelines to serve groups of buildings in urban or rural areas. Geothermal heat pumps rely on the stable shallow ground temperature as a thermal source for efficient heating and cooling of buildings. Enhanced geothermal systems create or improve permeability in hot, dry rock formations through hydraulic stimulation, allowing heat extraction in areas without natural hydrothermal fluid circulation.
The competitive landscape for geothermal energy includes integrated developers and operators like Ormat Technologies and Calpine Corporation. It also involves large energy companies with geothermal divisions such as Enel Green Power and Chevron. There are major engineering and equipment manufacturers like Mitsubishi Heavy Industries, Toshiba, Siemens Energy, and General Electric. Oilfield services companies, such as Baker Hughes, Halliburton, and SLB, bring their drilling expertise to geothermal projects. Nationally significant geothermal operators include KenGen in Kenya, Star Energy Geothermal in Indonesia, and Pertamina Geothermal Energy. According to the IEA's 2024 geothermal report, geothermal energy currently meets over 90% of heating demand in Iceland and makes up a significant portion of electricity supply in El Salvador, New Zealand, Kenya, and the Philippines. This underscores the commercial success of geothermal in countries with high resource quality and highlights the geographic challenges that next-generation technologies aim to address.
Market dynamics
4 factors across 3 forcesGeothermal Energy's Baseload Dispatchability Advantage in Variable Renewable Energy Grids
The main driver of the geothermal energy systems market is the technology's unique feature as a baseload, dispatchable renewable energy source. It can deliver a steady power output at high capacity factors, no matter the weather or time of day. According to the IEA's The Future of Geothermal Energy (2024), geothermal plants operate at capacity factors around 80%. This is much higher than solar PV, which operates at about 15-25%, and onshore wind, at 25-40%. As a result, geothermal acts as a dependable resource that helps balance the grid alongside variable solar and wind output.
As the share of variable renewable energy in power grids increases globally to meet decarbonization goals, the importance of dispatchable clean energy sources rises. This trend creates a growing demand for geothermal power. The IEA's Renewables 2025 report predicts that global renewable capacity will double between now and 2030, with solar and wind making up most of the additions. This rise in variable renewables will boost the need for flexible and baseload clean energy options to keep the grid stable. Geothermal's capability to provide baseload clean power in areas with available resources makes it an increasingly valuable asset as energy systems work toward decarbonization.
Table of contents
14 chapters · 154 sections · 320 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By System Type | Power Generation Systems | Geothermal heat pumps |
| By Technology | Hydrothermal Systems | Enhanced geothermal systems |
| By Component | Drilling Equipment | — |
| By Deployment Mode | Large-scale Utility-scale | Small-scale and distributed systems |
| By Application | Power Generation | Industrial applications |
| By End User | Utilities and Power Companies | Commercial sector |
By System Type
- The power generation systems segment is expected to hold the largest share of the geothermal energy systems market.
- Geothermal power plants are the most expensive installations in the geothermal sector.
- Utility-scale projects need an investment of USD 3 million to USD 8 million for each installed megawatt in conventional hydrothermal plants, and significantly more for next-generation EGS installations.
- The global installed geothermal power capacity of 15.4 GW reported by IRENA at the end of 2024 reflects decades of investment in power plant infrastructure across the United States, Indonesia, Philippines, Kenya, Mexico, Italy, Iceland, and New Zealand.
- Each operational power plant generates ongoing revenue for equipment suppliers and service providers through operations and maintenance contracts, spare parts purchases, and periodic upgrades.
- The main markets for geothermal power generation systems are in countries with the best hydrothermal resources.
- IRENA data shows that geothermal energy covers a large share of national electricity demand, including over 90% of heating in Iceland and significant contributions to grid electricity in Kenya and the Philippines.
- However, the geothermal heat pumps segment is expected to grow the fastest during the forecast period.
- Ground-source heat pump systems use the steady temperature of shallow ground or groundwater as a thermal reservoir for heating and cooling buildings.
- They operate independently of high-temperature geothermal resources, making them available in almost any region.
- The European Union's heat pump policy framework, including strong support from the REPowerEU plan for heat pump deployment to reduce dependence on natural gas for building heating, is driving rapid growth in ground-source heat pump installations across Germany, France, the Netherlands, and Sweden.
- The high energy efficiency, recognized by IRENA as providing three to five units of heating energy for each unit of electrical energy used, combined with compatibility with low-carbon electricity from renewable sources, makes geothermal heat pumps one of the most effective technologies for decarbonizing buildings.
By Technology
- The hydrothermal systems segment is expected to have the largest share of the geothermal energy systems market by technology.
- Conventional hydrothermal systems tap into naturally occurring geothermal reservoirs where hot water or steam is available at exploitable temperatures and flow rates.
- This represents the established technology base of the global geothermal industry and accounts for nearly all of the 15.4 GW of installed geothermal power capacity reported by IRENA at the end of 2024.
- The hydrothermal resource base in countries with high-quality geothermal resources supports large power plants that can operate for 30 to 50 years.
- This generates ongoing revenue from equipment and services at established project sites.
- Countries like the United States, which has the largest geothermal power fleet in the world, along with Indonesia, the Philippines, Kenya, Italy, and Mexico have the most developed hydrothermal resources.
- They are the main demand centers for hydrothermal power plant equipment, well drilling services, and plant operations technology.
- However, the enhanced geothermal systems segment is expected to grow the fastest during the forecast period.
- According to the IEA's The Future of Geothermal Energy (2024), EGS technology could turn geothermal energy from a niche resource into a globally available clean energy source.
- The IEA estimates that EGS has the technical potential to provide nearly 600 TW of capacity from resources within 8 km depth.
- They also estimated that with the right policy support, EGS costs could drop by 80% by 2035 to around USD 50 per MWh, making it one of the cheapest sources of dispatchable low-emissions electricity.
- The U.S. Department of Energy's Enhanced Geothermal Shot initiative and the DOE-funded FORGE demonstration site in Utah are producing technical data and reducing drilling costs.
- This will help commercialize EGS at scale during the forecast period.
By Component
- The drilling equipment segment is expected to have the largest share of the geothermal energy systems market by component.
- Drilling makes up the largest cost in a geothermal project, usually accounting for 30% to 50% of the total project capital cost.
- Therefore, the drilling equipment market captures the biggest share of total geothermal capital spending.
- According to the IEA's The Future of Geothermal Energy (2024), permitting and administrative processes can delay the commissioning of a new geothermal project by up to a decade.
- Drilling cost and performance are the main technical and economic challenges affecting project economics.
- Geothermal wells are drilled to depths of 1 to 5 kilometers for conventional hydrothermal projects and potentially 5 to 10 kilometers for next-generation EGS projects.
- These projects require specialized high-temperature drilling rigs, drill bits designed to handle tough hard rock at high temperatures, and wellbore casing systems rated for extreme downhole conditions.
- Baker Hughes, Halliburton, and SLB are the main providers of drilling equipment and services for the geothermal market.
- They adapt oilfield technology specifically for geothermal use.
- On the other hand, the control systems and monitoring software segment is expected to see the fastest growth during the forecast period.
- The digitalization of geothermal plant operations through better process control systems, real-time monitoring of well and reservoir performance, predictive maintenance analytics, and remote operations management is becoming standard for modern geothermal project development.
- The IEA's 2024 geothermal report pointed out that digital monitoring and optimization is a key trend that helps geothermal operators improve plant availability, optimize heat extraction from reservoirs over long periods, and lower operations and maintenance costs.
- As the EGS segment expands and requires more sophisticated subsurface management compared to conventional hydrothermal operations, the need for advanced monitoring and control software in geothermal applications is projected to grow significantly.
By Deployment Mode
- The large-scale utility-scale segment is expected to have the largest share of the geothermal energy systems market by deployment mode.
- Utility-scale geothermal power plants with a capacity of 10 megawatts and above are the most common form of commercial geothermal energy used worldwide.
- They account for the majority of the 15.4 GW of installed geothermal power capacity reported by IRENA at the end of 2024.
- Utility-scale projects achieve cost savings in drilling, plant construction, and grid connection.
- This makes them the most cost-effective option for high-enthalpy hydrothermal resources where fluid temperature and flow rate are adequate for large installations.
- Major geothermal companies, including Ormat Technologies, Enel Green Power, Calpine, and Pertamina Geothermal Energy, build and operate utility-scale plants typically ranging from 30 to 250 megawatts.
- The largest geothermal complexes in the United States exceed 700 megawatts in total installed capacity.
- However, the small-scale and distributed systems segment is expected to grow the fastest during the forecast period.
- The rise of ground-source heat pump installations in homes and commercial buildings, the development of small binary cycle power plants for distributed power supply in remote communities, and increasing interest in distributed direct-use geothermal heating systems for industrial and agricultural uses are all contributing to growth in the small-scale segment.
- The recognized maturity of geothermal heat pump technology for building applications allows for broad deployment of distributed geothermal systems across various locations.
- This is possible without the high-temperature reservoir requirements that utility-scale power plants have, making small-scale geothermal the most accessible segment of the market.
By Application
- The power generation segment is expected to hold the largest share of the geothermal energy systems market by application.
- Geothermal electricity generation is the most valuable commercial use of geothermal energy.
- It has driven capital investment in geothermal infrastructure worldwide for over a century.
- The IEA's The Future of Geothermal Energy (2024) confirms that geothermal power generation meets a significant portion of electricity demand in Iceland, El Salvador, New Zealand, Kenya, and the Philippines.
- These markets show the commercial reliability and long-term performance of geothermal power systems.
- The IEA's Renewables 2025 report predicts that annual geothermal capacity additions will triple by 2030 compared to the 0.4 GW added in 2024.
- This reflects a positive growth outlook for the power generation application and the demand for related equipment and services.
- However, the industrial applications segment is expected to grow the fastest during the forecast period.
- The decarbonization of industrial process heat is becoming an important growth area for medium-temperature geothermal resources.
- This shift is driven by rising carbon pricing in major industrial economies, corporate commitments to net-zero emissions, and the cost-effectiveness of geothermal heat for energy-intensive industries.
- The IEA's 2024 geothermal report identifies industrial heat decarbonization as a major opportunity for geothermal development.
- Advances in drilling and enhanced geothermal systems technology are increasing the availability of medium-enthalpy geothermal resources at shallower depths.
- This is expanding the geographic reach of geothermal heat that is useful for industrial applications.
By End User
- The utilities and power companies segment is expected to hold the largest share of the geothermal energy systems market.
- Electric utilities and independent power producers are the main developers, owners, and operators of geothermal power plants worldwide.
- They serve as the primary source for purchasing the high-cost equipment, drilling services, and long-term operations and maintenance contracts that make up most of the geothermal market revenue.
- National utilities like KenGen in Kenya operate the largest geothermal power fleet in Africa, with about 863 megawatts of installed capacity at the Olkaria geothermal field.
- Other major operators include state-owned enterprises like Pertamina Geothermal Energy in Indonesia and PNOC Renewables Corporation in the Philippines.
- Private utilities and IPPs, such as Ormat Technologies, Calpine Corporation, and Contact Energy in New Zealand, develop and manage geothermal power assets through long-term power purchase agreements with grid operators.
- However, the commercial sector segment is expected to grow the fastest during the forecast period.
- Commercial buildings, including offices, hotels, retail centers, and institutions, are becoming an important end-user segment for both geothermal heat pump systems and direct-use geothermal district heating connections.
- The increasing sustainability commitments of large commercial real estate owners, along with stricter energy efficiency regulations for commercial buildings in Europe and North America, are driving the purchase of ground-source heat pump systems as a key technology for heating and cooling.
- The high efficiency of geothermal heat pumps, recognized by IRENA, delivers three to five units of heating energy for each unit of electricity used.
- This provides a strong economic and environmental argument for the adoption of geothermal systems in markets where electricity grids are increasingly powered by low-carbon energy.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to have the largest share of the global geothermal energy systems market. This region includes two of the biggest geothermal power producers by installed capacity, Indonesia and the Philippines. It also features Japan's growing geothermal development program and China's increasing use of geothermal heat. Indonesia has some of the most productive high-enthalpy hydrothermal resources along the Pacific Ring of Fire. Pertamina Geothermal Energy and Star Energy Geothermal operate major power complexes there. The Philippines also enjoys excellent hydrothermal resources, with geothermal energy accounting for about 10% of the country's electricity generation. According to IRENA's Renewable Capacity Statistics 2025, New Zealand led geothermal capacity additions in 2024, followed by Indonesia, Turkey, and the United States. IRENA's data from April 2026 confirmed that geothermal added 0.3 GW in 2025, with the Philippines and Indonesia each contributing 0.1 GW of new capacity. The IEA's report, The Future of Geothermal Energy (2024), states that ASEAN countries together represent about 15% of global EGS technical potential, with Indonesia and the Philippines at the forefront of the regional assessment. The IEA's Renewables 2025 report identified Indonesia and the Philippines as two of the six countries expected to drive the planned tripling of annual geothermal additions by 2030, along with the United States, Japan, Turkey, and Kenya.
North America
North America is set to have the second largest regional share of the global geothermal energy systems market by 2026. This is largely due to the United States being the biggest geothermal power market in the world, with the highest installed geothermal capacity of any country. The U.S. has the largest technical EGS potential globally, exceeding 70 terawatts, which is about one-eighth of the total worldwide, according to the IEA's 2024 analysis. This underscores the long-term growth potential of the U.S. geothermal market, which far exceeds its current capacity. The U.S. Department of Energy's Enhanced Geothermal Shot initiative aims to reduce EGS costs to USD 45 per MWh by 2035. Additionally, the DOE-funded FORGE site in Utah is producing key technical data for EGS. The IEA's Renewables 2025 report lists the United States as one of six key markets expected to contribute to the projected tripling of annual geothermal capacity additions by 2030. The Inflation Reduction Act’s investment tax credit for geothermal energy and the production tax credit for geothermal power offer financial incentives that are improving project financing for new geothermal development across the United States. Canada also plays a role in regional demand through geothermal direct-use applications and new power development projects in British Columbia and the western provinces.
Competitive landscape
- Ormat Technologies, Inc.
- Calpine Corporation
- Enel Green Power S.p.A
- Chevron Corporation
- Mitsubishi Heavy Industries Ltd.
- Siemens Energy AG
- Toshiba Energy Systems & Solutions Corporation
- General Electric Company
- Baker Hughes Company
- Halliburton Company
- SLB · Schlumberger
- KenGen (Kenya Electricity Generating Company)
- Contact Energy Ltd.
- Star Energy Geothermal
- Pertamina Geothermal Energy
Frequently asked questions
The global geothermal energy systems market is expected to grow from USD 7.14 billion in 2026 to USD 14.82 billion by 2036.
Cite this report
Meticulous Research. (2026). Geothermal Energy Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1989). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/geothermal-energy-systems-market-6672