Electronic Warfare (EW) Systems Market (2026-2036)
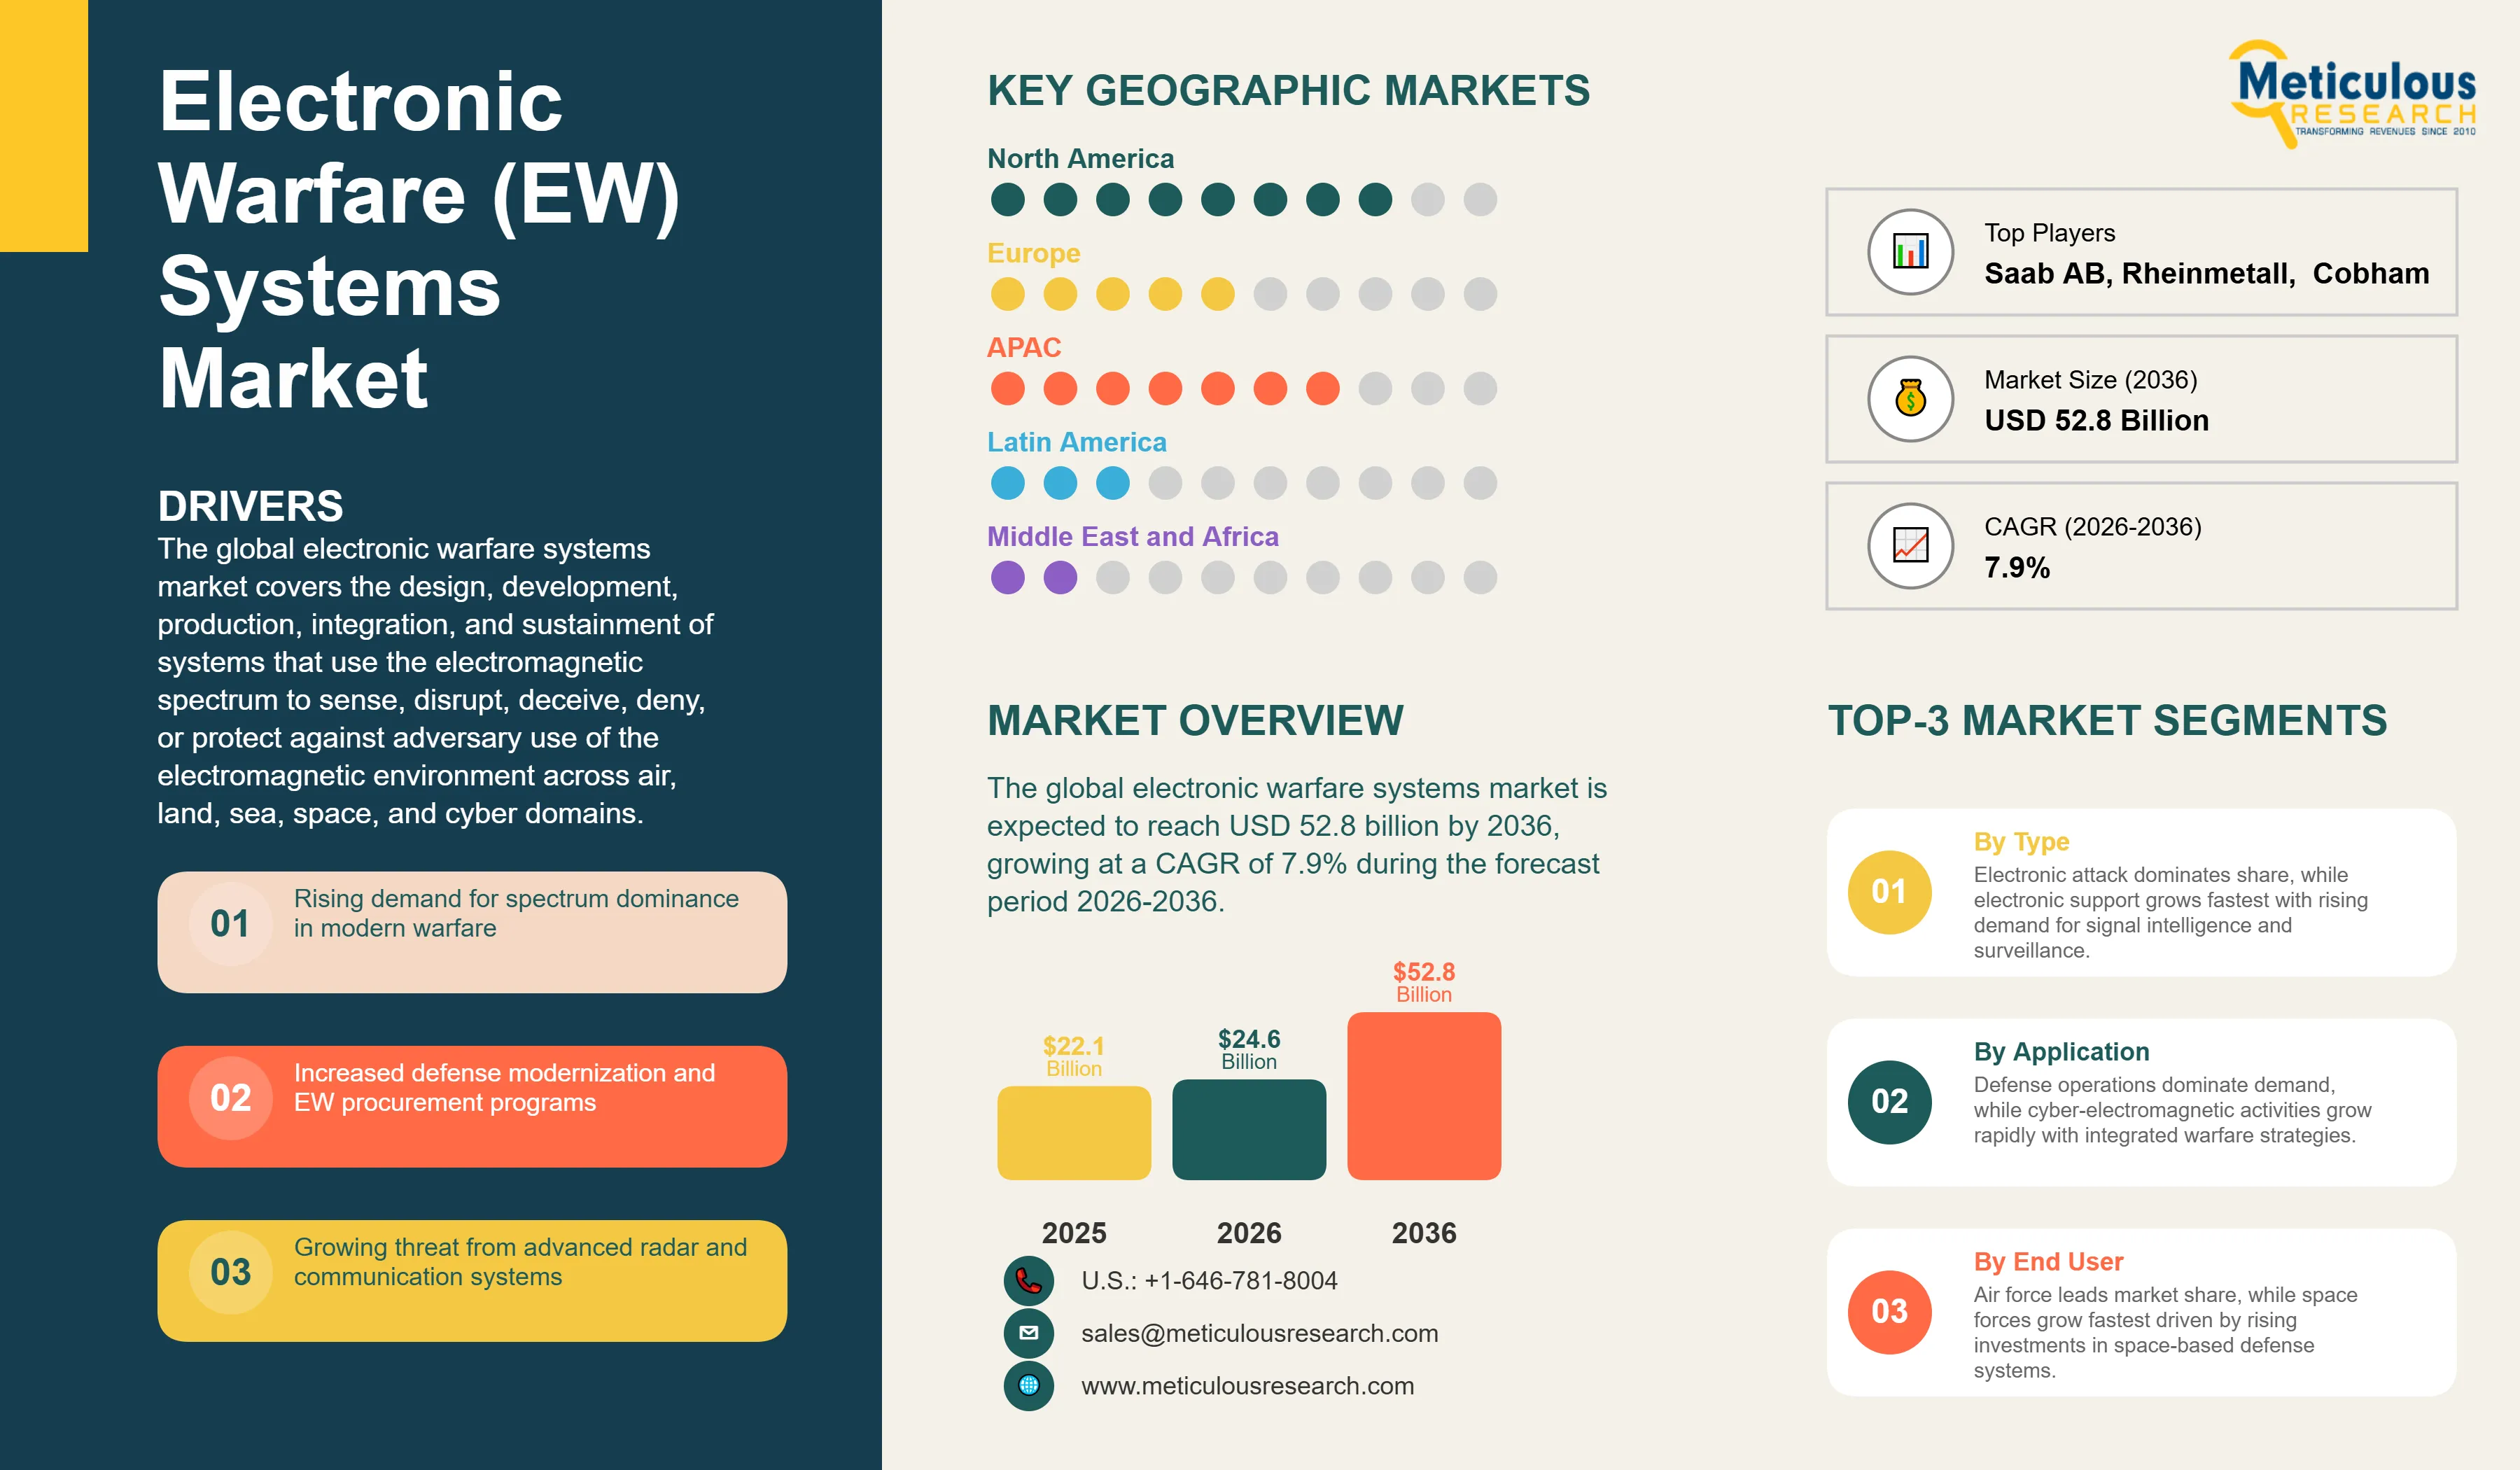
The global electronic warfare systems market was valued at USD 22.1 billion in 2025. This market is expected to reach USD 52.8 billion by 2036 from an estimated USD 24.6 billion in 2026, growing at a CAGR of 7.9% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 272
- Format
- PDF + Excel
- Report ID
- MR-1906
- Base year
- 2025
- 2025 · BASELINE
- $22.10B
- 2036
- $52.80B
- CAGR 2026–2036
- 7.9%
2025 baseline · 2026–2036 forecast at 7.9% CAGR · hover a bar for the value
Key highlights
The global electronic warfare systems market is projected to reach USD 52.8 billion by 2036.
The market is expected to grow at a CAGR of 7.9% during the forecast period 2026-2036.
The global electronic warfare systems market was valued at USD 22.1 billion in 2025 and is estimated to reach USD 24.6 billion in 2026.
North America is expected to dominate the global electronic warfare systems market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By EW type, the electronic attack segment is expected to hold the largest share of the market in 2026, while the electronic support segment is projected to register the highest CAGR during the forecast period.
By platform, the airborne systems segment is expected to hold the largest share in 2026, while the space-based systems segment is projected to register the highest CAGR during the forecast period.
By capability, the radar jamming segment is expected to hold the largest share in 2026, while the signal intelligence segment is projected to register the highest CAGR during the forecast period.
By application, the defense operations segment is expected to hold the largest share in 2026, while the cyber-electromagnetic activities segment is projected to register the highest CAGR during the forecast period.
By end user, the air force segment is expected to hold the largest share in 2026, while the space forces segment is projected to register the highest CAGR during the forecast period.
By level of autonomy, the semi-autonomous systems segment is expected to hold the largest share in 2026, while the fully autonomous and cognitive EW systems segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 52.8 Billion |
| Market Size in 2026 | USD 24.6 Billion |
| Market Size in 2025 | USD 22.1 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 7.9% |
| Format | PDF, Excel & Cloud Portal · 272 pages |
| Dominating EW Type | Electronic Attack (EA) |
| Fastest Growing EW Type | Electronic Support (ES) |
| Dominating Platform | Airborne Systems |
| Fastest Growing Platform | Space-Based Systems |
| Dominating Capability | Radar Jamming |
| Fastest Growing Capability | Signal Intelligence |
| Dominating Application | Defense Operations |
| Fastest Growing Application | Cyber-Electromagnetic Activities |
| Dominating End User | Air Force |
| Fastest Growing End User | Space Forces |
| Dominating Level of Autonomy | Semi-Autonomous Systems |
| Fastest Growing Level of Autonomy | Fully Autonomous/Cognitive EW Systems |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: ew type, platform, capability, application, end user, level of autonomy.
The global electronic warfare systems market covers the design, development, production, integration, and sustainment of systems that use the electromagnetic spectrum to sense, disrupt, deceive, deny, or protect against adversary use of the electromagnetic environment across air, land, sea, space, and cyber domains. This encompasses electronic support systems including signal intelligence, electronic intelligence, and communications intelligence platforms that detect, identify, and geolocate electromagnetic emissions; electronic attack systems including radar jamming, communication jamming, deception systems, and directed energy weapons that disrupt or deny adversary use of the electromagnetic spectrum; and electronic protection systems including anti-jamming receivers, signal encryption platforms, and spectrum management tools that defend friendly forces' electromagnetic operations against adversary electronic attack.
The growth of the global electronic warfare systems market is primarily driven by the demonstrated centrality of electromagnetic spectrum dominance to modern warfare outcomes, evidenced across multiple recent and ongoing conflicts including the Russia-Ukraine war where both sides have deployed extensive jamming, spoofing, and electronic support capabilities that have shaped battlefield outcomes for conventional precision-guided munitions, unmanned aerial systems, and communications systems. The proliferation of advanced radar systems, precision-guided weapons, and anti-access and area-denial architectures by near-peer adversaries including China and Russia is compelling NATO allies and partner nations to invest heavily in EW modernization programs to counter the electromagnetic threat environment that these systems create, driving large-scale acquisition programs across the U.S., European, and Indo-Pacific defense establishments.
Two significant opportunities are shaping the market's long-term trajectory. The development of AI-enabled and cognitive electronic warfare systems that can autonomously sense and adapt to novel electromagnetic threats in real time without requiring pre-programmed responses represents the most technically transformative near-term capability development opportunity, as the speed and complexity of modern electromagnetic threat environments increasingly exceeds the response time and threat library coverage of legacy rule-based EW systems that require manual updates to address new emitter characteristics. The progressive integration of electronic warfare with cyber operations and space domain capabilities within multi-domain operations frameworks is creating a new and expanding category of cyber-electromagnetic activities that demands joint EW and cyber capability development, generating procurement requirements that transcend traditional EW system boundaries and create new market opportunities for vendors with cross-domain electronic and cyber warfare expertise.
Report infographic
Market dynamics
7 factors across 3 forcesRising Electromagnetic Spectrum Warfare Requirements
The primary driver of the global electronic warfare systems market is the rapid escalation of electromagnetic spectrum warfare as a decisive component of modern combat operations, driven by the documented operational impact of advanced EW capabilities in the Russia-Ukraine conflict, the South Caucasus conflicts, and the increasing electromagnetic sophistication of adversary integrated air defense systems, precision-guided weapons, and communications networks that require advanced EW capabilities to counter. Defense establishments across NATO, the Indo-Pacific, and the Middle East are responding to observed electromagnetic threat escalation by substantially increasing EW procurement budgets, accelerating EW modernization programs, and elevating EW operational capability as a top-tier investment priority within constrained overall defense budgets. The U.S. Congress's establishment of the Electromagnetic Spectrum Superiority Strategy in 2020 and the subsequent programmatic investment it has generated, combined with equivalent NATO and partner nation EW prioritization frameworks, are translating strategic policy recognition of EW's operational importance into funded procurement programs that represent the primary near-term revenue driver for the EW systems market.
Expansion of Modernization Programs in Defense Forces
The large-scale defense modernization programs being executed across NATO member states, Australia, Japan, South Korea, India, and Gulf Cooperation Council nations in response to the elevated threat environments created by Chinese and Russian military capability development are generating very large EW system procurement requirements as legacy EW systems designed for Cold War threat environments are replaced with modern capability platforms engineered to counter the advanced radar, communication, and precision-guided weapon systems fielded by near-peer adversaries. The U.S. Army's Electronic Warfare and Cyber program of record, the Air Force's Next Generation Jamming pod development, the Navy's Next Generation Jammer programs, and the Marine Corps' EW modernization collectively represent multi-billion-dollar procurement programs driving the U.S. EW market. European NATO member state defense budget increases following Russia's 2022 invasion of Ukraine, with Germany, Poland, Sweden, Finland, and multiple other nations increasing defense spending above 2% of GDP for the first time in decades, are directly funding EW capability acquisition programs that had been deferred during the post-Cold War defense drawdown period.
Table of contents
15 chapters · 173 sections · 272 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By EW Type | Electronic Attack | Electronic support |
| By Platform | Airborne Systems | Space-based systems |
| By Capability | Radar Jamming | Signal intelligence |
| By Application | Defense Operations | Cyber-electromagnetic activities |
| By End User | Air Force | Space forces |
| By Level of Autonomy | Semi-Autonomous Systems | Fully autonomous and cognitive EW systems |
By EW Type
- Electronic Attack to Dominate
- The electronic attack segment is expected to account for the largest share of the global electronic warfare systems market.
- The large share of this segment is attributed to electronic attack representing the highest-procurement-value EW type category, encompassing airborne jamming systems including the E/A-18G Growler's AN/ALQ-99 and next-generation jamming pod systems, ship-based and land-based jamming systems, and directed energy weapon systems that represent large-scale platform acquisitions and major program-of-record investments across U.S. and allied defense establishments.
- The offensive electromagnetic attack capability represented by electronic attack systems is the highest-priority EW investment for defense forces seeking electromagnetic spectrum dominance, generating the largest individual procurement contract values within the EW market.
- However, the electronic support segment is poised to register the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the rapidly growing operational importance of electronic intelligence and signals intelligence in characterizing adversary electromagnetic order of battle for targeting, electronic warfare support, and intelligence purposes, the large-scale deployment of electronic support capabilities on unmanned aerial systems enabling persistent electromagnetic surveillance missions, and the AI-enhanced signal processing capabilities that are dramatically improving the speed and accuracy of automated signal identification in dense electromagnetic environments.
By Platform
- Airborne Systems to Hold the Largest Share
- The airborne systems segment is expected to account for the largest share of the global electronic warfare systems market.
- Airborne EW systems represent the highest per-platform investment and most operationally critical EW capability category, encompassing dedicated electronic attack aircraft including the EA-18G Growler and Eurofighter EW variants, self-protection jamming suites on fighter and strike aircraft, airborne early warning and electronic intelligence aircraft, and the growing fleet of unmanned aerial systems equipped with electronic support and attack payloads.
- The high value of airborne EW systems relative to other platforms, combined with the broad fleet-wide installation of self-protection EW suites across military aircraft globally, generates the largest segment revenue within the EW market.
- However, the space-based systems segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the U.S. Space Force's growing investment in space domain electromagnetic warfare capabilities, the progressive extension of anti-jamming and satellite protection technology into military satellite constellations, the development of space-based signal intelligence collection systems that monitor terrestrial and space electromagnetic environments from orbital vantage points, and the operational experience of the Russia-Ukraine conflict demonstrating both the strategic value of satellite-based EW capabilities and their vulnerability to adversary electronic attack.
By Capability
- Radar Jamming to Hold the Largest Share
- The radar jamming segment is expected to account for the largest share of the global electronic warfare systems market.
- Radar jamming represents the foundational and highest-priority offensive EW capability for armed forces seeking to defeat adversary integrated air defense systems that use radar to detect, track, and guide weapons against friendly aircraft and missiles.
- The large installed base of airborne jamming systems across tactical and strike aircraft globally, the Next Generation Jammer pod development for the U.S. Navy, and the broad international customer base for radar jamming equipment generate the highest aggregate procurement revenue of any EW capability category.
- However, the signal intelligence segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the rapidly expanding operational requirement for persistent and automated electromagnetic order of battle intelligence, the deployment of signals intelligence capabilities on unmanned aerial systems for persistent surveillance missions, and the AI-enhanced automated signal characterization technologies that are improving the speed and fidelity of signal intelligence collection and analysis in increasingly complex electromagnetic environments.
By Application
- Defense Operations to Hold the Largest Share
- The defense operations segment is expected to account for the largest share of the global electronic warfare systems market.
- Defense operations represent the primary procurement driver and revenue source for EW systems, encompassing the operational requirements of military forces for electromagnetic spectrum control in support of combat air operations, naval warfare, ground force maneuver, and strategic strike missions that have historically generated and continue to generate the largest EW system acquisition programs.
- The broad application of EW across all military operational domains and the universal requirement for both offensive jamming and defensive self-protection capabilities across military platforms reinforces defense operations as the dominant revenue application.
- However, the cyber-electromagnetic activities segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the U.S. Army's Cyber-Electromagnetic Activities doctrine and the equivalent multi-domain operations frameworks of other major military establishments that are driving procurement of integrated cyber-EW capabilities, the growing operational use of electromagnetic capabilities in non-kinetic information operations and electronic warfare campaigns against adversary command-and-control networks, and the emerging market for unified cyber and EW platform solutions that blur the boundary between traditional EW and offensive cyber operations.
By End User
- Air Force to Hold the Largest Share
- The air force segment is expected to account for the largest share of the global electronic warfare systems market.
- Air force customers represent the primary and highest-spending EW end-user category globally, as airborne EW is the operationally most critical and highest-per-platform investment EW category, with electronic attack aircraft, self-protection jamming suites on fighter and strike aircraft, airborne electronic intelligence aircraft, and electronic warfare training assets representing the largest individual program investments in the EW market.
- The U.S. Air Force and U.S. Navy's joint investment in airborne EW through the EA-18G Growler program and the Next Generation Jammer development, combined with equivalent European, Asian, and Middle Eastern air force EW modernization programs, generates the dominant share of global EW procurement value.
- However, the space forces segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the establishment of the U.S. Space Force as a dedicated military service with an explicit electromagnetic warfare mission area, the growing investment of other nations' space commands in satellite protection and space domain electromagnetic operations capabilities, and the operational experience of recent conflicts demonstrating both the strategic value of space-based EW capabilities and the vulnerability of satellite systems to adversary electronic attack that is driving defensive satellite EW investment across major space-faring nations.
By Level of Autonomy
- Semi-Autonomous Systems to Hold the Largest Share
- The semi-autonomous systems segment is expected to account for the largest share of the global electronic warfare systems market.
- Semi-autonomous EW systems that automate specific EW tasks including threat detection, library lookup, and countermeasure recommendation while maintaining human operator approval authority for jamming activation represent the current operational standard across most deployed EW platforms, reflecting the balance between automation speed advantages and the legal, operational, and safety requirements for human oversight of electromagnetic attack decisions.
- The large installed base of semi-autonomous EW suites across military aircraft, naval vessels, and land-based platforms globally establishes this category's market dominance.
- However, the fully autonomous and cognitive EW systems segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the growing operational requirement for machine-speed autonomous response to novel and adaptive electromagnetic threats that exceeds human operator response time capability, the DARPA and Air Force Research Laboratory programs maturing cognitive EW technology toward operational deployment, and the progressive operational testing and evaluation of autonomous EW capabilities that is building the evidence base required for regulatory and doctrinal acceptance of autonomous electromagnetic attack by major military establishments.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global electronic warfare systems market. The largest share of this region is mainly due to the United States' position as the world's largest defense spender and the home of the dominant EW systems development and manufacturing ecosystem, with the U.S. Department of Defense EW investment encompassing the EA-18G Growler electronic attack aircraft program operated jointly by the Navy and Marine Corps, the Next Generation Jammer pod development at Raytheon Technologies, the Army Electronic Warfare program of record including the Electronic Warfare Planning and Management Tool and the TLS-BCT system, and multiple classified EW development programs that collectively represent the largest single-nation EW procurement market globally. The concentration of leading EW prime contractors including Northrop Grumman, L3Harris, BAE Systems' U.S. division, Raytheon Technologies, and Lockheed Martin in the United States, combined with a deep and technically advanced defense electronics subcontractor and component supplier ecosystem, reinforces North America's dual role as the largest EW demand market and primary EW supply base. Canada's growing defense EW investment, driven by NORAD modernization commitments and Northern Warning System replacement programs, contributes additional North American market demand.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific electronic warfare systems market is expected to grow at the fastest CAGR during the forecast period. The region's rapid growth is driven by the escalating military competition between China and the United States and its allies in the Indo-Pacific region, which is driving very large EW modernization investments by Japan, South Korea, Australia, India, and multiple Southeast Asian nations seeking to develop credible electromagnetic deterrence capabilities against China's advanced integrated air defense and anti-access and area-denial systems. China's own very large EW development and acquisition program, reflecting its prioritization of electromagnetic spectrum operations in its military modernization strategy, generates substantial domestic EW procurement through the Chinese defense industrial complex encompassing CASC, CASIC, and affiliated defense electronics enterprises. India's EW modernization under the Defence Acquisition Procedure is generating large indigenous and imported EW system procurement for the Indian Air Force, Indian Navy, and Indian Army. Japan's Multi-Domain Defense Force initiative includes substantial EW capability investment across airborne, maritime, and space domains.
Europe
Europe represents a large and growing EW market, directly stimulated by Russia's demonstrated EW capabilities in Ukraine that have created urgent procurement demand across NATO's European members. Germany's Bundeswehr is investing in EW modernization across its air, land, and naval forces, the UK's defense EW strategy is generating procurement across multiple service branches, France's Armee de l'Air et de l'Espace is modernizing its airborne EW capabilities, and Poland's rapid defense buildup includes major EW system acquisitions. European EW prime contractors including Airbus Defence and Space's EW division, Thales Group, Leonardo, Saab AB's Electronic Defence Systems division, and Rohde and Schwarz collectively represent a strong regional EW supply base serving both domestic and international export markets.
Middle East & Africa
Israel's EW industry, represented by Elbit Systems and Israel Aerospace Industries, supplies advanced EW systems to the Israeli Defense Forces and to international customers across multiple continents, establishing Israel as a disproportionately important EW technology exporter relative to its size in the global market.
Competitive landscape
- BAE Systems plc (UK)
- Northrop Grumman Corporation (U.S.)
- L3Harris Technologies Inc. (U.S.)
- Thales Group · France
- Raytheon Technologies Corporation (U.S.)
- Lockheed Martin Corporation (U.S.)
- Saab AB · Sweden
- Leonardo S.p.A · Italy
- Elbit Systems Ltd. · Israel
- Israel Aerospace Industries · Israel
- Rheinmetall AG · Germany
- General Dynamics Corporation (U.S.)
- Rohde & Schwarz GmbH & Co. KG · Germany
- Mercury Systems Inc. (U.S.)
- Cobham plc (UK)
Frequently asked questions
The global electronic warfare systems market is expected to reach USD 52.8 billion by 2036 from an estimated USD 24.6 billion in 2026, at a CAGR of 7.9% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Electronic Warfare (EW) Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1906). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/electronic-warfare-systems-market-6589