Aerospace & Defense Factory Automation Market
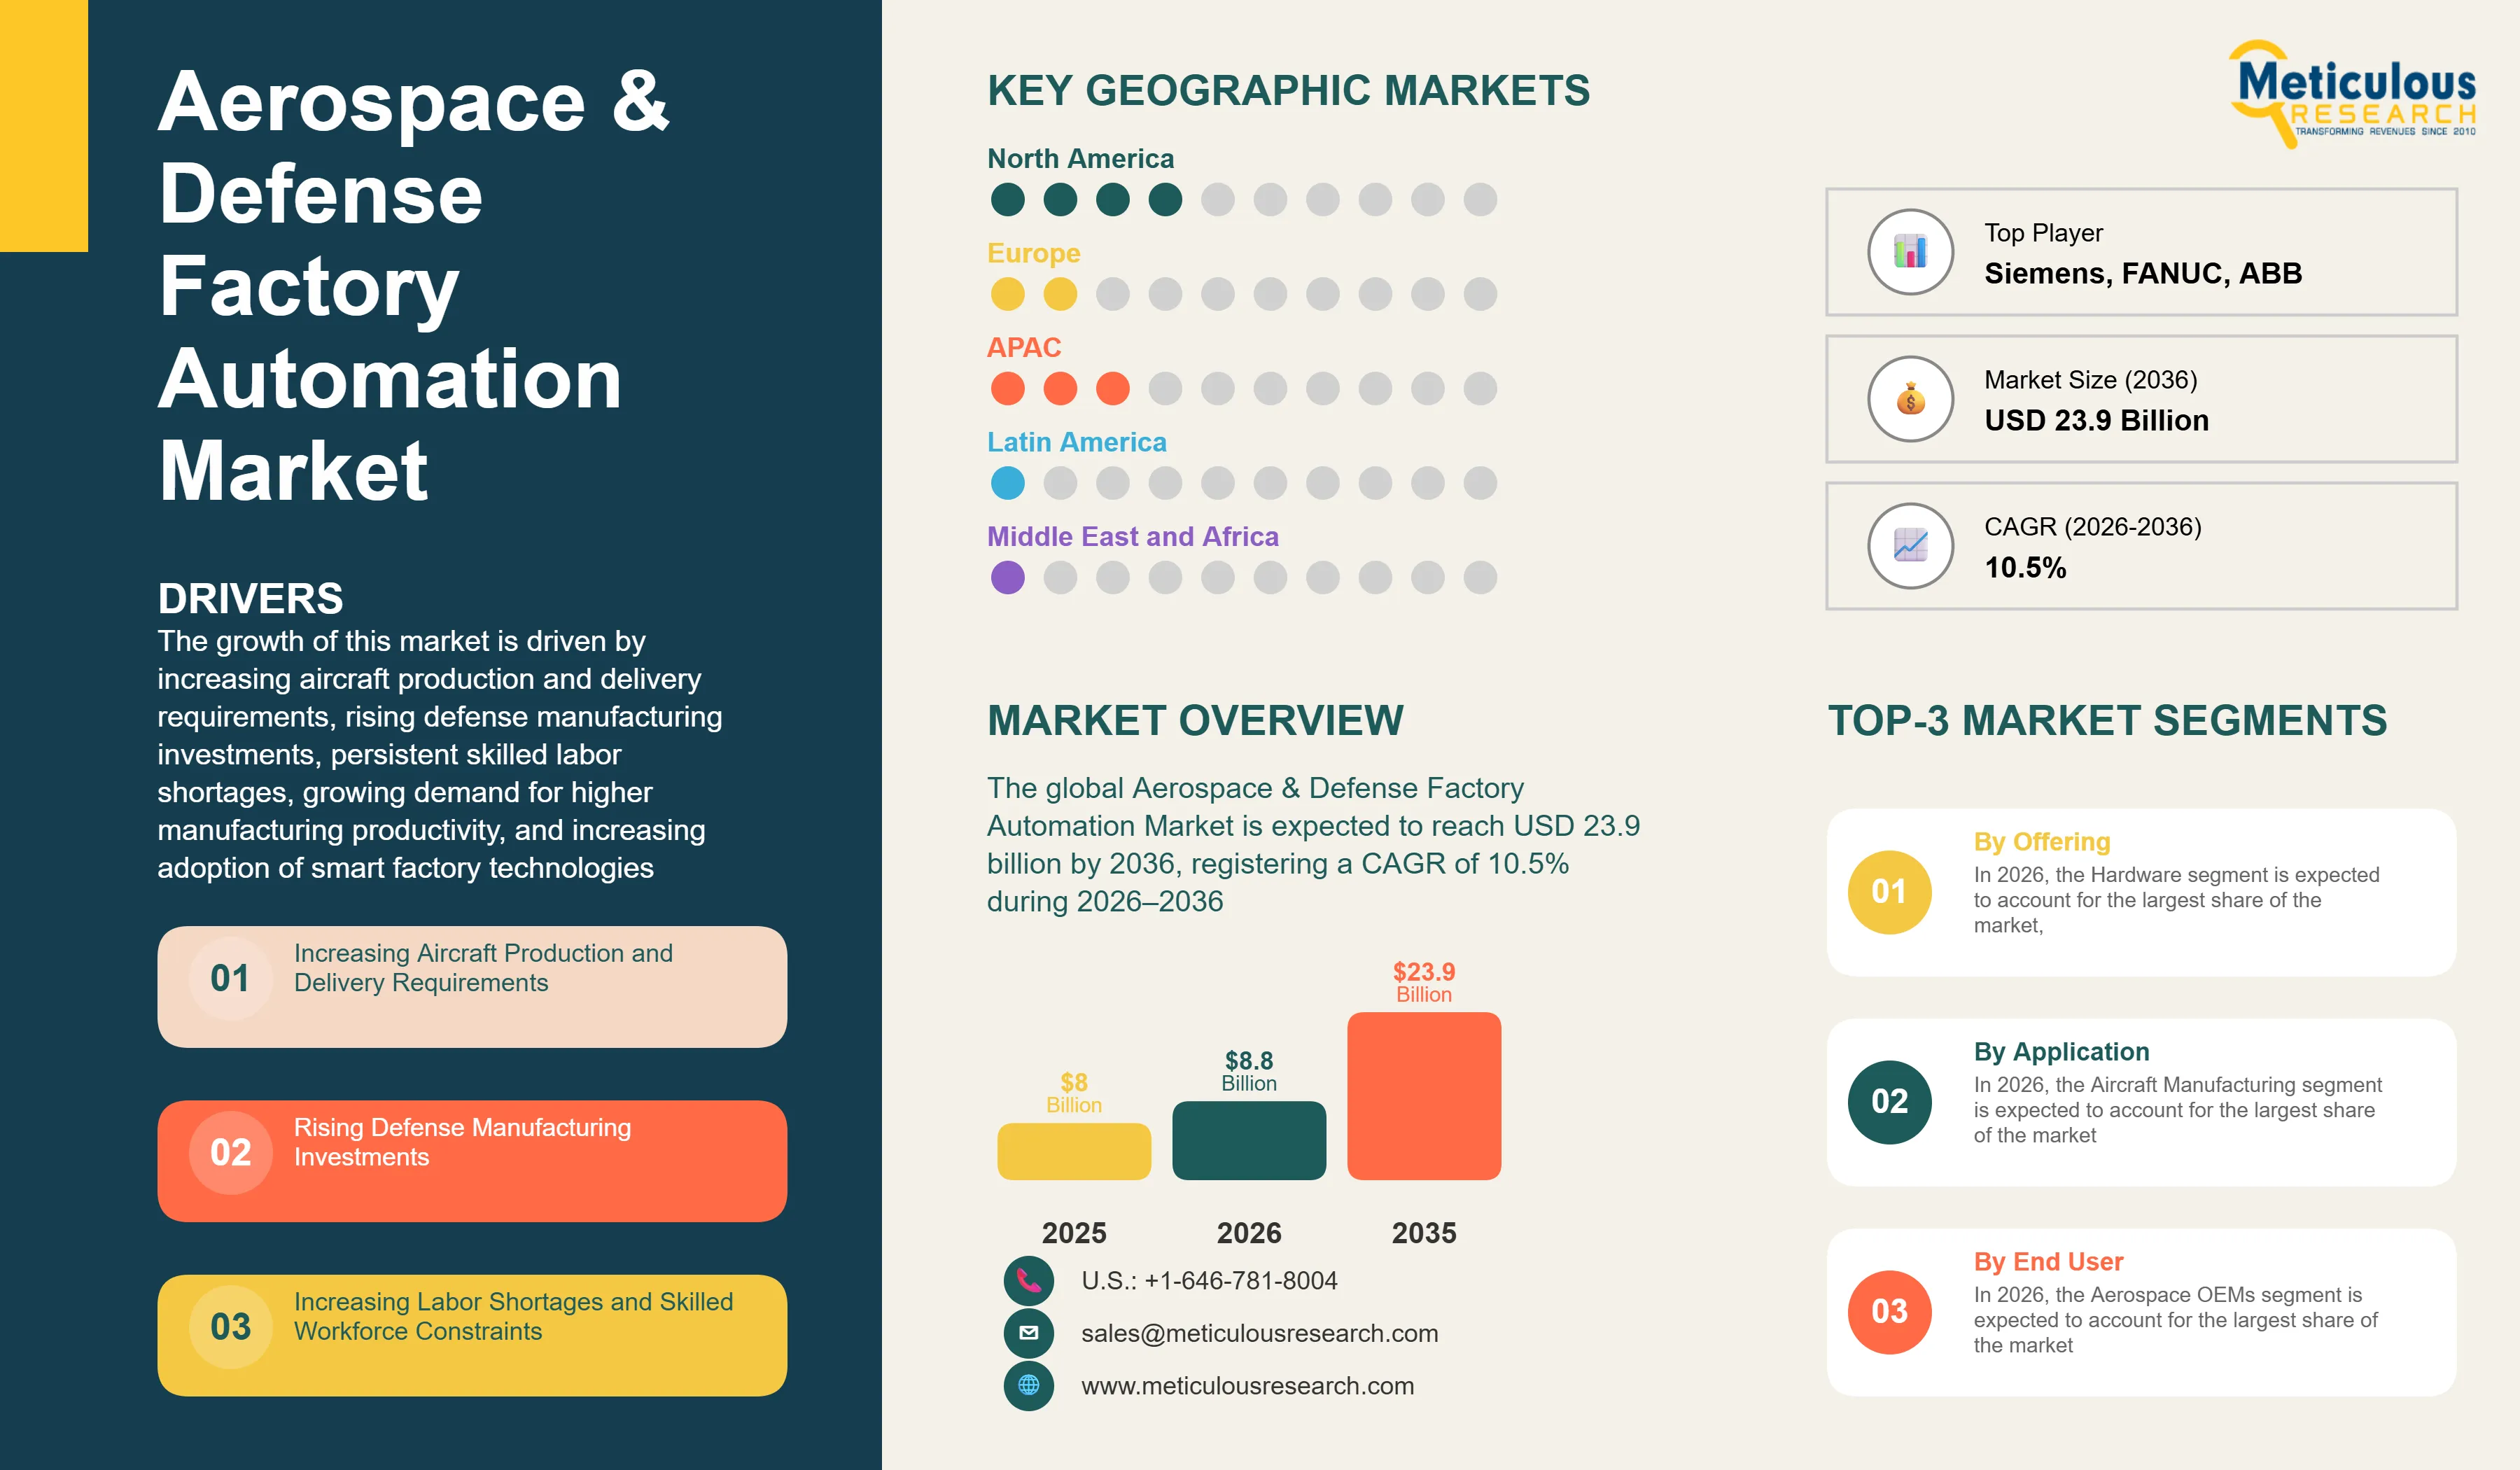
The global Aerospace & Defense Factory Automation Market was valued at USD 8.0 billion in 2025 and is projected to reach USD 8.8 billion in 2026. The market is expected to reach USD 23.9 billion by 2036, registering a CAGR of 10.5% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 299
- Format
- PDF + Excel
- Report ID
- MR-2146
- Base year
- 2025
- 2024 · HISTORICAL
- $2.70T
- 2036
- $23.90B
- CAGR 2026–2036
- 10.5%
2024–2025 baseline · 2026–2036 forecast at 10.5% CAGR · hover a bar for the value
Key highlights
The global Aerospace & Defense Factory Automation Market is projected to reach USD 23.9 billion by 2036, driven by rising aircraft production requirements, increasing defense manufacturing investments, persistent skilled labor shortages, and growing adoption of smart factory technologies.
North America is expected to account for the largest market share in 2026, while Asia-Pacific is projected to register the fastest growth during the forecast period.
By offering, Hardware is expected to account for the largest market share, whereas Software is projected to witness the fastest growth through 2036.
By technology, Industrial Robotics is expected to remain the dominant technology, while Autonomous Inspection is projected to register the highest CAGR as manufacturers seek to improve quality control without adding manual inspection labor.
More than 72% of commercial aircraft manufacturers already utilize robotic systems in fuselage assembly and component handling, with aerospace robotics shown to improve precision by up to 95% while reducing production defects by nearly 40%.
Sustained global defense modernization spending, including the U.S. Department of Defense's 2025 budget of over USD 842 billion, is expected to create substantial long-term demand for defense production capacity expansion and associated factory automation investment.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 10.5% |
| Format | PDF, Excel & Cloud Portal · 299 pages |
| Market Size (Value) in 2026 | USD 8.8 Billion |
| Market Size (Value) in 2036 | USD 23.9 Billion |
| Segments Covered | By Offering: Hardware (Industrial Robots, Collaborative Robots, AGVs, AMRs, CNC Machines, Machine Vision Systems, Automated Assembly & Welding Systems, Sensors & Controls), Software (MES, SCADA, IIoT Platforms, Digital Twin Software, AI/ML Manufacturing Software, Quality Management Software), Services (System Integration, Installation & Commissioning, Consulting, Maintenance & Support, Training, Retrofit & Modernization). · By Automation Type: Fixed Automation, Programmable Automation, Flexible Automation, Reconfigurable Automation, Autonomous Automation. · By Technology: Industrial Robotics, Collaborative Robotics, Automated Material Handling, Machine Vision, CNC & Machining Automation, Automated Assembly, Automated Welding & Joining, Automated Composite Manufacturing, Additive Manufacturing Automation, Digital Twin & Simulation, IIoT & Connected Factory, AI/ML-Based Automation, Autonomous Inspection. · By Manufacturing Process: Machining & Material Removal, Assembly, Joining, Composite Manufacturing, Surface Treatment & Finishing, Inspection & Testing, Material Handling & Logistics. · By Application: Aircraft Manufacturing, Defense Manufacturing, Space Manufacturing, Aerospace & Defense MRO, Other Applications. · By Product Type: Commercial Aircraft, Military Aircraft, Helicopters, UAVs, Missiles & Defense Systems, Spacecraft & Satellites, Launch Vehicles, Engines & Propulsion Systems. · By Factory Type: Greenfield Smart Factories, Brownfield Automated Factories, Hybrid Automated Factories, Fully Automated Factories, Flexible & Reconfigurable Manufacturing Facilities. · By End User: Aerospace OEMs, Defense OEMs, Aircraft Engine Manufacturers, Space & Launch Vehicle Manufacturers, Aerospace Tier-I Suppliers, Aerospace Tier-II & Tier-III Suppliers, Defense Component Manufacturers, MRO Providers, Government & Defense Manufacturing Facilities. |
| Countries Covered | North America: U.S., Canada. · Europe: Germany, France, U.K., Italy, Spain, Sweden, Netherlands, Poland, Rest of Europe. · Asia-Pacific: China, Japan, South Korea, India, Singapore, Australia, Malaysia, Rest of Asia-Pacific. · Latin America: Brazil, Mexico, Argentina, Rest of Latin America. · Middle East & Africa: UAE, Saudi Arabia, Israel, South Africa, Rest of Middle East & Africa. |
| Key Companies | ABB Ltd., FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Siemens AG, Schneider Electric SE, Rockwell Automation, Inc., Honeywell International Inc., Mitsubishi Electric Corporation, Kawasaki Heavy Industries, Ltd., Dassault Systèmes SE, Hexagon AB, Emerson Electric Co., Bosch Rexroth AG, and Cognex Corporation. |
Report overview
Segments covered: offering, automation type, technology, manufacturing process, application, product type, factory type, end user.
The Aerospace & Defense Factory Automation Market comprises the hardware, software, and services used to automate manufacturing operations across aircraft, defense systems, and space vehicle production, spanning industrial and collaborative robots, automated guided vehicles, CNC machining systems, machine vision, automated composite manufacturing, and the manufacturing execution systems, digital twin platforms, and industrial IoT software that connect and orchestrate factory-floor operations. Aerospace and defense manufacturing is characterized by low-volume, high-mix production of safety-critical components, requiring automation systems engineered for precision, traceability, and rigorous qualification, in contrast to the high-volume automation typical of automotive and consumer goods manufacturing.
The market is benefiting from sustained growth in both commercial aircraft production and defense manufacturing investment. According to Airbus' 2025 Global Market Forecast, the global commercial aircraft fleet is expected to increase from approximately 24,730 aircraft in 2024 to more than 49,000 aircraft by 2044, requiring around 43,420 new aircraft deliveries over the 20-year period. Boeing's 2025 Commercial Market Outlook similarly forecasts demand for approximately 43,600 new commercial airplanes through 2044. This large and sustained production requirement is increasing pressure on aerospace manufacturers and Tier-1 suppliers to raise production rates, improve throughput, and maintain stringent quality and traceability requirements. At the same time, defense spending continues to expand globally. According to SIPRI, global military expenditure reached US$2.7 trillion in 2024, an increase of 9.4% in real terms and the largest annual increase since at least the end of the Cold War. U.S. defense spending reached approximately US$997 billion in 2024, further supporting investments in aircraft, missiles, munitions, autonomous systems, and associated manufacturing capacity.
Persistent skilled labor constraints across aerospace and defense manufacturing are further accelerating automation adoption. The Aerospace Industries Association (AIA) has highlighted the industry's continuing workforce challenge, with U.S. aerospace and defense companies employing more than 2.2 million workers while facing persistent shortages of skilled technicians, engineers, machinists, and other specialized manufacturing personnel. These constraints are encouraging manufacturers to deploy robotics, automated inspection, CNC automation, digital manufacturing systems, and AI-enabled production technologies to increase throughput while reducing dependence on scarce skilled labor. The combination of record commercial aircraft backlogs, increased defense procurement, and workforce constraints is therefore accelerating investment in both greenfield smart factories and retrofit automation across existing aerospace and defense manufacturing facilities.
Report infographic
Market dynamics
8 factors across 4 forcesIncreasing Aircraft Production and Delivery Requirements
Sustained commercial aircraft order backlogs are placing significant pressure on aerospace manufacturers to increase production rates while maintaining stringent quality and safety standards. As of December 31, 2025, Airbus reported a commercial aircraft backlog of 8,754 aircraft, while Boeing's backlog stood at approximately 6,100 commercial airplanes, giving the two manufacturers a combined backlog of nearly 14,900 aircraft. Airbus delivered 793 commercial aircraft in 2025, while Boeing delivered 600 commercial airplanes, highlighting the substantial production ramp-up required to convert existing backlogs into deliveries. Meeting these delivery commitments is driving aerospace OEMs and Tier-1 suppliers to invest in automated assembly, precision machining, robotics, composite manufacturing, and automated inspection systems across aircraft production lines.
Rising Defense Manufacturing Investments
Elevated global defense spending amid ongoing geopolitical tensions is driving substantial investment in defense production capacity expansion. The U.S. Department of Defense allocated over USD 842 billion in its 2025 budget, with a significant share directed toward modernizing manufacturing capacity for aircraft, munitions, unmanned systems, and mobile autonomous platforms, directly supporting demand for defense factory automation investment.
Table of contents
16 chapters · 318 sections · 299 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Offering | Hardware | Software |
| By Technology | Industrial Robotics | Autonomous Inspection |
| By Manufacturing Process | Assembly | Composite Manufacturing |
| By Application | Aircraft Manufacturing | Aerospace & Defense MRO |
| By Factory Type | Brownfield Automated Factories | Greenfield Smart Factories |
| By End User | Aerospace OEMs | Defense OEMs |
By Offering
- Market Analysis by Offering (Primary Segmentation)
- Hardware is expected to account for the largest market share, reflecting the substantial capital investment in industrial robots, CNC automation, and machine vision systems required to automate aerospace and defense production lines.
- However, Software is projected to register the fastest growth during the forecast period, driven by increasing manufacturer investment in manufacturing execution systems, digital twin platforms, and AI-enabled production analytics to orchestrate increasingly connected smart factory operations.
By Technology
- Industrial Robotics is expected to account for the largest market share, consistent with its established role in fuselage assembly, drilling, and component handling across aircraft manufacturing programs.
- However, Autonomous Inspection is projected to register the highest CAGR, driven by growing manufacturer demand for automated quality control solutions capable of improving defect detection rates while reducing manual inspection labor requirements.
By Manufacturing Process
- Assembly is expected to account for the largest market share, reflecting the central role of automated assembly systems in airframe, engine, and final aircraft assembly.
- However, Composite Manufacturing is projected to register the fastest growth, driven by the continued expansion of composite-intensive aircraft designs and growing adoption of automated fiber placement and automated tape laying systems.
By Application
- Aircraft Manufacturing is expected to account for the largest market share, supported by sustained commercial aircraft order backlogs and production rate increases.
- However, Aerospace & Defense MRO is projected to register the fastest growth during the forecast period, driven by increasing automation of aircraft inspection, component repair, and engine maintenance operations across a growing global in-service fleet.
By Factory Type
- Brownfield Automated Factories are expected to account for the largest market share, reflecting the predominance of retrofit automation investment across the industry's large base of established manufacturing facilities.
- However, Greenfield Smart Factories are projected to register the fastest growth, driven by new facility construction supporting expanded commercial aircraft and defense production capacity.
By End User
- Aerospace OEMs are expected to account for the largest market share, reflecting their central role in driving large-scale automation investment to meet record aircraft order backlogs.
- However, Defense OEMs are projected to register the fastest growth, supported by sustained global defense modernization spending and production capacity expansion programs.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Aerospace & Defense Factory Automation Market. The region's leadership is supported by the concentration of leading aircraft OEMs, defense primes, space companies, and advanced manufacturing suppliers, alongside substantial defense and aerospace investment. According to the Aerospace Industries Association, the U.S. aerospace and defense industry generated approximately US$1 trillion in economic activity in 2025 and supported more than 2.1 million jobs. In addition, SIPRI estimates that U.S. military expenditure reached US$954 billion in 2025, accounting for approximately one-third of global military spending, while spending approved by the U.S. Congress for 2026 has risen to more than US$1 trillion. These large-scale aerospace and defense activities, combined with persistent production-capacity and skilled-labor requirements, are supporting investments in robotics, automated machining, automated inspection, digital manufacturing, and other factory automation technologies.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is projected to register the highest CAGR during the forecast period. The region's rapid growth is being supported by rising defense expenditure, expanding domestic aircraft manufacturing, and increasing investment in advanced aerospace production capabilities. SIPRI estimates that military expenditure in Asia and Oceania increased 8.1% in real terms to US$681 billion in 2025, making it one of the fastest-growing regional defense markets globally. China's military expenditure remained the second-highest globally in 2025 and accounted for approximately 12% of global military spending, while India remained among the world's five largest military spenders. At the same time, commercial aerospace production is expanding: Airbus delivered 793 commercial aircraft in 2025 and ended the year with a record backlog of 8,754 aircraft, while aircraft manufacturing programs in China, India, Japan, and South Korea are increasing demand for precision machining, robotic assembly, automated inspection, composite manufacturing, and digital factory systems.
Competitive landscape
The global Aerospace & Defense Factory Automation Market is moderately consolidated, with competition among diversified industrial automation and robotics leaders, specialized aerospace automation integrators, and industrial software providers. Companies compete primarily on automation precision and reliability, qualification credentials for aerospace-grade manufacturing processes, software and digital twin capabilities, and the ability to support flexible, low-volume, high-mix production environments.
Leading market participants are investing in AI-enabled robotics and autonomous inspection platforms, expanding digital twin and manufacturing execution system software capabilities, and forming strategic partnerships and acquisitions with specialized aerospace automation and robotics firms to strengthen their aerospace and defense-specific automation portfolios. Capacity expansions, new product launches, and technology partnerships remain key strategies adopted by major vendors seeking to capture the industry's accelerating automation investment.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Aerospace & Defense Factory Automation Market. The key players profiled in the report include ABB Ltd., FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Siemens AG, Schneider Electric SE, Rockwell Automation, Inc., Honeywell International Inc., Mitsubishi Electric Corporation, Kawasaki Heavy Industries, Ltd., Dassault Systèmes SE, Hexagon AB, Emerson Electric Co., Bosch Rexroth AG, and Cognex Corporation.
- ABB Ltd.
- FANUC Corporation
- KUKA AG
- Yaskawa Electric Corporation
- Siemens AG
- Schneider Electric SE
- Rockwell Automation, Inc.
- Honeywell International Inc.
- Mitsubishi Electric Corporation
- Kawasaki Heavy Industries, Ltd.
- Dassault Systèmes SE
- Hexagon AB
- Emerson Electric Co.
- Bosch Rexroth AG
- Cognex Corporation
Frequently asked questions
The global Aerospace & Defense Factory Automation Market is estimated at USD 8.8 billion in 2026.
Cite this report
Meticulous Research. (2026). Aerospace & Defense Factory Automation Market - Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2146). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/aerospace-defense-factory-automation-market-6829