Automotive Electronics Market (2025-2032)
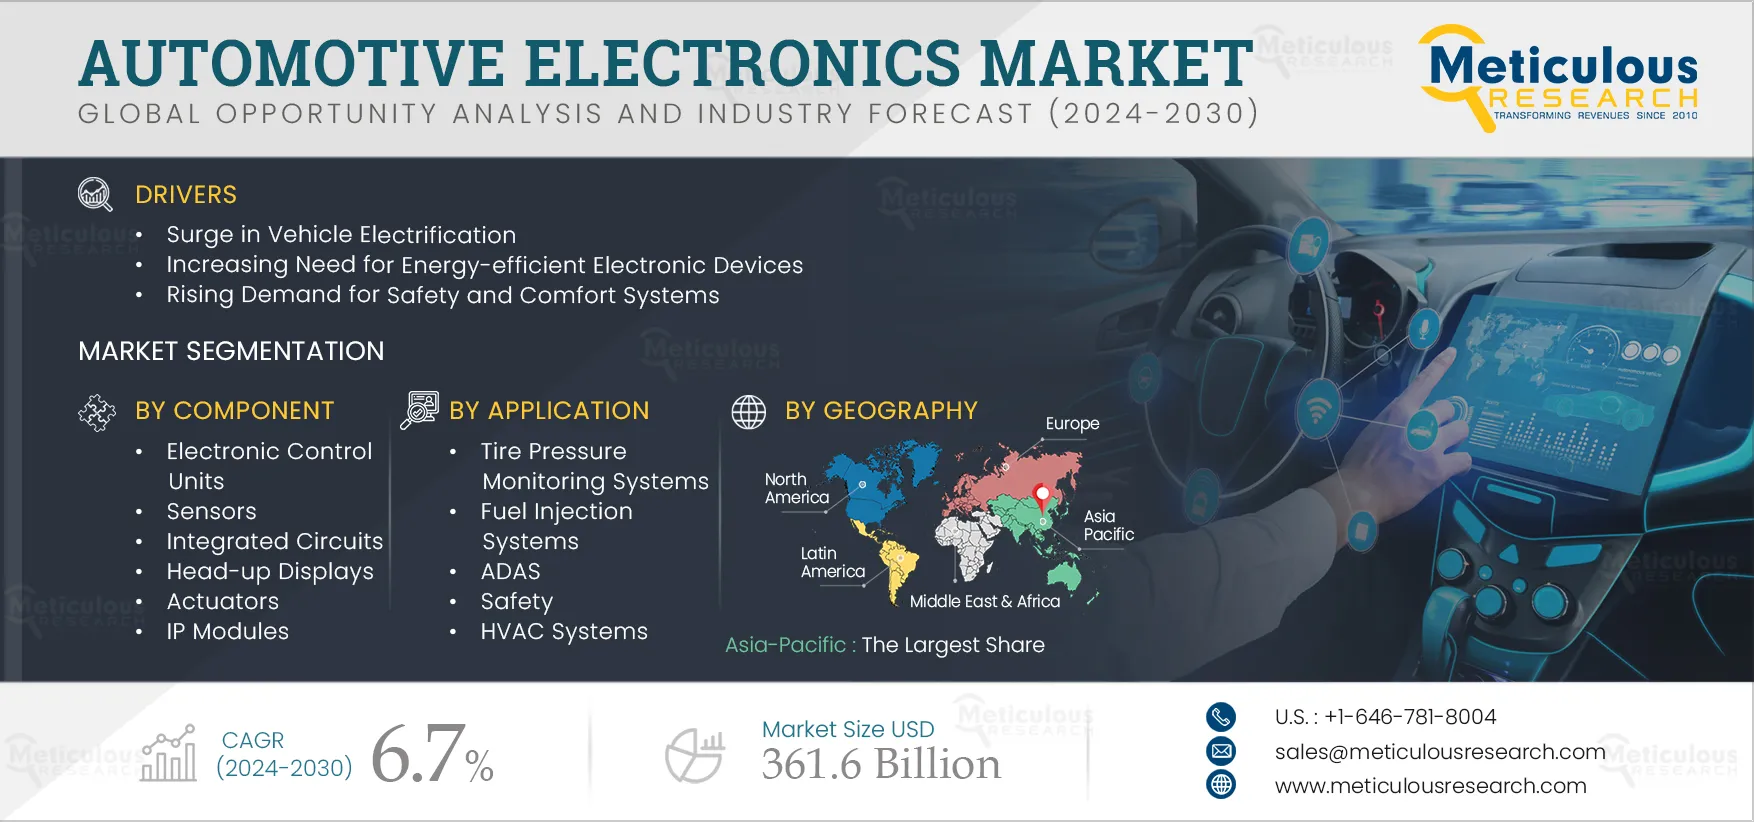
The Automotive Electronics Market is projected to reach $361.6 billion by 2032, at a CAGR of 6.7% during the forecast period of 2025 to 2032.
- Published
- Jan 2025
- Pages
- 300
- Format
- PDF + Excel
- Report ID
- MRSE - 104848
- Base year
- 2024
- 2032 · FORECAST
- $361.6B
- 2032
- $361.6B
- CAGR 2025–2032
- 6.7%
2024 baseline · 2025–2032 forecast at 6.7% CAGR · hover a bar for the value
Key highlights
In 2025, the Electronic Control Units Segment is Expected to Dominate the Automotive Electronics Market
In 2025, the Silicon Segment is Expected to Dominate the Automotive Electronics Market
In 2025, the Body Control & Comfort Segment is Expected to Dominate the Automotive Electronics Market
In 2025, the Internal Combustion Engine Segment is Expected to Dominate the Automotive Electronics Market
In 2025, the OEMs Segment is Expected to Dominate the Automotive Electronics Market
In 2025, Asia-Pacific is Expected to Dominate the Automotive Electronics Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2024 |
| Estimated Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size (2032) | USD 361.60 billion |
| CAGR (2025–2032) | 6.7% |
| Format | PDF, Excel & Cloud Portal · 300 pages |
| Segments Covered | By Component: Electronic Control Units, Sensors, Integrated Circuits, Head-up Displays, Actuators, IP Modules, Other Components · By Material: Silicon, Germanium, Other Materials · By Application: Tire Pressure Monitoring Systems, Engine Management & Powertrain Systems, Fuel Injection Systems, Infotainment Systems, ADAS, Body Control & Comfort, Safety, Architecture & Networking, HVAC Systems, Autonomous Mobility, Lighting Systems, Other Applications · By Vehicle Type: Internal Combustion Engine Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles, Passenger Vehicles · By Distribution Channel: OEMs, Aftermarket · By Channel: OEMs, Aftermarket |
| Countries Covered | Asia-Pacific (Japan, India, South Korea, Australia & New Zealand, Indonesia, Rest of Asia-Pacific), Europe (Germany, U.K., France, Italy, Spain, Sweden, Denmark) |
| Key Companies | Infineon Technologies AG, Robert Bosch GmbH, Valeo Inc., Continental AG, Hitachi, Ltd., Aptiv PLC, STMicroelectronics International N.V., ZF Friedrichshafen AG, Visteon Corporation, Advanced Micro Devices, Inc., Magna International Inc., Hyundai Mobis Co., Ltd. |
Report overview
Segments covered: component, material, application, vehicle type, distribution channel, channel. Regions: Asia-Pacific, Europe.
The growth of this market is attributed to the surge in vehicle electrification, the increasing need for energy-efficient electronic devices, and the rising demand for safety and control systems. In addition, the growing demand for ADAS & AD and the high demand for adaptive lighting systems in passenger & entry-level SUVs are expected to offer significant opportunities for the growth of this market. However, the high cost of electronic systems hampers the growth of this market. In addition, fluctuating raw material prices is a major challenge to the growth of this market.
Report infographic
Market dynamics
1 factors across 1 forceSurge in Vehicle Electrification to Drive the Growth of the Automotive Electronics Market
The growing availability of EVs, government incentives for EV adoption, the decreasing total cost of EV ownership, and the phasing out of fossil fuel-powered vehicles are driving the adoption of electric vehicles across the globe. Considering this gradual shift, the increasing need for automotive electronics is also expected to increase as they enhance electric vehicles' performance, efficiency, and safety. For example, BMS is a critical electronic system in EVs that monitors and controls the battery pack's performance. It ensures the optimal charging and discharging of the batteries, manages the temperature, and provides safety features to prevent overcharging or overheating. The transition to electrified vehicles has created a need for more advanced and reliable automotive electronic components to control and manage various aspects of the vehicle's operations, such as sensor technology, microcontrollers, and communication interfaces.
Furthermore, vehicles' increasing connectivity and digitalization have fueled the demand for automotive electronics. Electric vehicles have advanced infotainment systems, driver assistance features, and connectivity modules that enable communication with external networks. These systems require various electronics, including navigation units, touchscreens, cameras, sensors, and communication modules. The growing consumer demand for seamless connectivity, enhanced user experience, and advanced safety features has led to a surge in the development and integration of these automotive electronics.
Table of contents
13 chapters · 124 sections · 300 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Component | Electronic Control Units | Sensors |
| By Material | Silicon | Silicon |
| By Application | Body Control & Comfort | ADAS |
| By Vehicle Type | Internal Combustion Engine | Electric vehicles |
| By Distribution Channel | OEMs | — |
By Component
- The Electronic Control Units Segment is Expected to Dominate the Automotive Electronics Market
- This segment's large market share is attributed to increasing demand for technologically advanced vehicles in developed and developing countries, such as hybrid, pure electric cars, rising government regulations pertaining to fuel consumption, and the growing need for better mileage of vehicles by the middle-class population.
- However, the sensors segment is projected to register the highest CAGR during the forecast period.
By Material
- The silicon segment is expected to account for the largest share and is projected to register the highest CAGR during the forecast period of the automotive electronics market.
- Silicon-based integrated circuits play a vital role in automotive electronics.
- These ICs are fabricated on silicon wafers using semiconductor manufacturing processes.
- They integrate multiple electronic components, such as transistors, diodes, resistors, and capacitors, onto a single chip.
- ICs enable the miniaturization, high performance, and complexity required for various automotive applications.
By Application
- The body control & comfort segment is expected to account for the largest share of the automotive electronics market.
- This segment's large market share is attributed to increasingly stringent engine management requirements for EVs, rising number of premium comfort features in lower vehicle segments, and the integration of V2V and V2X connectivity technologies in vehicles.
- However, ADAS is projected to register the highest CAGR during the forecast period.
By Vehicle Type
- The internal combustion engine segment is expected to account for the largest share of the automotive electronics market.
- ICE engines are more durable and require less maintenance than electric motors, and stringent government norms with respect to fuel efficiency are some of the drivers for the growth of this segment.
- However, the electric vehicles segment is projected to register the highest CAGR during the forecast period.
By Distribution Channel
- The OEMs segment is expected to account for the largest share of the automotive electronics market.
- This segment's large market share is attributed to OEMs providing durability, longevity and shelf-life of auto electronics more genuine than third parties.
- However, the aftermarket segment is projected to register the highest CAGR during the forecast period.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia- Pacific is expected to account for the largest share of the market and is also expected to grow during the forecast period. The large market share is attributed to increasing demand for EVs, the growing number of manufacturers offering numerous advanced automotive electronics in the mobility industry, and incentive programs for EV adopters. In 2025, Asia-Pacific is Expected to Dominate the Automotive Electronics Market
Competitive landscape
- Infineon Technologies AG
- Robert Bosch GmbH
- Valeo Inc.
- Continental AG
- Hitachi, Ltd.
- Aptiv PLC
- STMicroelectronics International N.V.
- ZF Friedrichshafen AG
- Visteon Corporation
- Advanced Micro Devices, Inc.
- Magna International Inc.
- Hyundai Mobis Co., Ltd.
Frequently asked questions
The Automotive Electronics Market involves the production and sale of electronic components used in vehicles, including systems for control, safety, infotainment, and advanced driver assistance.
Cite this report
Meticulous Research. (2025). Automotive Electronics Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRSE - 104848). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/automotive-electronics-market-5531