Defense Electronics Market
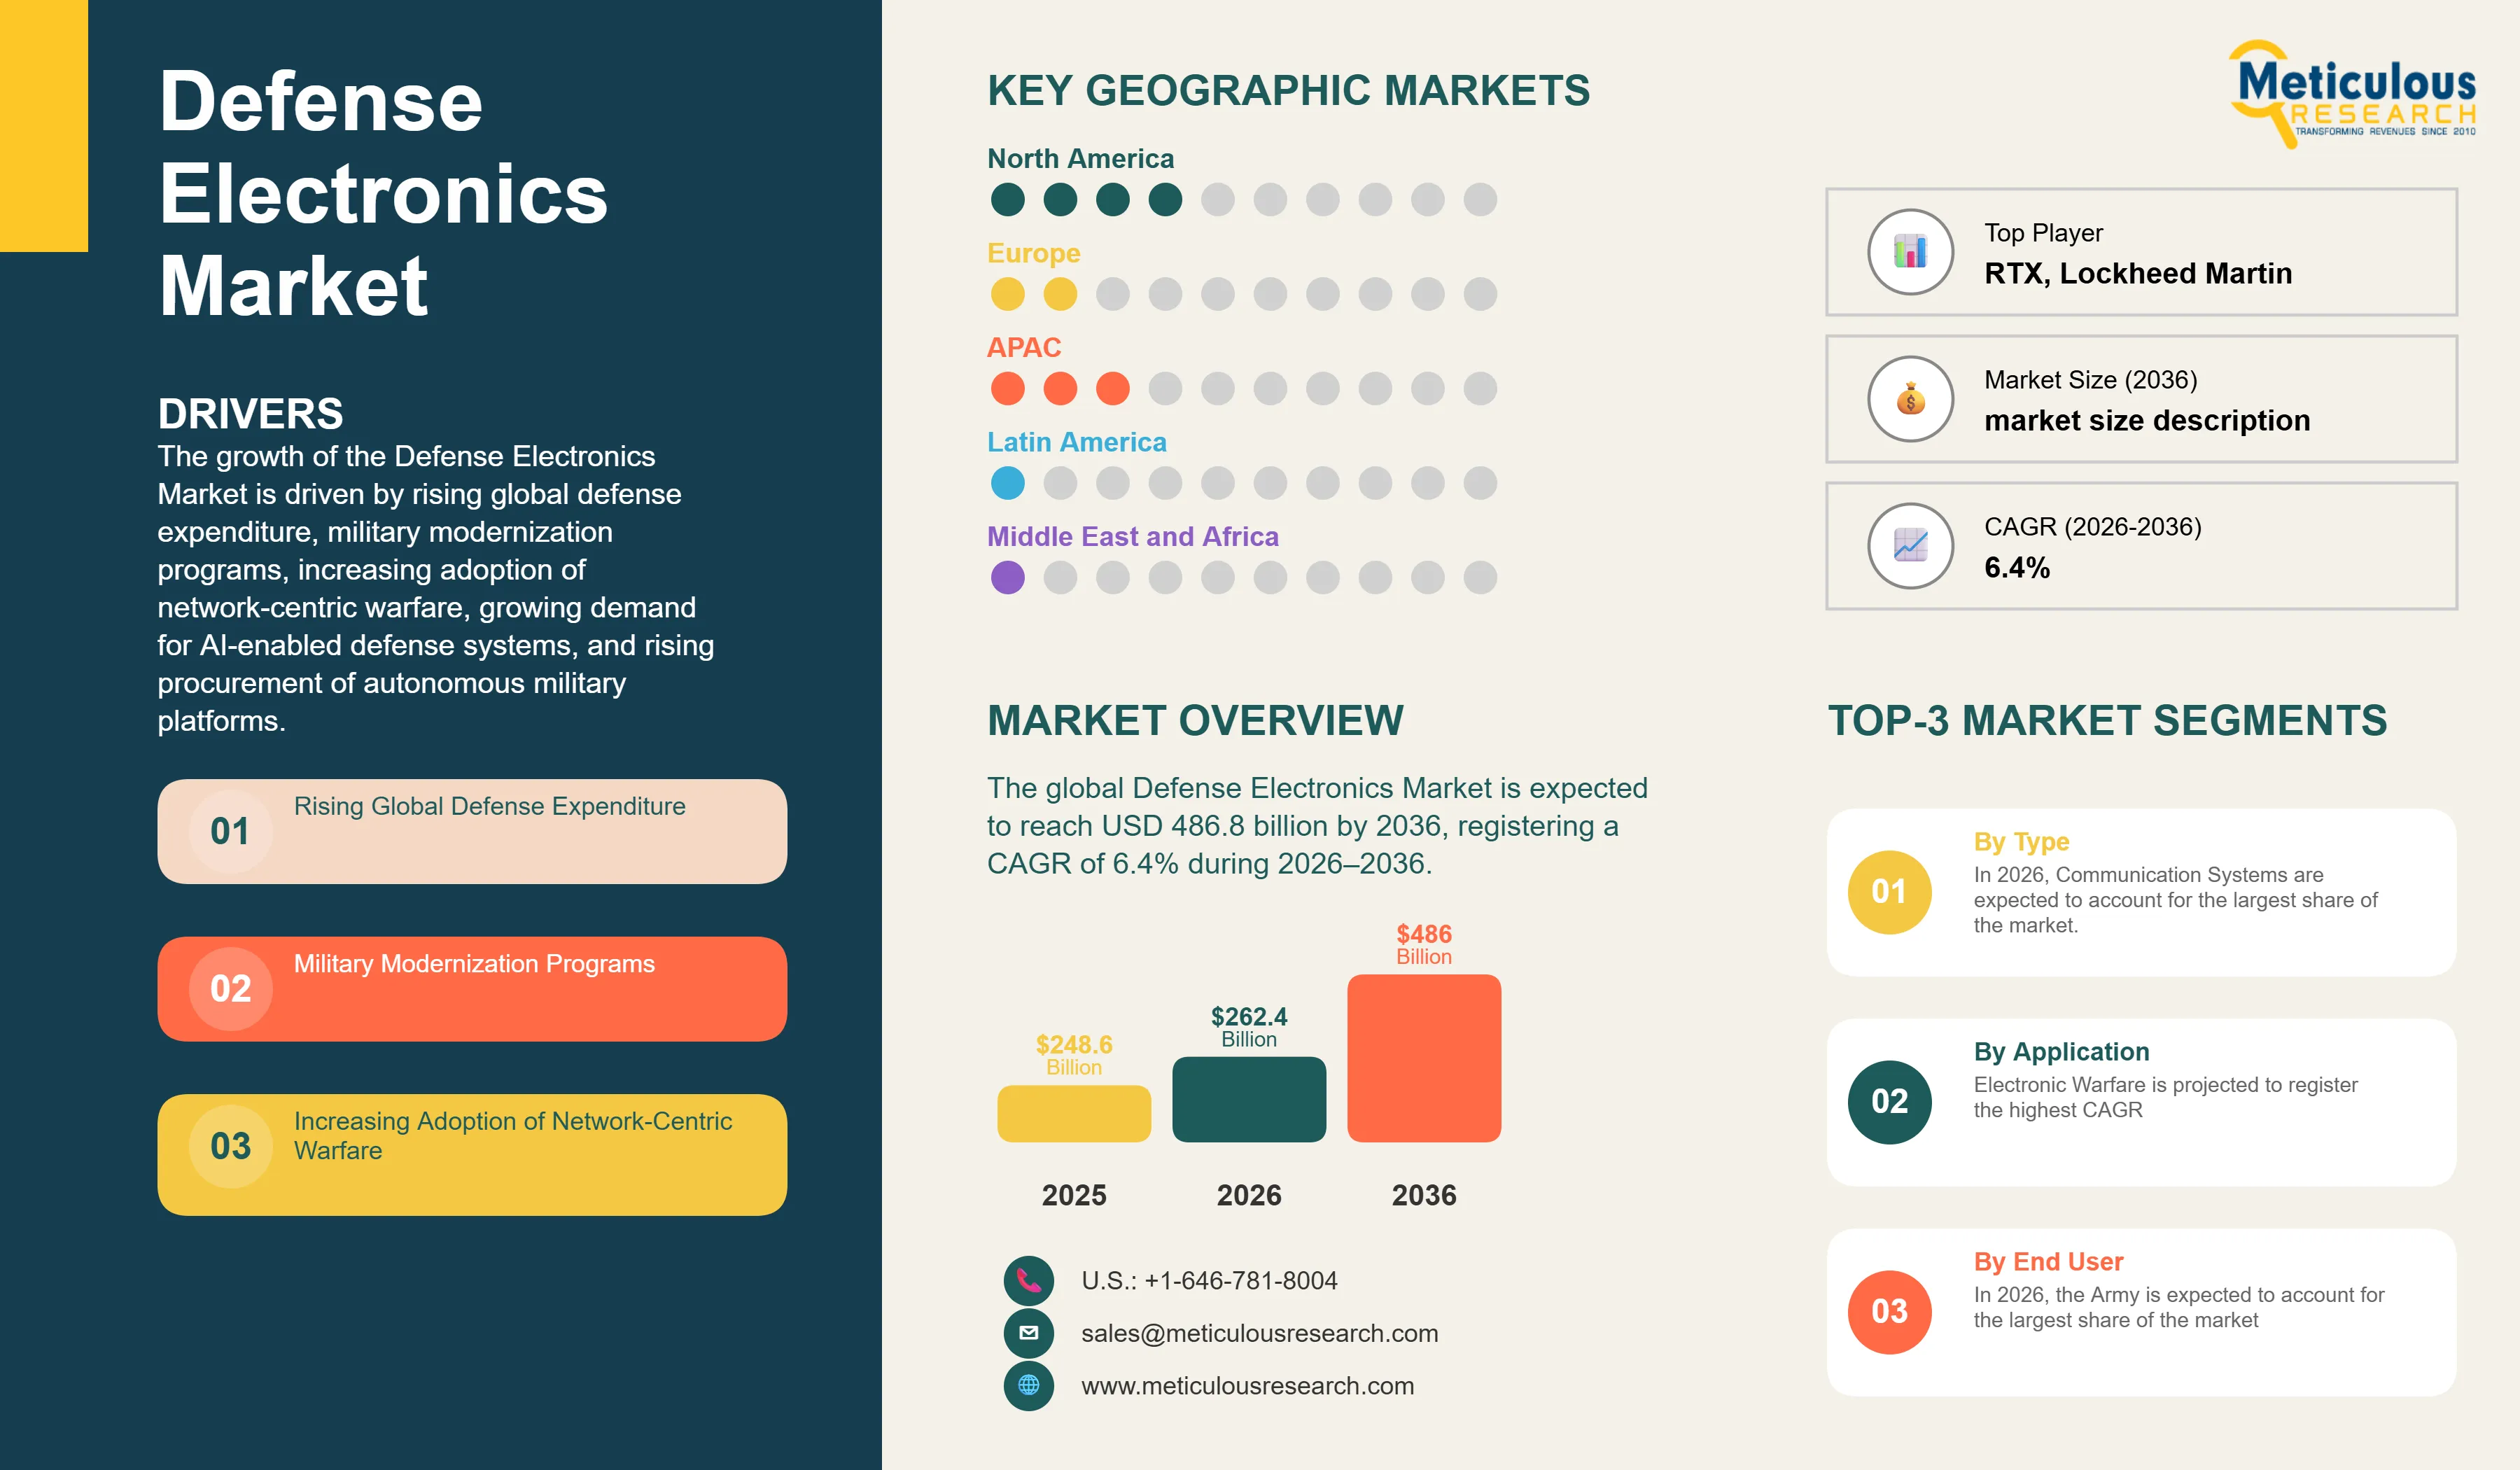
The global Defense Electronics Market is estimated was valued at USD 248.6 billion in 2025 and is projected to reach USD 262.4 billion in 2026. The market is expected to reach USD 486.8 billion by 2036, registering a CAGR of 6.4% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 310
- Format
- PDF + Excel
- Report ID
- MR-2126
- Base year
- 2025
- 2025 · BASELINE
- $248.6B
- 2036
- $486.8B
- CAGR 2026–2036
- 6.4%
2025 baseline · 2026–2036 forecast at 6.4% CAGR · hover a bar for the value
Key highlights
The global Defense Electronics Market is projected to reach USD 486.8 billion by 2036, driven by rising global defense expenditure, military modernization programs, increasing adoption of AI-enabled defense systems, and growing procurement of autonomous military platforms.
North America is expected to account for the largest market share in 2026, while Asia-Pacific is projected to register the fastest growth during the forecast period.
By product, Communication Systems are expected to account for the largest market share, whereas Electronic Warfare Systems are projected to witness the fastest growth through 2036.
By electronic component, Processing & Computing Modules are expected to dominate the market, while AI & Edge Computing Modules are projected to register the highest CAGR during the forecast period.
Growing adoption of AESA radars, software-defined radios (SDRs), Gallium Nitride (GaN) semiconductors, AI-enabled mission systems, and software-defined defense electronics is transforming modern military capabilities.
Increasing investments in multi-domain operations, space-based defense systems, next-generation battlefield digitization, and electronic warfare are expected to create significant long-term growth opportunities.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 6.4% |
| Format | PDF, Excel & Cloud Portal · 310 pages |
| Market Size (Value) in 2026 | USD 262.4 Billion |
| Market Size (Value) in 2036 | USD 486.8 Billion |
| Segments Covered | By Product: Communication Systems, Radar Systems, Electronic Warfare Systems, Electro-Optical & Infrared (EO/IR) Systems, Navigation & Positioning Systems, Mission Computers & Displays, Identification Friend or Foe (IFF) Systems, Military Power Electronics. · By Electronic Component: Processing & Computing Modules, RF & Microwave Components, Sensors, Power Electronics, Printed Circuit Boards (PCBs), Connectors & Interconnects, Displays & Human-Machine Interfaces, Antennas, Memory & Data Storage Devices, Electronic Packaging & Thermal Management Components. · By Platform: Airborne, Land, Naval, Space. · By Technology: Analog Electronics, Digital Electronics, RF & Microwave Electronics, Photonics & Electro-Optics, Artificial Intelligence & Edge AI, Software-Defined Electronics, Quantum Electronics. · By Application: Intelligence, Surveillance & Reconnaissance (ISR), Command, Control, Communications, Computers, Intelligence, Surveillance & Reconnaissance (C4ISR), Battlefield Communications, Electronic Warfare, Target Acquisition & Fire Control, Missile Guidance & Control, Border & Homeland Security, Force Protection. · By End User: Army, Navy, Air Force, Space Force, Homeland Security & Border Protection Agencies. |
| Countries Covered | North America: U.S., Canada. · Europe: U.K., Germany, France, Italy, Poland, Rest of Europe. · Asia-Pacific: China, India, Japan, South Korea, Australia, Singapore, Rest of Asia-Pacific. · Latin America: Brazil, Mexico, Argentina, Rest of Latin America. · Middle East & Africa: Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa. |
| Key Companies | RTX Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems plc, L3Harris Technologies, Inc., Thales S.A., Leonardo S.p.A., Elbit Systems Ltd., Saab AB, HENSOLDT AG, General Dynamics Corporation, Honeywell Aerospace Technologies, Indra Sistemas, S.A., Bharat Electronics Limited (BEL), and Rheinmetall AG. |
Report overview
Segments covered: product, electronic component, platform, technology, application, end user.
The Defense Electronics Market comprises electronic systems, subsystems, and components designed for military platforms operating across land, air, naval, and space domains. The market includes communication systems, radar systems, electronic warfare systems, electro-optical and infrared (EO/IR) systems, navigation and positioning systems, mission computers, military power electronics, and identification friend or foe (IFF) systems, along with supporting electronic components such as processors, RF modules, sensors, antennas, connectors, rugged displays, power electronics, and secure data storage devices. These technologies enable intelligence gathering, battlefield communication, surveillance, navigation, targeting, command and control, and electronic protection for modern armed forces.
The market is experiencing strong growth as governments worldwide continue to modernize their armed forces in response to evolving geopolitical threats and technological advancements. According to the Stockholm International Peace Research Institute (SIPRI), global military expenditure reached a record US$2.89 trillion in 2025, marking the 11th consecutive year of growth. Global military spending increased by 41% between 2016 and 2025, while the world's military burden rose to 2.5% of global GDP. In addition, NATO member states agreed in 2025 to increase the Alliance's long-term defence spending target from 2% to 5% of GDP by 2035, reflecting an unprecedented commitment to defence modernization and advanced military capabilities. Increasing investments in advanced fighter aircraft, naval vessels, missile defense systems, unmanned platforms, integrated battlefield communication networks, and space-based defense capabilities are significantly increasing demand for next-generation defense electronics.
Another major growth driver is the transition toward network-centric and multi-domain warfare, where real-time information sharing across air, land, sea, cyber, and space domains has become essential for military effectiveness. Governments are increasingly deploying AI-enabled surveillance systems, software-defined radios, Active Electronically Scanned Array (AESA) radars, edge computing platforms, autonomous military systems, and satellite-enabled command-and-control networks to improve battlefield awareness and decision-making. According to SIPRI, the combined military expenditure of NATO members reached approximately US$1.58 trillion in 2025, accounting for nearly 55% of global military spending, highlighting the scale of ongoing investments in advanced defence technologies. At the same time, the growing use of Gallium Nitride (GaN) semiconductors, open system architectures (MOSA), software-defined electronics, and space-based defense technologies is reshaping the defense electronics ecosystem and creating new opportunities for technology providers.
Market dynamics
10 factors across 5 forcesRising Global Defense Expenditure and Military Modernization
The steady increase in global defense spending is one of the primary factors driving the Defense Electronics Market. Governments are investing heavily in modernizing military capabilities by procuring advanced aircraft, naval vessels, armored vehicles, missile defense systems, and integrated battlefield communication platforms. According to SIPRI, global military expenditure reached a record level in 2025, reflecting increasing geopolitical tensions and national security priorities. These investments are driving demand for advanced radar systems, secure communication equipment, mission computers, sensors, electronic warfare systems, and other defense electronics.
Growing Adoption of AI-Enabled Defense Systems and Autonomous Platforms
Artificial intelligence is rapidly transforming military operations by improving target recognition, autonomous navigation, predictive maintenance, battlefield intelligence, and decision support. Defense organizations are increasingly integrating AI into unmanned aerial vehicles (UAVs), autonomous ground vehicles, naval platforms, surveillance systems, and command-and-control networks. At the same time, the growing procurement of autonomous military platforms and AI-enabled electronic warfare systems is increasing demand for high-performance processors, edge computing modules, secure communication systems, and advanced sensors, thereby supporting sustained market growth.
Table of contents
14 chapters · 255 sections · 310 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product | Communication Systems | Electronic Warfare Systems |
| By Electronic Component | Processing & Computing Modules | AI & Edge Computing Modules |
| By Platform | Airborne | Space |
| By Technology | Digital Electronics | Mission systems.However, Artificial Intelligence & Edge AI |
| By Application | C4ISR | Electronic Warfare |
| By End User | Army | Space Force |
By Product
- The Communication Systems segment is expected to account for the largest share of the global Defense Electronics Market.
- The large share of this segment is mainly due to increasing deployment of secure battlefield communications, satellite communications, software-defined radios, and network-centric military operations.
- However, the Electronic Warfare Systems segment is projected to register the fastest growth during the forecast period.
- The rapid growth of this segment is attributed to rising investments in electronic attack, electronic protection, spectrum dominance, and countermeasure technologies.
By Electronic Component
- Processing & Computing Modules are expected to account for the largest market share because they serve as the core processing platforms for modern military communication, surveillance, and mission systems.
- However, AI & Edge Computing Modules are projected to register the highest CAGR during the forecast period owing to increasing deployment of autonomous systems, intelligent sensors, and AI-enabled battlefield decision support.
By Platform
- The Airborne segment is expected to account for the largest market share due to increasing procurement of advanced fighter aircraft, military helicopters, airborne surveillance platforms, and UAVs.
- However, the Space segment is projected to register the highest CAGR during the forecast period owing to increasing investments in military satellites, missile warning systems, secure satellite communications, and space surveillance capabilities.
By Technology
- Digital Electronics are expected to account for the largest market share because digital architectures form the foundation of modern military communication, computing, radar, and mission systems.However, Artificial Intelligence & Edge AI is projected to register the highest CAGR during the forecast period due to increasing adoption across autonomous military platforms, intelligence analysis, target recognition, and real-time battlefield decision-making.
By Application
- C4ISR is expected to account for the largest market share owing to increasing investments in integrated battlefield management, secure communication networks, and real-time intelligence sharing.
- However, Electronic Warfare is projected to register the highest CAGR during the forecast period, driven by increasing emphasis on electromagnetic spectrum superiority, electronic attack capabilities, and countermeasure systems.
By End User
- The Army segment is expected to account for the largest market share due to extensive procurement of communication systems, surveillance equipment, electronic warfare platforms, and battlefield electronics.
- However, the Space Force segment is projected to register the highest CAGR during the forecast period because of increasing investments in military satellites, space surveillance, missile tracking, and space-based defense capabilities.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Defense Electronics Market. The region's dominance is supported by the presence of major defense contractors, continuous military modernization programs, and substantial investments in advanced electronic warfare, radar, secure communications, and space-based defense systems. The United States accounts for the largest share of global defense spending and continues to invest heavily in next-generation military technologies. According to the Stockholm International Peace Research Institute (SIPRI), the U.S. remained the world's largest military spender in 2025, accounting for approximately 33% of global military expenditure. Ongoing procurement of advanced fighter aircraft, naval combat systems, missile defense platforms, unmanned systems, and AI-enabled battlefield technologies is driving strong demand for defense electronics across the region.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is projected to register the highest CAGR during the forecast period. Rising geopolitical tensions, increasing indigenous defense manufacturing, and growing investments in military modernization are accelerating demand for advanced defense electronics across China, India, Japan, South Korea, and Australia. According to the Stockholm International Peace Research Institute (SIPRI), military expenditure in Asia and Oceania increased by 8.1% to approximately US$681 billion in 2025, accounting for nearly one-quarter of global military spending. China remained the region's largest defense spender with an estimated US$336 billion budget, followed by India (US$92.1 billion), Japan (US$62.2 billion), South Korea (US$47.8 billion), and Australia (US$35.3 billion). Governments in the region are expanding investments in integrated air defense systems, secure communication networks, surveillance systems, electronic warfare capabilities, and autonomous military platforms. The rapid modernization of armed forces, coupled with rising defense budgets and increasing domestic procurement of advanced military technologies, is expected to significantly boost demand for defense electronics throughout the forecast period
Competitive landscape
The global Defense Electronics Market is moderately consolidated, with competition among defense prime contractors, military electronics manufacturers, radar system developers, communication technology providers, and advanced semiconductor companies. Market participants compete primarily on technological innovation, system reliability, cybersecurity capabilities, interoperability, product performance, manufacturing capacity, and long-term defense contracts.
Leading companies are investing in Gallium Nitride (GaN) semiconductors, Active Electronically Scanned Array (AESA) radar systems, artificial intelligence, edge computing, software-defined electronics, and open system architectures (MOSA) to strengthen their market position. Strategic partnerships with defense ministries, military agencies, and system integrators, along with acquisitions, R&D investments, and long-term government procurement contracts, remain the key strategies adopted by major vendors. Companies are also expanding their capabilities in electronic warfare, autonomous military systems, secure battlefield communications, and space-based defense electronics to support evolving multi-domain military operations.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Defense Electronics Market. The key players profiled in the report include RTX Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems plc, L3Harris Technologies, Inc., Thales S.A., Leonardo S.p.A., Elbit Systems Ltd., Saab AB, HENSOLDT AG, General Dynamics Corporation, Honeywell Aerospace Technologies, Indra Sistemas, S.A., Bharat Electronics Limited (BEL), and Rheinmetall AG.
- RTX Corporation
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- BAE Systems plc
- L3Harris Technologies, Inc.
- Thales S.A.
- Leonardo S.p.A
- Elbit Systems Ltd.
- Saab AB
- HENSOLDT AG
- General Dynamics Corporation
- Honeywell Aerospace Technologies
- Indra Sistemas, S.A.
- Bharat Electronics Limited (BEL)
- Rheinmetall AG
Frequently asked questions
The global Defense Electronics Market is estimated at USD 262.4 billion in 2026.
Cite this report
Meticulous Research. (2026). Defense Electronics Market - Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2126). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/defense-electronics-market-6809