Bone Densitometer Market (2026-2036)
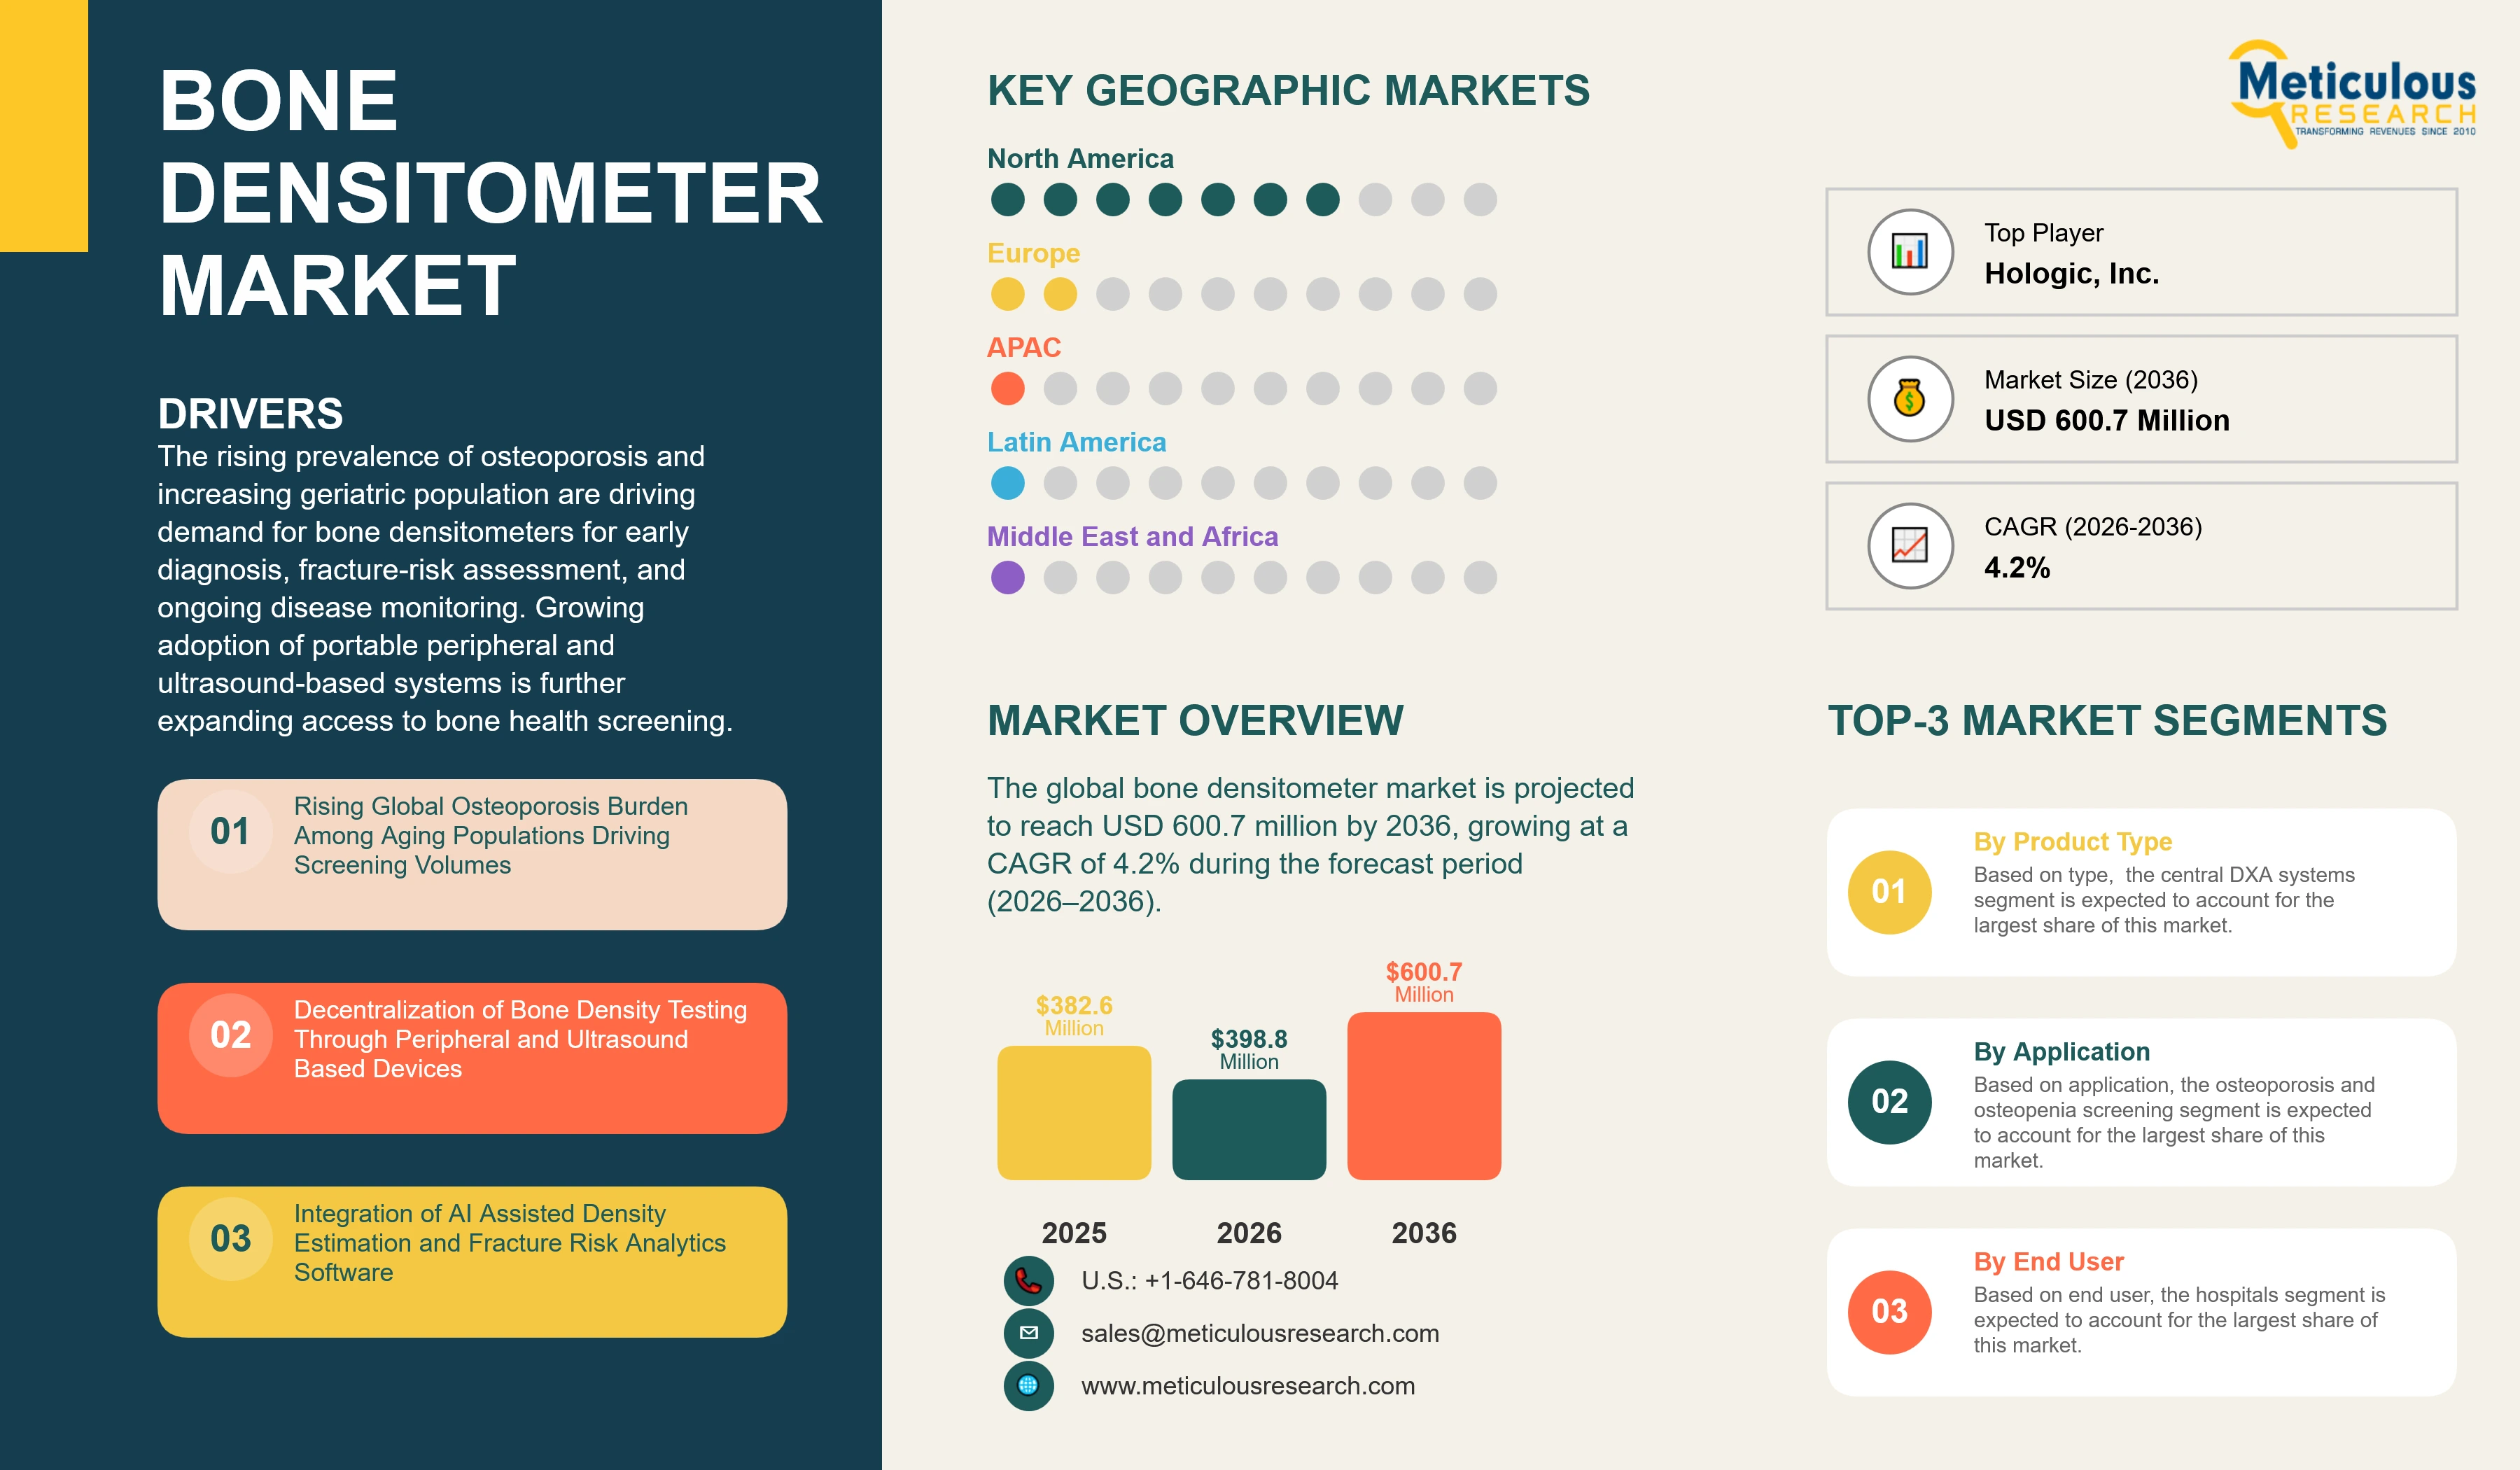
The global bone densitometer market was valued at USD 382.6 million in 2025. The market is projected to reach USD 600.7 million by 2036, growing from USD 398.8 million in 2026 at a CAGR of 4.2% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 289
- Format
- PDF + Excel
- Report ID
- MR-2144
- Base year
- 2025
- 2025 · BASELINE
- $382.6M
- 2036
- $600.7M
- CAGR 2026–2036
- 4.2%
2025 baseline · 2026–2036 forecast at 4.2% CAGR · hover a bar for the value
Key highlights
The global bone densitometer market is projected to reach USD 600.7 million by 2036.
The market is expected to grow at a CAGR of 4.2% during the forecast period 2026–2036.
The total bone densitometer market was valued at USD 382.6 million in 2025 and is estimated to reach USD 398.8 million in 2026.
North America is expected to dominate this market with the largest revenue share in 2026, supported by the country's rapidly aging population, well-established osteoporosis screening infrastructure, and a Medicare reimbursement framework that has driven routine bone density testing among older adults for close to three decades.
Asia Pacific is projected to witness the fastest revenue growth during the forecast period, driven by a large and aging population base in China and India, growing government-led osteoporosis awareness programs, and rising investment in diagnostic imaging capacity across public and private hospital networks.
By product type, the central (axial) DXA systems segment is expected to hold the largest share of the market in 2026, reflecting its position as the clinical reference standard for diagnosing osteoporosis at the hip and spine.
By product type, the peripheral DXA and quantitative ultrasound systems segment is projected to register the highest growth during the forecast period, driven by rising demand for portable, radiation-light devices suited to primary care clinics, pharmacies, and community screening programs.
By application, osteoporosis and osteopenia screening is expected to account for the largest share of the market in 2026, while fracture risk assessment is projected to register the highest CAGR during the forecast period.
By end user, hospitals are expected to account for the largest share in 2026, while diagnostic imaging centers are projected to register the highest CAGR during the forecast period.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 600.7 Million |
| Market Size in 2026 | USD 398.8 Million |
| Market Size in 2025 | USD 382.6 Million |
| Revenue Growth Rate (2026–2036) | CAGR of 4.2% |
| Format | PDF, Excel & Cloud Portal · 289 pages |
| Dominating Product Type | Central (Axial) DXA Systems |
| Fastest Growing Product Type | Peripheral DXA and Quantitative Ultrasound Systems |
| Dominating Application | Osteoporosis and Osteopenia Screening |
| Fastest Growing Application | Fracture Risk Assessment |
| Dominating End User | Hospitals |
| Fastest Growing End User | Diagnostic Imaging Centers |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: product type, application, end user.
The global bone densitometer market comprises diagnostic systems used to assess bone health, measure bone mineral density (BMD), and evaluate fracture risk, primarily for the diagnosis and monitoring of osteoporosis and osteopenia. The market includes central or axial dual-energy X-ray absorptiometry (DXA) systems for measuring the hip and lumbar spine; peripheral DXA systems for sites such as the forearm, finger, and heel; quantitative ultrasound (QUS) systems, also known as bone sonometers, which assess bone properties without ionizing radiation; and other technologies, including quantitative computed tomography (QCT) and radiographic absorptiometry. These systems are used across hospitals, diagnostic imaging centers, orthopedic and rheumatology clinics, and other healthcare settings for osteoporosis screening, fracture risk assessment, and treatment monitoring.
Market growth is supported by the expanding global aging population and rising prevalence of osteoporosis and low bone mass. The U.S. Census Bureau reported that the U.S. population aged 65 years and older reached 61.2 million in 2024, accounting for 18.0% of the population. CDC data indicate that 12.6% of U.S. adults aged 50 and older have osteoporosis at the femoral neck or lumbar spine, while an additional 43.1% have low bone mass. Globally, the International Osteoporosis Foundation estimates that osteoporosis affects approximately 500 million people, with more than 37 million fragility fractures occurring annually.
However, adoption is constrained by the high cost of central DXA systems, limited reimbursement in some emerging markets, and continued use of refurbished equipment. Increasing adoption of portable peripheral and ultrasound systems, advanced fracture-risk assessment software, and AI-enabled bone analysis is creating additional growth opportunities.
Report infographic
Market dynamics
3 factors across 1 forceAging Populations and Rising Fragility Fracture Burden Sustaining Long Term Screening Demand
The structural shift toward older populations across North America, Europe, and increasingly Asia represents the most durable demand driver in the global bone densitometer market, converting osteoporosis screening from a discretionary clinical activity into a routine element of preventive care for aging patients. In the United States, the Census Bureau's Vintage 2024 estimates place the population aged 65 and older at 61.2 million, with this group projected to keep growing faster than any other age segment through the next decade, directly expanding the pool of patients eligible for routine bone mineral density testing under Medicare and private insurance guidelines.
The clinical case for expanded testing is reinforced by the scale of the underlying disease burden. CDC surveillance data show that osteoporosis prevalence among U.S. adults aged 50 and over rose over the decade to 2017–2018, particularly among women, while the International Osteoporosis Foundation's global estimates put the number of people affected by osteoporosis worldwide at approximately 500 million, with fragility fractures occurring at a rate of roughly 70 every minute. With the Foundation projecting that the annual number of hip fractures will nearly double between 2018 and 2050 as global populations age, health systems in both developed and emerging markets are under sustained pressure to expand access to bone density testing as a frontline tool for identifying at risk patients before a first fracture occurs.
Decentralization of Screening Through Peripheral DXA and Quantitative Ultrasound Devices
The gradual shift of bone density testing away from centralized, hospital based radiology departments and toward primary care clinics, pharmacies, and community screening settings is reshaping the competitive dynamics of the bone densitometer market. Peripheral DXA systems, which scan the forearm or finger, and quantitative ultrasound devices, which assess bone properties at the heel without ionizing radiation, require substantially less capital investment, floor space, and specialized operator training than central DXA systems, making them practical for deployment well beyond traditional radiology settings.
Manufacturers including OsteoSys Co., Ltd., Furuno Electric Co., Ltd., and Medonica Co., Ltd. have built their peripheral and ultrasound product portfolios specifically around this decentralized use case, positioning compact tabletop and portable devices for orthopedic clinics, occupational health providers, and screening camps in markets where access to a dedicated DXA suite remains limited. Echolight S.p.A.'s radiofrequency echographic multi spectrometry technology similarly targets this decentralized opportunity by offering a radiation free alternative capable of assessing both bone density and bone quality at the point of care. This trend is expanding the overall base of installed devices even as it shifts a growing share of unit volume toward lower priced product categories relative to hospital grade central DXA systems.
Software Driven Differentiation Through Fracture Risk Analytics and AI Assisted Density Estimation
The incorporation of advanced analytical software into bone densitometer platforms is becoming a meaningful axis of competitive differentiation, as manufacturers look beyond hardware performance to clinical decision support as a source of recurring revenue and customer retention. Trabecular bone score software, which derives an index of bone microarchitecture from standard DXA scans to complement conventional bone mineral density readings, has been incorporated into leading DXA platforms as a way of improving fracture risk stratification without requiring additional patient scanning.
At the same time, software only tools that estimate bone mineral density from computed tomography scans acquired for unrelated clinical purposes, several of which have received FDA 510(k) clearance as Class II bone densitometer devices under 21 CFR 892.1170, are opening a parallel opportunity to identify osteoporosis risk opportunistically in patients who have not undergone a dedicated DXA scan. As health systems look to close the well documented diagnostic gap in osteoporosis, estimated by the International Osteoporosis Foundation at up to 80 percent of fracture patients remaining undiagnosed, this kind of software layered on top of existing imaging infrastructure is emerging as a complementary growth avenue alongside conventional hardware sales.
Table of contents
11 chapters · 106 sections · 289 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Central (Axial) DXA Systems | Peripheral DXA and quantitative ultrasound systems |
| By Application | Osteoporosis and Osteopenia Screening | Fracture risk assessment |
| By End User | Hospitals | Diagnostic imaging centers |
By Product Type
- The Central (Axial) DXA Systems Segment to Dominate the Global Bone Densitometer Market
- The central DXA systems segment is expected to account for the largest share of this market.
- This leading position reflects the status of central DXA as the clinical reference standard for diagnosing osteoporosis, recommended by leading professional bodies for measuring bone mineral density at the hip and lumbar spine, the two skeletal sites most strongly associated with fracture risk and with the greatest clinical consequence when fractured.
- Systems from Hologic, Inc. and GE HealthCare Technologies Inc. anchor this segment in hospital and dedicated radiology settings across developed markets.
- However, the peripheral DXA and quantitative ultrasound systems segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the lower capital and operating cost of peripheral and ultrasound devices relative to central DXA systems, their suitability for deployment in primary care and community screening settings without a dedicated radiology infrastructure, and their radiation light or radiation free operation, which broadens the range of clinical environments in which routine testing can be offered.
By Application
- The osteoporosis and osteopenia screening segment is expected to account for the largest share of this market, reflecting the role of bone densitometry as the primary diagnostic tool used to identify patients with reduced bone mass before a fragility fracture occurs, consistent with CDC surveillance data showing that low bone mass affects more than four in ten U.S. adults aged 50 and over.
- However, the fracture risk assessment segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the increasing use of bone densitometer output as an input to composite fracture risk tools, growing clinical emphasis on identifying patients for pharmacological intervention before a first fracture rather than after, and the integration of bone microarchitecture analysis software that extends the clinical value of a single DXA scan beyond a simple bone density reading.
By End User
- The Hospitals Segment to Hold the Largest Share
- The hospitals segment is expected to account for the largest share of this market, supported by the concentration of central DXA installations within hospital radiology departments and the role of hospitals as the primary site for managing patients following a fragility fracture.
- However, the diagnostic imaging centers segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the expansion of standalone and outpatient imaging center networks in both developed and emerging markets, which are increasingly incorporating bone densitometry alongside other imaging modalities to serve aging patient populations without requiring a hospital visit.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of this market. This leading position is supported by the scale of the region's aging population, with the U.S. Census Bureau reporting that Americans aged 65 and older reached 61.2 million in 2024, and by a long standing Medicare framework covering bone mass measurement for qualifying beneficiaries that has embedded routine bone density testing into standard preventive care for older adults. The presence of leading manufacturers including Hologic, Inc. and GE HealthCare Technologies Inc., together with an established base of hospital and outpatient imaging infrastructure, reinforces the depth of the North American market.
Asia-Pacific
Fastest growthHowever, the Asia Pacific bone densitometer market is expected to grow at the fastest rate from 2026 to 2036. The rapid growth of this market is driven by the scale of population aging across China, Japan, South Korea, and India, and by the International Osteoporosis Foundation's assessment that fracture liaison and secondary prevention infrastructure in the region remains underdeveloped relative to the size of the at risk population, creating substantial headroom for expanded diagnostic capacity. Manufacturers including OsteoSys Co., Ltd., Medonica Co., Ltd., and Nanoomtech Co., Ltd. in South Korea, together with the recent expansion of BPL Medical Technologies' bone mineral density portfolio across India and the Middle East following its acquisition of South Korea based Yozma BMtech, illustrate the growing regional manufacturing and distribution base supporting this growth.
Europe
Europe represents a large and well established market for bone densitometers, supported by national osteoporosis screening guidelines in several member states and by long standing manufacturers including DMS Imaging in France and Echolight S.p.A. in Italy, both of which maintain deep application expertise in the region's hospital and outpatient diagnostic networks.
Middle East & Africa
The Middle East and Africa region represents a smaller but growing market, driven by expanding hospital infrastructure investment in the Gulf states and by distribution partnerships extending established DXA and ultrasound product lines into the region.
Latin America
The Latin America market is supported primarily by hospital and diagnostic center investment in Brazil and Mexico, alongside growing awareness of osteoporosis screening among aging urban populations.
Competitive landscape
- Hologic, Inc.
- GE HealthCare Technologies Inc.
- FUJIFILM Holdings Corporation
Frequently asked questions
The global bone densitometer market is expected to reach USD 600.7 million by 2036 from an estimated USD 398.8 million in 2026, at a CAGR of 4.2% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Bone Densitometer Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-2144). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/bone-densitometer-market-6827