Aerospace and Defense C-Class Parts Market (2025-2032)
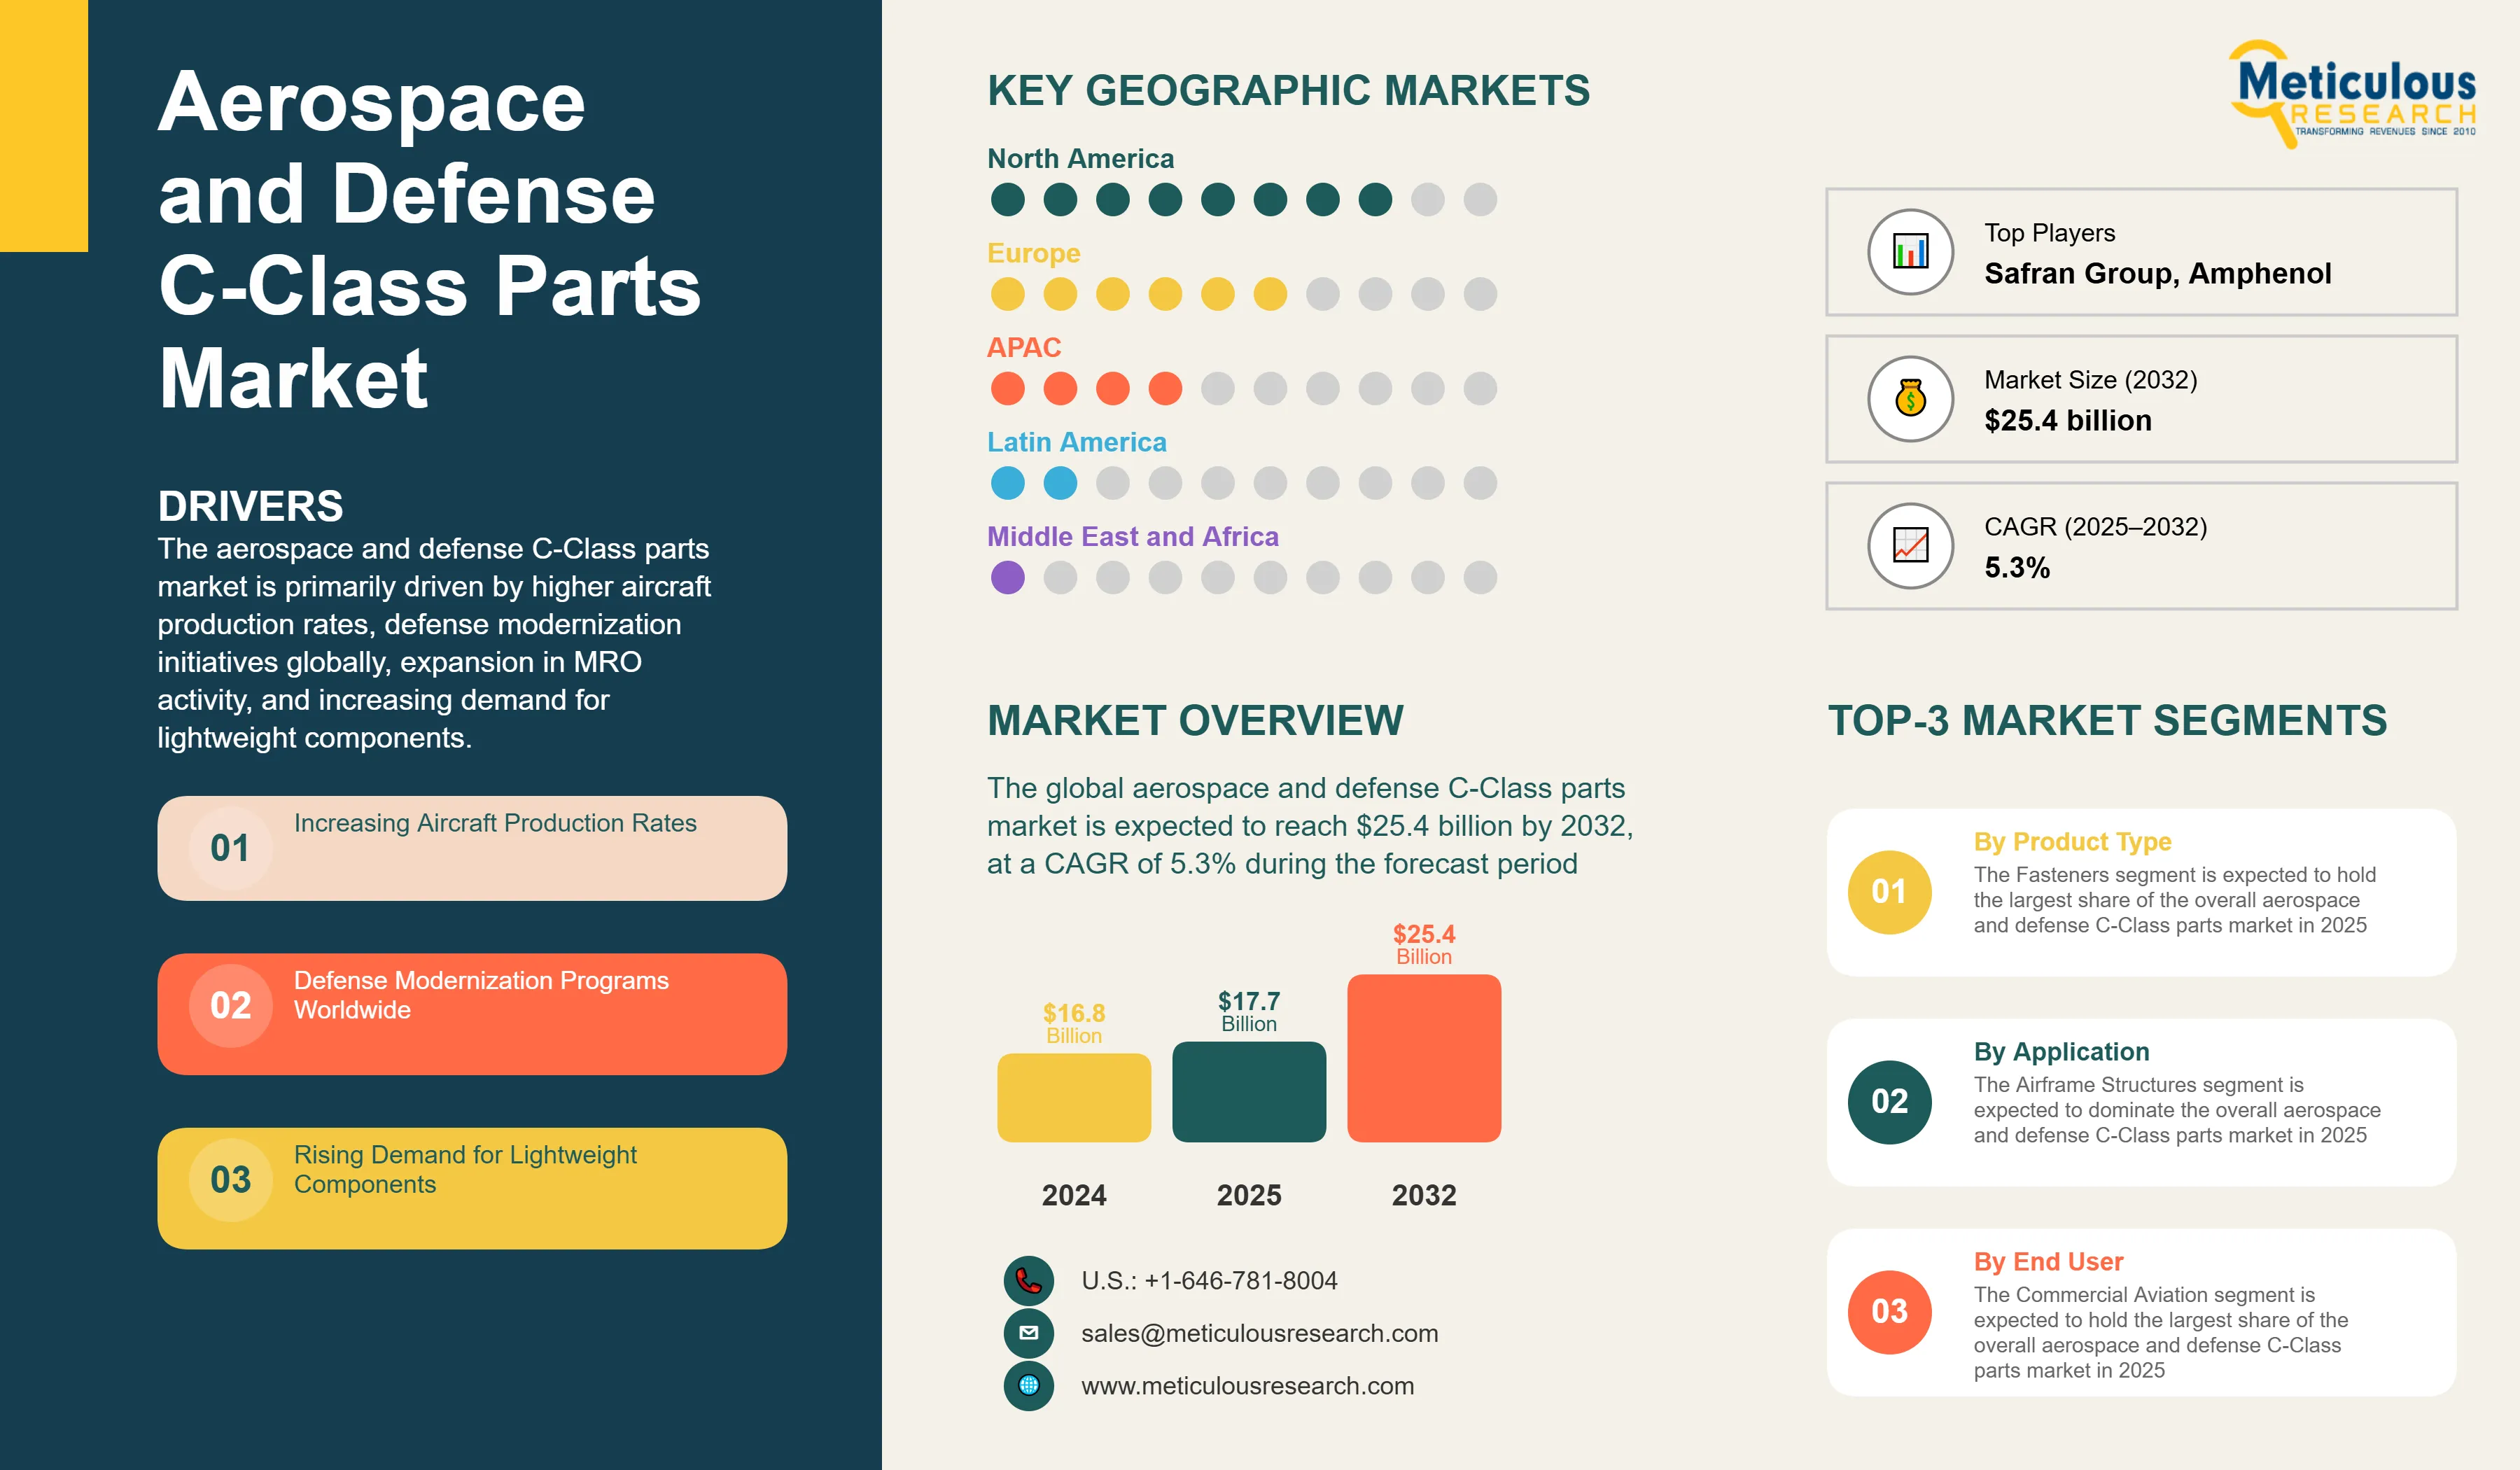
The global aerospace and defense C-Class parts market was valued at $16.8 billion in 2024. This market is expected to reach $25.4 billion by 2032 from an estimated $17.7 billion in 2025, at a CAGR of 5.3% during the forecast period of 2025–2032. Report Overview This comprehensive market research report
- Published
- May 2025
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MRAD - 1041485
- Base year
- 2024
- 2024 · BASELINE
- $16.80B
- 2032
- $25.40B
- CAGR 2025–2032
- 5.3%
2024 baseline · 2025–2032 forecast at 5.3% CAGR · hover a bar for the value
Key highlights
The global aerospace and defense C-Class parts market was valued at $16.8 billion in 2024.
This market is expected to reach $25.4 billion by 2032 from an estimated $17.7 billion in 2025, at a CAGR of 5.3% during the forecast period of 2025–2032.
North America is expected to hold the largest share of the global aerospace and defense C-Class parts market in 2025, attributed to the region's concentration of major aerospace OEMs, substantial defense budgets, advanced manufacturing capabilities, and robust MRO infrastructure.
Europe follows as the second-largest market, supported by the presence of Airbus and other major manufacturers.
However, Asia-Pacific is witnessing the fastest growth rate during the forecast period, primarily driven by rapidly expanding domestic aerospace industries, increasing defense modernization efforts, growing commercial air travel, and substantial investments in manufacturing capabilities.
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 280 |
| Format | PDF & Excel |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 5.3% |
| Market Size (Value)in 2025 | USD 17.7 Billion |
| Market Size (Value) in 2032 | USD 25.4 Billion |
| Segments Covered | By Product Type · Fasteners · Bearings and Bushings · Seals & Gaskets · Electrical and Electronic Components · Fluid System Components · Standard Hardware · Machined & Precision Components · By Application · Airframe Structures · Propulsion Systems · Interior Systems · Flight Control Systems · Landing Gear Systems · Avionics and Electrical Systems · Environmental and Fluid Systems · Weapons and Defense Systems · Spacecraft & Satellite Structures · By End User · Commercial Aviation · Military Aviation · Spacecraft & Satellite Manufacturers · Rotorcraft OEMs · MRO & Aftermarket · By Distribution Channel · OEM Direct Sales · Tier 1/2 Supplier Sales · Aftermarket/Distribution |
| Countries Covered | North America (U.S., Canada) · Europe (Germany, France, U.K., Italy, Spain, Rest of Europe) · Asia-Pacific (Japan, South Korea, Australia, China, India, Rest of Asia-Pacific) · Latin America (Brazil, Mexico, Rest of Latin America) · Middle East & Africa (Saudi Arabia, United Arab Emirates, Rest of Middle East & Africa) |
| Key Companies | Precision Castparts Corp (Berkshire Hathaway), Howmet Aerospace (formerly Arconic), TriMas Corporation, Consolidated Aerospace Manufacturing (CAM), Stanley Black & Decker (Engineered Fastening), Lisi Aerospace, RBC Bearings, Trelleborg Sealing Solutions, TransDigm Group, Eaton Aerospace, Parker Hannifin Corporation, Satcom Direct (Carlisle Companies), Safran Group, Amphenol Corporation, AMG Advanced Metallurgical Group, Barnes Group Inc., Wesco Aircraft (Incora), and KLX Aerospace (Boeing Distribution Services), among others. |
Report overview
Segments covered: product type, application, end-user, distribution channel, end user. Regions: North America.
This comprehensive market research report analyzes the global aerospace and defense C-Class parts market, evaluating how these critical components support aircraft manufacturing, defense systems, and MRO operations across various industries and regions. The report provides a strategic analysis of market dynamics, growth projections till 2032, and competitive positioning across global and regional/country-level markets.
The aerospace and defense C-Class parts market is primarily driven by higher aircraft production rates, defense modernization initiatives globally, expansion in MRO activity, and increasing demand for lightweight components. Advanced materials and digital supply chain technologies are reshaping the industry, while Industry 4.0 technology adoption and integration of value-added services are gaining significant traction. Additionally, supplier consolidation and sustainability initiatives aimed at carbon footprint reduction are further driving market growth, especially in commercial aviation, military applications, and space industry sectors.
Report infographic
Market dynamics
2 factors across 2 forcesThe aerospace and defense C-Class parts
market offers several high-growth opportunities. Advanced materials are substantially enhancing component performance and weight reduction capabilities. Another major opportunity lies in digital supply chain solutions creating new efficiencies beyond traditional procurement methods. Additionally, emerging markets with growing aerospace sectors are opening untapped regional segments for expansion. The market is also benefiting from increased interest in the commercial space industry and advancement of Industry 4.0 technologies specifically designed for aerospace manufacturing.
Table of contents
12 chapters · 147 sections · 280 pages · click to expandGeographic analysis
North America
Largest shareNorth America is expected to hold the largest share of the global aerospace and defense C-Class parts market in 2025, attributed to the region's concentration of major aerospace OEMs, substantial defense budgets, advanced manufacturing capabilities, and robust MRO infrastructure.
Europe
Europe follows as the second-largest market, supported by the presence of Airbus and other major manufacturers.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is witnessing the fastest growth rate during the forecast period, primarily driven by rapidly expanding domestic aerospace industries, increasing defense modernization efforts, growing commercial air travel, and substantial investments in manufacturing capabilities.
Competitive landscape
The global aerospace and defense C-Class parts market features a diverse competitive landscape with established component manufacturers, specialized aerospace suppliers, and diversified industrial groups with aerospace divisions pursuing varied approaches to parts manufacturing and distribution.
Market dynamics are increasingly influenced by key trends such as vertical integration strategies, enhancement of manufacturing technologies, and development of comprehensive supply chain solutions. Leading companies are prioritizing improvements in material science, production efficiency, and certification compliance to address evolving customer requirements and regulatory frameworks.
The key players operating in the global aerospace and defense C-Class parts market include Precision Castparts Corp (Berkshire Hathaway), Howmet Aerospace, TriMas Corporation, Consolidated Aerospace Manufacturing (CAM), Stanley Black & Decker (Engineered Fastening), Lisi Aerospace, RBC Bearings, Trelleborg Sealing Solutions, TransDigm Group, Eaton Aerospace, Parker Hannifin Corporation, Safran Group, Amphenol Corporation, and Wesco Aircraft (Incora) among others.
- Precision Castparts Corp · Berkshire Hathaway
- Howmet Aerospace (formerly Arconic)
- TriMas Corporation
- Consolidated Aerospace Manufacturing (CAM)
- Stanley Black & Decker · Engineered Fastening
- Lisi Aerospace
- RBC Bearings
- Trelleborg Sealing Solutions
- TransDigm Group
- Eaton Aerospace
- Parker Hannifin Corporation
- Satcom Direct · Carlisle Companies
- Safran Group
- Amphenol Corporation
- AMG Advanced Metallurgical Group
- Barnes Group Inc.
- Wesco Aircraft · Incora
- KLX Aerospace (Boeing Distribution Services)
Frequently asked questions
The global aerospace and defense C-Class parts market was valued at $16.8 billion in 2024. This market is expected to reach $25.4 billion by 2032 from an estimated $17.7 billion in 2025, at a CAGR of 5.3% during the forecast period of 2025–2032.
Cite this report
Meticulous Research. (2025). Aerospace and Defense C-Class Parts Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRAD - 1041485). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/aerospace-and-defense-c-class-parts-market-6168