Electric Grid Balancing Services Market (2026-2036)
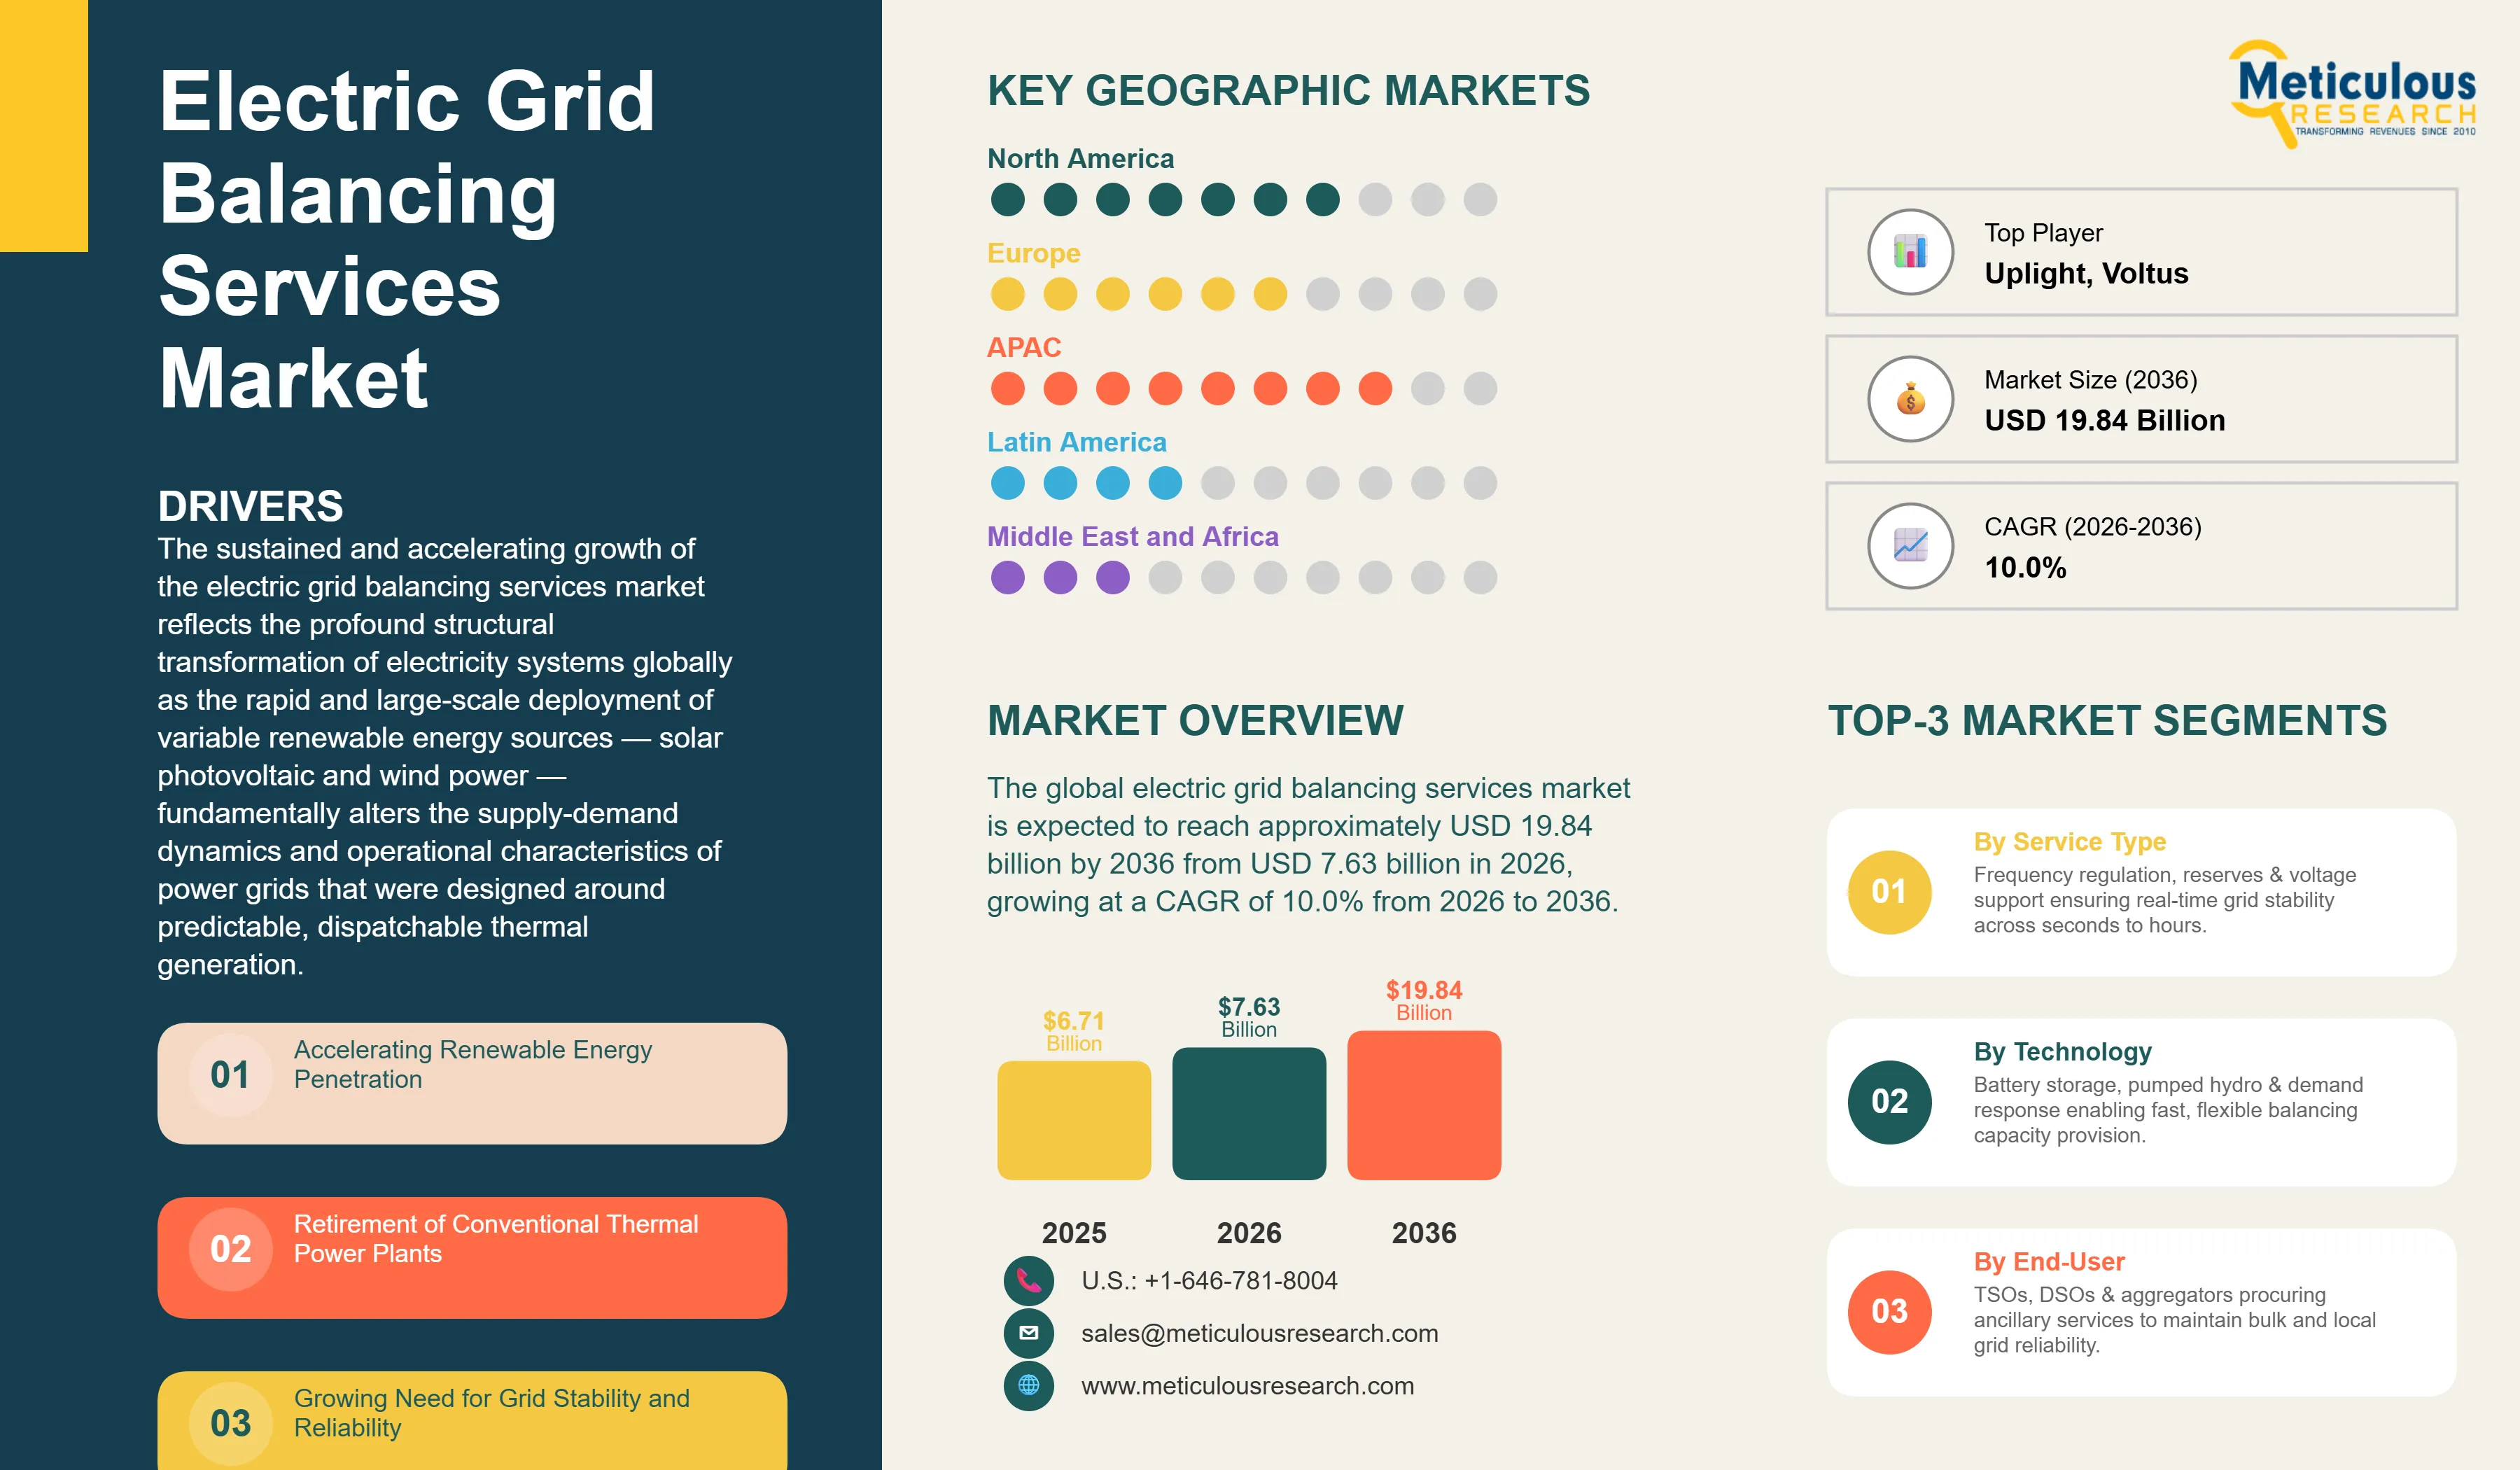
The global electric grid balancing services market was valued at USD 6.71 billion in 2025. The market is expected to reach approximately USD 19.84 billion by 2036 from USD 7.63 billion in 2026, growing at a CAGR of 10.0% from 2026 to 2036.
- Published
- Mar 2026
- Pages
- 279
- Format
- PDF + Excel
- Report ID
- MREP - 1041828
- Base year
- 2025
- 2025 · BASELINE
- $6.71B
- 2036
- $19.84B
- CAGR 2026–2036
- 10.0%
2025 baseline · 2026–2036 forecast at 10.0% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global electric grid balancing services market is projected to reach USD 19.84 billion by 2036.
The market is expected to grow at a CAGR of 10.0% from 2026 to 2036.
Europe dominates the global electric grid balancing services market with the largest market share in 2026, driven by the continent's leading position in renewable energy penetration creating the most acute grid balancing challenges globally, the most mature and well-designed ancillary service market structures providing revenue certainty attracting investment, and supportive regulatory frameworks explicitly creating market mechanisms for battery storage and demand response participation in balancing markets.
Asia-Pacific is expected to witness the fastest growth during the forecast period, supported by China's massive renewable energy deployment creating unprecedented balancing requirements across its national grid, India's accelerating energy transition creating balancing market development needs, and Australia's rapidly evolving National Electricity Market establishing world-leading battery storage ancillary service frameworks that are serving as models for other Asia-Pacific market designs.
By service type, the frequency regulation segment holds the largest market share in 2026, as the most time-critical and highest-value ancillary service, commanding premium pricing for sub-second automated response capability provided by battery storage and fast-response demand resources.
By technology, the battery energy storage systems segment holds the largest and fastest-growing market share in 2026, reflecting BESS systems' unique combination of sub-second response speed, bi-directional capability enabling both injection and absorption, and the ability to stack multiple balancing service revenues from a single asset improving project economics.
By end-user, the transmission system operators segment holds the largest market share in 2026, as the primary procurers of high-value system-critical balancing services including frequency regulation, spinning reserves, and black start capability that maintain bulk power system stability.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 19.84 Billion |
| Market Size in 2026 | USD 7.63 Billion |
| Market Size in 2025 | USD 6.71 Billion |
| Market Growth Rate (2026-2036) | CAGR of 10.0% |
| Format | PDF, Excel & Cloud Portal · 279 pages |
| Dominating Region | Europe |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Service Type, Technology, End-User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: service type, technology, end-user.
The sustained and accelerating growth of the electric grid balancing services market reflects the profound structural transformation of electricity systems globally as the rapid and large-scale deployment of variable renewable energy sources — solar photovoltaic and wind power — fundamentally alters the supply-demand dynamics and operational characteristics of power grids that were designed around predictable, dispatchable thermal generation. Grid balancing services — encompassing the full spectrum of ancillary services that transmission and distribution system operators procure to maintain instantaneous supply-demand equilibrium, voltage stability, frequency within regulatory bounds, and system resilience following contingency events — are experiencing exponentially growing demand as the inertia-free, weather-dependent output profiles of renewable generation create balancing challenges of unprecedented scale and complexity. The simultaneous retirement of conventional thermal power plants that historically provided implicit balancing capability through their inherent rotating mass inertia and dispatchable output control is creating acute system needs for explicitly procured and remunerated balancing services from dedicated storage, demand response, and fast-response generation resources. Battery energy storage systems have emerged as the dominant new balancing technology, combining sub-second response capability far exceeding conventional generation resources with the flexibility to provide multiple balancing service types simultaneously from a single asset — creating compelling economics that are attracting billions in investment and displacing traditional gas peaker plant balancing strategies across high-renewable-penetration markets.
Electric grid balancing services constitute the essential operational services procured by system operators to maintain power system stability in real time, ensuring that electricity supply and demand remain continuously balanced across time scales ranging from sub-seconds to hours, that voltage levels are maintained within statutory limits at all points in the network, and that the system maintains adequate reserves to respond to unexpected generation losses or demand surges without service interruption. The fundamental physics of alternating current power systems — where all generators must operate in precise synchrony and any instantaneous imbalance between supply and demand manifests as frequency deviation from the 50 or 60 Hz system nominal — creates non-negotiable requirements for balancing services that system operators must procure through market mechanisms or regulatory mandates regardless of cost. The market for these services has existed in structured forms since electricity market liberalization in the 1990s and 2000s, but the renewable energy transition is dramatically reshaping both the quantity and characteristics of balancing services required, the technologies best positioned to provide them, and the market designs that efficiently procure them.
The grid balancing services market is structured around distinct service products operating across different timescales and providing different system functions. Frequency containment reserves — the fastest-acting balancing product responding automatically within seconds to frequency deviations — provide the primary defense against large generation losses, with battery storage systems increasingly dominating this segment given their sub-second response speed far exceeding the 5-30 second response requirements of conventional thermal plants. Frequency restoration reserves, operating over 30 seconds to 15 minutes, restore frequency to nominal following containment, with automatic and manual variants served by both battery storage and demand response. Replacement reserves, active over 15 minutes to hours, relieve faster-acting reserves and restore system margin, typically provided by slower-starting thermal plants, pumped hydro, and large demand response programs. Voltage support and reactive power services maintain voltage profiles across transmission and distribution networks, provided by synchronous condensers, static VAR compensators, and increasingly by grid-forming inverters attached to battery storage systems that can provide synthetic inertia alongside reactive power. The expanding scope of distributed energy resource aggregation — enabling collections of residential batteries, electric vehicles, smart appliances, and commercial building energy management systems to collectively provide balancing services through virtual power plant platforms — is democratizing balancing service provision beyond large utility-scale assets toward millions of small distributed resources.
The market design evolution enabling efficient grid balancing is as commercially significant as the technology advancement. European ancillary service markets — particularly the ENTSO-E harmonized products across Continental Europe and the highly developed UK Balancing Mechanism — have established sophisticated procurement frameworks that co-optimize across multiple balancing products, enable cross-border trading of balancing capacity, and provide multi-year capacity contracts giving storage developers revenue certainty for capital investment decisions. Australia's National Electricity Market has pioneered contingency Frequency Control Ancillary Services market designs enabling battery storage to competitively displace gas peakers in high-value regulation services, with Hornsdale Power Reserve and subsequent large-scale battery projects demonstrating transformational economics. US organized wholesale markets including PJM, MISO, CAISO, and ISO-NE have evolved performance-based frequency regulation market designs that explicitly value the fast response capability of battery storage at premium prices, creating investable revenue streams that have catalyzed gigawatt-scale BESS deployment for grid balancing purposes across North America.
Report infographic
Market dynamics
4 factors across 3 forcesAccelerating Renewable Energy Penetration and Grid Stability Imperatives
The primary and most powerful driver of grid balancing services market growth is the unprecedented acceleration of renewable energy deployment globally that is transforming the operational characteristics of electricity systems in ways that dramatically increase the quantity and diversity of balancing services required. The International Energy Agency projects global solar and wind capacity additions exceeding 7,300 GW between 2024 and 2030 — representing more than a doubling of current renewable capacity in six years — with penetration reaching 40-60% of electricity generation in leading markets including Germany, Denmark, Spain, and California. This penetration level creates fundamental grid stability challenges that require systematic balancing service procurement at scales far exceeding historical requirements: solar generation creates steep morning ramp-up and evening ramp-down events — the California Independent System Operator's famous duck curve — requiring fast-ramping balancing resources capable of following multi-gigawatt generation swings within hours; wind variability creates minute-to-minute power fluctuations requiring continuous fast frequency regulation; and the displacement of synchronous thermal generators by inverter-based renewable generation reduces system inertia, making frequency excursions following generation loss events faster and deeper, requiring faster-responding frequency containment reserves. Grid operators including National Grid ESO (UK), REE (Spain), ELIA (Belgium), and Amprion (Germany) have published quantified balancing service procurement increases of 50-200% over 5-year planning horizons tied directly to renewable penetration growth targets, providing concrete market volume projections that enable storage developer and demand response aggregator investment planning.
Table of contents
10 chapters · 116 sections · 279 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Service Type | Frequency Regulation | — |
| By Technology | Battery Energy Storage | Battery energy storage systems |
| By End-User | Transmission System Operators | Energy aggregators and VPP operators |
By Service Type
- Frequency regulation services command approximately 32-36% of total grid balancing services market revenue in 2026, reflecting their position as the most time-critical and highest-value ancillary service product — where instantaneous automated response capability in the sub-second to 30-second timeframe commands substantial price premiums over slower-acting reserves.
- Frequency regulation encompasses the automatic governor response and automated frequency restoration services that defend system frequency within statutory bands following any generation-load imbalance event, with market prices reflecting both the scarcity value of fast-response capability and the performance incentives that reward response accuracy and speed.
- Battery energy storage systems have become the dominant technology for frequency regulation in developed markets due to their exceptional performance characteristics — providing precisely calibrated power injection or absorption within 100-300 milliseconds, far exceeding the 5-30 second response times of gas turbines and steam generators — with PJM's performance-based frequency regulation market design explicitly pricing this speed advantage through performance scores that result in battery storage earning 2-4 times the revenue per MW of capacity compared to conventional generation.
- The spinning reserves service segment represents the second-largest revenue category, encompassing the synchronized generation capacity maintained at partial load ready to increase output within 10 minutes following a contingency event — traditionally provided by thermal generation running below full capacity but increasingly co-located with battery storage that provides the first 30-seconds of response while conventional reserves are ramping.
- Black start services — the capability to restart a power system following complete blackout without external power supply — represent a high-value niche balancing service where large-scale battery storage is emerging as a technically superior alternative to conventional diesel generators and gas turbines in isolated and renewable-heavy systems.
By Technology
- Battery energy storage systems represent approximately 40-45% of grid balancing services technology market revenue in 2026 and demonstrate the highest growth rate at approximately 13-15% CAGR — reflecting the combination of superior technical performance across multiple balancing service types, rapidly declining capital costs, and revenue stacking business models that aggregate multiple simultaneous balancing service revenue streams from single assets to deliver compelling investor returns.
- Lithium-ion chemistry — predominantly lithium iron phosphate (LFP) for stationary grid applications given its superior cycle life, thermal stability, and acceptable energy density — dominates BESS deployments for grid balancing, with utility-scale systems ranging from 10 MW/20 MWh to 1,000 MW/4,000 MWh operating at increasingly competitive levelized costs.
- The revenue stacking business model that defines BESS grid balancing economics combines frequency regulation revenue (typically the highest per-MW revenue stream), spinning reserve capacity payments, energy arbitrage revenue from wholesale price spread exploitation, and capacity market revenue where available — with sophisticated asset optimization software from companies including Fluence, Modo Energy, and REstore continuously optimizing dispatch across all revenue streams while managing battery state of charge and health constraints.
- Pumped hydro storage remains the largest installed capacity of grid balancing technology globally — representing approximately 90% of utility energy storage worldwide — but faces limited growth due to geographic constraints and multi-decade development timelines, maintaining its position as the dominant long-duration balancing technology while battery storage captures the growth in faster-responding short-duration services.
- Demand-side management platforms enabling industrial and commercial load flexibility represent a significant and growing technology segment, with software platforms aggregating controllable industrial processes, commercial building systems, and increasingly residential smart appliances into demand response portfolios providing balancing services at marginal cost for loads that would curtail or shift operations for grid payments.
By End-User
- Transmission system operators account for approximately 48-52% of grid balancing services market revenue in 2026, reflecting their role as the primary procurers of the highest-value system-critical balancing services — frequency regulation, spinning and non-spinning reserves, black start, and voltage support — that maintain bulk power system stability and security of supply across national and regional transmission grids.
- TSOs including National Grid ESO (UK), RTE (France), ELIA (Belgium), TenneT (Netherlands/Germany), REE (Spain), and CAISO (California) operate transparent competitive procurement processes for balancing services through tendering, capacity auctions, and real-time balancing markets that have become increasingly important revenue streams for battery storage and demand response asset owners.
- The distribution system operator end-user segment is growing rapidly at approximately 13-15% CAGR as increasing distributed energy resource penetration at distribution voltage levels creates local congestion, voltage violation, and power quality balancing challenges that distribution networks have not historically been designed to manage, requiring DSO-procured flexibility services from local distributed assets.
- Independent power producers utilizing battery storage assets for revenue stacking across multiple balancing service markets represent a growing commercial segment as specialized storage developers including Gresham House Energy Storage Fund, Harmony Energy, Zenobe Energy, and international players including Fluence's asset management division develop and operate merchant battery storage portfolios optimized for multi-service balancing revenue.
- Energy aggregators and VPP operators are the fastest-growing end-user category at approximately 16-18% CAGR, reflecting the platform business model advantages of aggregating diverse distributed resources into scalable balancing service portfolios with marginal cost advantages over utility-scale alternatives.
Geographic analysis
Europe
Europe holds approximately 38-42% of the global electric grid balancing services market in 2026, driven by the continent's leading renewable energy penetration creating the most acute grid balancing challenges globally combined with the most mature and commercially sophisticated ancillary service market structures that efficiently procure and remunerate balancing service provision. The UK's balancing mechanism represents one of the world's most developed balancing service markets, with National Grid ESO procuring multiple product types through competitive tenders that have catalyzed over 3 GW of battery storage deployment specifically for frequency regulation and fast reserve services. Germany's grid balancing market — managed by four transmission operators Amprion, TenneT, 50Hertz, and TransnetBW — has undergone substantial reform to accommodate growing renewable penetration, with the aFRR (automatic Frequency Restoration Reserve) and mFRR (manual FRR) products providing multi-hundred-million euro annual procurement volumes attracting significant battery storage and demand response investment. The ENTSO-E Framework Guidelines on Electricity Balancing and the subsequent Network Code on Electricity Balancing are driving harmonization of European balancing market designs — enabling cross-border balancing capacity trading through the PICASSO and MARI platforms — creating a progressively integrated European balancing market that improves procurement efficiency and provides larger revenue certainty for balancing service investors across member states. Nordic countries, led by Denmark and Sweden with wind penetration exceeding 50% of annual generation, demonstrate the most sophisticated balancing market operations globally, with Energinet and Svenska Kraftnat procuring diverse balancing products across timescales with advanced merit-order optimization that is increasingly serving as a global reference design for balancing market development.
Asia-Pacific
Asia-Pacific demonstrates the highest regional growth rate at approximately 12-14% CAGR, propelled by China's extraordinary renewable energy deployment scale creating the world's most rapidly growing grid balancing requirement, Australia's pioneering battery storage balancing market demonstrating transformational economics that is inspiring regional replication, and India's emerging balancing market development responding to the renewable energy transition. China's State Grid Corporation and China Southern Grid are operating the world's largest grid balancing challenge — managing over 700 GW of installed renewable capacity across vast geographic transmission distances — with the National Development and Reform Commission developing comprehensive energy storage market frameworks that will create tens of gigawatts of grid balancing storage deployment through mandatory storage co-location requirements with renewable projects and explicit ancillary service market compensation mechanisms. Australia's National Electricity Market has become a global laboratory for battery storage grid balancing economics, with projects including the Hornsdale Power Reserve, Victoria Big Battery, and multiple subsequent large-scale BESS deployments demonstrating that battery storage can reduce frequency regulation costs, capture substantial ancillary service revenues, and improve system reliability outcomes simultaneously — attracting over AUD 10 billion in announced battery storage investment for grid balancing purposes. Japan's electricity system balancing market is evolving in response to the post-Fukushima energy policy transformation that has rapidly increased renewable penetration while retiring nuclear baseload, with the Japan Electric Power Exchange developing capacity market and balancing service procurement frameworks that are catalyzing battery storage deployment by independent power producers and vertically integrated utilities.
Competitive landscape
- AutoGrid Systems
- Uplight (formerly Enbala)
- Voltus
- CPower Energy Management
- OhmConnect
- REstore · Honeywell
Frequently asked questions
The global electric grid balancing services market is expected to grow from USD 7.63 billion in 2026 to USD 19.84 billion by 2036.
Cite this report
Meticulous Research. (2026). Electric Grid Balancing Services Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MREP - 1041828). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/electric-grid-balancing-services-market-6511