Agricultural Biologicals Market (2026-2036)
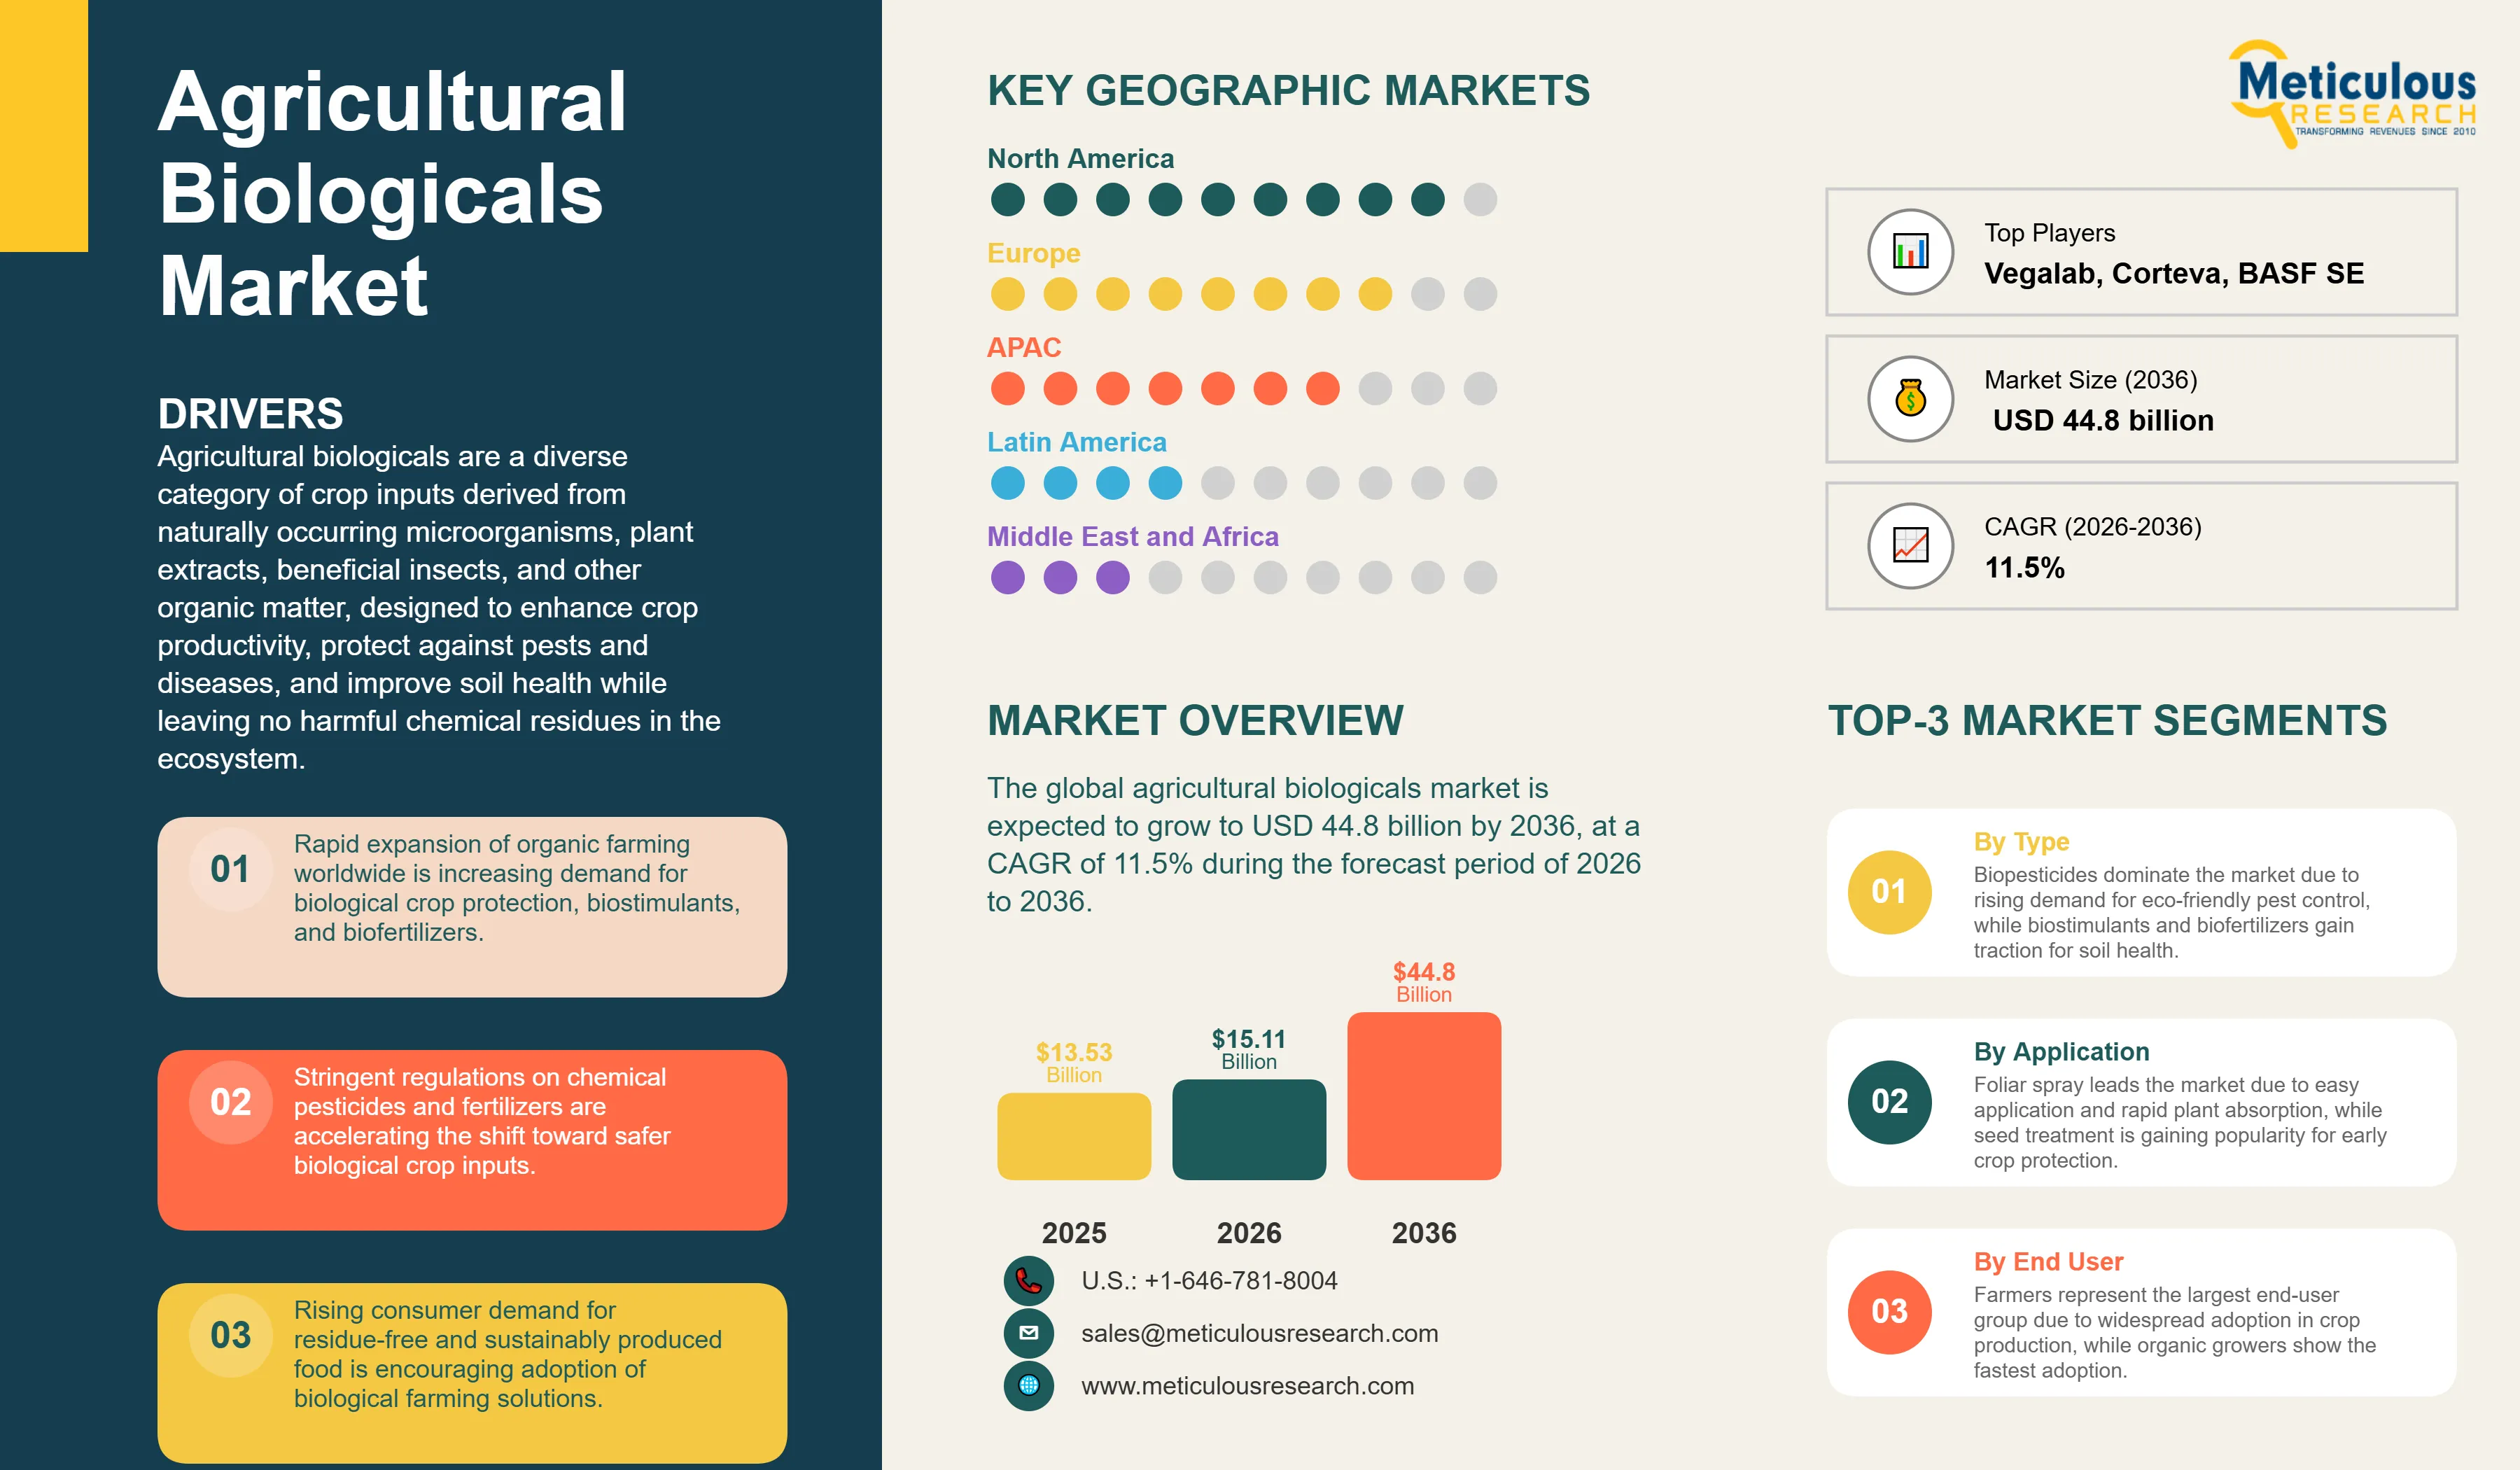
The global agricultural biologicals market was valued at USD 13.53 billion in 2025 and is projected to reach USD 15.11 billion in 2026. The market is expected to grow to USD 44.8 billion by 2036, at a CAGR of 11.5% during the forecast period of 2026 to 2036.
- Published
- Mar 2026
- Pages
- 275
- Format
- PDF + Excel
- Report ID
- MR-628
- Base year
- 2025
- 2025 · BASELINE
- $13.53B
- 2036
- $44.80B
- CAGR 2026–2036
- 11.5%
2025 baseline · 2026–2036 forecast at 11.5% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global agricultural biologicals market is projected to reach USD 44.8 billion by 2036, growing at a CAGR of 11.5% during the forecast period of 2026 to 2036.
North America is expected to account for the largest share of the global agricultural biologicals market in 2026, driven by strong regulatory frameworks for biological crop protection products and high adoption of sustainable farming practices.
Latin America is projected to grow at the highest CAGR during the forecast period, driven by large-scale agricultural production and increasing adoption of biological crop inputs in major export crops.
Europe is the second-largest regional market, driven by stringent environmental regulations and expanding organic farming activities.
By product type, biopesticides are expected to account for the largest share of the market in 2026, while the biostimulants segment is projected to grow at the highest CAGR during the forecast period.
By source, the microbial segment is expected to account for the largest share of the overall agricultural biologicals market in 2026.
By farming type, conventional farming is expected to account for the largest share of the overall agricultural biologicals market, while organic farming is expected to grow at the highest CAGR through 2036.
By mode of application, seed treatment is expected to grow at the highest CAGR during the forecast period.
By crop type, the cereals & grains segment is expected to account for the largest share of the overall agricultural biologicals market.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 44.8 Billion |
| Market Size in 2025 (Base Year) | USD 13.53 Billion |
| Market Size in 2026 | USD 15.11 Billion |
| Market Growth Rate (2026–2036) | CAGR of 11.5% |
| Format | PDF, Excel & Cloud Portal · 275 pages |
| Dominating Region (2026) | North America |
| Fastest Growing Region | Latin America |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | By Product Type: Biopesticides (Bioinsecticides, Biofungicides, Bionematicides, Bioherbicides, Other Biopesticides), Biostimulants, Biofertilizers · By Source: Microbial (Bacteria, Fungi, Viruses, Other Microorganisms), Biochemical, Semiochemicals, Other Sources · By Formulation: Liquid, Dry · By Mode of Application: Foliar Spray, Seed Treatment, Soil Treatment, Post-harvest, Other Modes · By Farming Type: Conventional Farming, Organic Farming · By Crop Type: Fruits & Vegetables, Cereals & Grains (Corn, Wheat, Rice, Other Cereals & Grains), Oilseeds & Pulses, Other Crop Types · By Geography: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | North America (U.S., Canada); Europe (Germany, France, Italy, Spain, U.K., Netherlands, Rest of Europe); Asia-Pacific (China, India, Japan, Australia, South Korea, Indonesia, Philippines, Rest of Asia-Pacific); Latin America (Brazil, Mexico, Argentina, Chile, Rest of Latin America); Middle East & Africa |
| Key Companies | Bayer AG (Germany), BASF SE (Germany), Syngenta AG (Switzerland), Corteva, Inc. (U.S.), FMC Corporation (U.S.), UPL Limited (India), Novonesis Group (Denmark), Koppert B.V. (Netherlands), Valent BioSciences LLC (U.S.), Lallemand Inc. (Canada), Andermatt Group AG (Switzerland), Bioceres Crop Solutions Corp. (Argentina), Certis Biologicals LLC (U.S.), Gowan Company LLC (U.S.), Rovensa Next (Spain), IPL Biologicals Limited (India), Seipasa S.A. (Spain), W. Neudorff GmbH KG (Germany), Rizobacter S.A. (Argentina), Vegalab SA (Switzerland), and others |
Report overview
Segments covered: product type, source, formulation, mode of application, farming type, crop type. Regions: North America, Europe, Asia-Pacific, Latin America.
Agricultural biologicals are a diverse category of crop inputs derived from naturally occurring microorganisms, plant extracts, beneficial insects, and other organic matter, designed to enhance crop productivity, protect against pests and diseases, and improve soil health while leaving no harmful chemical residues in the ecosystem. The category includes three principal product segments, namely biopesticides, biostimulants, and biofertilizers. Agricultural biologicals are widely recognized as critical enablers of sustainable agriculture, organic farming, and integrated pest management (IPM) systems, positioning them as essential tools in the global transition away from dependence on synthetic agrochemicals.
The agricultural biologicals market is primarily driven by the rapid expansion of organic farming worldwide. Organic agriculture is now practiced in more than 183 countries, with over 99 million hectares of agricultural land managed organically by at least 4.5 million farmers globally, thereby significantly increasing the demand for biologically derived crop protection and plant nutrition solutions.
In addition, the stringent regulations on synthetic pesticides and chemical fertilizers across major agricultural markets is driving the adoption of biological crop inputs. Growing consumer demand for residue-free and sustainably produced food products is further encouraging growers to adopt integrated pest management (IPM) practices and biological crop protection solutions. At the same time, climate change–induced crop stress, including drought, soil degradation, and nutrient imbalance, is driving the adoption of biostimulants and microbial-based plant health solutions that enhance crop resilience and improve nutrient-use efficiency.
The market is also witnessing increasing innovation and investment activity. Over 1,300 patents related to agricultural biologicals have been filed globally over the past five years, with around three-quarters focused on the development of novel biological crop solutions, showcasing the strong innovation momentum in this sector. In addition, a growing number of strategic collaborations, licensing agreements, and product development partnerships between large crop protection companies and specialized biologicals developers is further driving technological advancement and commercialization in the market.
Report infographic
Biostimulants: Fastest-Growing Product Type
The biostimulants segment is expected to grow at the highest CAGR among the three product types during the forecast period, driven by the growing importance of abiotic stress management (drought, heat, salinity) in the context of climate change, the expansion of organic farming, and the increasing scientific understanding of plant-microbiome interactions. Seaweed-based biostimulants, protein hydrolysate-based products, humic and fulvic acid formulations, and microbial biostimulants (including mycorrhizal fungi and plant growth-promoting rhizobacteria) are all experiencing strong commercial growth.
The EU’s Fertilizing Products Regulation (FPR), which created a harmonized EU-wide regulatory framework for biostimulants upon entering into force in July 2022, has significantly improved market access for innovative biostimulant products across Europe. Yara’s launch of its YaraAmplix biostimulant portfolio in 2024 illustrates the entry of major conventional fertilizer companies into the biostimulant space.
Biofertilizers: Rapid Growth in Emerging Markets
The biofertilizers market is expected to grow significantly in Asia-Pacific and Latin America, where the economics of biological nitrogen fixation and phosphate solubilization are most compelling, given high synthetic fertilizer prices, small farm sizes, and government programs supporting adoption of biofertilizer. Rhizobium-based biofertilizers for legume production is the highest-volume category within biofertilizers globally, with substantial markets in soybean production across Brazil, Argentina, and the U.S. Mycorrhizal biofertilizers market is also gaining traction in specialty crops, organic farming, and land restoration programs. In India, government subsidies and the National Mission for Sustainable Agriculture continue to drive biofertilizer penetration into smallholder farming systems.
Market dynamics
4 factors across 2 forcesGrowth in Organic Farming and Rising Demand for Organic Food
The rapid expansion of organic farming worldwide is one of the key drivers of the agricultural biologicals market. Organic farming systems rely heavily on biological crop protection products, biofertilizers, and biostimulants for pest management, plant nutrition, and soil health improvement. As a result, the expansion of certified organic farmland directly increases demand for biological agricultural inputs.
According to the latest global organic agriculture statistics published by FiBL and IFOAM – Organics International, organic agriculture is practiced in 183 countries, with around 99 million hectares of agricultural land managed organically worldwide. In parallel, global retail sales of organic food and beverages reached €145 billion in 2024, highlighting strong consumer demand for organically produced food products.
Policy initiatives are also driving the transition toward sustainable farming systems. For example, the European Union’s Farm to Fork Strategy targets a 50% reduction in chemical pesticide use by 2030 and aims to expand organic farmland to 25% of total EU agricultural land, creating long-term demand for biological crop protection and plant nutrition products
Increasing Government Initiatives and Regulatory Frameworks Supporting Biologicals
Government policies and regulatory frameworks are increasingly driving the development and commercialization of agricultural biologicals. Several countries are streamlining regulatory approval processes for biological crop protection products while simultaneously tightening restrictions on synthetic pesticides.
In the U.S., the Environmental Protection Agency (EPA) Office of Pesticide Programs' Biopesticides and Pollution Prevention Division (BPPD) regulates biological pesticides, offering a dedicated pathway that enables faster registration, often under one year, compared to over three years for conventional chemical pesticides.
Emerging agricultural economies are also promoting the use of biological inputs. In India, government programs led by the Ministry of Agriculture and Farmers Welfare and the Department of Biotechnology (DBT) support biofertilizers and biopesticides through research grants, production incentives like Rs. 15,000/ha under PKVY, and laboratory infrastructure. Similarly, national initiatives in China, including the Ministry of Agriculture and Rural Affairs (MARA) approvals for new biopesticides and "zero growth" policies on chemical pesticides achieved ahead of 2020 targets, encourage the adoption of biological inputs in large-scale production.In Brazil, regulatory initiatives by the Ministry of Agriculture and Livestock (MAPA), including the Bioinputs Law and 162 biological registrations in 2025 (14.5 months average approval), have accelerated approvals for biological crop protection products in one of the world’s largest agricultural economies.
Table of contents
14 chapters · 169 sections · 275 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Biopesticides | Biostimulants |
| By Source | Microbial source | — |
| By Formulation | Liquid formulations | Liquid |
| By Mode of Application | Foliar spray | Seed Treatment |
| By Crop Type | Fruits & vegetables crop type | — |
By Product Type
- The agricultural biologicals market includes all biological crop inputs derived from naturally occurring microorganisms, plant extracts, beneficial insects, and other organic matter that are used in crop production to improve yield, protect against pests and diseases, enhance soil health, and stimulate plant growth.
- The market is segmented by product type, source, formulation, mode of application, farming type, crop type, and geography.
- Market sizing includes both volume (metric tons) and value (USD) where applicable, with value data provided across all segments and volume data provided for product type and geography segments.
- Biopesticides is expected to account for the largest share of the global agricultural biologicals market in 2026.
- The largest share of this segment is primarily attributed to the universal need for crop protection across all agricultural systems, the growing regulatory and market pressure to reduce reliance on synthetic pesticides, and the proven commercial efficacy of established microbial biopesticide products.
- Bacillus thuringiensis (Bt) formulations remain the highest-volume biopesticide globally, with application across caterpillar and beetle pest management in vegetables, fruits, corn, and cotton.
- Bioinsecticides (including Bt-based, entomopathogenic fungal, and baculovirus products) dominate within biopesticides, followed by biofungicides (Trichoderma, Bacillus subtilis, and other biocontrol agents), which are growing rapidly in response to the increasing prevalence of fungicide resistance in key foliar pathogens.
- Bionematicides are one of the highest-growth sub-segments, primarily driven by the regulatory restrictions of chemical nematicides and the agronomic importance of nematode management in high-value fruit, vegetable, and specialty crop production.
By Source
- Microbials: Largest and Fastest-Growing Source Segment
- The microbial source segment is expected to account for the largest share of the global agricultural biologicals market in 2026, and is also projected to grow at the highest CAGR from 2026 to 2036.
- This is mainly due to their broad applicability across all three product categories (biopesticides, biostimulants, biofertilizers), their superior selectivity and safety profile compared to chemical alternatives, minimal pre-harvest interval and re-entry period requirements, and compatibility with organic certification standards.
- Key microbial active ingredients include Bacillus thuringiensis, Bacillus subtilis, Bacillus firmus, Trichoderma species, Beauveria bassiana, Metarhizium anisopliae, Rhizobium species, Azotobacter species, Pseudomonas fluorescens, and mycorrhizal fungi.
- AI-enabled strain discovery and CRISPR-based microbial engineering are continuously expanding the functional and commercial performance of the microbial segment.
By Formulation
- Liquid Formulations: Largest Share and Highest CAGR
- The liquid formulations segment is expected to account for the largest share of the agricultural biologicals market in 2026, driven by their superior compatibility with modern irrigation technologies (drip and sprinkler systems), more uniform and easy application characteristics, longer effective duration (up to 6 months versus up to 3 months for dry formulations), and better compatibility with foliar spray application equipment.
- Liquid formulations are well-suited for fermentation-derived microbial products where maintaining cell viability in liquid suspension allows for more flexible handling and application timing.
- The liquid segment is also expected to grow at the highest CAGR during the forecast period, driven by the ongoing expansion of drip and sprinkler irrigation infrastructure in major agricultural markets and the growing preference among commercial growers for liquid biological inputs that can be tank-mixed with conventional crop protection products.
By Mode of Application
- Foliar Spray: Largest Market Share in 2026
- Foliar spray is expected to account for the largest share of the global agricultural biologicals market in 2026, driven by the advantages of foliar spray technique, including uniform biochemical distribution across the plant canopy, efficient use of biopesticide active ingredients, minimal to no wastage of biological materials, and compatibility with standard spray application equipment already owned by most commercial growers.
- The foliar spray segment is mainly dominant for biofungicide, bioinsecticide, and biostimulant applications in high-value fruit, vegetable, and specialty crop production, where frequent applications through the growing season justify the efficiency and precision of liquid foliar delivery.
- Seed Treatment: Fastest-Growing Mode of Application
- The seed treatment segment is projected to grow at the highest CAGR among all modes of application during the forecast period, mainly due to the accelerating regulatory phase-out of neonicotinoid seed treatment insecticides across major markets creating replacement demand for biological alternatives; the agronomic advantages of biological seed treatments (rhizosphere colonization for nutrition support, systemic resistance induction, early-season protection, enhanced germination and seedling vigor); the adoption of precision coating and film-forming seed treatment technologies that maximize biological active ingredient adhesion and uniform distribution on seed surfaces; and the growing farmer preference for “one-step” seed treatments that deliver multiple biological benefits simultaneously.
By Crop Type
- Fruits & Vegetables: Largest Crop Type Segment
- The fruits & vegetables crop type segment is expected to account for the largest share of the global agricultural biologicals market in 2026, driven by the high value per hectare of horticultural crops, the stringent MRL requirements for fresh produce in premium export markets, the diversity of pest and disease pressures in horticultural production requiring multiple biological tools, and the growing consumer demand for organic and residue-free fresh produce globally.
- Cereals & Grains: High-Growth Segment with Large Volume Opportunity
- The cereals & grains segment is emerging as one of the highest-value growth opportunities for agricultural biologicals.
- The growth of biologicals market for cereals & grains is mainly attributed to the huge global acreage under major cereal crops (corn, wheat, rice, barley, sorghum) and the rapidly improving cost-effectiveness of biological inputs for large-scale commodity production.
Geographic analysis
North America
Largest shareNorth America is expected to account for the largest share of the global agricultural biologicals market in 2026. The U.S. is the dominant national market, driven by the world’s most advanced and well-funded commercial biologicals industry, strong EPA regulatory support for biopesticide registration (including expedited review timelines), high organic food market penetration, extensive use of biological inputs in high-value horticultural and specialty crop production, and a well-developed distribution infrastructure. North America: Largest Regional Market
Latin America
Fastest growthLatin America is projected to grow at the highest CAGR during the forecast period, driven by the unique combination of massive agricultural scale with Brazil alone is the world’s largest exporter of soybeans, corn, beef, sugar, and coffee; rapid growth in the adoption of domestic biologicals within commodity crop production systems; supportive regulatory frameworks; and the dynamics of intense competition among global and regional biological companies vying for dominant positions in the world’s most strategically important emerging biologicals market. Brazil is the largest agricultural biologicals market in Latin America and one of the fastest-growing globally. Recent regulatory developments illustrate continued support for innovation, including the May 2024 approval by Brazil’s Ministry of Agriculture and Livestock (MAPA) of three bio-insecticidal and bio-nematicidal products developed by Bioceres Crop Solutions using its Burkholderia-based platform. Latin America: Fastest-Growing Regional Market for Agricultural Biologicals
Competitive landscape
- BASF SE · Germany
- Syngenta AG · Switzerland
- Corteva, Inc. (U.S.)
- FMC Corporation (U.S.)
- UPL Limited · India
- Sumitomo Chemical Co., Ltd. · Japan
- Novonesis Group · Denmark
- Koppert Biological Systems · Netherlands
- Valent BioSciences LLC (U.S.)
- Lallemand Inc. · Canada
- Andermatt Group AG · Switzerland
- Bioceres Crop Solutions Corp. · Argentina
- Certis Biologicals LLC (U.S.)
- Gowan Company LLC (U.S.)
- Rovensa Next · Spain
- IPL Biologicals Limited · India
- Seipasa S.A. · Spain
- W. Neudorff GmbH KG · Germany
- Rizobacter S.A. · Argentina
- Vegalab SA · Switzerland
- Som Phytopharma India Limited · India
Frequently asked questions
Agricultural biologicals are naturally derived crop inputs, including biopesticides, biostimulants, and biofertilizers, used to manage pests and diseases, improve soil health, and enhance crop productivity. This study provides market insights and forecasts by product type and geography (value and volume) and by source, formulation, mode of application, farming type, and crop type (value).
Cite this report
Meticulous Research. (2026). Agricultural Biologicals Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MR-628). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/agricultural-biologicals-market-5314