Advanced Automotive Diagnostic Tools Market (2026-2036)
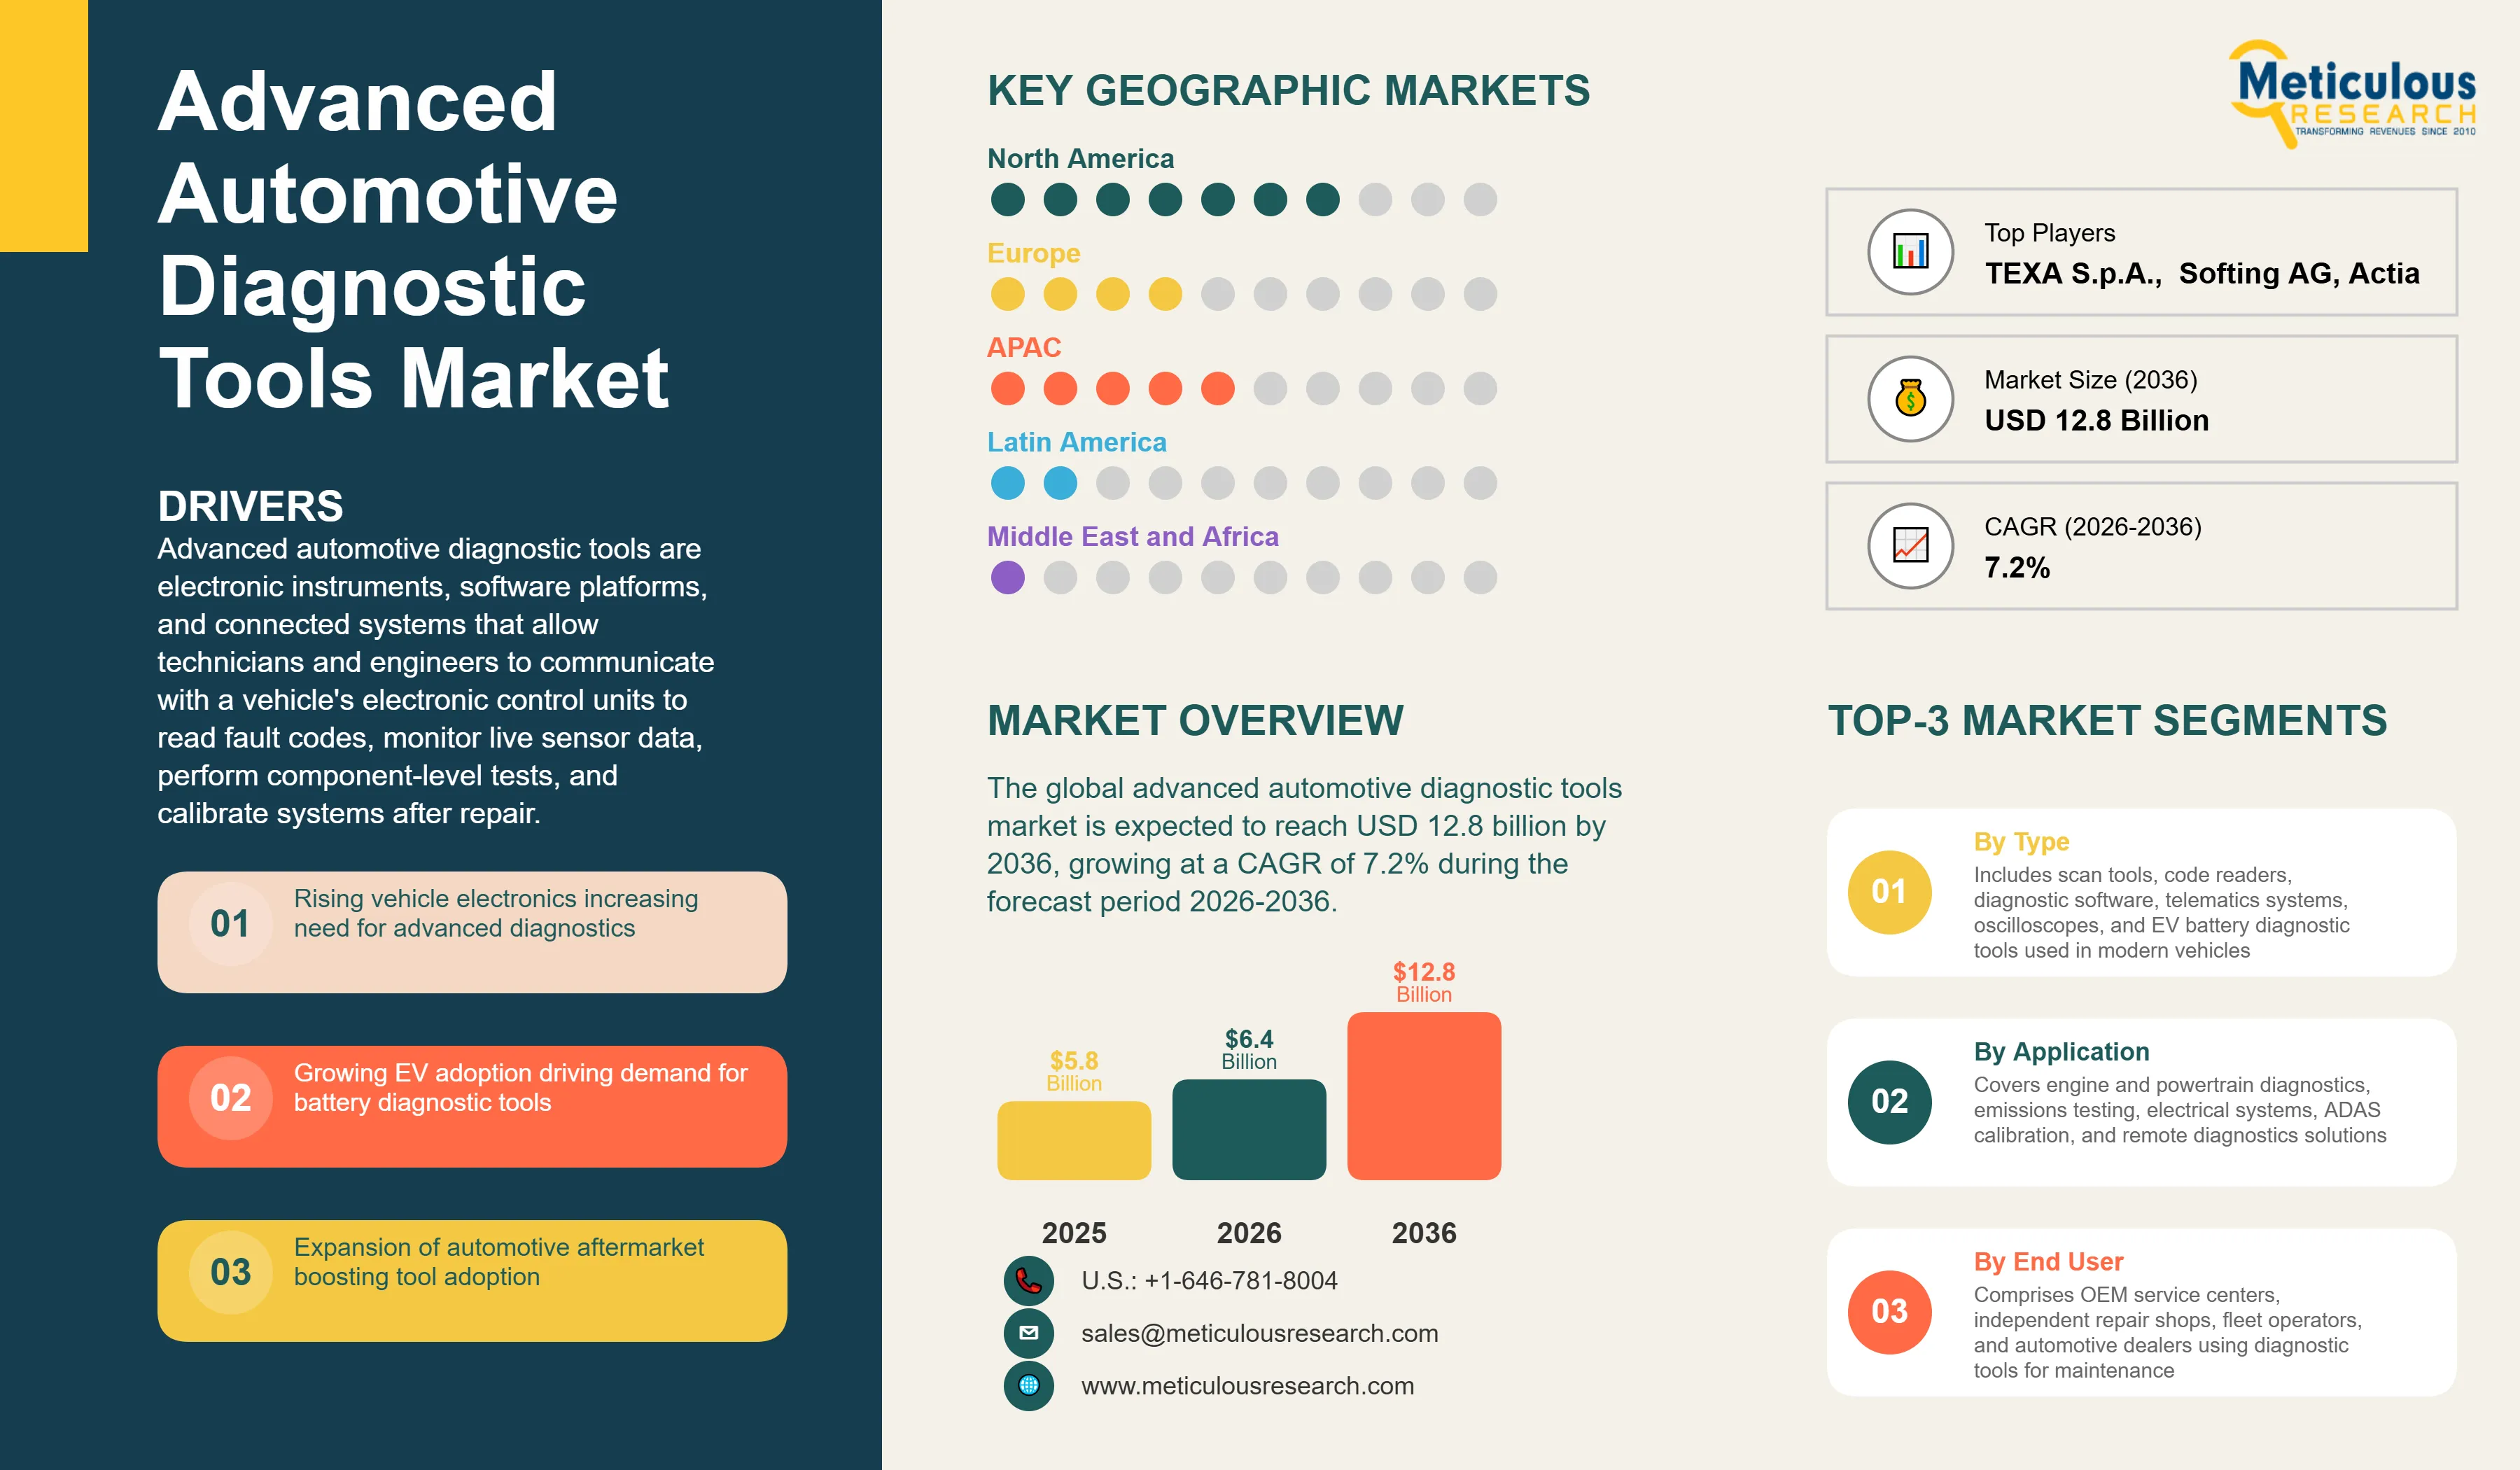
The global advanced automotive diagnostic tools market was valued at USD 5.8 billion in 2025. This market is expected to reach USD 12.8 billion by 2036 from an estimated USD 6.4 billion in 2026, growing at a CAGR of 7.2% during the forecast period 2026-2036.
- Published
- May 2026
- Pages
- 285
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041953
- Base year
- 2025
- 2025 · BASELINE
- $5.80B
- 2036
- $12.80B
- CAGR 2026–2036
- 7.2%
2025 baseline · 2026–2036 forecast at 7.2% CAGR · hover a bar for the value
Key highlights
The global advanced automotive diagnostic tools market is projected to reach USD 12.8 billion by 2036.
The market is expected to grow at a CAGR of 7.2% during the forecast period 2026-2036.
The global market for advanced automotive diagnostic tools was valued at USD 5.8 billion in 2025 and is estimated to reach USD 6.4 billion in 2026.
North America is expected to dominate the global advanced automotive diagnostic tools market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By tool type, the scan tools segment is expected to hold the largest share of the market in 2026, while the battery and EV diagnostic tools segment is projected to register the highest CAGR during the forecast period.
By connectivity type, the wired diagnostics segment is expected to hold the largest share in 2026, while the cellular/cloud connectivity segment is projected to register the highest CAGR during the forecast period.
By vehicle type, the passenger cars segment is expected to hold the largest share in 2026, while the electric vehicles segment is projected to register the highest CAGR during the forecast period.
By application, the engine and powertrain diagnostics segment is expected to hold the largest share in 2026, while the safety systems diagnostics (ADAS) segment is projected to register the highest CAGR during the forecast period.
By end user, the independent repair shops segment is expected to hold the largest share in 2026, while the fleet operators segment is projected to register the highest CAGR during the forecast period.
By deployment model, the on-premises diagnostics segment is expected to hold the largest share in 2026, while the cloud-based diagnostics segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 12.8 Billion |
| Market Size in 2026 | USD 6.4 Billion |
| Market Size in 2025 | USD 5.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 7.2% |
| Format | PDF, Excel & Cloud Portal · 285 pages |
| Dominating Tool Type | Scan Tools |
| Fastest Growing Tool Type | Battery and EV Diagnostic Tools |
| Dominating Connectivity Type | Wired Diagnostics |
| Fastest Growing Connectivity Type | Cellular/Cloud Connectivity |
| Dominating Vehicle Type | Passenger Cars |
| Fastest Growing Vehicle Type | Electric Vehicles (EVs) |
| Dominating Application | Engine and Powertrain Diagnostics |
| Fastest Growing Application | Safety Systems Diagnostics (ADAS) |
| Dominating End User | Independent Repair Shops |
| Fastest Growing End User | Fleet Operators |
| Dominating Deployment Model | On-Premises Diagnostics |
| Fastest Growing Deployment Model | Cloud-Based Diagnostics |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: tool type, connectivity type, vehicle type, application, end user.
Advanced automotive diagnostic tools are electronic instruments, software platforms, and connected systems that allow technicians and engineers to communicate with a vehicle's electronic control units to read fault codes, monitor live sensor data, perform component-level tests, and calibrate systems after repair. A modern vehicle is effectively a rolling network of dozens to over one hundred ECUs controlling everything from the engine and transmission to the braking system, airbags, infotainment, advanced driver assistance systems, and the high-voltage battery management system in an EV. When any of these systems malfunctions or needs service, a technician requires a diagnostic tool that can establish communication with the relevant ECU over the vehicle's CAN bus or Ethernet network, retrieve and interpret the fault codes stored in its memory, and often command the system through active tests to isolate the faulty component. Without the right diagnostic tool, a modern vehicle is essentially a black box to the workshop.
The market is growing because every major trend in automotive technology is increasing the complexity of vehicles that need to be diagnosed. According to the IEA's Global EV Outlook 2025, global EV sales reached around 17-18 million in 2024, and the growing EV fleet requires specialized high-voltage battery diagnostic tools and BMS communication capabilities that conventional diagnostic equipment does not provide. According to the Auto Care Association’s 2026 Auto Care FactBook, the U.S. automotive aftermarket generated approximately USD 414 billion in total sales in 2024, with repair and maintenance representing a large share, and the profitability of that repair business increasingly depends on technicians having the right diagnostic tools to identify and fix faults efficiently without guesswork. The right-to-repair movement, which in the U.S. has resulted in a memorandum of understanding between automakers and independent repairers and in Europe has seen legislative developments supporting independent access to vehicle diagnostic data, is expanding the addressable market for third-party diagnostic tool providers.
Two particularly powerful growth drivers are converging. The proliferation of ADAS features including automatic emergency braking, lane keeping assist, and adaptive cruise control requires calibration after any repair that affects camera, radar, or lidar sensor alignment, and this calibration must be performed with the OEM or equivalent ADAS calibration equipment, creating a new and growing diagnostic tool procurement category in workshops that was essentially nonexistent five years ago. Simultaneously, the shift toward software-defined vehicles, where vehicle features and capabilities are delivered and updated through software rather than hardware, is transforming OTA diagnostics from a convenience into a core vehicle architecture feature that generates ongoing diagnostic data streams and remote service opportunities.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Vehicle Electrification and Electronic Complexity
Every major automotive technology trend is adding electronic control units, sensors, and communication buses to vehicles, and each additional system requires diagnostic capability in the service workflow. Modern premium vehicles contain over 100 ECUs communicating over multiple CAN, LIN, MOST, and Automotive Ethernet networks, and diagnosing an intermittent fault in such a system requires tools capable of monitoring live data from multiple ECUs simultaneously, correlating signals across different networks, and performing guided fault isolation tests that conventional multimeters cannot provide. According to Bosch's Automotive Handbook, the most recent edition of which documents that the average semiconductor content per vehicle has been doubling approximately every eight years, this electronics proliferation trend shows no sign of slowing. The transition to electric vehicles adds another layer of diagnostic complexity through high-voltage battery systems, power electronics, and electric drive systems that require specialized insulation testing, cell-level battery analysis, and high-voltage safety protocols that represent entirely new diagnostic skill sets and tool requirements.
Expansion of Automotive Aftermarket Services
The global automotive aftermarket is large, growing, and increasingly dependent on advanced diagnostic tools for both the identification of vehicle faults and the calibration of repaired systems to specification. According to the Auto Care Association's 2024 Fact Book, the U.S. automotive aftermarket generated approximately USD 475 billion in 2023 across parts, service labor, and related categories. The average age of vehicles on U.S. roads reached a record 12.6 years in 2024 according to S&P Global Mobility, and older vehicles that are out of manufacturer warranty are serviced predominantly by the independent aftermarket, which requires diagnostic tools that can work across the full range of vehicle brands and model years rather than being limited to OEM-proprietary systems. The growth of the independent aftermarket is creating sustained demand for multi-brand diagnostic platforms that cover the broadest possible vehicle range, which is the core product positioning of Autel, Launch Tech, TEXA, and Snap-on's professional aftermarket diagnostic lines.
Table of contents
14 chapters · 174 sections · 285 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Tool Type | Scan Tools | Battery and EV diagnostic tools |
| By Vehicle Type | Passenger Cars | Electric vehicles |
| By Application | Engine and Powertrain Diagnostics | Safety systems diagnostics |
By Tool Type
- Scan Tools to Dominate
- The scan tools segment is expected to account for the largest share of the global advanced automotive diagnostic tools market.
- Scan tools that communicate with vehicle ECUs over the OBD-II diagnostic port to read fault codes, access live data, and perform active tests are the most universally required diagnostic instrument in automotive service, used in virtually every service interaction across passenger cars, commercial vehicles, and light trucks.
- Professional multi-brand scan tools from Bosch, Snap-on, Autel, and Launch Tech are standard workshop equipment for both dealer and independent workshops globally.
- However, the battery and EV diagnostic tools segment is projected to register the highest CAGR during the forecast period.
- The rapidly growing global EV fleet, which surpassed 55 million vehicles in 2024 per the IEA, is creating urgent workshop demand for tools capable of assessing EV battery state of health, diagnosing BMS faults, testing charging system components, and safely handling high-voltage battery systems.
- This is a new product category that is growing rapidly from a small current base as EV service volumes increase and as workshops invest in the specialized equipment required to service EVs competently.
By Vehicle Type
- Passenger Cars to Hold the Largest Share
- The passenger cars segment is expected to account for the largest share of the global advanced automotive diagnostic tools market.
- Passenger cars represent by far the largest component of the global vehicle parc by unit count, and the aftermarket diagnostic tool market is sized proportionally to the vehicle population.
- The high average electronic complexity of modern passenger cars, with over 100 ECUs in premium models, combined with the mandatory OBD-II diagnostic port requirement across all markets, makes passenger car diagnostic tooling the core of the market.
- However, the electric vehicles segment is projected to register the highest CAGR during the forecast period.
- With global EV sales growing at above-average rates and the EV parc expanding rapidly toward tens of millions of vehicles requiring service, the EV-specific diagnostic tool segment is growing significantly faster than the overall market.
- Battery health assessment tools, BMS diagnostic platforms, and charging system analyzers for EVs represent an entirely new tool category that every EV-servicing workshop needs to acquire as the EV fleet in their market grows.
By Application
- Engine and Powertrain Diagnostics to Hold the Largest Share
- The engine and powertrain diagnostics segment is expected to account for the largest share of the global advanced automotive diagnostic tools market.
- Engine and transmission faults are the most common diagnostic requirements across the global vehicle fleet, and engine diagnostic capability is a fundamental requirement of every professional scan tool.
- The very large ICE vehicle parc of over 1.5 billion vehicles generates the majority of diagnostic tool demand through engine and drivetrain service.
- However, the safety systems diagnostics segment, particularly ADAS calibration, is projected to register the highest CAGR during the forecast period.
- As ADAS systems become standard equipment on new vehicles following regulatory mandates in Europe and North America, and as these vehicles progressively enter the service cycle, the demand for ADAS calibration equipment and software is growing very rapidly.
- Every workshop repairing ADAS-equipped vehicles needs calibration capability, and the European General Safety Regulation's requirements affecting all new vehicles from July 2024 are creating a particularly sharp and immediate increase in ADAS calibration tool demand across European workshops.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global advanced automotive diagnostic tools market. The United States has the world's most developed automotive aftermarket, and one of the world's highest rates of diagnostic tool investment per workshop. The U.S. mandatory OBD-II requirement for all vehicles sold since 1996 established a standardized diagnostic architecture that has supported widespread diagnostic tool deployment across the independent repair sector. The U.S. vehicle parc is heavily dominated by trucks, SUVs, and premium vehicles with high electronic content that require advanced diagnostic tools for service. The Right-to-Repair memorandum of understanding signed between the Automotive Service Association and automakers in 2023 provides independent repairers with access to telematics data and remote diagnostic capabilities that were previously restricted to dealer networks, expanding the addressable market for advanced diagnostic tool providers in the U.S. independent channel. Snap-on Incorporated is the world's leading professional automotive diagnostic tool brand and generates the majority of its revenues from the North American professional workshop market.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific advanced automotive diagnostic tools market is expected to grow at the fastest CAGR during the forecast period. The region contains the world's two largest automotive markets by new vehicle sales, China and India, and has the world's fastest-growing EV adoption concentrated in China. China's domestic automotive diagnostic tool industry has grown very rapidly, with Autel Intelligent Technology and Launch Tech having grown from small domestic players to global competitors with millions of diagnostic tool users worldwide. India's record vehicle sales of over 20 million units in fiscal year 2024 per SIAM data are expanding the Indian vehicle parc and its associated service industry, driving growing diagnostic tool procurement across both dealer networks and the large independent repair sector. Japan, South Korea, and Australia are technologically sophisticated automotive markets with advanced diagnostic tool adoption, and Southeast Asian markets including Thailand, Indonesia, and Vietnam are growing rapidly as their automotive industries develop.
Europe
Europe is a technically advanced and regulatory-driven automotive diagnostic tools market, where the EU General Safety Regulation's ADAS mandates are creating particularly strong near-term demand for ADAS calibration tools and where the progressive transition to electric vehicles across European automotive markets is driving EV diagnostic tool investment. Germany, as the home of the European automotive industry and the headquarters of Bosch, Continental, and Hella, is both the largest European diagnostic tool market by revenue and the location of significant diagnostic tool R&D. The UK's right-to-repair regulations and the established independent aftermarket culture in France, Italy, and Spain sustain strong diagnostic tool demand across European independent workshops.
Competitive landscape
- Robert Bosch GmbH · Germany
- Snap-on Incorporated (U.S.)
- Continental AG · Germany
- Delphi Technologies/BorgWarner Inc. (U.S.)
- DENSO Corporation · Japan
- Autel Intelligent Technology Corp. Ltd. · China
- Launch Tech Co. Ltd. · China
- Actia Group · France
- AVL List GmbH · Austria
- TEXA S.p.A · Italy
- Softing AG · Germany
- KPIT Technologies Ltd. · India
- Vector Informatik GmbH · Germany
- Hickok Incorporated (U.S.)
- Hella GmbH & Co. KGaA · Germany
Frequently asked questions
The global advanced automotive diagnostic tools market is expected to reach USD 12.8 billion by 2036 from an estimated USD 6.4 billion in 2026, at a CAGR of 7.2% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Advanced Automotive Diagnostic Tools Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041953). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/advanced-automotive-diagnostic-tools-market-6636