Additive Manufacturing Market (2024-2031)
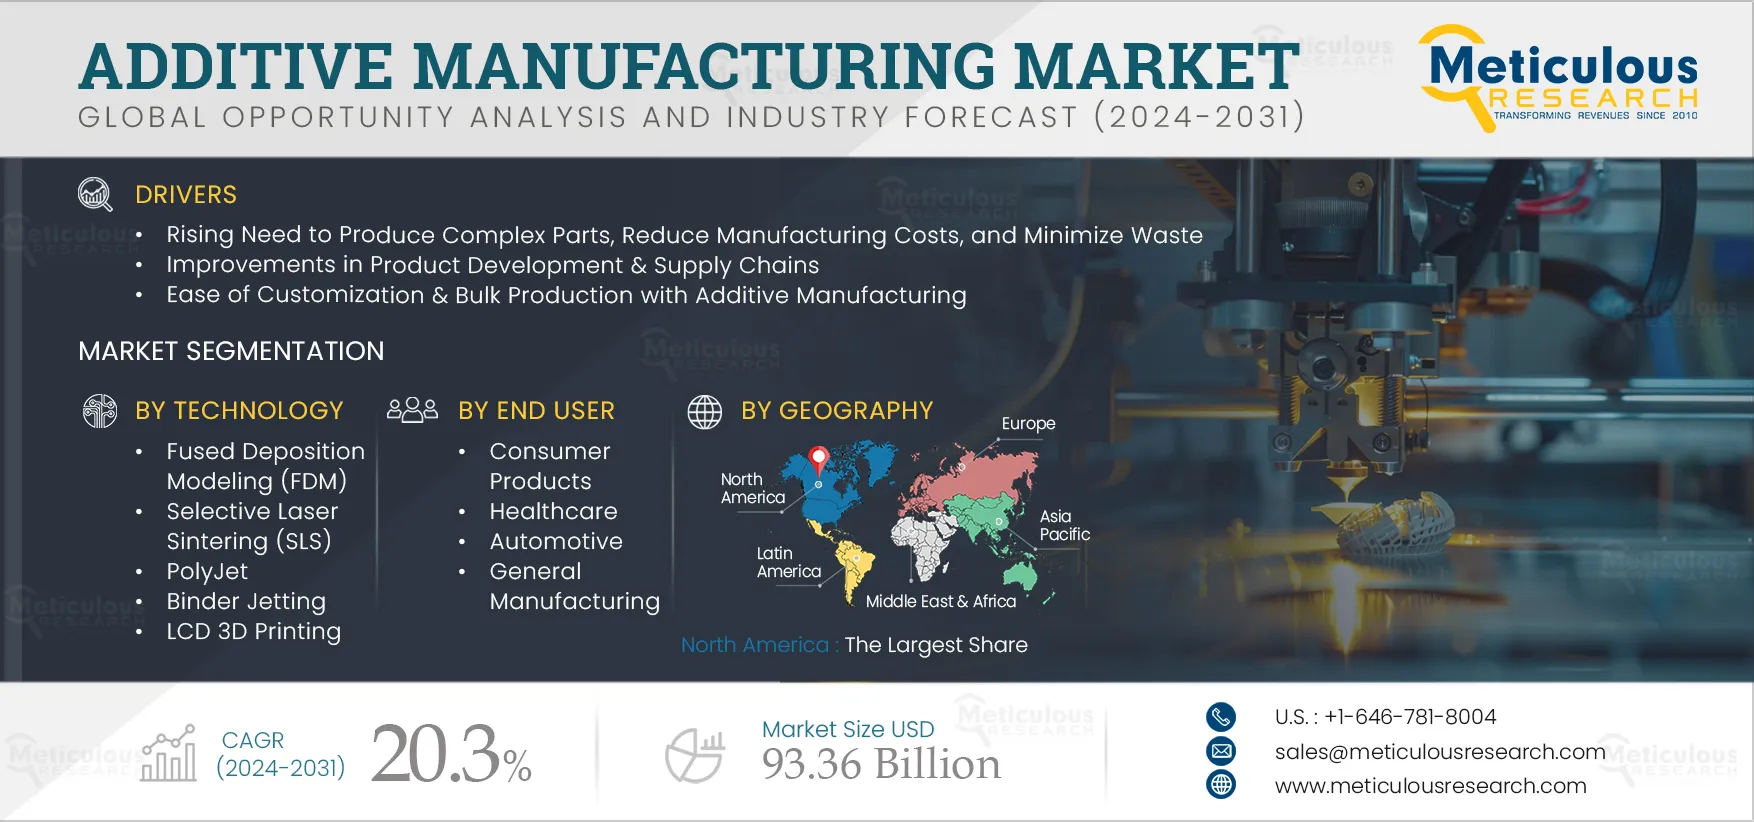
The Additive Manufacturing Market is expected to reach above $93.36 billion by 2031, at a CAGR of 20.3% from 2024 to 2031.
- Published
- May 2024
- Pages
- 450
- Format
- PDF + Excel
- Report ID
- MR-1155
- Base year
- 2023
- 2031 · FORECAST
- $93.36B
- 2031
- $93.36B
- CAGR 2024–2031
- 20.3%
2023 baseline · 2024–2031 forecast at 20.3% CAGR · hover a bar for the value
Key highlights
By Offering: In 2024, the Services Segment to Dominate the Additive Manufacturing Market
By Technology: In 2024, the Fused Deposition Modeling (FDM) Segment to Dominate the Additive Manufacturing Market
By End User: In 2024, the Consumer Products Segment to Dominate the Additive Manufacturing Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 450 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR | 20.3% |
| Market Size | USD 93.36 Billion by 2031 |
| Segments Covered | By Offering · Hardware · Software · Materials · Polymers · Metals · Ceramics · Composites · Other Materials · (Note: Other materials include resins, alloys, and sandstone) · Services · By Technology · Fused Deposition Modeling (FDM) · Selective Laser Sintering (SLS) · Direct Metal Laser Sintering (DMLS) · PolyJet · Stereolithography (SLA) · Digital Light Processing (DLP) · Directed Energy Deposition (DED) · Multi Jet Fusion · Binder Jetting · LCD 3D Printing · Laser Metal Fusion (LMF) · Electron Beam Melting (EBM) · Selective Absorption Fusion (SAF) · Other Technologies · (Note: Other technologies include Continuous Liquid Interface Production (CLIP), Selective Deposits Layer (SDL), and Laminated Object Manufacturing (LOM)) · By End User · Consumer Products · Consumer Electronics · Jewelry & Luxury Goods · Decorative Art · Parts & Fixtures · Healthcare · Dental · Prosthetic Printing · Prototype and 3D Models · Instrument Printing · Bioprinting Tissues and Organs · Automotive · Custom & Spare Parts · Prototyping · Mounts & Fixtures · General Manufacturing · Machinery & Equipment Manufacturing · Molds and Tools Printing · Parts & Prototype Printing · Electronics & Semiconductors · IC & PCB · Electronic Components · Aerospace & Defense · Prototype & Test Units · Body & Spare Parts · Weapon Printing · Mounts & Fixtures · Chemicals & Materials · Energy and Oil & Gas · Other End Users · (Note: Other end users include food, fashion and clothing, architecture, and academic research) |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Netherlands, Switzerland, Sweden, Denmark, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia & New Zealand, Indonesia, Thailand, Vietnam, Malaysia, Singapore, and Rest of Asia- Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Israel, and Rest of Middle East & Africa) |
| Key Companies | 3D Systems Corporation (U.S.), 3DCeram (France), Arcam AB (Sweden), Autodesk, Inc., (U.S.), Canon Inc. (Japan), Dassault Systèmes SE (France), Stratasys, Ltd. (U.S.), voxeljet AG (Germany), ExOne Operating, LLC (U.S.), MakerBot Industries, LLC (U.S.), Materialise NV (Belgium), EOS GmbH (Germany), Optomec, Inc., (U.S.), Proto Labs, Inc. (U.S.), Shapeways Holdings, Inc. (U.S.) |
Report overview
Segments covered: offering. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the additive manufacturing market is driven by the rising need to produce complex parts, reduce manufacturing expenses, and minimize waste, improvements in product development and supply chains, and easy customization and bulk production using additive manufacturing. Furthermore, the growing use of 3D printers to produce functional end-use parts and composite 3D printing is expected to offer significant growth opportunities for players operating in the additive manufacturing market.
Market dynamics
5 factors across 3 forcesImprovements in Product Development and Supply Chains
Advancements in product development and supply chain management are significant drivers of growth in the additive manufacturing market. Additive manufacturing allows for rapid prototyping, enabling companies to iterate and test designs quickly and cost-effectively. This speed and flexibility reduce time-to-market for new products. Additive manufacturing technologies can create highly complex geometries that traditional manufacturing methods struggle with. This freedom of design enables the creation of products with enhanced functionality and performance.
Additive manufacturing also enables the digital storage and on-demand production of spare parts, reducing the need for extensive inventory storage and ensuring the availability of parts for older or low-volume products. Moreover, AM allows for on-demand production, reducing the need for large inventories and minimizing the risk of overproduction or stockouts. Such factors help to drive the growth of the additive manufacturing market during the forecast period.
Easy Customization and Bulk Production Using Additive Manufacturing
Additive manufacturing (AM) allows for the production of highly customized and individualized products. Whether it's personalized consumer goods, customized medical implants, or tailored automotive components, AM technology enables manufacturers to meet specific customer needs and preferences. Unlike traditional manufacturing methods, which often require costly tooling changes for customization, AM offers design freedom. This flexibility allows for rapid iteration and adaptation of products without the need for extensive retooling. While AM is often associated with customization, it can also excel in bulk production scenarios. Depending on the technology and materials used, additive manufacturing processes can achieve high throughput and efficiency, making them suitable for mass production.
Moreover, additive manufacturing makes it more feasible to produce customized products on a large scale. By leveraging digital design and manufacturing processes, companies can efficiently produce large quantities of unique items tailored to individual customers or market segments.
Table of contents
11 chapters · 157 sections · 450 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Offering | Services | — |
| By Technology | Fused Deposition Modeling (FDM) | — |
| By End User | Consumer Products | — |
By Offering
- The Services Segment to Dominate the Additive Manufacturing Market
- The services segment is expected to account for the largest share of 52.8% of the additive manufacturing market.
- The segment includes services such as additive manufacturing services, education, repair & maintenance or consulting services, and training services associated with additive manufacturing hardware and software.
- The large share of the segment is attributed to the growing adoption of additive manufacturing, increased funding for companies in this sector, heightened interest from manufacturers in 3D printing, and the expanding number of industries utilizing additive manufacturing to enhance value-added services.
- End users increasingly depend on additive manufacturing service providers to achieve reduced costs, minimized waste, on-demand spare part production, improved performance, shorter lead times, and decreased inventory management needs.
- Additionally, the number of companies offering these services is on the rise.
- Consequently, the increasing number of service providers, along with the benefits of outsourcing, is driving the growth of this segment.
- The companies are also expanding their service offerings for the end users.
- For instance, in October 2022, voxeljet AG (Germany) expanded its portfolio of on-demand 3D printing services due to increasing demand for 3D polymer printing.
- Similarly, in November 2021, Shapeways Holdings, Inc. (U.S.) partnered with Desktop Metal, Inc. (U.S.) to increase access to additive manufacturing services.
By Technology
- The Fused Deposition Modeling (FDM) segment is expected to account for the largest share of 11.5% of the additive manufacturing market.
- The segment’s large share is attributed to the technology’s low cost and ability to manufacture a wide range of 3D-printed objects for automotive, aerospace, consumer goods, and jewelry applications.
- The cost-effectiveness of FDM technology in producing custom thermoplastic parts and prototypes has encouraged its adoption among manufacturing companies.
- The technology is popular among companies across various industries, such as automotive (BMW, Hyundai, and Lamborghini) and consumer goods manufacturing (Black and Decker, Dial, Nestle).
- Most companies use FDM for product development, prototyping, and manufacturing processes.
By End User
- The consumer products segment is expected to account for the largest share of 22.4% of the additive manufacturing market.
- The large share of the segment is attributed to the increasing production of consumer electronics, increasing spending on jewelry & luxury goods, and rising demand for decorative art.
- Additive manufacturing allows companies to offer customized products tailored to individual consumer preferences.
- This is particularly beneficial in markets such as fashion, footwear, eyewear, and personalized accessories, where unique designs can be quickly produced to meet specific customer needs.
- In addition, the ability to rapidly prototype new designs accelerates product development cycles.
- Companies can quickly iterate on design concepts, test functionality, and gather consumer feedback before committing to full-scale production.
- This reduces time-to-market and enhances innovation, further contributing to the demand for additive manufacturing in the consumer product segment.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 32.4% of the additive manufacturing market, followed by Europe and Asia-Pacific. The large share of the region is attributed to the presence of key market players and the growing demand for customized 3D-printed products in the region across healthcare, consumer electronics, aerospace & defense, and automotive sectors. The region is also growing in its adoption of industrialization 4.0, increasing collaborations & investments by enterprises in the development of advanced 3D printing and its materials, and supportive government initiatives. For instance, in May 2022, the U.S. president launched Additive Manufacturing Forward (AM Forward), a voluntary compact among major manufacturers to help smaller U.S.-based suppliers increase their use of AM. In 2024, North America to Dominate the Additive Manufacturing Market
Competitive landscape
- April 2024
Materialise (Belgium), a global leader in 3D printing software and services, announced a partnership with Renishaw (U.K.), a global engineering technologies company. The partnership will increase efficiency and productivity for manufacturers using Renishaw's additive manufacturing (AM) systems. Through the partnership, Renishaw system users will benefit from Materialise's next-generation build processor software tailored to the RenAM 500 series of metal AM systems.
- March 2024
3DEO (U.S.) announced a strategic partnership and investment with IHI AEROSPACE (IA) (Japan), an aerospace engineering and manufacturing company, to bolster the adoption and implementation of AM technologies by IA, tapping into 3DEO’s expertise in Design for Additive Manufacturing (DfAM) and technology differentiation.
- June 2023
Xi’an Bright Laser Technologies (China) and Siemens (China) Co., Ltd. signed a strategic cooperation agreement to establish long-term strategic cooperation to promote digital factories and advance the production of metal additive manufacturing equipment.
- April 2023
Oqton (U.S.), a software provider helping manufacturers increase innovation and efficiency by intelligently automating production, announced a partnership with Castor Technologies Ltd. (Israel), an automated software company. Under this, the integration of CASTOR’s software with Oqton’s Manufacturing OS offers a seamless solution for manufacturing contractors and organizations to evaluate and analyze the business case and technical feasibility of using additives for manufacturing.
- 3D System Corporation (U.S.)
- 3Dceram · France
- Dassault Systemes SE · France
- Colibrium Additive (U.S.)
- Materialise NV · Belgium
- Shapeways Holdings, Inc. (U.S.)
- Canon Inc. · Japan
- Optomec, Inc. (U.S.)
- Proto Labs, Inc. (U.S.)
- Stratasys, Ltd. (U.S.)
- EOS GmbH · Germany
- Desktop Metal, Inc. (U.S.)
- Formlabs Inc. (U.S.)
- Autodesk, Inc. (U.S.)
Frequently asked questions
The additive manufacturing market is expected to reach $93.36 billion by 2031, at a CAGR of 20.3% from 2024 to 2031.
Cite this report
Meticulous Research. (2024). Additive Manufacturing Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MR-1155). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/additive-manufacturing-market-5838