Solar Roofing Tiles Market (2026-2036)
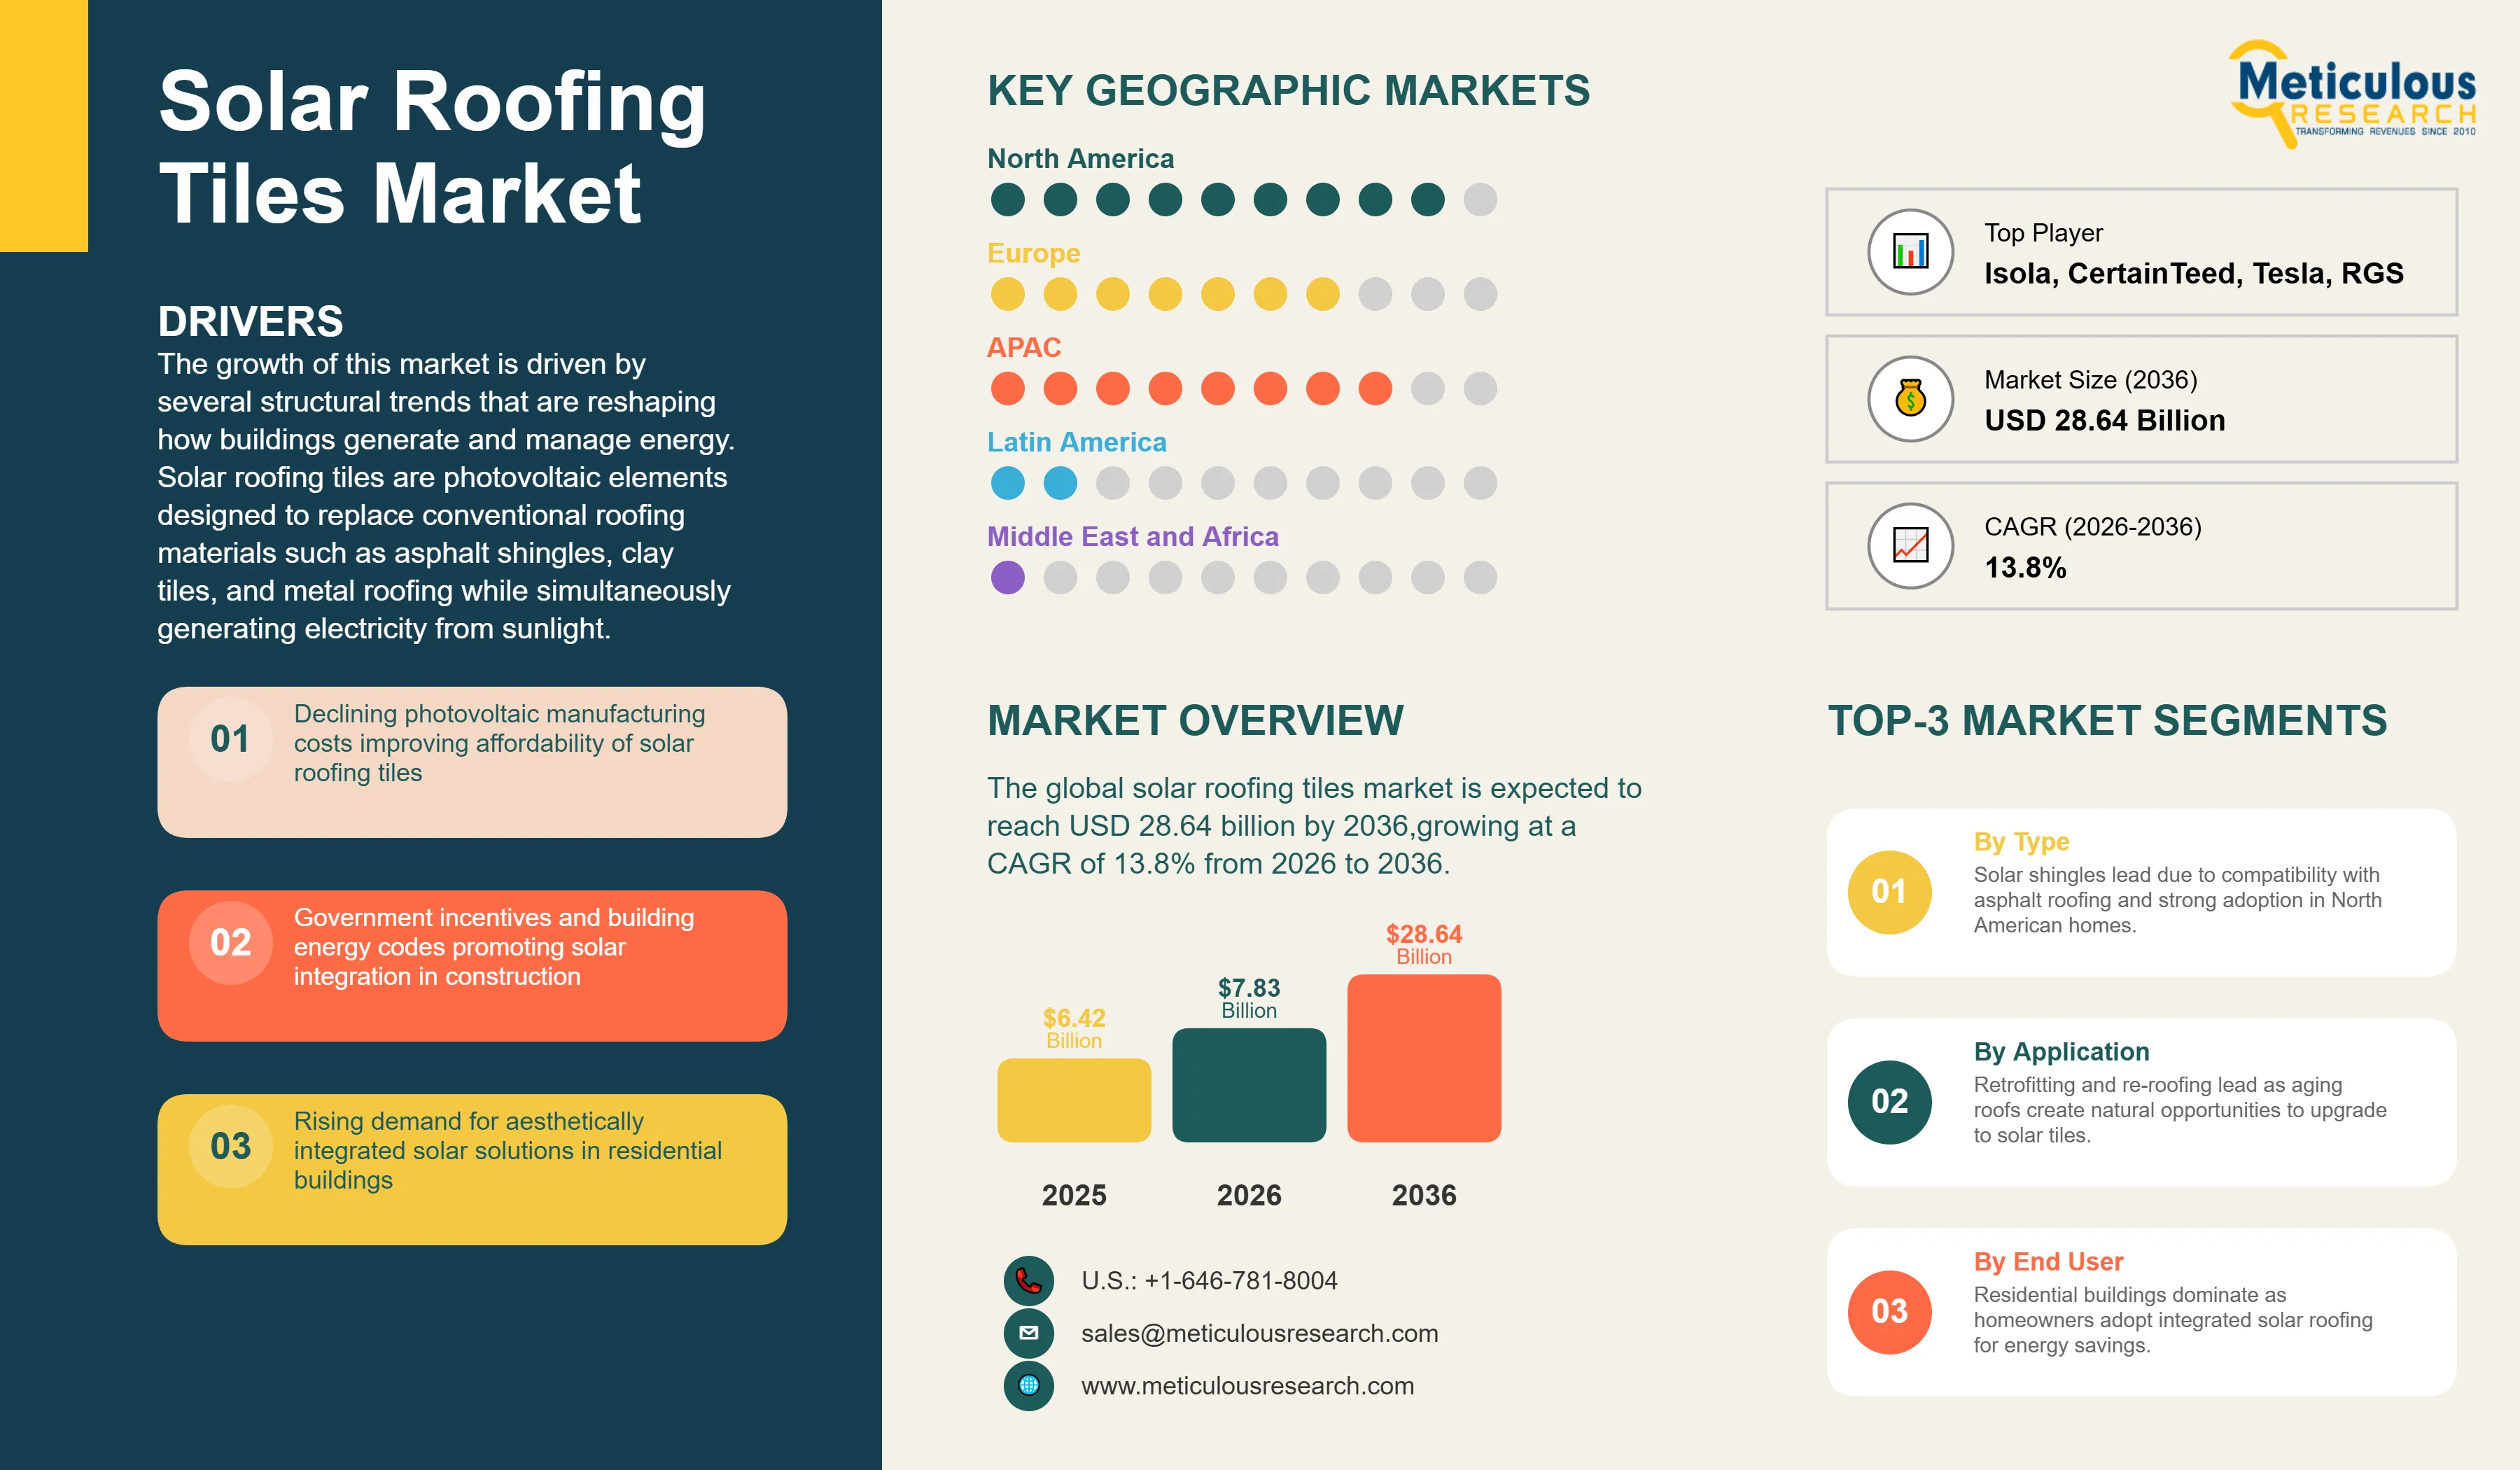
The global solar roofing tiles market was valued at USD 6.42 billion in 2025. This market is expected to reach USD 28.64 billion by 2036 from USD 7.83 billion in 2026, growing at a CAGR of 13.8% from 2026 to 2036.
- Published
- Mar 2026
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041841
- Base year
- 2025
- 2025 · BASELINE
- $6.42B
- 2036
- $28.64B
- CAGR 2026–2036
- 13.8%
2025 baseline · 2026–2036 forecast at 13.8% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global solar roofing tiles market is projected to reach USD 28.64 billion by 2036.
The market is expected to grow at a CAGR of 13.8% from 2026 to 2036.
North America is expected to dominate the global solar roofing tiles market with the largest market share in 2026, supported by Tesla Energy's Solar Roof establishing strong consumer awareness of the product category, California's Title 24 building code requirements mandating solar generation on new residential construction, and the Inflation Reduction Act's investment tax credit making solar tile installations more financially accessible for homeowners.
Asia-Pacific is expected to witness the fastest growth during the forecast period, driven by Japan's revised Building Energy Efficiency Act introducing solar installation requirements for new residential construction, China's expanding domestic solar tile manufacturing capacity and green building policy initiatives, and Australia's high residential solar adoption rate creating a favorable consumer environment for integrated solar roofing products.
By product format, the solar shingles segment is expected to hold the largest share of the overall solar roofing tiles market in 2026, reflecting its compatibility with the dominant asphalt shingle roofing style across North American residential markets and the commercial success of Tesla Solar Roof and CertainTeed Apollo II products in driving early adoption.
By product format, the flat solar roof tiles segment is expected to witness the fastest growth during the forecast period, supported by growing demand in European markets where flat tile formats align with regional roofing traditions and where new building energy regulations are increasing interest in architecturally integrated solar solutions.
By system output range, the 3 kW to 6 kW segment is expected to hold the largest share of the overall solar roofing tiles market in 2026, as this range corresponds to the standard residential solar tile system that most manufacturers design, size, and quote for a typical single-family home across major markets.
By installation type, the retrofit and re-roofing segment is expected to hold the largest share of the overall solar roofing tiles market in 2026, reflecting the large volume of existing residential and commercial roofs reaching end-of-life each year and the positioning of solar tiles as a premium upgrade within the natural roofing replacement cycle.
By building type, the residential buildings segment is expected to hold the largest share of the overall solar roofing tiles market in 2026, as all major solar tile manufacturers, including Tesla Energy, CertainTeed, Wienerberger, and Marley, focus their primary go-to-market activity, distribution networks, and product development on the residential roofing channel.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 28.64 Billion |
| Market Size in 2026 | USD 7.83 Billion |
| Market Size in 2025 | USD 6.42 Billion |
| Market Growth Rate (2026-2036) | CAGR of 13.8% |
| Format | PDF, Excel & Cloud Portal · 280 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Product Format, System Output Range, Installation Type, Building Type, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: product type, cell technology, application, end-user-.
The growth of this market is driven by several structural trends that are reshaping how buildings generate and manage energy. Solar roofing tiles are photovoltaic elements designed to replace conventional roofing materials such as asphalt shingles, clay tiles, and metal roofing while simultaneously generating electricity from sunlight. Unlike rack-mounted solar panels that are installed above an existing roof surface, solar tiles are integrated directly into the roof structure. This integration allows the tiles to serve as both the weatherproofing layer and a power generation system, making them an attractive alternative for property owners who want to generate solar energy without altering the visual character of their buildings.
Several factors are supporting the growth of this market. The declining cost of photovoltaic cell manufacturing is reducing the price premium of solar tiles over conventional roofing materials, making the investment more financially viable for a broader range of buyers. At the same time, growing adoption of net-zero energy building standards in national construction codes is increasing demand for integrated solar roofing in new residential and commercial construction. Rising consumer interest in aesthetically compatible solar solutions is also contributing to adoption, particularly in markets where homeowner association rules or local planning regulations restrict the use of visible rack-mounted panels. In addition, government incentive programs such as the 30% investment tax credit under the U.S. Inflation Reduction Act are reducing the financial burden of solar tile installations for homeowners and developers.
Solar roofing tiles are a category of building-integrated photovoltaics designed to replace standard roofing materials while generating electricity. The product category includes several formats. Solar shingles replicate the dimensions and installation method of standard asphalt shingles and are designed to integrate into conventional shingled roofs. Flat solar tiles resemble low-profile slate or concrete tiles and are used in both premium residential and commercial applications. Textured solar tiles mimic the three-dimensional appearance of clay barrel tiles or wood shake profiles. Solar metal roofing products integrate photovoltaic cells into standing seam metal roof panels for applications requiring a modern or industrial aesthetic.
The commercial development of this market has been significantly influenced by Tesla Energy's Solar Roof, which entered production in 2017 and established the solar shingle as a viable consumer product in the residential roofing replacement segment. Tesla's system uses tempered glass tiles that incorporate monocrystalline silicon cells on sun-facing roof sections, paired with non-active glass tiles of identical appearance on shaded sections. This approach provides full roof coverage with a consistent visual appearance from street level. Beyond Tesla, the market includes CertainTeed's Apollo II shingle product, which embeds thin monocrystalline cells into a flexible shingle format compatible with standard roofing contractor installation practices. In Europe, manufacturers such as Wienerberger, Roofit.Solar, and Tegola Solar have developed solar tile products designed for the clay and concrete tile roofing styles common in Mediterranean and Central European residential construction.
The competitive landscape of the solar roofing tiles market includes roofing materials manufacturers that have added solar capability to their product lines, solar energy companies that have developed roofing-integrated products, and specialist building-integrated photovoltaic developers. Established roofing companies benefit from existing distribution networks and contractor relationships, while solar-focused entrants bring strong expertise in photovoltaic technology and system integration. The market also relies on balance-of-system component providers such as Enphase Energy and SolarEdge, which supply microinverters and power optimizers that enable module-level energy harvesting from individual solar tiles and manage output from partially shaded or irregularly shaped roofs.
Report infographic
Market dynamics
4 factors across 3 forcesDeclining Manufacturing Costs and Favorable Roofing Replacement Economics
One of the primary drivers of the solar roofing tiles market is the sustained decline in photovoltaic cell and module manufacturing costs. Solar module prices have fallen by approximately 90% over the past decade, driven largely by scale expansion and efficiency improvements in Chinese manufacturing. This cost reduction is narrowing the price gap between solar roofing tiles and conventional roofing materials on a lifetime cost basis. For homeowners who are already planning to replace an aging roof, the incremental cost of upgrading to a solar tile system is becoming more financially manageable, particularly in markets with high electricity prices or strong net metering policies that provide good economic returns on solar generation.
The roofing replacement market creates a natural entry point for solar tile adoption. When a roof reaches the end of its service life, typically after 20 to 30 years, the homeowner must invest in replacement regardless of any interest in solar energy. At this point, choosing a solar tile system instead of a conventional roof adds solar generation capability to what would otherwise be a purely maintenance-driven expenditure. This dynamic makes the replacement roofing market a key demand channel for solar tiles, separate from the segment of homeowners who proactively seek to add solar to an otherwise serviceable roof. Government financial incentives such as the U.S. Inflation Reduction Act's 30% clean energy credit further improve the economics of solar tile adoption, reducing the effective incremental cost for eligible homeowners.
Table of contents
11 chapters · 94 sections · 280 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Format | Solar Shingles | Flat solar roof tiles |
| By System Output Range | 3 kW to 6 kW | 6 kW |
| By Installation Type | Retrofit and re-roofing | New construction |
| By Building Type | Residential Buildings | Commercial and institutional buildings |
By Product Format
- The solar shingles segment is expected to hold the largest share of the solar roofing tiles market.
- The dominant position of this segment is primarily due to its strong adoption in North America, where asphalt shingles are the most widely used residential roofing material.
- Solar shingles are designed to install in a similar manner to conventional asphalt shingles, allowing roofing contractors familiar with standard shingle installation to work with solar tile products without extensive retraining.
- Tesla Energy's Solar Roof uses tempered glass shingles incorporating monocrystalline silicon cells, and CertainTeed's Apollo II embeds thin monocrystalline cells into a flexible shingle substrate.
- Both companies distribute their products through roofing contractor networks that already serve the large North American asphalt shingle replacement market, which makes the shingle format the most commercially accessible product format for solar tile adoption in the region.
- However, the flat solar roof tiles segment is expected to witness the fastest growth during the forecast period.
- This growth is driven by increasing adoption in European and Asia-Pacific markets where flat tile profiles are more compatible with local roofing traditions.
- Manufacturers including Wienerberger with its Koramic Solesia product and Tegola Solar have developed flat solar tile lines specifically for clay and concrete tile markets that dominate residential roofing in France, Germany, Italy, Spain, and Japan.
- European building energy regulations requiring solar generation in new residential construction are accelerating adoption of flat solar tile formats in these markets, as architects and developers prefer products that integrate naturally with regional roofing aesthetics rather than adding a visually distinct system on top of a conventional roof.
By System Output Range
- The 3 kW to 6 kW system output range is expected to hold the largest share of the solar roofing tiles market.
- This range corresponds to the standard residential solar tile system configuration that meets the energy consumption requirements of a typical single-family home in major markets.
- Most solar roofing tile manufacturers, including Tesla Energy and CertainTeed, design their residential product lines and installer training programs around this capacity range as the default system size for an average homeowner.
- A standard mid-sized home in the United States, Europe, or Australia typically consumes between 8,000 and 14,000 kilowatt-hours of electricity annually, and a 3 kW to 6 kW solar tile system sized to the available sun-facing roof area meets a significant portion of that demand under typical irradiance conditions.
- This capacity range also represents the most effective range for financial returns under most net metering tariff structures, allowing homeowners to offset a substantial share of their electricity bill without generating beyond what the grid connection allows at favorable export rates.
- However, the 6 kW to 12 kW segment is expected to witness the fastest growth during the forecast period.
- This growth is driven by two converging trends.
- First, increasing household electricity consumption due to the adoption of electric vehicles and heat pumps is raising the energy offset target that homeowners want from a solar tile system, pushing average system sizing upward from the traditional 3 to 5 kW range toward 7 to 10 kW and above.
- Second, the growing availability of home battery storage systems such as Tesla Powerwall and Enphase IQ Battery is encouraging homeowners to install larger solar tile arrays to maximize self-consumption and battery charging.
- Tesla Energy actively promotes combined Solar Roof and Powerwall packages as an integrated energy system, and this bundled product strategy is increasing average system sizes across the markets where Tesla operates.
By Installation Type
- The retrofit and re-roofing segment is expected to hold the largest share of the solar roofing tiles market.
- This segment dominates because the existing stock of residential and commercial buildings far exceeds the volume of new construction in any given year, and a significant portion of that stock reaches roofing end-of-life every year, creating a continuous flow of replacement projects.
- Asphalt shingle roofs typically require replacement after 20 to 30 years, clay and concrete tile roofs after 30 to 50 years, and metal roofs after 40 to 70 years.
- This replacement cycle creates a recurring demand channel that solar tile manufacturers address by positioning their products as a premium upgrade at the point when a homeowner must invest in a new roof regardless of any interest in solar energy.
- The retrofit channel is also the core commercial model of established roofing manufacturers such as CertainTeed, Marley, and Redland that have added solar tile products to their existing contractor distribution networks built around the replacement roofing market.
- However, the new construction segment is expected to witness the fastest growth during the forecast period.
- Building energy code requirements mandating solar installation on new residential construction in California, Japan, and a growing number of European jurisdictions are creating regulatory-driven demand for solar roofing in new build projects.
- New construction offers a more efficient installation context than retrofit because the roof deck is bare, electrical rough-in can be planned from the outset, and the combined cost of roofing and solar is evaluated together in the initial project budget rather than as a separate upgrade decision.
- Large production homebuilders including D.R.
- Horton and Lennar have developed dedicated solar tile procurement programs for their California communities, creating volume purchasing relationships with manufacturers that are beginning to produce meaningful scale effects in product cost and installer availability.
By Building Type
- The residential buildings segment is expected to hold the largest share of the solar roofing tiles market.
- Residential buildings represent the primary target market for all major solar roofing tile manufacturers, as the product category was conceived and commercially developed specifically to address the residential roofing replacement market.
- Tesla Energy's Solar Roof is marketed exclusively to homeowners and residential developers.
- CertainTeed's Apollo II is distributed through residential roofing contractor networks.
- European manufacturers including Wienerberger, Marley, Tegola Solar, and Roofit.Solar similarly focus their go-to-market activity on residential roofing channels and consumer-facing marketing that addresses homeowner concerns about aesthetics, energy bills, and home value.
- The residential segment also benefits from strong government financial support in key markets, including the U.S. Inflation Reduction Act's residential clean energy credit, German KfW home improvement loan programs covering building-integrated solar, and UK home energy retrofit grant schemes that are specifically structured to support individual homeowner investments.
- However, the commercial and institutional buildings segment is expected to witness the fastest growth during the forecast period.
- As solar tile product lines expand to include larger-format tiles and higher-wattage system configurations suitable for commercial roof areas, and as building energy regulations increasingly require solar generation on new commercial construction, developers of retail, office, hospitality, and institutional buildings are beginning to specify solar tile systems as part of their building envelope design.
- The heritage and architecturally sensitive sub-segment within institutional buildings is a particularly significant growth area.
- Schools, museums, local government offices, and places of worship that are subject to planning restrictions preventing conventional panel installations are under increasing pressure to reduce energy costs and demonstrate environmental responsibility.
- Specialist solar tile products approved for use on listed and heritage buildings, such as those offered by Marley Solartile and Redland Solar Slate, are gaining traction in this institutional sub-segment across the United Kingdom and Europe.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to hold the largest share of the global solar roofing tiles market. This leadership is primarily driven by strong demand in the United States, where Tesla Energy's Solar Roof has established broad consumer awareness of the solar tile product category, California's Title 24 building code requirements have created a large regulatory-driven market for solar roofing in new residential construction, and the Inflation Reduction Act's 30% investment tax credit provides meaningful financial support for homeowners investing in building-integrated solar systems. California is the largest single state market for solar roofing in the United States, driven by its solar mandate for new residential construction and its high retail electricity prices, which shorten the payback period for solar installations. Other high-solar states including Texas, Florida, Arizona, and Colorado also contribute to regional demand. Tesla's installer network, which has grown significantly since the Solar Roof's commercial launch, covers major metropolitan areas across the United States and provides installation services that are critical to consumer adoption of what is a more technically complex installation than conventional solar panels. Canada contributes to regional demand through provincial net metering programs and home retrofit incentives in provinces such as Ontario and British Columbia.
Asia-Pacific
Fastest growthAsia-Pacific is expected to witness the highest growth rate in the solar roofing tiles market during the forecast period. This growth is primarily driven by regulatory developments in Japan, expanding manufacturing and deployment in China, and favorable consumer conditions in Australia. Japan is a particularly significant growth market. The country's revised Building Energy Efficiency Act introduces solar installation requirements for new residential construction from 2025, creating large-scale demand for solar roofing products in a market known for high construction quality and consumer preference for aesthetically refined solutions. Japanese consumers and architects are likely to favor solar tile formats over conventional panel systems for new residential projects, given the strong emphasis on building aesthetics in the Japanese housing market. China is contributing to regional growth both as a manufacturing base and as an increasingly active deployment market. Chinese manufacturers of building-integrated photovoltaic products are expanding production capacity for solar tiles, supported by domestic green building policy requirements and growing consumer interest in energy-efficient housing. LONGi Green Energy's BIPV division and other domestic producers are developing products for both the Chinese market and export. Australia has one of the highest residential solar adoption rates in the world, with solar panels installed on more than one-third of homes. As early solar adopters in Australia approach roof replacement cycles, the combination of an existing interest in solar energy and the need for roof replacement creates a favorable environment for solar tile adoption. South Korea and India also represent growing markets, with South Korea's premium residential construction sector creating demand for advanced building materials and India's rapidly expanding residential construction market offering greenfield opportunities as green building standards develop.
Competitive landscape
- Tesla Energy, Inc.
- CertainTeed LLC (Saint-Gobain)
- Brava Roof Tile LLC
- Wienerberger AG
- Roofit.Solar OY
- Tegola Solar S.p.A
- Isola Group AS
- Marley Eternit Ltd.
- Redland Roofing Systems · Etex Group
- Oxford PV Ltd.
- SunRoof Technologies sp. z o.o
- RGS Energy
- Soltech Energy Sweden AB
- Enphase Energy, Inc
Frequently asked questions
The global solar roofing tiles market is expected to grow from USD 7.83 billion in 2026 to USD 28.64 billion by 2036.
Cite this report
Meticulous Research. (2026). Solar Roofing Tiles Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MRCHM - 1041841). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/solar-roofing-tiles-market-6524