Semiconductor Gases Market
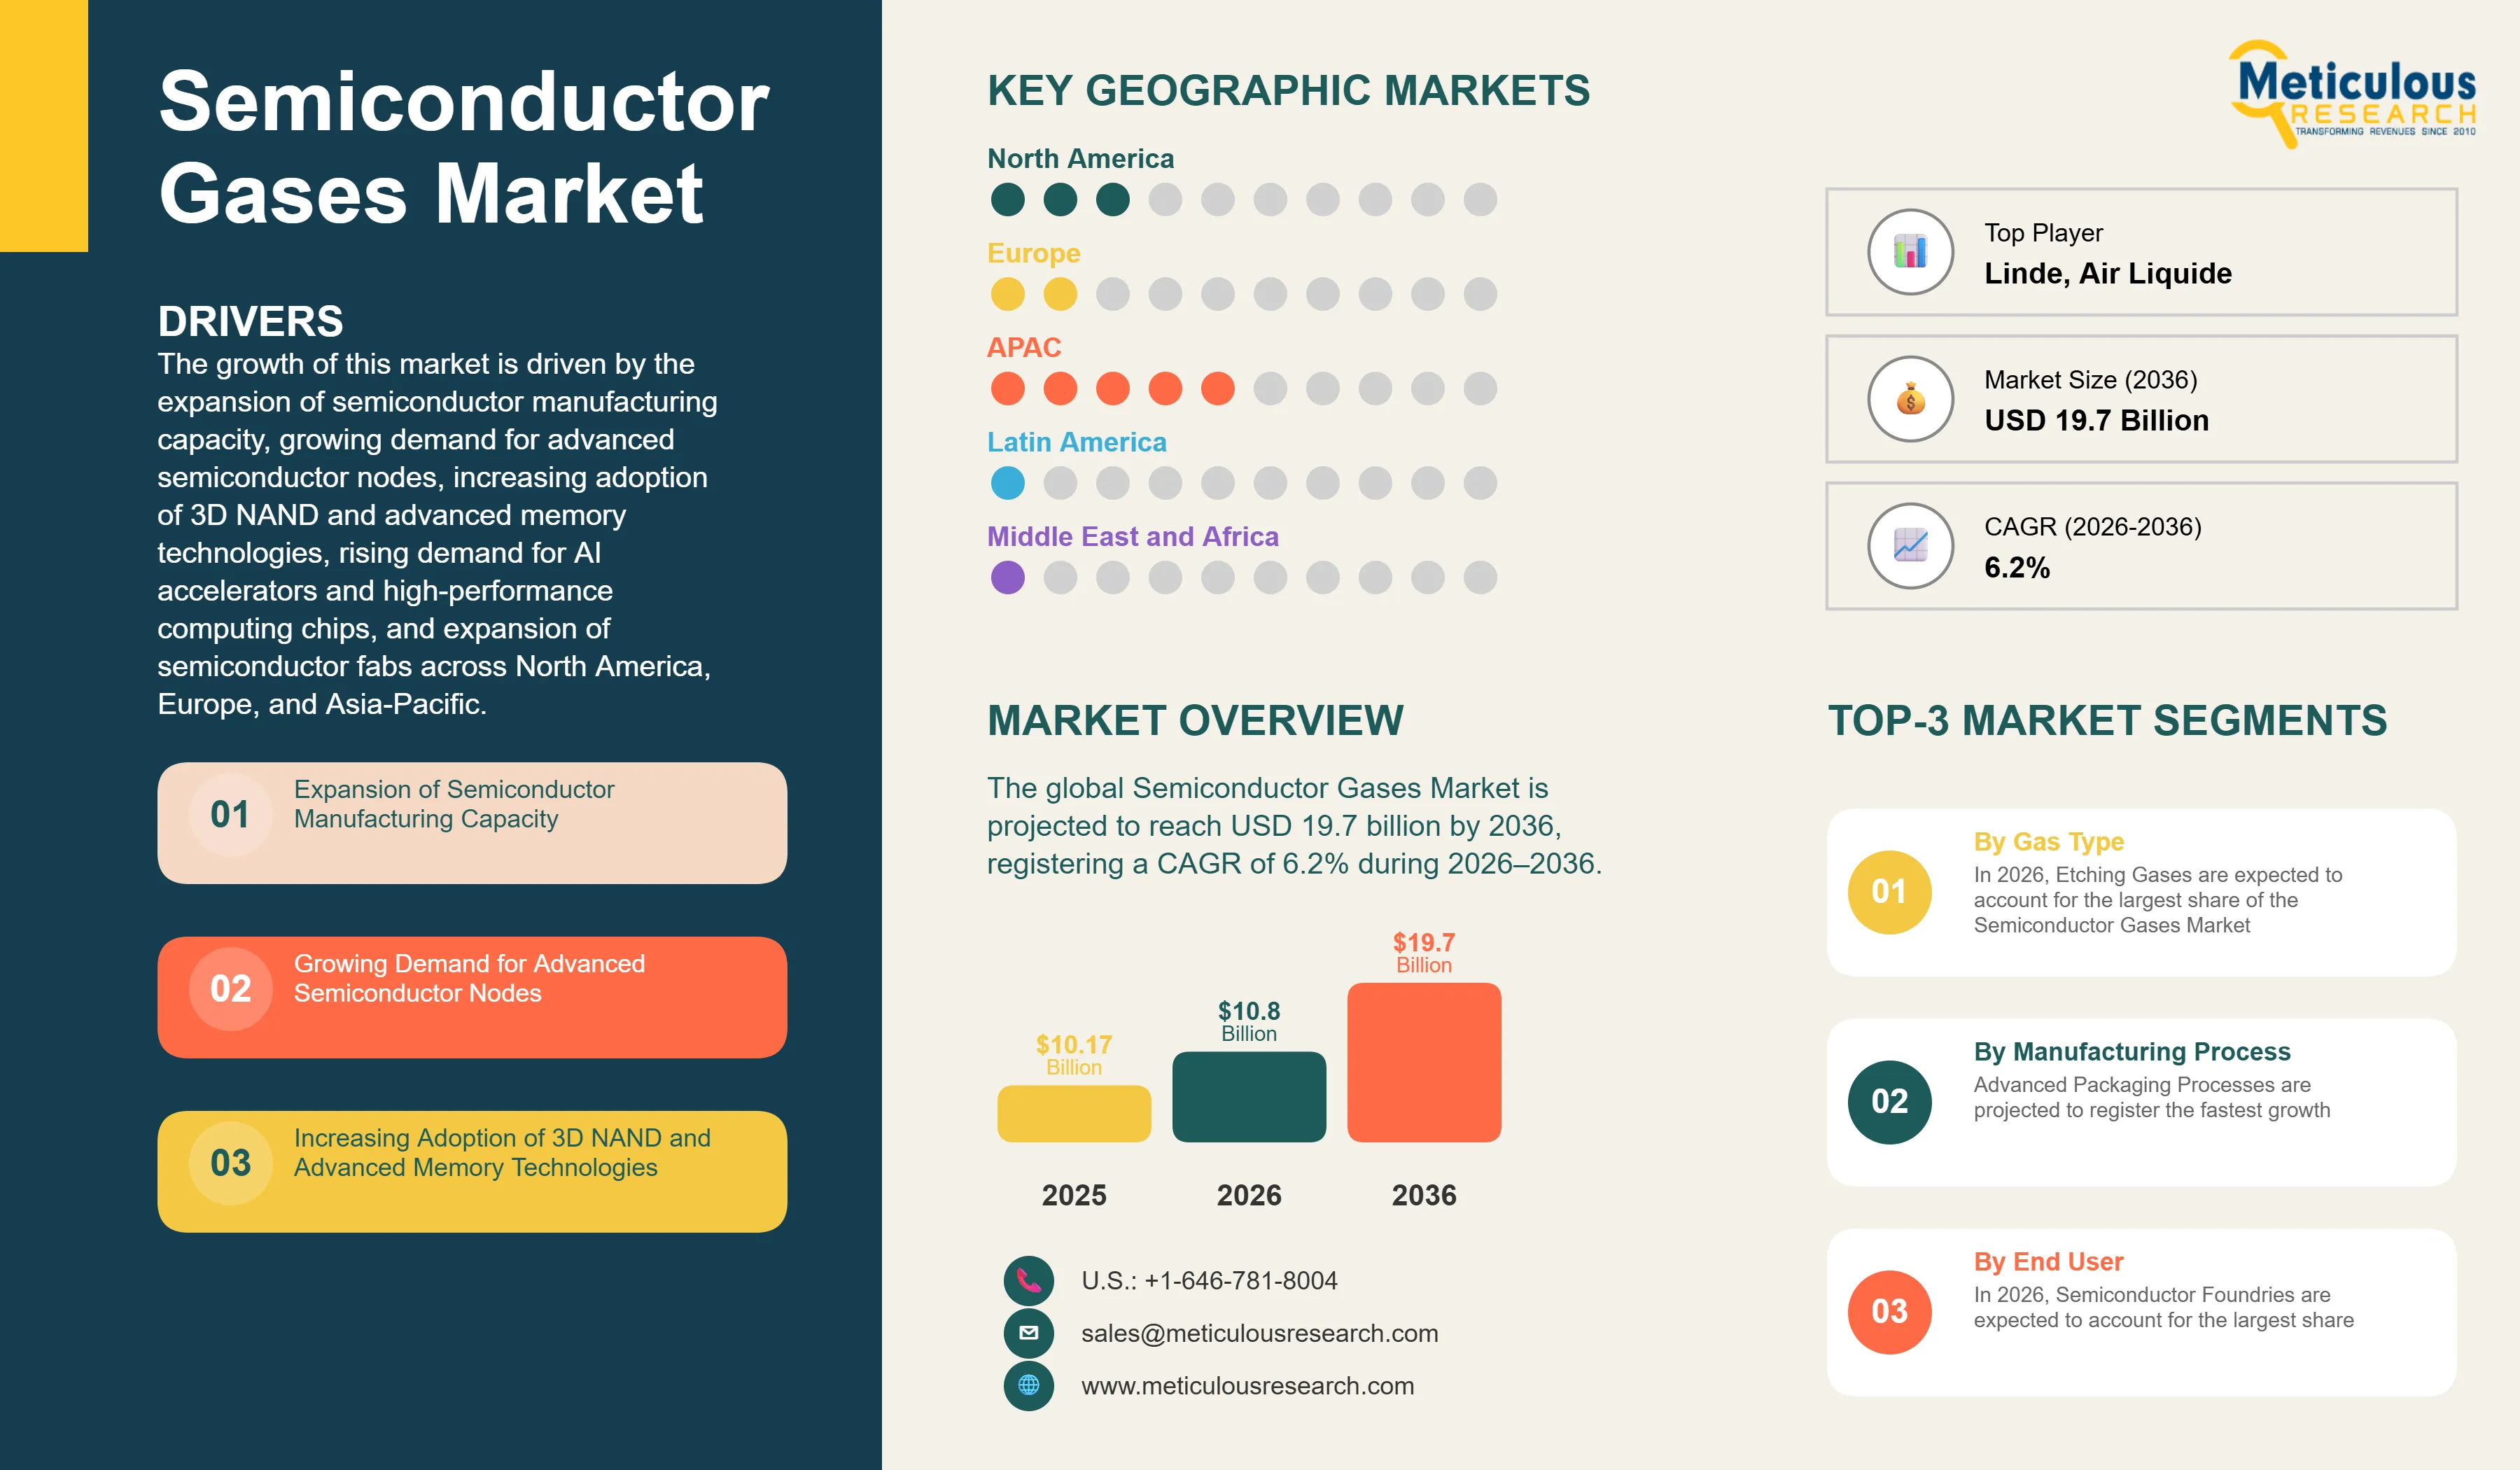
The global Semiconductor Gases Market was valued at USD 10.8 billion in 2026 and is projected to reach USD 19.7 billion by 2036, registering a CAGR of 6.2% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 304
- Format
- PDF + Excel
- Report ID
- MR-2130
- Base year
- 2025
- 2026 · ESTIMATED
- $10.80B
- 2036
- $19.70B
- CAGR 2026–2036
- 6.2%
2025 baseline · 2026–2036 forecast at 6.2% CAGR · hover a bar for the value
Key highlights
The global Semiconductor Gases Market is projected to reach USD 19.7 billion by 2036, driven by expansion of semiconductor manufacturing capacity, increasing adoption of advanced process nodes, growing production of 3D NAND and HBM, and rising demand for AI accelerators and high-performance computing chips.
Asia-Pacific is expected to account for the largest market share in 2026, supported by the concentration of semiconductor manufacturing and advanced memory production across China, Taiwan, South Korea, Japan, and Southeast Asia.
By gas type, Etching Gases are expected to account for a significant market share, supported by increasing process complexity and growing adoption of advanced semiconductor architectures.
By gas category, Specialty Gases are expected to account for a significant market share due to their extensive use in deposition, etching, doping, and cleaning processes.
Increasing adoption of 3D NAND, HBM, advanced logic nodes, AI accelerators, and heterogeneous integration is increasing demand for high-purity and application-specific semiconductor gases.
The transition toward low-global-warming-potential (low-GWP) etching and cleaning gases is creating opportunities for next-generation semiconductor gas chemistries.
Increasing semiconductor manufacturing investments in the U.S., Europe, India, and Asia-Pacific are expected to create additional demand for semiconductor gas production, purification, distribution, and on-site supply infrastructure.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 6.2% |
| Format | PDF, Excel & Cloud Portal · 304 pages |
| Market Size (Value) in 2026 | USD 10.8 Billion |
| Market Size (Value) in 2036 | USD 19.7 Billion |
| Segments Covered | By Gas Type: Etching Gases, Deposition Gases, Doping Gases, Cleaning Gases, Carrier & Inert Gases, Other Semiconductor Gases. · By Gas Category: Specialty Gases, Bulk Gases. · By Semiconductor Manufacturing Process: Deposition, Etching, Cleaning, Doping & Ion Implantation, Lithography, Oxidation & Thermal Processing, Advanced Packaging Processes. · By Semiconductor Type: Logic & Microprocessors, Memory, Analog & Power Semiconductors, Compound Semiconductors, Microcontrollers & Connectivity Semiconductors. · By Wafer Size: 150 mm ≤, 200 mm, 300 mm, >300 mm. · By Supply Mode: Cylinders, Bundled Cylinders, Bulk Supply, On-Site Gas Generation, On-Site Gas Supply & Management. · By End User: Semiconductor Foundries, Integrated Device Manufacturers (IDMs), Memory Manufacturers, Compound Semiconductor Manufacturers, Outsourced Semiconductor Assembly & Test (OSAT) Providers, Research & Development Institutions. |
| Countries Covered | North America: U.S., Canada. · Europe: Germany, France, U.K., Netherlands, Ireland, Italy, Belgium, Rest of Europe. · Asia-Pacific: China, Taiwan, South Korea, Japan, Singapore, India, Malaysia, Vietnam, Rest of Asia-Pacific. · Latin America: Brazil, Mexico, Argentina, Rest of Latin America. · Middle East & Africa: Israel, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa. |
| Key Companies | Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., Merck KGaA, SK Inc. Materials, Entegris, Inc., Resonac Holdings Corporation, Taiyo Nippon Sanso Corporation, Messer SE & Co. KGaA, Iwatani Corporation, Nippon Sanso Holdings Corporation, Korea Industrial Gases Co., Ltd., Sumitomo Seika Chemicals Co., Ltd., Fujikin Incorporated, and Versum Materials. |
Report overview
Segments covered: gas type, gas category, semiconductor manufacturing process, semiconductor type, wafer size, supply mode, end user.
The Semiconductor Gases Market comprises specialty and bulk gases used throughout semiconductor manufacturing and advanced packaging processes. These gases are essential for processes including deposition, etching, cleaning, doping and ion implantation, lithography, oxidation, thermal processing, and advanced packaging. The market encompasses etching gases, deposition gases, doping gases, cleaning gases, carrier and inert gases, and other specialty gases.
Semiconductor gases are critical process materials because they enable precise deposition and removal of material layers during wafer fabrication. As semiconductor geometries become smaller and device structures become more complex, manufacturers require increasingly precise control over gas composition, flow, purity, and contamination levels. Electronic-grade and ultra-high-purity gases are therefore essential for maintaining process consistency and semiconductor yield. According to SEMI's 2026 300mm Fab Outlook, global 300mm front-end fab equipment spending is expected to reach a record US$142 billion in 2026, representing a 25% year-on-year increase. The report tracks 413 fabs and production lines worldwide, highlighting the scale of semiconductor manufacturing capacity requiring high-purity process gases.
The increasing complexity of semiconductor manufacturing is expanding gas requirements across multiple process steps. Advanced logic devices require highly controlled deposition and etching processes, while 3D NAND manufacturing relies extensively on multilayer deposition and high-aspect-ratio etching. Similarly, HBM and other advanced memory technologies require increasingly sophisticated fabrication processes. SEMI forecasts that global advanced semiconductor manufacturing capacity at 7nm and below will increase approximately 69%, from 850,000 wafers per month in 2024 to 1.4 million wafers per month by 2028. In 2026 alone, advanced-process capacity is expected to reach approximately 1.16 million wafers per month, surpassing one million wafers for the first time. The growing production of GPUs, AI accelerators, CPUs, and ASICs is further increasing demand for advanced semiconductor manufacturing capacity and associated process gases.
The market is also being shaped by the geographic expansion of semiconductor manufacturing. New and expanded fabs across North America, Europe, and Asia-Pacific are increasing local demand for semiconductor gases and associated purification, storage, distribution, and point-of-use delivery infrastructure. SEMI's 2026 outlook indicates that global 300mm installed semiconductor capacity is projected to increase by approximately 7% in 2026, while five new 200mm volume-production fabs are expected to begin operations during the year, bringing the total number of such fabs to 256. The localization of semiconductor supply chains is also encouraging gas producers to establish production and supply capabilities closer to major semiconductor manufacturing clusters. This localization trend is reinforced by major government-backed investments; for example, the U.S. Department of Commerce reported in 2025 that Micron planned US$200 billion in U.S. semiconductor manufacturing and R&D investments, including expansion of advanced memory production supporting AI and high-performance computing.
Market dynamics
24 factors across 5 forcesExpansion of Semiconductor Manufacturing Capacity
The expansion of semiconductor manufacturing capacity worldwide is a major driver of the Semiconductor Gases Market. New semiconductor fabs require continuous supplies of process gases for deposition, etching, cleaning, doping, oxidation, and other fabrication processes. Capacity expansions at existing fabs also increase gas consumption as manufacturers add wafer-processing equipment and increase production volumes.
Semiconductor manufacturing investments are expanding beyond traditional production centers as governments and industry players seek to strengthen domestic and regional supply chains. New fabrication projects across the U.S., Europe, India, China, Taiwan, South Korea, Japan, and Southeast Asia are therefore creating additional demand for both specialty and bulk semiconductor gases.
The impact is particularly significant for fabs manufacturing advanced logic and memory devices, where increasing process complexity requires a greater variety of high-purity gases. The expansion of fabs across North America, Europe, and Asia-Pacific is expected to remain a key source of demand during the forecast period.
Growing Demand for Advanced Semiconductor Nodes
The shift toward advanced semiconductor nodes is increasing the complexity and intensity of semiconductor gas consumption. Advanced nodes require highly controlled deposition, etching, cleaning, and doping processes to manufacture increasingly small and sophisticated device structures.
The continued development of advanced processors for AI, high-performance computing, data centers, smartphones, and high-end computing applications is supporting investment in leading-edge manufacturing capabilities. These manufacturing processes require high-purity gases with tightly controlled impurity levels to maintain process uniformity and yield.
Advanced etching and deposition techniques, including plasma etching, CVD, ALD, selective deposition, and selective etching, are becoming increasingly important as manufacturers transition toward more complex transistor architectures and advanced memory structures.
Increasing Adoption of 3D NAND and Advanced Memory Technologies
The growing production of 3D NAND, DRAM, and High Bandwidth Memory (HBM) is creating significant demand for semiconductor gases. 3D NAND requires repeated deposition and etching of vertically stacked layers, resulting in intensive use of deposition and etching gases.
HBM production is also gaining importance due to increasing demand from AI accelerators and high-performance computing systems. Advanced memory manufacturing requires precise deposition, etching, cleaning, and other process steps, increasing consumption of specialty gases.
The increasing deployment of HBM and advanced memory technologies is therefore creating opportunities for suppliers of silane, ammonia, nitrogen trifluoride, fluorine-based etching gases, and other specialized process gases.
Rising Demand for AI Accelerators and High-Performance Computing Chips
The rapid expansion of AI and high-performance computing is increasing demand for advanced semiconductors, including GPUs, AI accelerators, CPUs, and application-specific integrated circuits (ASICs). Manufacturing these devices requires advanced process technologies and increasingly complex wafer fabrication processes.
AI-related semiconductor demand is also increasing the need for advanced packaging and HBM integration. Processes such as 2.5D packaging, 3D packaging, wafer-level packaging, and hybrid bonding require specialized process environments and gases, creating additional opportunities for semiconductor gas suppliers.
Table of contents
15 chapters · 250 sections · 304 pages · click to expandGeographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Semiconductor Gases Market. The large share of this region is mainly due to the concentration of semiconductor foundries, memory manufacturers, advanced packaging facilities, and semiconductor chemical and gas suppliers across Taiwan, South Korea, China, Japan, Singapore, and Southeast Asia. Taiwan and South Korea are particularly important for advanced logic and memory manufacturing, while China is expanding domestic semiconductor production capacity.
North America
Fastest growthHowever, North America is projected to register the fastest growth during the forecast period. The rapid growth of this region is attributed to increasing investments in semiconductor fabrication capacity in the U.S., government support for domestic semiconductor manufacturing, expansion of advanced-node production, and development of localized semiconductor supply chains. The geographic expansion of semiconductor manufacturing is also increasing demand for localized specialty gas production, purification, and distribution infrastructure.
Competitive landscape
The global Semiconductor Gases Market is characterized by the presence of major industrial gas companies, specialty chemical manufacturers, and semiconductor material suppliers. Competition is primarily based on gas purity, product consistency, process performance, supply reliability, technical qualification, production capabilities, safety standards, geographic presence, and customer support.
Leading companies are focusing on expanding semiconductor-grade gas production and purification capabilities, developing advanced gas chemistries, strengthening supply infrastructure near semiconductor manufacturing clusters, and supporting customers with integrated gas management solutions. The increasing localization of semiconductor manufacturing is also encouraging suppliers to establish regional production and distribution networks to improve supply reliability.
Environmental considerations are increasingly influencing competitive strategies, particularly for etching and cleaning gases with high global-warming potential. Suppliers are therefore investing in lower-GWP alternatives and technologies that can meet semiconductor process requirements while reducing environmental impact.
The key companies profiled in the global Semiconductor Gases Market include Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., Merck KGaA, SK Inc. Materials, Entegris, Inc., Resonac Holdings Corporation, Taiyo Nippon Sanso Corporation, Messer SE & Co. KGaA, Iwatani Corporation, Nippon Sanso Holdings Corporation, Korea Industrial Gases Co., Ltd., Sumitomo Seika Chemicals Co., Ltd., Fujikin Incorporated, and Versum Materials.
- Linde plc
- Air Liquide S.A.
- Air Products and Chemicals, Inc.
- Merck KGaA
- SK Inc. Materials
- Entegris, Inc.
- Resonac Holdings Corporation
- Taiyo Nippon Sanso Corporation
- Messer SE & Co. KGaA
- Iwatani Corporation
- Nippon Sanso Holdings Corporation
- Korea Industrial Gases Co., Ltd.
- Sumitomo Seika Chemicals Co., Ltd.
- Fujikin Incorporated
- Versum Materials
Frequently asked questions
The global Semiconductor Gases Market is estimated at USD 10.8 billion in 2026.
Cite this report
Meticulous Research. (2026). Semiconductor Gases Market - Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2130). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/semiconductor-gases-market-6813