Semiconductor Gas Abatement Systems Market
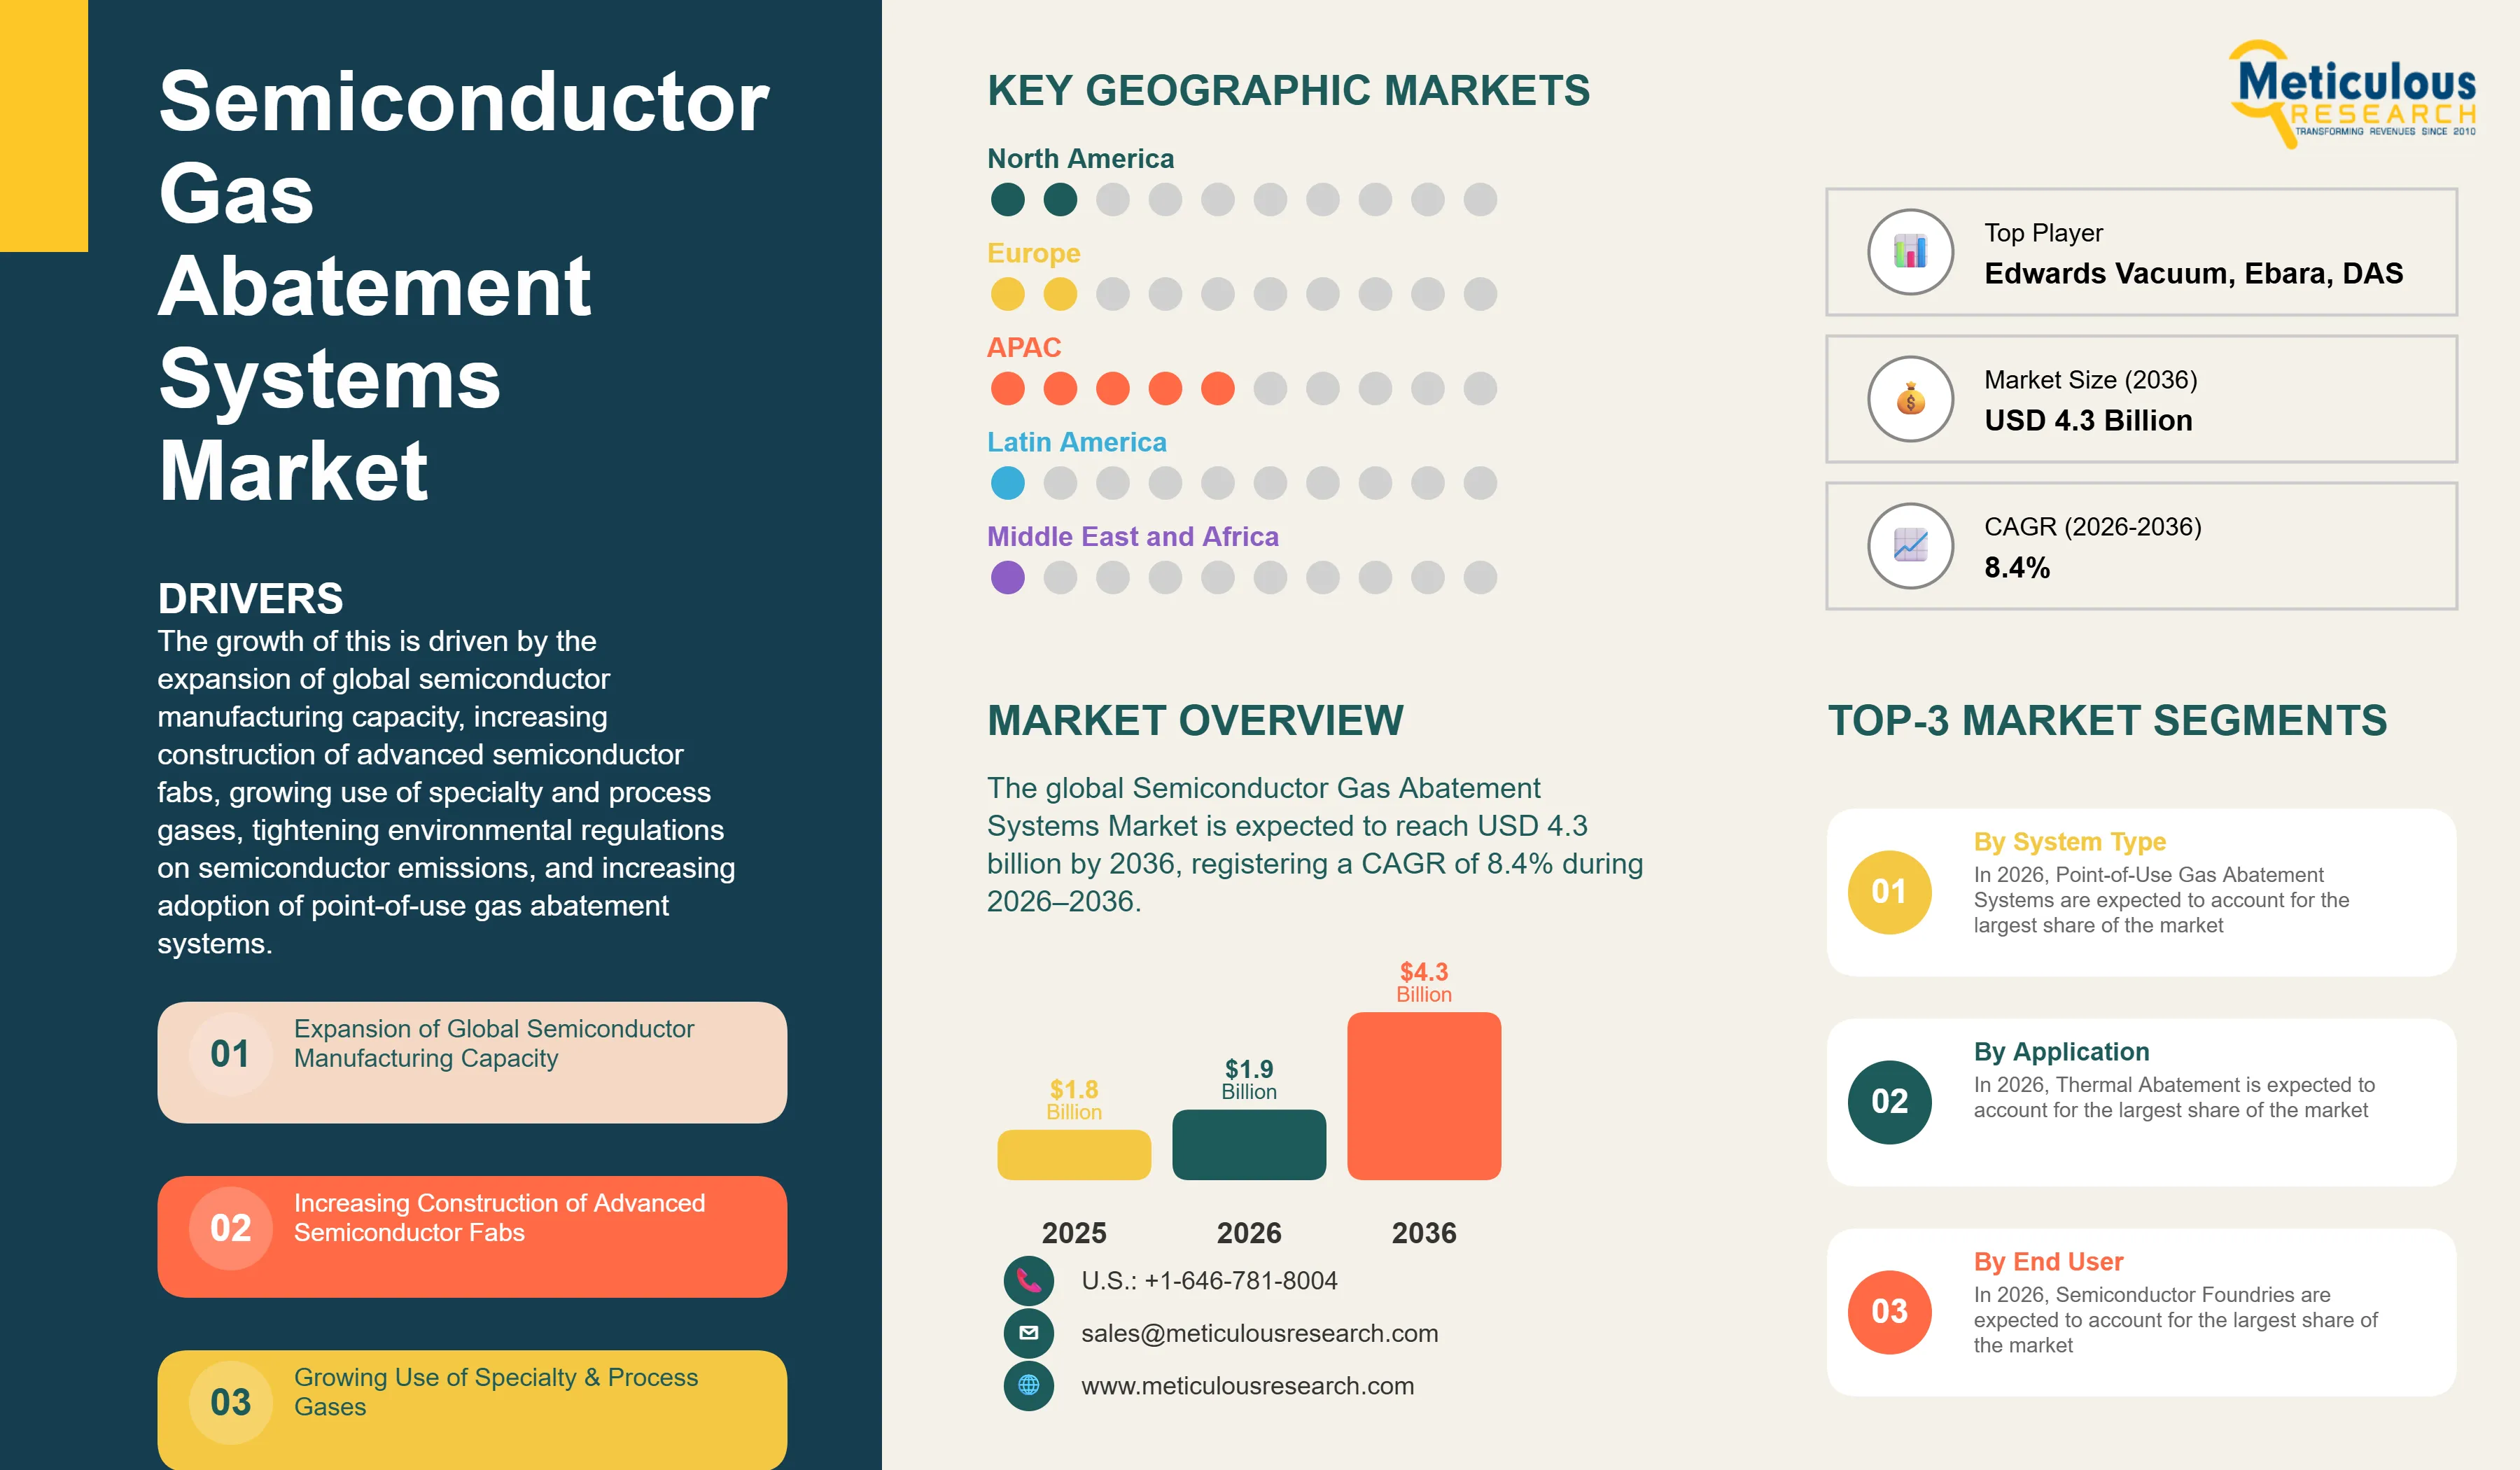
The global Semiconductor Gas Abatement Systems Market was valued at USD 1.8 billion in 2025 and is projected to reach USD 1.9 billion in 2026. The market is expected to reach USD 4.3 billion by 2036, registering a CAGR of 8.4% during the forecast period (2026–2036).
- Published
- Aug 2026
- Pages
- 277
- Format
- PDF + Excel
- Report ID
- MR-2142
- Base year
- 2025
- 2025 · BASELINE
- $1.80B
- 2036
- $4.30B
- CAGR 2026–2036
- 8.4%
2025 baseline · 2026–2036 forecast at 8.4% CAGR · hover a bar for the value
Key highlights
The global Semiconductor Gas Abatement Systems Market is projected to reach USD 4.3 billion by 2036, driven by expanding global semiconductor manufacturing capacity, growing use of specialty and process gases, and tightening environmental regulations on semiconductor emissions.
Asia-Pacific is expected to account for the largest market share in 2026, while North America is projected to register the fastest growth during the forecast period.
By system type, Point-of-Use Gas Abatement Systems are expected to account for the largest market share, whereas Integrated Abatement Systems are projected to witness the fastest growth through 2036.
By abatement technology, Thermal Abatement is expected to remain the dominant technology, owing to its efficiency in handling high gas flow rates and meeting stringent emission regulations.
Fluorinated process gases such as NF₃, CF₄, and SF₆ carry global warming potentials thousands of times greater than CO₂, making high-efficiency abatement essential to semiconductor manufacturers' environmental compliance and sustainability commitments.
Record global fab equipment spending, projected to reach USD 133 billion in 2026 and exceed USD 150 billion in 2027, is expected to create substantial long-term demand for new gas abatement system installations.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 8.4% |
| Format | PDF, Excel & Cloud Portal · 277 pages |
| Market Size (Value) in 2026 | USD 1.9 Billion |
| Market Size (Value) in 2036 | USD 4.3 Billion |
| Segments Covered | By System Type: Point-of-Use Gas Abatement Systems, Centralized Gas Abatement Systems, Integrated Abatement Systems, Gas Abatement Monitoring & Control Systems. · By Abatement Technology: Thermal Abatement, Plasma Abatement, Catalytic Abatement, Wet Scrubbing, Dry Abatement, Hybrid Abatement. · By Gas Type: Fluorinated Gases (NF₃, CF₄, C₂F₆, CHF₃, SF₆), Silane & Silicon-Containing Gases, Nitrogen-Containing Gases, Hydrogen & Hydrogen-Containing Gases, Oxygen-Containing Gases, Other Hazardous Process Gases. · By Semiconductor Process: Etching, Chemical Vapor Deposition (CVD), Atomic Layer Deposition (ALD), Plasma-Enhanced CVD (PECVD), Cleaning Processes, Epitaxy, Ion Implantation, Other Semiconductor Processes. · By Semiconductor Device: Logic Devices, Memory Devices (DRAM, NAND, HBM), Microprocessors & Microcontrollers, Analog & Mixed-Signal Devices, Power Semiconductors, RF & Connectivity Devices, Image Sensors, Compound Semiconductor Devices. · By Fab Type: Logic & Foundry Fabs, Memory Fabs, Analog & Power Semiconductor Fabs, Compound Semiconductor Fabs, MEMS & Sensor Fabs, Advanced Packaging Facilities. · By System Capacity: Small-Capacity Systems, Medium-Capacity Systems, Large-Capacity Systems, Multi-Tool/Multi-Chamber Systems. · By End User: Semiconductor Foundries, Integrated Device Manufacturers (IDMs), Memory Manufacturers, Compound Semiconductor Manufacturers, MEMS & Sensor Manufacturers, Advanced Packaging & OSAT Providers, Semiconductor R&D Facilities. |
| Countries Covered | North America: U.S., Canada. · Europe: Germany, France, U.K., Netherlands, Belgium, Ireland, Italy, Rest of Europe. · Asia-Pacific: Taiwan, China, South Korea, Japan, Singapore, India, Malaysia, Vietnam, Rest of Asia-Pacific. · Latin America: Brazil, Mexico, Argentina, Rest of Latin America. · Middle East & Africa: Israel, UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa. |
| Key Companies | Edwards Vacuum, Ebara Corporation, DAS Environmental Expert GmbH, Kanken Techno Co., Ltd., CS CLEAN SYSTEMS AG, Busch Vacuum Solutions, Ecosys Abatement, Plasma-Therm LLC, Linde plc, Air Liquide S.A., Fujifilm Holdings Corporation, MEKICS Co., Ltd., KNM Group Berhad, Kurita Water Industries Ltd., and Veolia Water Technologies. |
Report overview
Segments covered: system type, abatement technology, gas type, semiconductor process, semiconductor device, fab type, system capacity, end user.
The Semiconductor Gas Abatement Systems Market comprises the equipment and technologies used to treat and neutralize hazardous, corrosive, and greenhouse process gases released during semiconductor fabrication steps such as etching, chemical vapor deposition, atomic layer deposition, and chamber cleaning. Abatement systems span point-of-use units installed directly at individual process tools, centralized systems that treat combined exhaust streams from multiple tools, and increasingly, integrated multi-stage systems that combine thermal, plasma, and wet treatment technologies to achieve high destruction and removal efficiency across complex gas mixtures.
Gas abatement is a mission-critical, non-discretionary element of semiconductor fab infrastructure, driven by both process necessity and environmental compliance. Semiconductor manufacturing uses a range of fluorinated process gases, including NF₃, CF₄, C₂F₆, CHF₃, and SF₆, in etching and chamber cleaning applications. According to the U.S. Environmental Protection Agency (EPA), semiconductor manufacturing uses high-global-warming-potential fluorinated compounds including PFCs, NF₃, and SF₆, and under normal operating conditions, approximately 10% to 80% of fluorinated greenhouse gases can pass through process chambers unreacted. The EPA reports 100-year global warming potentials of up to 11,100 for PFCs, 16,100 for NF₃, and 23,500 for SF₆, compared with CO₂'s reference value of 1, underscoring the importance of effective abatement technologies. These characteristics make high-efficiency abatement systems essential to semiconductor manufacturers' environmental compliance and sustainability commitments.
The market is benefiting from record levels of global semiconductor manufacturing investment. According to SEMI's latest 300mm Fab Outlook published in April 2026, worldwide 300mm fab equipment spending is projected to increase 18% to US$133 billion in 2026 and a further 14% to US$151 billion in 2027, surpassing US$150 billion for the first time. SEMI is tracking 413 fabs and production lines globally in its current 300mm outlook, while total installed 300mm capacity is projected to increase by approximately 7% in 2026. This sustained expansion of semiconductor manufacturing capacity is directly supporting demand for point-of-use and centralized gas abatement systems installed alongside etch, deposition, and cleaning equipment.
The AI-driven memory buildout provides an additional demand catalyst. SEMI projects 300mm memory fab equipment investment to reach US$52 billion in 2026, representing a 29% year-over-year increase, with DRAM equipment spending expected to reach US$37 billion and 3D NAND spending US$14 billion. The expansion of advanced DRAM, HBM, 3D NAND, and leading-edge logic production requires increasingly complex deposition and etching processes, increasing the number and complexity of process-gas streams that must be treated. Consequently, continued investment in AI semiconductor capacity is expected to translate into sustained demand for high-efficiency thermal, plasma, catalytic, and wet gas abatement systems.
Report infographic
Market dynamics
8 factors across 4 forcesExpansion of Global Semiconductor Manufacturing Capacity
Sustained global investment in semiconductor manufacturing capacity, with SEMI projecting worldwide 300mm fab equipment spending to reach USD 133 billion in 2026 and USD 151 billion in 2027, is directly driving demand for gas abatement systems, as every new process tool installed in a fab requires an associated point-of-use or centralized abatement solution.
Increasing Construction of Advanced Semiconductor Fabs
Major semiconductor manufacturers are constructing new fabs across the United States, Taiwan, South Korea, Japan, and Europe to support both leading-edge and mature-node production, supported by regional policy incentives aimed at strengthening semiconductor supply chain resilience. Each new fab construction project requires comprehensive gas abatement infrastructure design and installation before production tools can be qualified for operation.
Table of contents
4 chapters · 295 sections · 277 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By System Type | Point-of-Use Gas Abatement Systems | Integrated Abatement Systems |
| By Abatement Technology | Thermal Abatement | Plasma Abatement |
| By Gas Type | Fluorinated Gases | Silane & Silicon-Containing Gases |
| By Semiconductor Process | Etching | Atomic Layer Deposition (ALD) |
| By Fab Type | Logic & Foundry Fabs | HBM Fabs, within the Memory Fabs |
| By End User | Semiconductor Foundries | Advanced Packaging & OSAT Providers |
By System Type
- Point-of-Use Gas Abatement Systems are expected to account for the largest market share, reflecting fabs' growing preference for tool-specific abatement solutions that provide higher destruction efficiency and reduce cross-contamination risk.
- However, Integrated Abatement Systems are projected to register the fastest growth during the forecast period, driven by increasing adoption of multi-stage hybrid systems capable of treating complex, multi-gas exhaust streams from advanced-node process tools.
By Abatement Technology
- Thermal Abatement is expected to account for the largest market share, owing to its proven efficiency in handling high gas flow rates and meeting stringent emission regulations across a wide range of process gases.
- However, Plasma Abatement is projected to register the fastest growth, supported by its increasing adoption for high-efficiency destruction of fluorinated gases in advanced-node etch and deposition applications.
By Gas Type
- Fluorinated Gases are expected to account for the largest market share, reflecting their widespread use in etching and chamber cleaning applications and the stringent abatement efficiency required given their high global warming potential.
- However, Silane & Silicon-Containing Gases are projected to register the fastest growth, driven by increasing use in deposition processes for advanced logic and memory device manufacturing.
By Semiconductor Process
- Etching is expected to account for the largest market share, given its intensive use of fluorinated process gases requiring dedicated abatement capacity.
- However, Atomic Layer Deposition (ALD) is projected to register the fastest growth, driven by its expanding role in advanced-node gate and interconnect formation, which requires precise gas chemistry control and associated abatement infrastructure.
By Fab Type
- Logic & Foundry Fabs are expected to account for the largest market share, consistent with SEMI's data identifying Logic & Micro, including Foundry, as the largest segment of global fab equipment spending.
- However, HBM Fabs, within the Memory Fabs segment, are projected to register the fastest growth, supported by surging demand for high-bandwidth memory used in AI accelerator chips.
By End User
- Semiconductor Foundries are expected to account for the largest market share, reflecting the scale of new fab construction underway among leading contract manufacturers.
- However, Advanced Packaging & OSAT Providers are projected to register the highest CAGR, driven by rising process gas use in advanced packaging applications such as hybrid bonding and 3D packaging.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Semiconductor Gas Abatement Systems Market. The region's leadership is supported by the concentration of semiconductor manufacturing capacity in Taiwan, South Korea, China, and Japan. According to SEMI's latest 300mm Fab Outlook, Taiwan, Korea, and China are expected to remain among the world's largest destinations for 300mm fab equipment investment, while global 300mm fab equipment spending is projected to reach US$133 billion in 2026. SEMI also projects that Taiwan's 300mm fab equipment investment will increase significantly through 2028, supported by continued expansion of leading-edge logic and advanced memory capacity. The expansion of 2nm and sub-2nm production in Taiwan is expected to require extensive new etching, deposition, and cleaning equipment and, consequently, additional point-of-use and centralized gas abatement infrastructure.
North America
Fastest growthHowever, North America is projected to register the highest CAGR during the forecast period. The region's growth is driven by large-scale new fab construction supported by domestic semiconductor manufacturing incentives. According to SEMI's 2026 300mm Fab Outlook, the Americas are projected to account for approximately US$60 billion in 300mm fab equipment spending during 2026–2028, making the region one of the fastest-growing destinations for semiconductor manufacturing investment. SEMI is also tracking more than 400 global 300mm fabs and production lines, with additional capacity being added to support AI, advanced logic, memory, and automotive semiconductor demand. Every new etch, deposition, and chamber-cleaning process tool installed across these fab construction projects generates demand for appropriate gas treatment infrastructure, directly supporting regional demand for point-of-use thermal, plasma, catalytic, and wet abatement systems.
Competitive landscape
The global Semiconductor Gas Abatement Systems Market is moderately consolidated, with competition among specialized gas abatement equipment manufacturers, industrial gas companies, and vacuum and exhaust system integrators. Companies compete primarily on destruction and removal efficiency performance, technology breadth across thermal, plasma, and wet abatement platforms, energy efficiency, and global service and support network coverage tied to major fab construction hubs.
Leading market participants are investing in developing higher-efficiency plasma and hybrid abatement technologies, expanding integrated monitoring and predictive maintenance capabilities, and forming strategic partnerships with semiconductor manufacturers and equipment OEMs to secure long-term system supply and service agreements tied to major new fab construction projects. Capacity expansions, technology upgrades, and energy-efficiency-focused product development remain key strategies adopted by major vendors.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Semiconductor Gas Abatement Systems Market. The key players profiled in the report include Edwards Vacuum, Ebara Corporation, DAS Environmental Expert GmbH, Kanken Techno Co., Ltd., CS CLEAN SYSTEMS AG, Busch Vacuum Solutions, Ecosys Abatement, Plasma-Therm LLC, Linde plc, Air Liquide S.A., Fujifilm Holdings Corporation, MEKICS Co., Ltd., KNM Group Berhad, Kurita Water Industries Ltd., and Veolia Water Technologies.
- Edwards Vacuum
- Ebara Corporation
- DAS Environmental Expert GmbH
- Kanken Techno Co., Ltd.
- CS CLEAN SYSTEMS AG
- Busch Vacuum Solutions
- Ecosys Abatement
- Plasma-Therm LLC
- Linde plc
- Air Liquide S.A.
- Fujifilm Holdings Corporation
- MEKICS Co., Ltd.
- KNM Group Berhad
- Kurita Water Industries Ltd.
- Veolia Water Technologies
Frequently asked questions
The global Semiconductor Gas Abatement Systems Market is estimated at USD 1.9 billion in 2026.
Cite this report
Meticulous Research. (2026). Semiconductor Gas Abatement Systems Market - Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2142). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/semiconductor-gas-abatement-systems-market-6825