Photolithography Materials Market (2026-2036)
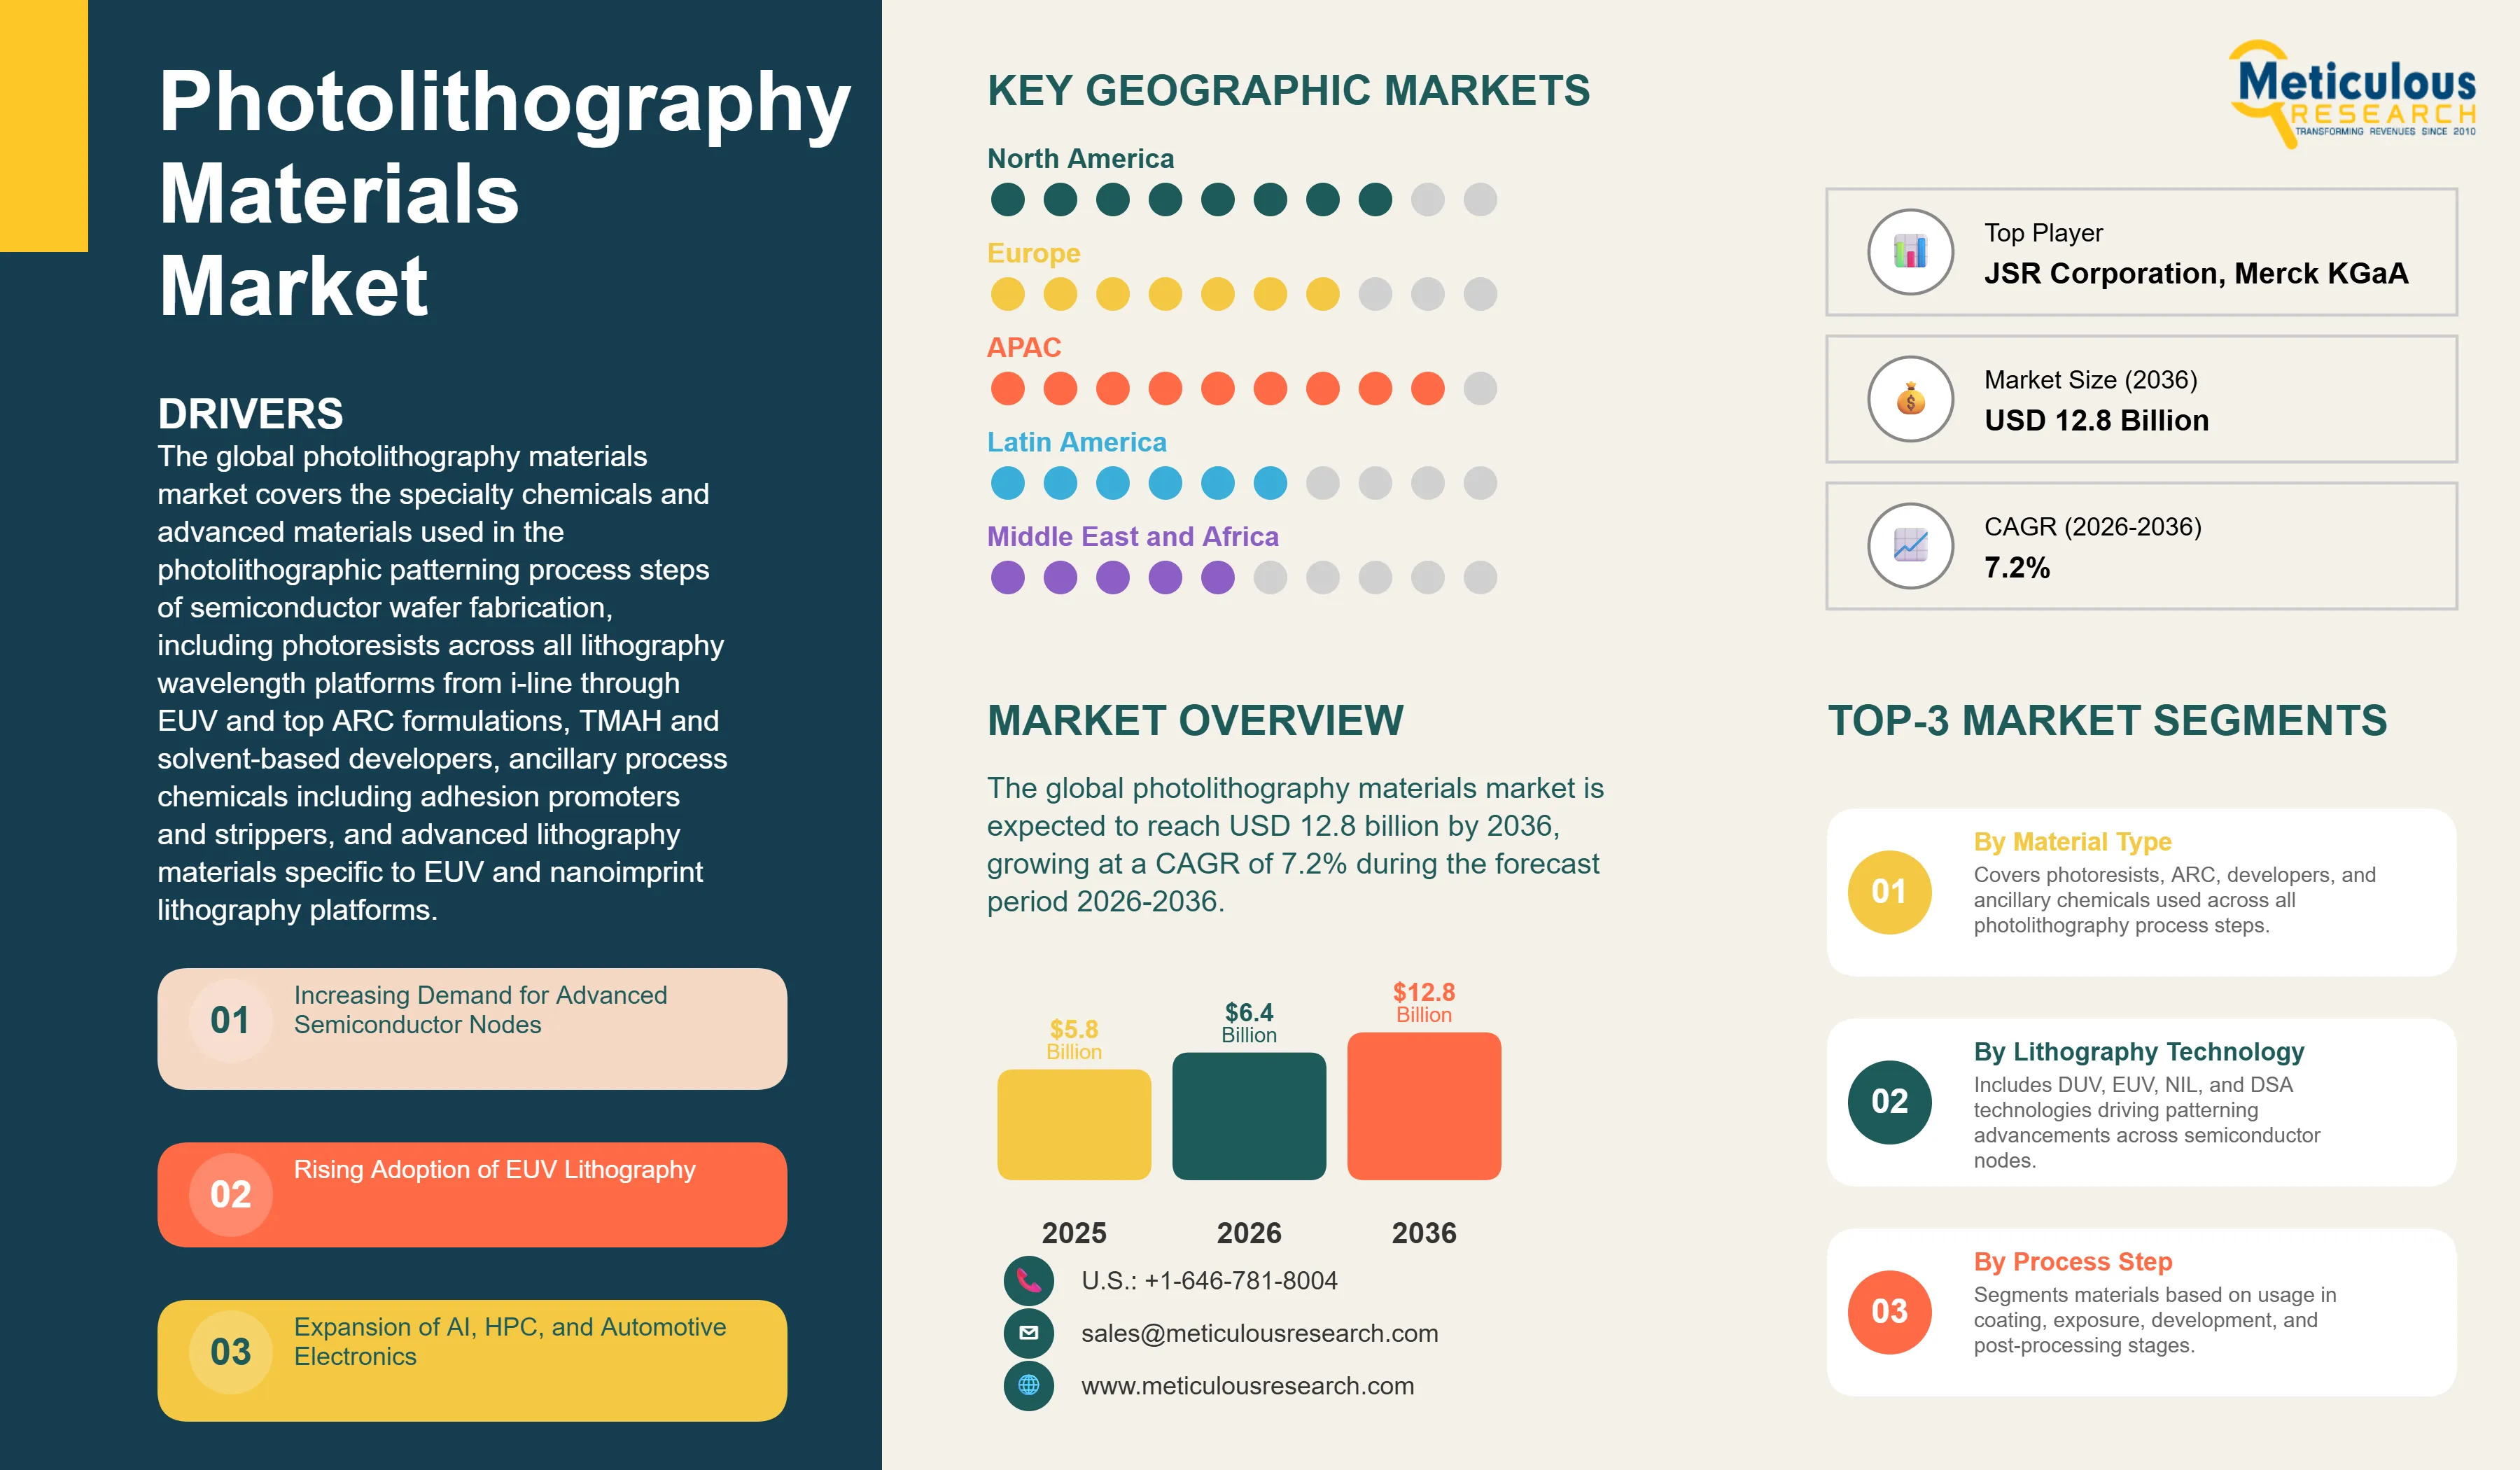
The global photolithography materials market was valued at USD 5.8 billion in 2025. This market is expected to reach USD 12.8 billion by 2036 from an estimated USD 6.4 billion in 2026, growing at a CAGR of 7.2% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 296
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041892
- Base year
- 2025
- 2025 · BASELINE
- $5.80B
- 2036
- $12.80B
- CAGR 2026–2036
- 7.2%
2025 baseline · 2026–2036 forecast at 7.2% CAGR · hover a bar for the value
Key highlights
The global photolithography materials market is projected to reach USD 12.8 billion by 2036.
The market is expected to grow at a CAGR of 7.2% during the forecast period 2026-2036.
The global photolithography materials market was valued at USD 5.8 billion in 2025 and is estimated to reach USD 6.4 billion in 2026.
Asia-Pacific is expected to dominate the global photolithography materials market with the largest market share in 2026, driven by the concentration of the world's leading semiconductor foundries and IDMs in Taiwan, South Korea, Japan, and China, which collectively account for the majority of global wafer fabrication capacity and therefore the largest share of photolithography material consumption across all lithography technology generations from i-line through EUV.
North America is projected to witness the fastest growth during the forecast period, driven by the U.S. CHIPS and Science Act investments catalyzing a major wave of domestic fab construction by TSMC in Arizona, Samsung in Texas, Intel across multiple U.S. sites, and Micron in Idaho and New York, which are creating rapidly growing domestic photolithography material demand centers in a region where consumption has historically been limited relative to Asia-Pacific production volumes.
By material type, the photoresists segment is expected to hold the largest share of the global photolithography materials market in 2026.
By lithography technology, the DUV segment is expected to hold the largest share in 2026.
By technology node, the 28 nm and above segment is expected to hold the largest share in 2026 by volume consumption, while the 3 nm and below segment is projected to register the highest CAGR.
By application, the foundry segment is expected to hold the largest share in 2026, reflecting pure-play foundries' dominant and growing share of global advanced semiconductor manufacturing capacity.
By end user, the foundries segment is expected to hold the largest share in 2026, while the OSAT segment is projected to register the highest CAGR.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 12.8 Billion |
| Market Size in 2026 | USD 6.4 Billion |
| Market Size in 2025 | USD 5.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 7.2% |
| Format | PDF, Excel & Cloud Portal · 296 pages |
| Dominating Material Type | Photoresists |
| Fastest Growing Material Type | Advanced Lithography Materials (EUV-Specific) |
| Dominating Lithography Technology | Deep Ultraviolet (DUV) |
| Fastest Growing Lithography Technology | Extreme Ultraviolet (EUV) |
| Dominating Technology Node | >=28 nm |
| Fastest Growing Technology Node | <=3 nm |
| Dominating Application | Foundry |
| Fastest Growing Application | Advanced Packaging |
| Dominating End User | Foundries |
| Fastest Growing End User | OSAT |
| Dominating Geography | Asia-Pacific |
| Fastest Growing Geography | North America |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: material type, lithography technology, end user.
The global photolithography materials market covers the specialty chemicals and advanced materials used in the photolithographic patterning process steps of semiconductor wafer fabrication, including photoresists across all lithography wavelength platforms from i-line through EUV, anti-reflective coatings including bottom ARC and top ARC formulations, TMAH and solvent-based developers, ancillary process chemicals including adhesion promoters, edge bead removers, thinners, and strippers, and advanced lithography materials specific to EUV, directed self-assembly, and nanoimprint lithography platforms. These materials are consumed across every patterned layer in semiconductor chip manufacturing and are critical determinants of the resolution, line edge roughness, defect density, and pattern fidelity that define device performance and manufacturing yield at each technology node.
The growth of the global photolithography materials market is primarily driven by the semiconductor industry's continued advancement along the technology node roadmap toward 3 nm, 2 nm, and sub-2 nm logic nodes that require progressively more sophisticated photoresist chemistries and process materials to achieve the pattern resolution, sensitivity, and defect performance required at leading-edge manufacturing. The rapid expansion of EUV lithography capacity at TSMC, Samsung Foundry, and Intel Foundry is creating strong demand for EUV-specific photoresist chemistries, anti-reflective underlayers, and associated process chemicals engineered for 13.5 nm wavelength exposure, representing the highest-value segment of the photolithography materials market with material costs per wafer layer significantly exceeding DUV equivalents.
Two significant opportunities are shaping the market's long-term trajectory. The progression toward High-NA EUV lithography, with ASML's EXE:5000 scanner entering production at Intel Foundry for its Intel 14A process, is creating demand for next-generation photoresist and underlayer materials specifically engineered for the 0.55 numerical aperture optical system and its tighter depth of focus that requires thinner resist films with enhanced etch resistance and sensitivity. The rapid growth of advanced packaging as a pathway for system performance scaling beyond single-chip transistor density improvements is creating a large and fast-growing new demand channel for photolithography materials in redistribution layer patterning, micro-bump formation, and through-silicon via processes at OSAT facilities and integrated packaging foundries.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Demand for Advanced Semiconductor Nodes
The semiconductor industry's continued advancement toward sub-3 nm and sub-2 nm logic nodes is the primary structural driver of the photolithography materials market, as each successive technology node generation requires new or substantially reformulated photoresist chemistries, anti-reflective coating architectures, and ancillary process chemicals engineered to meet the tighter resolution, line edge roughness, defect density, and etch selectivity specifications of the smaller feature dimensions and more complex multi-layer patterning schemes required at leading-edge nodes. The transition from DUV multi-patterning to EUV single exposure and the progression toward High-NA EUV for sub-2 nm nodes each represent step-change increases in photolithography material performance requirements that create commercial opportunities for material suppliers with the R&D capability to develop qualified products meeting the new specifications. The computing semiconductor demand driven by AI accelerator chip production, the memory demand driven by high-bandwidth memory for AI systems, and the logic demand driven by smartphone and PC application processor advancement are all sustaining leading-edge node fabrication investment and the associated photolithography material demand.
Growing Global Fab Investments
The unprecedented wave of semiconductor fabrication investment being driven by the U.S. CHIPS and Science Act, the EU Chips Act, Japan's semiconductor reindustrialization programs, India's semiconductor incentive scheme, and the parallel capacity expansion programs of TSMC, Samsung, Intel, Micron, SK Hynix, and domestic Chinese manufacturers is creating the largest sustained increase in global wafer fabrication capacity in semiconductor industry history. New fab construction investments of several hundred billion dollars collectively announced for the 2024 to 2030 period represent direct capital expenditure programs that will require photolithography materials procurement at every production stage from facility qualification and process development through full-volume production ramp. Each new advanced logic or memory fab entering production represents a sustained and growing annual photolithography material procurement program extending across the facility's multi-decade operational lifetime, providing long-term revenue visibility for qualified photolithography material suppliers contracted to supply new manufacturing programs.
Table of contents
14 chapters · 193 sections · 296 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Material Type | Photoresists | Advanced lithography materials |
| By Lithography Technology | DUV | EUV |
| By Technology Node | >=28 nm | 3 nm and below |
| By Application | Foundry | Advanced packaging |
| By End User | Foundries | OSAT |
By Material Type
- Photoresists to Dominate
- The photoresists segment is expected to account for the largest share of the global photolithography materials market.
- The large share of this segment is attributed to photoresists representing the primary functional patterning material applied at every photolithographic layer in wafer fabrication, the high dollar value per unit volume of advanced DUV and EUV photoresist formulations that can cost several thousand dollars per liter for leading-edge EUV products, and the broad consumption base spanning legacy i-line and KrF photoresists used in mature node production through ArF immersion resists at 7 to 14 nm and EUV resists at 5 nm and below.
- JSR Corporation, Tokyo Ohka Kogyo, Shin-Etsu Chemical, Fujifilm, and Sumitomo Chemical collectively supply the large majority of the global photoresist market.
- However, the advanced lithography materials segment is poised to register the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the accelerating expansion of EUV lithography capacity at leading foundries driving demand for EUV-specific underlayer and topcoat materials, the commercial introduction of High-NA EUV driving a new generation of resist and process material development, and the increasing commercial activity in directed self-assembly and nanoimprint lithography material platforms targeting specific advanced patterning applications.
By Lithography Technology
- DUV to Hold the Largest Share
- The DUV segment is expected to account for the largest share of the global photolithography materials market.
- This dominance reflects the vast installed base of DUV lithography scanners globally spanning KrF, ArF dry, and ArF immersion platforms that serve the full range of semiconductor manufacturing from legacy mature nodes through leading-edge 7 nm production via multi-patterning, generating very large and sustained photoresist, ARC, and developer material consumption volumes across thousands of production scanner tools at foundries and IDMs worldwide.
- However, the EUV segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the continued rapid expansion of EUV scanner installations at TSMC, Samsung Foundry, and Intel Foundry for advanced logic production and the ramp of EUV in DRAM manufacturing at Samsung, SK Hynix, and Micron for sub-1z and sub-1alpha DRAM nodes, each new scanner installation representing sustained annual photoresist and process chemical consumption at EUV material pricing levels substantially above DUV equivalents.
By Technology Node
- The >=28 nm Segment to Hold the Largest Share
- The 28 nm and above segment is expected to account for the largest share of the global photolithography materials market by consumption volume, as legacy and mature node semiconductor manufacturing at 28 nm, 40 nm, 65 nm, 90 nm, and above collectively represents the largest installed base of semiconductor fabrication capacity globally and generates very high aggregate photolithography material consumption volumes across the thousands of mature node wafer starts processed monthly at high-volume manufacturing facilities worldwide, including the rapidly expanding mature node capacity being built in China.
- However, the 3 nm and below segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the advancing production ramp of TSMC's N3 and N2 node families, Samsung Foundry's 3GAE and 2 nm SF2 processes, and Intel Foundry's Intel 18A and future Intel 14A platforms, all of which use multiple EUV exposure layers per chip manufacturing flow and consume photolithography materials at the highest per-wafer value intensity of any technology node generation, supporting very high revenue growth despite more modest wafer volume growth compared with mature nodes.
By Application
- Foundry to Hold the Largest Share
- The foundry segment is expected to account for the largest share of the global photolithography materials market.
- This dominance reflects pure-play foundries' dominant and increasing share of global semiconductor manufacturing capacity, anchored by TSMC's leading market position supplying the large majority of the world's most advanced logic chip production for Apple, NVIDIA, AMD, Qualcomm, and MediaTek, and the growing capacity of Samsung Foundry, GlobalFoundries, UMC, and SMIC collectively representing a large and growing photolithography material consumption base across all technology nodes from mature to leading-edge.
- However, the advanced packaging segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the rapid adoption of photolithography-based redistribution layer patterning and micro-bump formation in advanced packaging workflows by OSAT companies and integrated packaging foundries, the growing volume of AI accelerator chiplet packages and high-bandwidth memory stacks requiring fine-pitch interconnect lithography, and the progressive expansion of advanced packaging from a small number of leading-edge applications toward broader semiconductor assembly production that is progressively displacing conventional wire bond and flip-chip packaging in new design starts.
By End User
- Foundries to Hold the Largest Share
- The foundries segment is expected to account for the largest share of the global photolithography materials market.
- Pure-play foundries represent the dominant photolithography material consumption channel, as their business model of manufacturing chips for fabless semiconductor companies across the full range of technology nodes from legacy through leading-edge generates high-volume, continuous material procurement programs that constitute the primary revenue base for photolithography material suppliers.
- TSMC alone, as the world's largest semiconductor foundry with over 50% of global foundry revenue, represents an extraordinary concentration of photolithography material demand that makes it the single most important customer account for the majority of photoresist and specialty chemical suppliers serving the semiconductor industry.
- However, the OSAT segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by OSAT companies' rapid adoption of advanced packaging processes requiring photolithographic patterning, creating new photolithography material demand at packaging facilities that have historically required only wire bond and conventional flip-chip assembly chemicals.
- The expanding OSAT advanced packaging capacity investment programs of ASE Group, Amkor Technology, JCET, and Powertech Technology in response to AI package demand are establishing a new and growing photolithography material consumption base within the OSAT segment.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global photolithography materials market. The largest share of this region is mainly due to the concentration of the world's leading semiconductor foundries and IDMs in Taiwan, South Korea, Japan, and China, which collectively process the large majority of global semiconductor wafer output and therefore consume the largest share of photolithography materials across all technology generations. TSMC's multiple Hsinchu, Taichung, Tainan, and Kaohsiung fab complexes in Taiwan collectively represent the largest single-country photolithography material consumption base globally, followed by Samsung's Hwaseong, Pyeongtaek, and Giheung complexes and SK Hynix's Icheon and Cheongju facilities in South Korea. Japan's photolithography materials market benefits from both the domestic consumption of Sony Semiconductor, Kioxia, and Renesas manufacturing facilities and the dominant role of Japanese photoresist and specialty chemical suppliers including JSR, Tokyo Ohka Kogyo, Shin-Etsu Chemical, and Fujifilm that serve global semiconductor manufacturers from Japanese production bases. China's photolithography material demand is growing rapidly as SMIC, CXMT, and YMTC expand domestic semiconductor manufacturing capacity at mature and mid-range technology nodes.
North America
Fastest growthHowever, the North American photolithography materials market is expected to grow at the fastest CAGR during the forecast period. North America's rapid growth is driven by the unprecedented wave of semiconductor manufacturing investment catalyzed by the CHIPS and Science Act's USD 52 billion in semiconductor manufacturing incentives, which is bringing TSMC's three-fab Arizona complex, Samsung's Taylor and Austin Texas facilities, Intel's Ohio, Arizona, and New Mexico facilities, Micron's Idaho and New York memory fabs, and GlobalFoundries' U.S. capacity expansions into production over the 2025 to 2030 period. These new facilities collectively represent tens of gigawatts of additional U.S. semiconductor manufacturing capacity that will require sustained photolithography material supply streams, creating a large new North American photolithography material demand center that global suppliers including JSR, Tokyo Ohka Kogyo, Merck, DuPont, Brewer Science, and Avantor are investing to serve through U.S. manufacturing and distribution capacity expansion.
Europe
Europe's photolithography materials market is supported by the strong domestic semiconductor specialty chemical industry anchored by Merck KGaA's Semiconductor Solutions division in Darmstadt, BASF's electronic materials business, and the photoresist and ARC activities of regional specialty chemical producers, as well as the growing European semiconductor manufacturing base including ASML's EUV scanner manufacturing in Veldhoven that positions the Netherlands as a center of EUV ecosystem activity. The EU Chips Act's EUR 43 billion investment mobilization program is supporting fab expansions by Intel in Magdeburg, TSMC in Dresden, Infineon in Austria, and STMicroelectronics across multiple European sites that will increase European photolithography material consumption through the forecast period.
Competitive landscape
- JSR Corporation · Japan
- Tokyo Ohka Kogyo Co. Ltd. · Japan
- Shin-Etsu Chemical Co. Ltd. · Japan
- Fujifilm Holdings Corporation · Japan
- Merck KGaA · Germany
- DuPont de Nemours Inc. (U.S.)
- Sumitomo Chemical Co. Ltd. · Japan
- Dongjin Semichem Co. Ltd. · South Korea
- LG Chem Ltd. · South Korea
- Samsung SDI Co. Ltd. · South Korea
- BASF SE · Germany
- Cabot Microelectronics (U.S.)
- Avantor Inc. (U.S.)
- Brewer Science Inc. (U.S.)
- Allresist GmbH · Germany
Frequently asked questions
The global photolithography materials market is expected to reach USD 12.8 billion by 2036 from an estimated USD 6.4 billion in 2026, at a CAGR of 7.2% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Photolithography Materials Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRCHM - 1041892). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/photolithography-materials-market-6575