Orthopedic Implants Market (2026-2036)
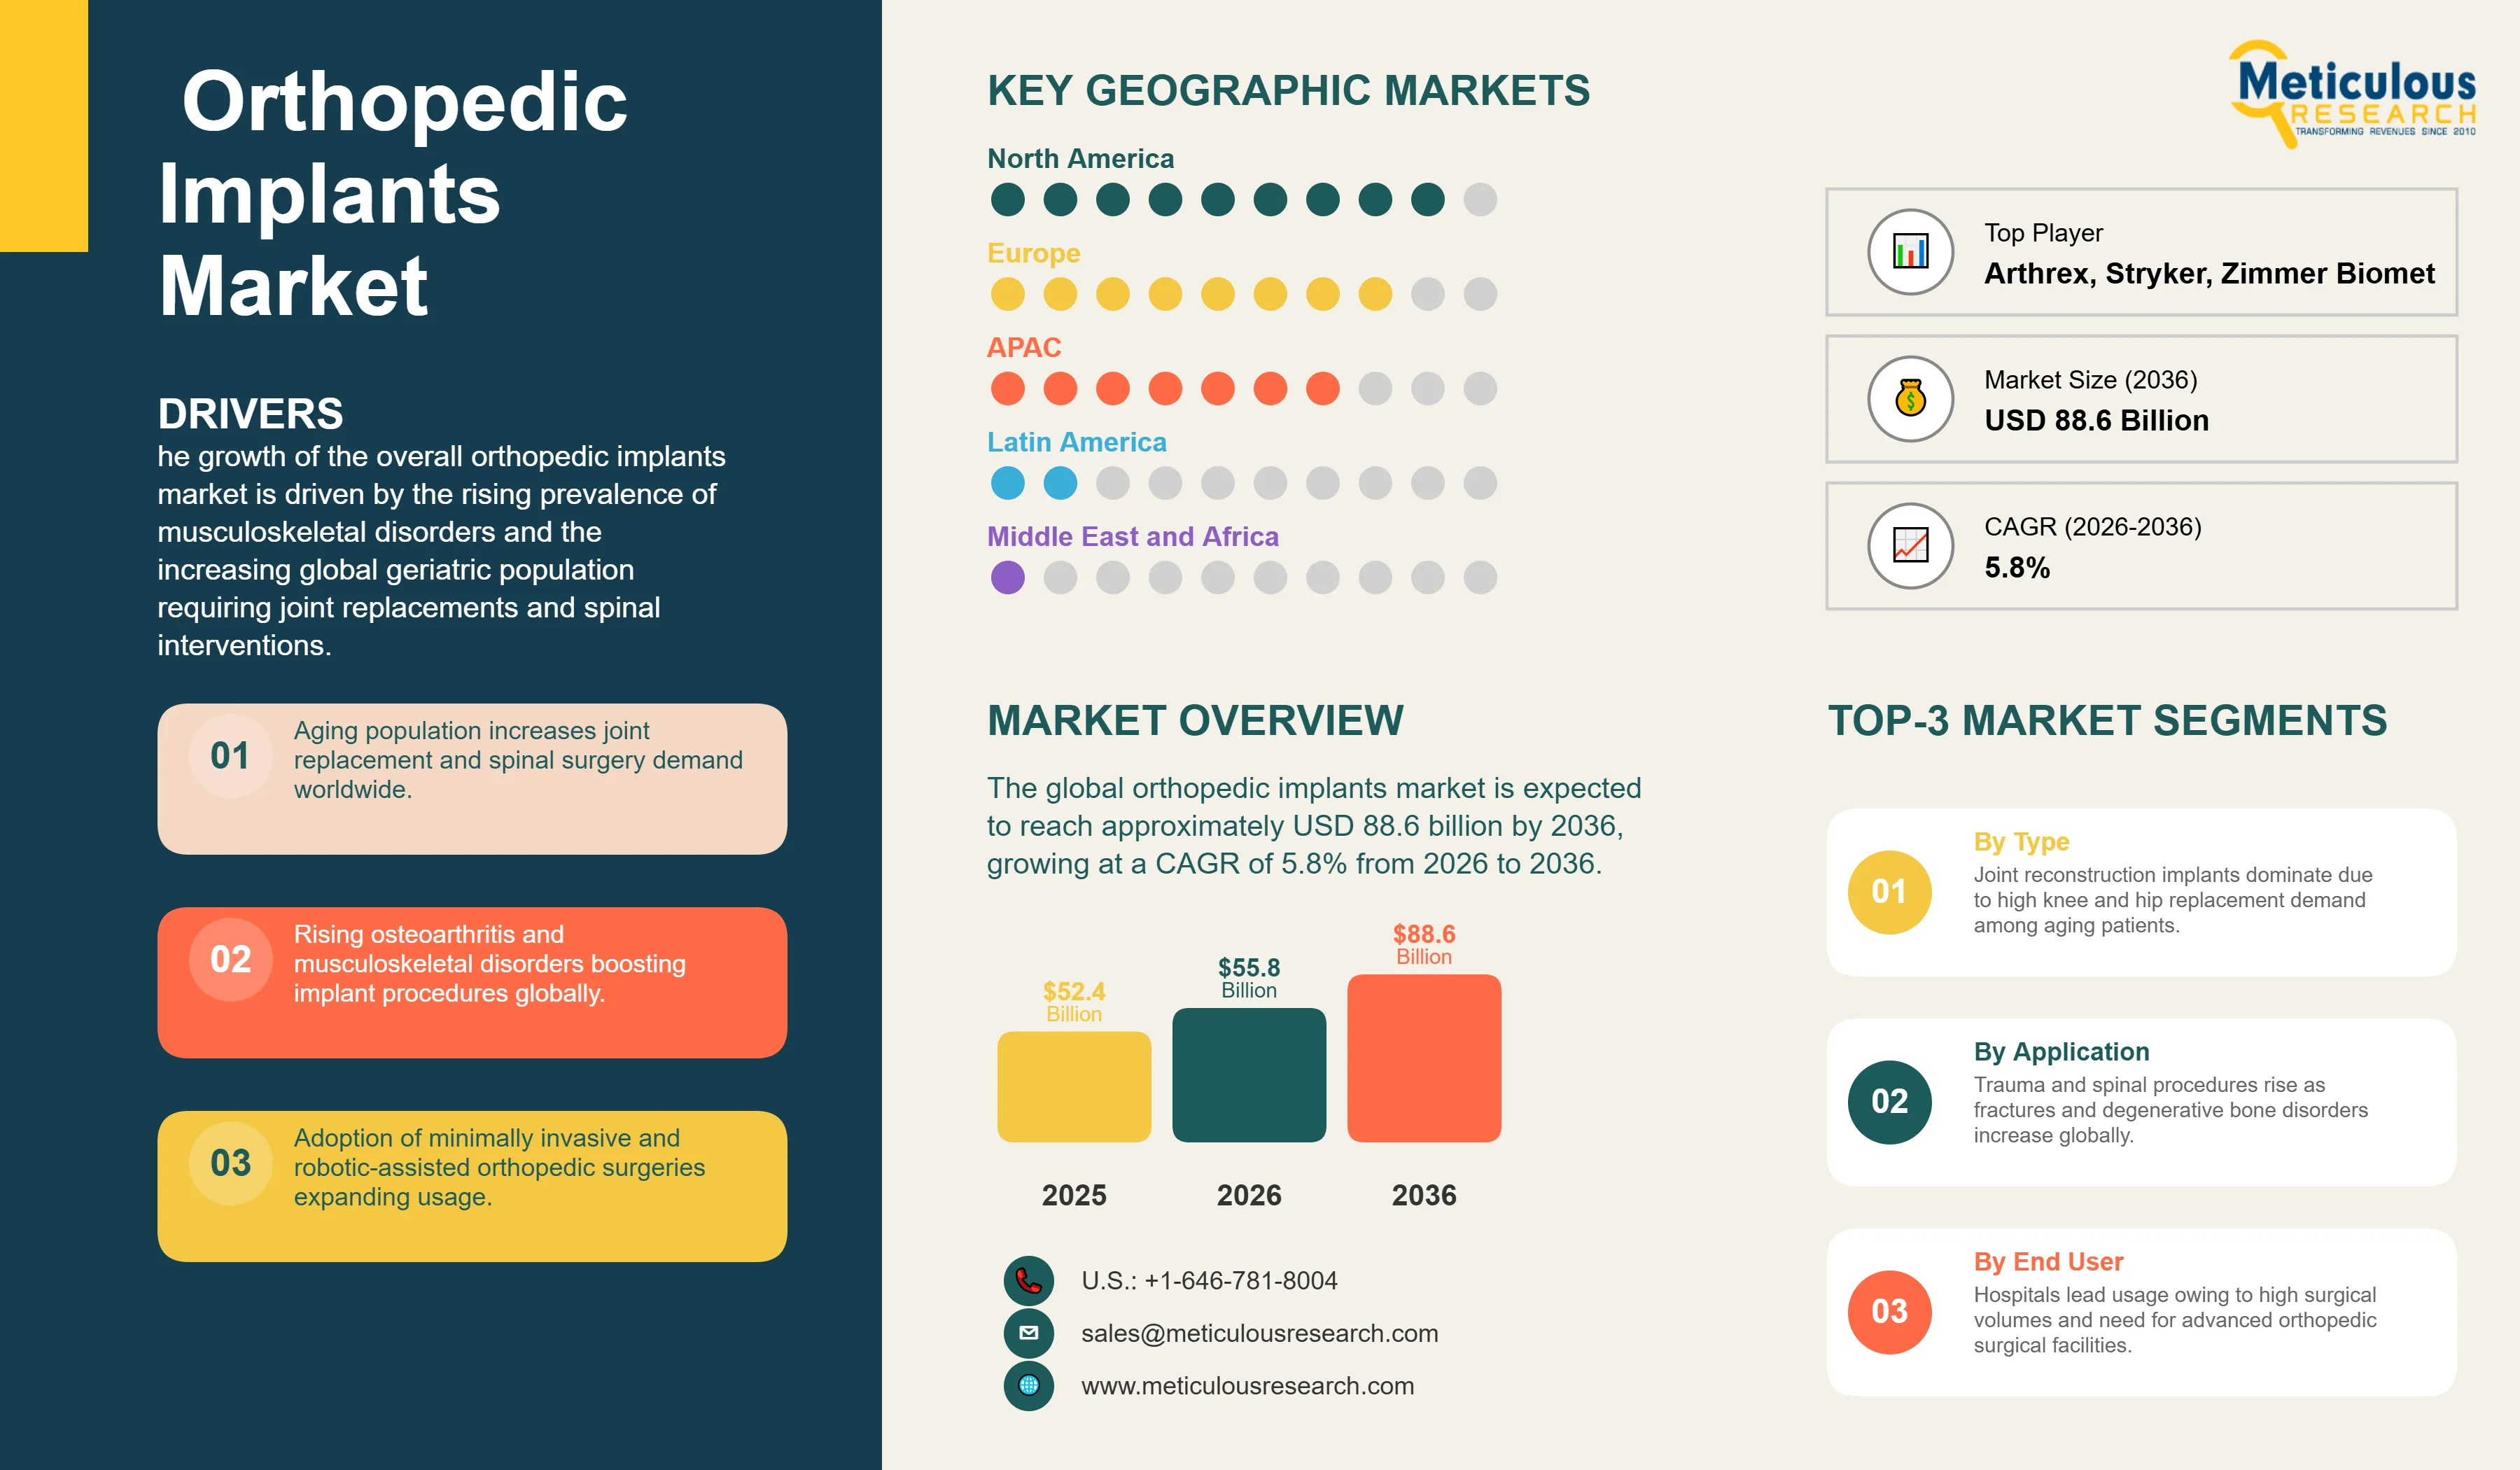
The global orthopedic implants market was valued at USD 52.4 billion in 2025. The market is expected to reach approximately USD 88.6 billion by 2036 from USD 55.8 billion in 2026, growing at a CAGR of 5.8% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 272
- Format
- PDF + Excel
- Report ID
- MR-1750
- Base year
- 2025
- 2025 · BASELINE
- $52.40B
- 2036
- $88.60B
- CAGR 2026–2036
- 5.8%
2025 baseline · 2026–2036 forecast at 5.8% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global orthopedic implants market is projected to reach USD 88.6 billion by 2036.
The market is expected to grow at a CAGR of 5.8% from 2026 to 2036.
North America dominates the global orthopedic implants market with the largest market share in 2026, driven by high healthcare expenditure, advanced surgical infrastructure, and the presence of leading manufacturers in the United States.
Asia Pacific is expected to witness the fastest growth during the forecast period, supported by increasing medical tourism, improving healthcare accessibility, and the rapid expansion of private orthopedic clinics in China, India, and Japan.
By product type, the joint reconstruction segment holds the largest market share in 2026, particularly in supporting the massive demand for knee and hip replacements among the aging population.
By material, the metallic segment holds the largest market share in 2026, due to its proven mechanical strength, durability, and biocompatibility in load-bearing applications.
By end-user, the hospitals segment holds the largest share of the overall market in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 88.6 Billion |
| Market Size in 2026 | USD 55.8 Million |
| Market Size in 2025 | USD 52.4 Million |
| Market Growth Rate (2026-2036) | CAGR of 5.8% |
| Format | PDF, Excel & Cloud Portal · 272 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Product Type, Material, Procedure, End-user, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: product type, material, procedure, end-user.
The growth of the overall orthopedic implants market is driven by the rising prevalence of musculoskeletal disorders and the increasing global geriatric population requiring joint replacements and spinal interventions. As manufacturers seek to integrate more biocompatible materials and address the demand for personalized surgical solutions, advanced orthopedic implant systems have become essential for restoring mobility and improving the quality of life for patients worldwide. The rapid expansion of minimally invasive surgical (MIS) techniques and the increasing adoption of robotic-assisted orthopedic procedures continue to fuel significant growth of this market across all major geographic regions.
Orthopedic implants are specialized medical devices used to replace or support damaged bone and joint structures, facilitating functional restoration and pain relief. These systems include joint prostheses, spinal fusion devices, trauma plates, and dental implants, which are designed to withstand significant mechanical stress and integrate seamlessly with biological tissues. The market is defined by high-performance materials such as titanium alloys, advanced ceramics, and PEEK polymers, which significantly enhance the longevity and stability of implants in diverse clinical applications. These systems are indispensable for surgeons seeking to optimize patient outcomes and meet the rising demand for active lifestyle preservation.
The market includes a diverse range of solutions, ranging from standard off-the-shelf implants for routine procedures to complex patient-specific designs for revision surgeries and oncology cases. These systems are increasingly integrated with advanced technologies such as 3D printing (additive manufacturing) and bioactive coatings to provide services such as improved osseointegration and reduced risk of implant failure. The ability to provide stable, high-precision results while minimizing surgical trauma has made advanced orthopedic implants the technology of choice for healthcare providers where clinical efficiency and patient safety are paramount.
The global healthcare sector is pushing hard to modernize surgical capabilities, aiming to reduce hospital stays and personalized recovery goals. This drive has increased the adoption of smart implants featuring integrated sensors, with advanced data analytics helping to monitor implant health and patient activity levels in real-time. At the same time, the rapid growth in the ambulatory surgical center (ASC) market is increasing the need for high-reliability, clinically-proven implant systems tailored for outpatient settings.
Report infographic
Market dynamics
4 factors across 3 forcesAging Population and Rise of Chronic Bone Disorders
A key driver of the orthopedic implants market is the rapid movement of the global healthcare industry toward active-aging, highly functional recovery. Global patient demand for active lifestyles, effective joint preservation, and minimally invasive treatments has created significant incentives for the adoption of advanced orthopedic implants. The trend toward “outpatient” surgery and the integration of implants into daily mobility routines drive manufacturers toward scalable solutions that modern orthopedics can uniquely provide. It is estimated that as global life expectancy rises and diagnostic tools for osteoarthritis become more accessible through 2036, the need for robust, effective implants increases significantly; therefore, joint reconstruction and spinal systems, with their ability to ensure high-density mechanical support, are considered a crucial enabler of modern geriatric care strategies.
Table of contents
11 chapters · 94 sections · 272 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Joint Reconstruction Implants | — |
| By Application/End-user | Hospital | Ambulatory surgical centers (ASCs) |
| By Material | Metallic | — |
By Product Type
- The joint reconstruction segment accounts for a significant portion of the overall orthopedic implants market in 2026.
- This is mainly attributed to the versatile use of this technology in supporting daily mobility and pain relief within extremely diverse patient populations, such as the elderly and sports professionals.
- These systems offer the most comprehensive way to ensure skeletal integrity across diverse high-frequency movements.
- The knee and hip replacement sectors alone consume a large share of orthopedic implant production, with major projects in North America and Europe demonstrating the technology’s capability to handle high-density mechanical requirements.
- However, the orthobiologics and smart implant segments are expected to grow at a rapid CAGR during the forecast period, driven by the growing need for biological healing, clinical procedures, and regenerative medicine systems.
By Application/End-user
- The hospitals segment holds the largest share of the overall market in 2026.
- This is primarily due to the massive volume of orthopedic surgeries performed in inpatient settings and the rigorous safety standards required for complex surgical interventions.
- Current large-scale healthcare facilities are increasingly specifying high-density implant integrations to ensure compliance with global clinical standards and patient expectations for faster, visible recovery results.
- The ambulatory surgical centers (ASCs) segment is expected to witness the fastest growth during the forecast period.
- The shift toward outpatient orthopedics and the complexity of minimally invasive surgical suites are pushing the requirement for advanced implant systems that can handle varied procedural types and mechanical stresses while ensuring absolute reliability for cost-effective healthcare systems.
By Material
- The metallic segment commands the largest share of the global orthopedic implants market in 2026.
- This dominance stems from its superior mechanical stability, structural consistency in records, and excellent biocompatibility for load-bearing joints, making it the material of choice for high-performance orthopedic products.
- Large-scale operations in joint replacement, trauma fixation, and spinal fusion drive demand, with advanced alloys from suppliers like Zimmer Biomet and Stryker enabling reliable performance in extreme physiological environments.
- However, the ceramic and polymeric segments are poised for steady growth through 2036, fueled by expanding applications in wear-resistant surfaces and radiolucent spinal formulations.
- Manufacturers face mounting pressure to optimize outcomes for younger, more active patients, where advanced ceramics provide a low-friction alternative for long-term implant survival.
Geographic analysis
North America
Largest shareNorth America holds the largest share of the global orthopedic implants market in 2026. The largest share of this region is primarily attributed to the massive healthcare expenditure and the presence of the world’s most advanced orthopedic manufacturing hubs, particularly in the United States. The U.S. alone accounts for a significant portion of global orthopedic implant production, with its position as a leading innovator of surgical technology driving sustained growth. The presence of leading manufacturers like Zimmer Biomet and Stryker and a well-developed clinical research network provides a robust market for both standard and high-density orthopedic solutions.
Europe
Europe and Asia-Pacific together account for a substantial share of the global orthopedic implants market. The growth of these markets is mainly driven by the need for technological modernization in the geriatric care, sports medicine, and trauma sectors. The demand for advanced implant systems in Europe is mainly due to its stringent regulatory standards and the presence of innovators like Smith & Nephew and Medtronic.
Asia-Pacific
In Asia-Pacific, the leadership in medical tourism and the push for surgical safety innovation are driving the adoption of high-reliability orthopedic implants. Countries like China, India, and Japan are at the forefront, with significant focus on integrating robotic-assisted solutions into daily surgical routines and advanced implant treatments to ensure the highest levels of performance and reliability.
Latin America
Latin America is witnessing significant expansion in the orthopedic implants market, driven by the region’s emergence as a critical hub for private healthcare services and medical device manufacturing. Countries like Brazil, Mexico, and Colombia are increasingly adopting digital surgical planning to meet international clinical standards and ensure the “quality” credentials of their healthcare providers. The presence of global orthopedic giants and a growing focus on the medical device value chain provide a fertile ground for advanced implant solutions.
Middle East & Africa
In the Middle East & Africa, the market is fueled by the rapid development of specialized orthopedic hospitals and the establishment of new medical cities, particularly in Saudi Arabia and the UAE. These nations are integrating advanced orthopedic passports into their smart healthcare and sustainable wellness initiatives to ensure long-term patient performance. Additionally, the focus on trauma care in regions like South Africa and Egypt is driving the adoption of high-reliability implant systems to ensure effective healing and compliance with global healthcare regulations.
Competitive landscape
- Zimmer Biomet
- Stryker Corporation
- Johnson & Johnson (DePuy Synthes)
- Smith & Nephew plc
Frequently asked questions
The global orthopedic implants market is expected to grow from USD 55.8 billion in 2026 to USD 88.6 billion by 2036.
Cite this report
Meticulous Research. (2026). Orthopedic Implants Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1750). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/orthopedic-implants-market-6433