Li-ion Battery Recycling Market (2024-2031)
The Li-ion Battery Recycling Market was valued at $1.7 billion in 2023. This market is expected to reach $8.6 billion by 2031 from an estimated $2.1 billion in 2024, at a CAGR of 22.3% during the forecast period from 2024 to 2031. Li-ion Battery Recycling Market Size & Forecast The growth of this market
- Published
- Sep 2024
- Pages
- 330
- Format
- PDF + Excel
- Report ID
- MROTH - 104797
- Base year
- 2023
- 2023 · BASELINE
- $1.70B
- 2031
- $8.60B
- CAGR 2024–2031
- 22.3%
2023 baseline · 2024–2031 forecast at 22.3% CAGR · hover a bar for the value
Key highlights
The Contractual Services Segment to Dominate the Li-ion Battery Recycling Market in 2024
The Lithium Nickel Manganese Cobalt Oxide (NMC) Segment to Dominate the Li-ion Battery Recycling Market in 2024
The Pyrometallurgical Process Segment to Dominate the Li-ion Battery Recycling Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 330 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 22.3% |
| Market Size (Value) | USD 8.6 Billion by 2031 |
| Segments Covered | By Business Model · Contractual Recycling Services · Contractual Recycling Services, By Source · Lithium-ion Cell Manufacturing Waste · Electronic Portable Devices · Electric Vehicles · Energy Storage Systems · Other Sources · Contractual Recycling Services, By End-use Industry · Consumer Electronics · Automotive · Industrial · Power & Utility · Other End-use Industries · Direct-to-Market · Direct-to-Market, By Source · Lithium-ion Cell Manufacturing Waste · Electronic Portable Devices · Electric Vehicles · Energy Storage Systems · Other Sources · Direct-to-Market, By End-use Industry · Consumer Electronics · Automotive · Industrial · Power & Utility · Other End-use Industries · Direct-to-Market, By Material · Graphite · Nickel · Cobalt · Copper · Manganese · Lithium · Aluminum · Iron · Other Materials · By Battery Type · Lithium Cobalt Oxide (LCO) · Lithium Iron Phosphate (LFP) · Lithium Manganese Oxide (LMO) · Lithium Nickel Cobalt Aluminum Oxide (NCA) · Lithium Nickel Manganese Cobalt Oxide (NMC) · Lithium Titanate Oxide (LTO) · By Recycling Process · Pyrometallurgical Process · Hydrometallurgical Process · Other Recycling Processes |
| Countries Covered | Europe (Germany, U.K., France, Italy, Spain, Switzerland, Belgium, Norway, Poland, Finland, Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Singapore, Australia & New Zealand, Malaysia, Rest of Asia-Pacific), North America (U.S., Canada), Latin America (Brazil, Argentina, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Saudi Arabia, South Africa, and Rest of the Middle East & Africa) |
| Key Companies | Duesenfeld GmbH (Germany), RecycLiCo Battery Materials Inc. (Canada), Li-Cycle Holdings Corp. (Canada), Cirba Solutions (U.S.), Accurec-Recycling GmbH (Germany), Redux Recycling GmbH (U.S.), Redwood Materials, Inc. (U.S.), Glencore plc (Switzerland), Fortum Corporation (Finland), Trishulavel Eshan Pvt Ltd (Li-Circle) (India), SNAM S.A.S (A subsidiary of Floridienne S.A) (France), Primobius GmbH (Germany), MTB GROUP (France), Tata Chemicals Limited (India), OnTo Technology (U.S.), American Battery Technology Company (U.S.), Attero Recycling Pvt. Lyd. (India), Umicore SA (Belgium), Lithion Recycling Inc. (Canada), Ascend Elements, Inc. (U.S.), ACE Green Recycling, Inc. (Singapore), and BatX Energies Pvt. Ltd. (India). |
Report overview
Segments covered: model, battery type, process. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
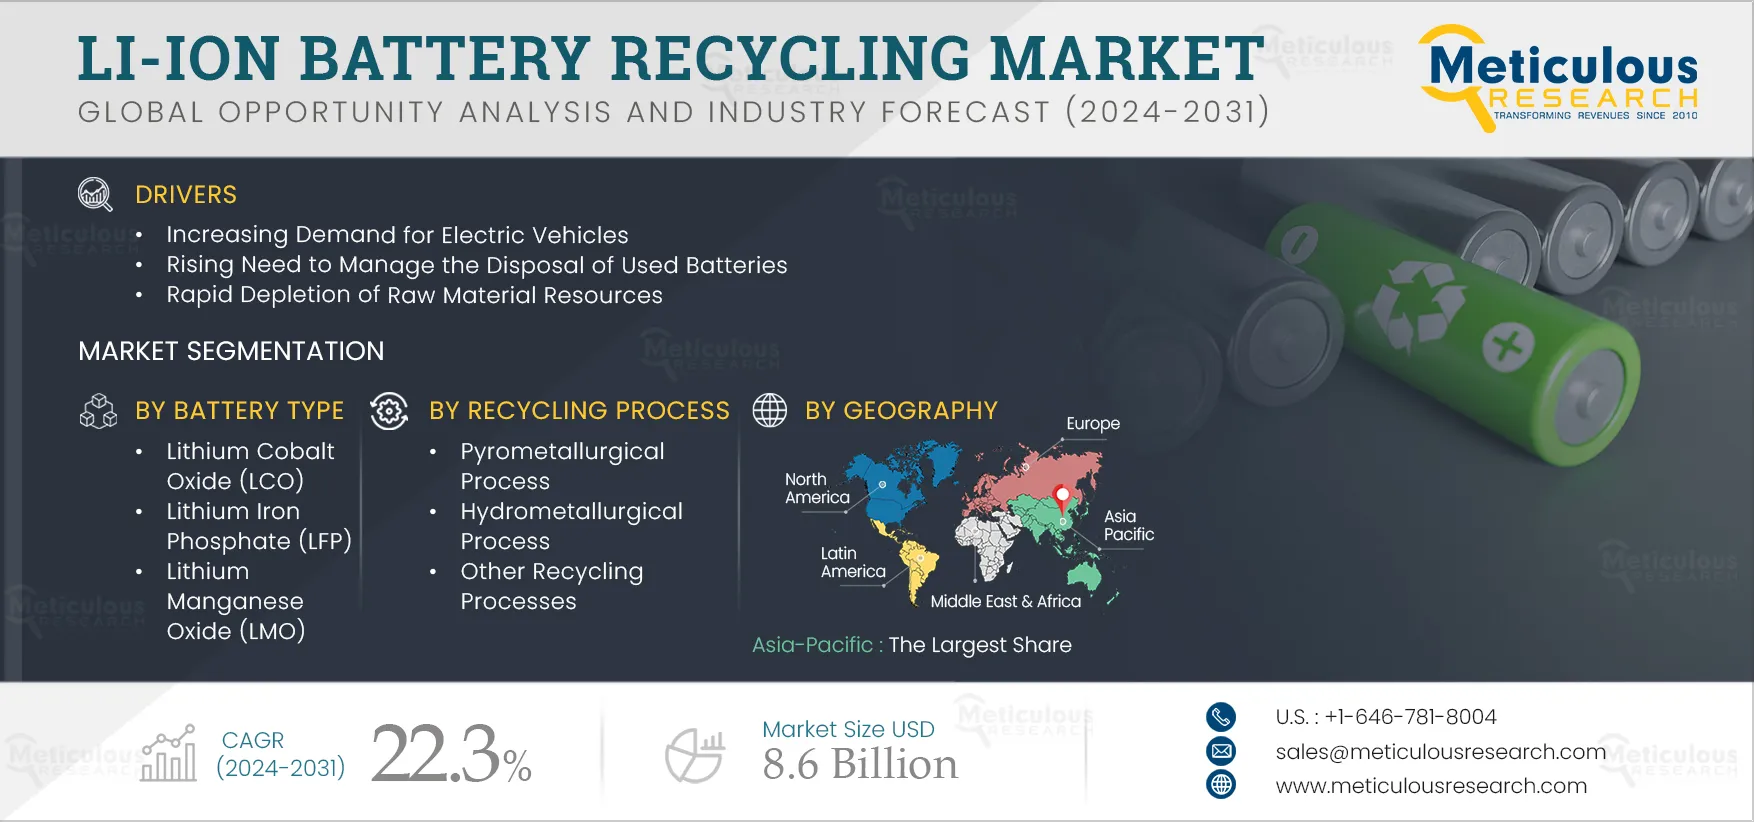
The growth of this market is driven by several factors, including the increasing demand for electric vehicles (EVs), the rising need to manage the disposal of used batteries, the rapid depletion of raw materials, and stringent regulatory frameworks for battery recycling. However, a lack of proper recycling infrastructure restrains market growth.
Additionally, supportive government policies aimed at promoting battery recycling and advancements in recycling technologies are expected to generate growth opportunities for the players operating in this market. On the other hand, the high cost of Li-ion recycling is a major challenge for market growth.
Furthermore, increasing investments in battery recycling infrastructure is a key trend in the Li-ion battery recycling market.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Demand For Electric Vehicles
The expansion of charging infrastructure, government incentives for EV adoption, reduced total ownership costs, and strategic advancements in the EV sector are driving global electric vehicle adoption. According to the World Economic Forum, global electric car sales surged by approximately 60% in 2022, surpassing 10 million units for the first time. The International Energy Agency reports that one in seven passenger cars sold worldwide in 2022 was an EV, a significant increase from 2017, when only one in 70 new cars sold were electric. Additionally, under the Net Zero Emissions (NZE) by 2050 scenario, electric vehicles are projected to make up around 60% of new car sales by 2030, totaling about 300 million units.
Batteries or energy storage systems are critical components for all-electric vehicles, including Hybrid Electric Vehicles (HEVs) and Plug-in Hybrid Electric Vehicles (PHEVs). As the adoption of electric vehicles (EVs) grows, the demand for battery manufacturing and supply becomes increasingly important. Given that EV batteries have a finite lifespan and will eventually require replacement, there will be a substantial number of used batteries that must be managed and disposed of responsibly.
Electric vehicle batteries contain valuable materials such as lithium, cobalt, nickel, and manganese, which are finite resources. Recycling these materials is essential for conserving resources and minimizing the environmental and financial costs associated with mining and extracting new materials. As demand for EVs escalates, companies will require a substantial supply of batteries, particularly lithium-ion batteries, to support the industry's growth and sustainability goals. In response, several companies are implementing strategies to secure raw materials, achieve net-zero emissions targets, and reduce waste from used EV batteries. Consequently, as EV adoption rises, battery recycling will play an increasingly critical role in mitigating the environmental impact of EVs and ensuring the industry's long-term viability.
Stringent Regulatory Frameworks for Battery Recycling
Governments worldwide are establishing comprehensive battery recycling and secondary use policies to foster sustainable supply chains for battery manufacturers and prevent batteries from ending up in landfills at the end of their lifecycle. As a result, these regulatory frameworks are anticipated to significantly boost the growth of lithium-ion battery recycling during the forecast period.
Some of the important regulations governing li-ion battery recycling are as follows:
- In July 2023, the European Union enacted a new regulation on EV battery recycling, replacing the 2006 battery legislation. This updated regulation significantly enhances legal requirements to foster new circular partnerships among battery manufacturers, the industry, and recyclers. It establishes guidelines covering the manufacture, design, traceability, collection, reuse, and recycling of batteries throughout their entire lifecycle.
- In August 2022, India introduced a regulation that mandates producers, including importers, to take responsibility for the collection and recycling or refurbishment of waste batteries, as well as the use of recovered materials in new batteries. This regulation requires that all waste batteries be collected and sent for recycling or refurbishment, explicitly prohibiting disposal through landfills or incineration. Producers can either manage these obligations directly or delegate them to authorized entities for the collection, recycling, or refurbishment of waste batteries. The regulation applies to all types of batteries, including those used in electric vehicles, portable devices, automobiles, and industrial applications.
These regulatory frameworks underscore the increasing demand for lithium-ion battery recycling facilities by ensuring systematic and responsible management of waste batteries, advancing the recycling industry, and reducing environmental impacts amid the rising adoption of electric vehicles. By implementing stringent regulations, governments aim to promote a more environmentally friendly and sustainable lifecycle for batteries. These factors are driving the growth of the battery recycling sector and supporting market growth.
Rapid Depletion of Raw Material Resources
In today’s world, driven by the rising demand for battery-powered devices and electric vehicles EVs, conserving essential natural resources has become crucial. The expansion of the EV sector may increase the demand for rare elements, but since supply is concentrated in a few countries, this can lead to supply chain challenges. However, battery recycling emerges as a critical solution. Recycling not only mitigates environmental impacts but also reduces the overall cost of batteries—and, by extension, EVs. The production of EV batteries relies heavily on rare and valuable materials such as cobalt, nickel, and lithium, which are finite, costly to mine, and have considerable environmental footprints.
Raw materials are pivotal in the cost structure of technologies essential for energy transitions. For Li-ion batteries, advancements in technology and economies of scale have reduced overall costs by approximately 90% over the past decade. However, this reduction has shifted the cost burden to raw materials, which now account for about 50-70% of total battery costs, up from 40-50% five years ago. Consequently, fluctuations in the prices of raw materials, such as lithium and nickel, significantly affect overall battery costs. For instance, a doubling of lithium or nickel prices could lead to a roughly 6% increase in battery costs. If both materials were to double in price simultaneously, it could offset all anticipated cost reductions from increased production capacity. Therefore, the growing demand for Li-ion battery recycling is crucial. Recycling helps mitigate the impact of volatile raw material prices by recovering valuable materials from used batteries and reducing reliance on newly mined resources.
Table of contents
12 chapters · 162 sections · 330 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Business Model | Contractual Services | — |
| By Battery Type | Lithium Nickel Manganese Cobalt Oxide (NMC) | Lithium iron phosphate (LFP) |
| By Process | Pyrometallurgical Process | Hydrometallurgical process |
By Business Model
- The contractual services segment is expected to account for the larger share of over 74.0% of the Li-ion battery recycling market.
- The large share of this segment is primarily attributed to increasing government incentives and regulatory compliance for battery recycling, the rising need to manage the disposal of used batteries, and the development of more efficient and effective recycling technologies through contractual services.
- Additionally companies' focus on managing the liabilities associated with the handling, processing, and disposal of hazardous waste and the rising need to improve the sustainability of battery manufacturing support the segment's large share.
- Moreover, this segment is projected to register a higher CAGR during the forecast period.
By Battery Type
- The lithium nickel manganese cobalt oxide (NMC) segment is expected to account for the largest share of over 44.0% of the Li-ion battery recycling market.
- The substantial market share of this segment is due to the advantages provided by Nickel Manganese Cobalt (NMC) batteries, such as superior thermal stability and safety compared to other lithium-ion batteries, high energy density, and long cycle life.
- The increasing adoption of NMC batteries in applications requiring extended battery life—such as EVs and portable electronic devices—further drives demand.
- Additionally, the global expansion of the EV market contributes to the growing prominence of NMC batteries.
- However, the lithium iron phosphate (LFP) segment is expected to record the highest CAGR during the forecast period.
- Factors supporting the rapid growth of this segment include the increasing adoption of LFP batteries in EVs, rising awareness of resource scarcity, and stringent government regulations on battery disposal and recycling to minimize environmental impact and promote sustainability.
By Process
- Based recycling process, the Li-ion battery recycling market is segmented into pyrometallurgical process, hydrometallurgical process, and other recycling processes.
- The pyrometallurgical process segment is expected to account for the largest share of 45.0% of the Li-ion battery recycling market.
- This segment's large share is attributed to the high recycling rate, the growing need to remove organic materials from Li-ion batteries, the demand for efficient and cost-effective recycling methods, the need to recover valuable materials from used Li-ion batteries to minimize new mining, stringent environmental regulations, and increasing demand for scalable, flexible, and low-cost recycling processes.
- However, the hydrometallurgical process segment is anticipated to register the highest CAGR during the forecast period.
- This segment's growth is driven by several factors.
- These include the increasing need to recover a variety of materials such as copper, lithium, silver, nickel, and zinc, the growing use of selective separation techniques involving chemicals, the rising demand to address shortages of critical raw materials, and the need for recycling processes that consume less energy, produce less waste, and have a lower environmental impact.
Geographic analysis
Asia-Pacific
Largest shareIn 2024, Asia-Pacific is expected to account for the largest share of 45.7% of the Li-ion battery recycling market, followed by North America, Europe, Latin America, and the Middle East & Africa. The region is anticipated slated to register the highest CAGR of 22.0% during the forecast period. Asia-Pacific's substantial market share is driven by several key factors. These include the expanding consumer electronics industry, growing concerns about the depletion of precious and rare earth metals, the introduction of new policies and regulations to improve lithium-ion battery recycling and reduce environmental pollution, and increased awareness and commitment to environmental sustainability. Furthermore, factors such as the rising demand for lithium-ion batteries for electric vehicle (EV) production, the growing adoption of electric mobility, and the increasing volume of battery waste generated are also contributing to the growth of the Li-ion battery recycling market in Asia-Pacific.
Competitive landscape
- October 2023
Stellantis N.V. (Netherlands) signed a memorandum of understanding with Orano SA (France) to form a joint venture focused on recycling end-of-life electric vehicle (EV) batteries and scrap from gigafactories in Europe and North America. The joint venture is set to produce materials commonly known as "black mass" or "active mass."
- April 2023
Fortum (Finland) launched Europe's largest closed-loop hydrometallurgical battery recycling facility in Finland.
- January 2023
The UAE government unveiled plans to establish its first electric vehicle battery recycling plant. This initiative aims to promote green mobility, support the country's goal of achieving net-zero emissions by 2050, and advance the development of a circular economy.
- January 2023
The U.S. government, through the Department of Energy, allocated USD 74 million to support electric vehicle (EV) battery recycling and reuse initiatives. Additionally, in August 2022, the U.S. Department of Energy (DOE) launched a USD 335 million program to advance battery recycling efforts.
- December 2022
Ni Hsin Group Berhad of Malaysia partnered with SIRIM Berhad, an industrial research and technology organization, to establish a lithium-ion battery recycling facility in Malaysia. The SIRIM-Ni Hsin Lithium-Ion Battery Recycling Pilot Plant is set to commence operations in 2023, with an annual recycling capacity of 550 tons of lithium-ion batteries.
- Duesenfeld GmbH · Germany
- RecycLiCo Battery Materials Inc. · Canada
- Li-Cycle Holdings Corp. · Canada
- Cirba Solutions (U.S.)
- Accurec-Recycling GmbH · Germany
- Redux Recycling GmbH (U.S.)
- Redwood Materials, Inc. (U.S.)
- Glencore plc · Switzerland
- Fortum Corporation · Finland
- Trishulavel Eshan Pvt Ltd (Li-Circle) · India
- SNAM S.A.S (A subsidiary of Floridienne S.A) · France
- Primobius GmbH · Germany
- MTB GROUP · France
- Tata Chemicals Limited · India
- OnTo Technology (U.S.)
- American Battery Technology Company (U.S.)
- Attero Recycling Pvt. Lyd · India
- Umicore SA · Belgium
- Lithion Recycling Inc. · Canada
- Ascend Elements, Inc. (U.S.)
- ACE Green Recycling, Inc. · Singapore
- Aand BatX Energies Pvt. Ltd. · India
Frequently asked questions
The Lithium-ion Battery Recycling Market encompasses the processes and technologies used to reclaim valuable materials from used lithium-ion batteries, which are commonly found in electric vehicles (EVs), consumer electronics, and energy storage systems.
Cite this report
Meticulous Research. (2024). Li-ion Battery Recycling Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MROTH - 104797). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/li-ion-battery-recycling-market-5481