In-vitro Diagnostics Market (2025-2032)
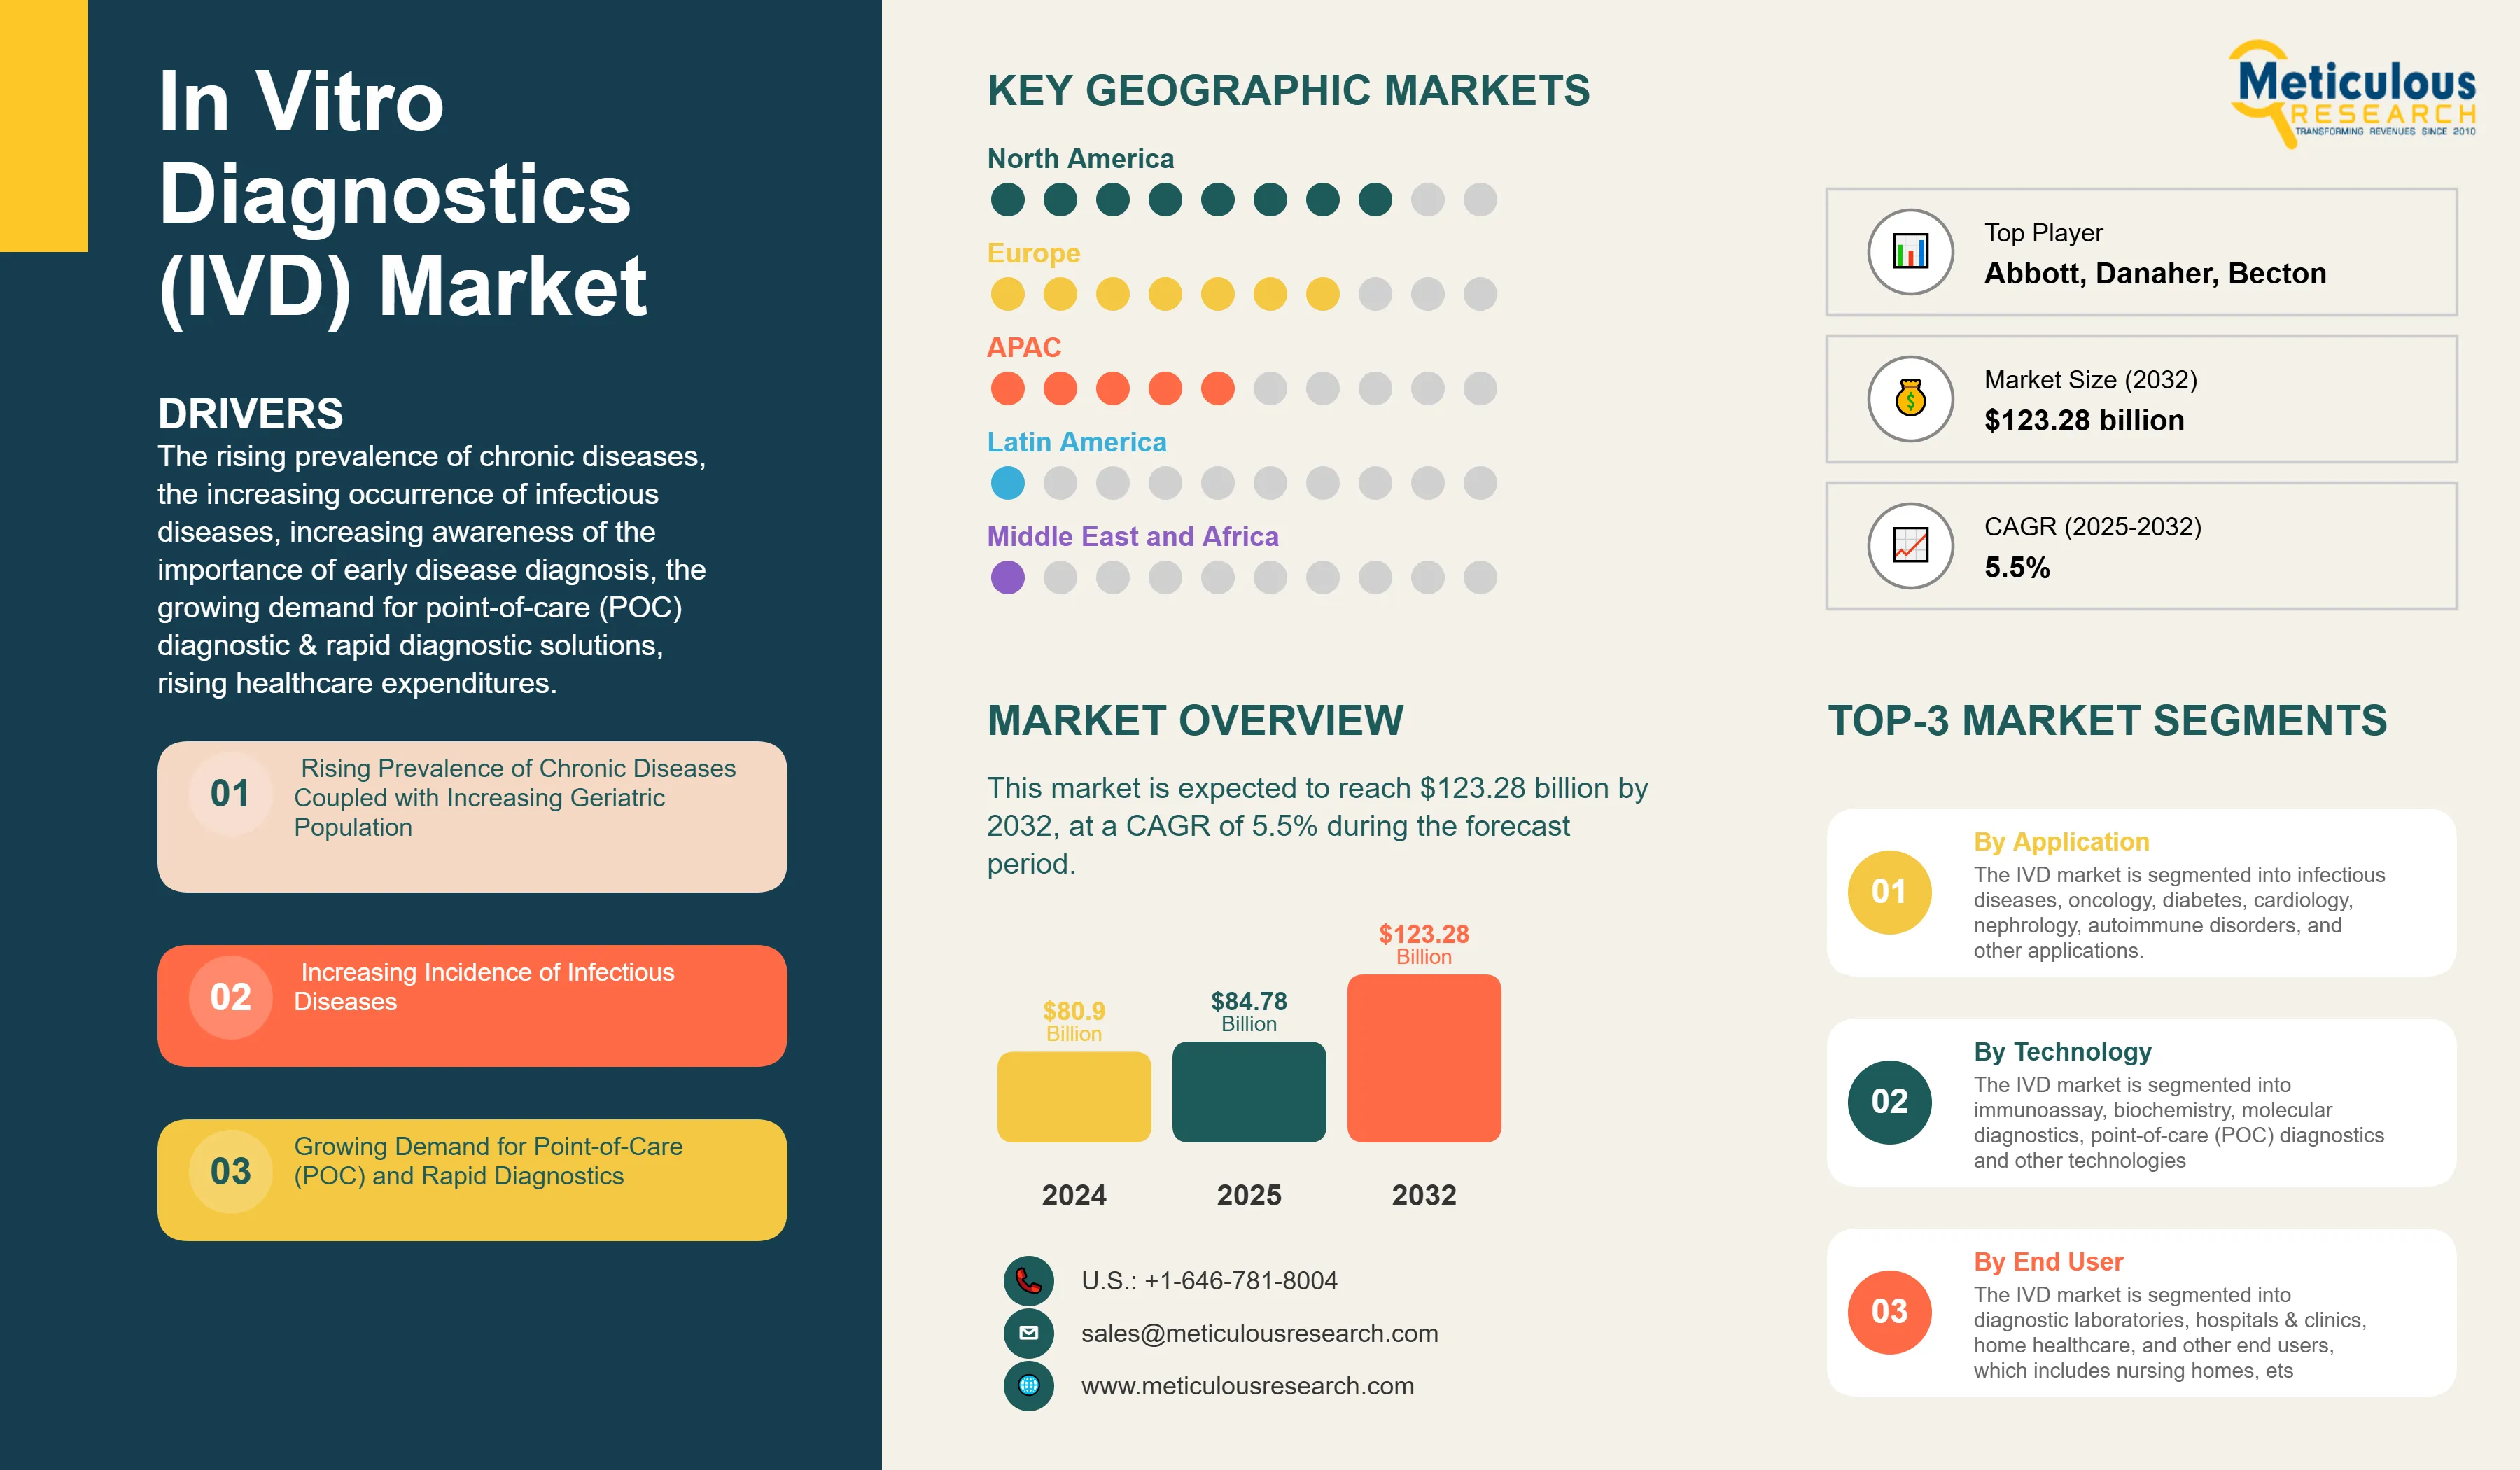
The In Vitro Diagnostics (IVD) Market was valued at $80.9 billion in 2024. This market is expected to reach $123.28 billion by 2032 from an estimated $84.78 billion in 2025, at a CAGR of 5.5% during the forecast period from 2025 to 2032. IVD Market Size & Forecast The growth of the In Vitro Diagnostics
- Published
- Jun 2025
- Pages
- 520
- Format
- PDF + Excel
- Report ID
- MRHC - 104132
- Base year
- 2024
- 2024 · BASELINE
- $80.90B
- 2032
- $123.3B
- CAGR 2025–2032
- 5.5%
2024 baseline · 2025–2032 forecast at 5.5% CAGR · hover a bar for the value
Key highlights
The Reagents & Kits Segment to Account for the Largest Share of this Market in 2024
The Molecular Diagnostics Segment to Account for the Largest Share of this Market in 2024
The Infectious Diseases Segment to Account for the Largest Share of this Market in 2024
The Lab Testing Segment to Account for the Largest Share of this Market in 2024
The Hospitals & Clinics Segment to Account for the Largest Share of this Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Page No | 520 |
| Format | |
| Forecast Period | 2025-2032 |
| Base Year | 2024 |
| CAGR | 5.5% |
| Market Size (Value) | $123.28 billion by 2032 |
| Segments Covered | By Offering · Reagents & Kits · Instruments · Software & Services · By Technology · Molecular Diagnostics · Polymerase Chain Reaction (PCR) · Hybridization · Isothermal Nucleic Acid Amplification Technology · DNA Sequencing & Next-Generation Sequencing · Microarrays · Mass Spectrometry · Other Molecular Diagnostic Technologies · (Note:-Other Molecular Diagnostic Technologies majorly include electrophoresis, Ligase Chain Reaction (LCR), Northern Blot, and Southern Blot) · Point of Care (POC) Diagnostics · Lateral Flow Assays/Rapid Tests · POC Molecular Diagnostics · Other PoC Products · Immunoassay/Immunochemistry · Enzyme-linked Immunosorbent Assays (ELISA) · Enzyme-linked Immunospot Assays (ELISPOT) · Western Blotting · Radioimmunoassay · Biochemistry/Clinical Chemistry · Metabolic Panel · Electrolyte Panel · Liver Panel · Lipid Profile · Renal Profile · Thyroid Function Panel · Whole Blood Glucose Monitoring · Microbiology · Hematology · Coagulation/Hemostasis · Urinalysis · Other IVD Technologies · (Note:Other IVD technologies comprise anatomical pathology, histochemistry, and loop-mediated amplification). · By Application · Infectious Diseases · Sexually Transmitted Diseases (STD) Testing · Healthcare-associated Infections (HAIs) · Hepatitis · HIV · Tropical Diseases · Respiratory Infections (Excluding Influenza) · Influenza · Other Infectious Diseases · Oncology · Diabetes · Cardiology · Nephrology · Autoimmune Disorders · Other Applications · (Note 1:Other applications comprise drugs of abuse tests, coagulation tests, neonatal testing, genetic testing, and neurological disorders testing. · Note 2:Other infectious diseases include congenital infections, meningitis, norovirus (stomach flu), hand, foot, and mouth disease (HFMD), and pertussis). · By Diagnostic Approach · Laboratory Testing · OTC/Self-testing · Point-of-Care Testing · By End User · Diagnostic Laboratories · Hospitals & Clinics · Home Healthcare · Other End Users · (Note: Other end users comprise nursing homes, academic & research institutes, ambulatory care centers, and transfusion laboratories.) |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Spain, Italy, Switzerland, Rest of Europe), Asia-Pacific (China, Japan, India, Australia, South Korea, Rest of Asia-Pacific), Latin America (Brazil, Mexico, Argentina, Rest of Latin America), the Middle East (Saudi Arabia & Rest of Middle East), and Africa (South Africa and Rest of Africa) |
| Key Companies | Abbott Laboratories (U.S.), Becton, Dickinson and Company (U.S.), bioMérieux SA (France), Bio-Rad Laboratories, Inc. (U.S.), Danaher Corporation (U.S.), F. Hoffmann-La Roche Ltd. (Switzerland), Illumina, Inc. (U.S.), QIAGEN N.V. (Netherlands), Shenzhen Mindray Bio-Medical Electronics Co., Ltd (China), Siemens Healthineers AG (Germany), Thermo Fisher Scientific Inc. (U.S.), Wama Diagnostica (Brazil), Wiener Laboratorios SAIC (Argentina), Ortho-Clinical Diagnostics, Inc. (U.S.), Agilent Technologies Inc. (U.S.), DiaSorin S.p.A. (Italy), Hologic, Inc. (U.S.), Abcam Plc (U.K.), Raybiotech, Inc. (U.S.), Oy Medix Biochemica Ab (Finalnd), InBios International, Inc. (U.S.), Dextra Laboratories Ltd. (U.K.), Genecopoeia, Inc. (U.S.), Sakura Finetek USA, Inc. (U.S.), and Edvotek, Inc. (U.S.) |
Report overview
Segments covered: offering. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the In Vitro Diagnostics (IVD) market is driven by the rising prevalence of chronic diseases, the increasing occurrence of infectious diseases, increasing awareness of the importance of early disease diagnosis, the growing demand for point-of-care (POC) diagnostic & rapid diagnostic solutions, rising healthcare expenditures, and increasing investments in research and development. However, stringent technical requirements and regulatory processes for high/moderate-complexity tests, and variance in test results observed in rapid IVD tests restrain the growth of the market. Moreover, emerging economies, an inclination toward personalized medicine, and advancements in genomics & proteomics are expected to offer significant growth opportunities for market stakeholders. The evolving regulatory landscape poses a challenge to the growth of the market.
Report infographic
Market dynamics
5 factors across 3 forcesRising Prevalence of Chronic Diseases and Increasing Geriatric Population
The global incidence of chronic diseases and conditions, including cancer, diabetes, arthritis, and cardiovascular diseases, is escalating. The World Health Organization reports that chronic diseases are responsible for 41 million deaths annually, representing approximately 74% of global mortality. Contributing factors to this upward trend include an aging population and social behaviors such as tobacco and alcohol consumption, physical inactivity, and poor dietary habits. The International Diabetes Federation projects that the global prevalence of diabetes will increase to 11.3% of the population by 2030, up from 10.5% in 2021.
The majority of older adults are diagnosed with chronic diseases due to declining bodily functions and weakened immunity. According to the World Population Prospects, the population aged 65 and older is expanding at a faster rate than other age groups. In 2019, there were 703 million individuals in this age group globally, with projections indicating this number will double to 1.5 billion by 2050. Consequently, the increasing prevalence of chronic diseases, combined with the growing geriatric population, is expected to drive an increase in diagnostic testing and subsequently boost growth in the IVD market.
Rising Awareness Regarding Early Disease Diagnosis
Early diagnosis of infectious diseases facilitates improved treatment and future care. It enables healthcare professionals and patients to make crucial medical decisions regarding care and support. Growing awareness of the benefits of early disease diagnosis underscores its importance. Detecting a disease in its early stages can lead to substantial cost savings in treatment. For example, the World Health Organization reports that, in certain high-income countries, early diagnosis of cancer can reduce treatment costs by two to four times. In addition, early diagnosis is often lifesaving for patients with critical conditions such as cancer.
Furthermore, key players and organizations in the IVD market are actively pursuing initiatives to enhance early diagnosis and reduce mortality rates associated with infectious diseases. For example, in June 2022, Illumina, Inc. (U.S.) and Ochsner Health System (U.S.) introduced new initiatives by providing multi-cancer early detection tests to patients at risk of cancer. Consequently, the increasing awareness of early disease diagnosis, combined with supportive initiatives, is anticipated to drive growth in the market.
Table of contents
13 chapters · 196 sections · 520 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Reagents & Kits | Kits and reagents |
| By Technology | Molecular Diagnostics | Molecular diagnostics |
| By Application | Infectious Diseases | Cardiology |
| By Diagnostic Approach | Lab Testing | Point-of-care testing |
| By End User | Hospitals & Clinics | Hospitals & clinics |
By Offering
- The Reagents & Kits Segment to Account for the Largest Share of this Market in 2024
- The kits & reagents segment is expected to account for the largest share of 81.1% of the IVD market.
- The substantial market share of this segment is due to the frequent use of reagents and kits for detecting a variety of chronic diseases, as well as the wide availability of a diverse range of reagents and consumables for diagnosing different conditions.
- Furthermore, the kits and reagents segment is slated to register the highest CAGR of 5.0% during the forecast period.
- The increased volume of testing for infectious diseases and the rising awareness among the general population about self-testing kits drive this segment's growth.
By Technology
- The molecular diagnostics segment is expected to account for the largest share of 23.1% of the IVD market.
- The large market share is due to the growing prevalence of infectious diseases and the superior sensitivity of molecular diagnostics for detecting infectious agents.
- Moreover, the molecular diagnostics segment is expected to record the highest CAGR during the forecast period.
- The high sensitivity of various technologies, low sample volume requirements, and cost-effectiveness drive this segment's growth.
By Application
- The infectious diseases segment is expected to account for the largest share of 37.8% of IVD market.
- The large market share of this segment is attributed to the increasing prevalence of infectious diseases, government initiatives to promote awareness and testing, and global outbreaks of infectious diseases.
- However, the cardiology segment is anticipated to record the highest CAGR during the forecast period.
- This segment's growth is driven by the increasing incidence of cancer and the rising number of diagnostic laboratories.
By Diagnostic Approach
- The Lab Testing Segment to Account for the Largest Share of this Market in 2024
- The laboratory testing segment is expected to account for the largest share of the IVD market.
- This segment’s large market share is attributed to the higher accuracy & reliability of lab testing compared to point-of-care testing, low costs, the availability of a wide range of IVD tests, and the presence of robust quality assurance programs.
- However, the point-of-care testing segment is projected to record the highest CAGR during the forecast period.
- This segment's growth is driven by quick results, the ability to be performed by non-healthcare professionals, shorter hospital stays, easy sample collection, and rapid medical decisions.
By End User
- The hospitals & clinics segment is expected to account for the largest share of the IVD market.
- This segment's substantial market share is due to hospitals and clinics being the primary contact points for patients with health conditions, the expansion of diagnostic capabilities during the COVID-19 pandemic, and the significant global burden of chronic diseases.
- Moreover, the hospitals & clinics segment is projected to record the highest CAGR during the forecast period.
- This segment's growth is driven by the increasing number of tests, government funding, the increasing hospitalization rate, and the increasing demand for diagnostic products.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 37.5% of the IVD market. The key factors contributing to the large share of this regional market include the rising prevalence of chronic and infectious diseases, increased awareness about early disease diagnosis, growing adoption of advanced diagnostic products, and heightened funding activities combined with novel advancements in diagnostic technologies.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is poised to record the highest CAGR during the forecast period. This segment's growth is driven by continuous improvements in healthcare infrastructure, the rising number of hospitals, increasing governments in this sector, rapid urbanization, the growing burden of infectious diseases, and efforts to improve the accessibility of diagnostic services to enhance the prevention of infectious diseases by developing diagnostic products or platforms.
Competitive landscape
- January 2023
Becton, Dickinson, and Company (U.S.) and CerTest Biotec (Spain) received Emergency Use Authorization (EUA) from the US FDA for their molecular polymerase chain reaction (PCR) assay, VIASURE Monkeypox Virus Real-Time PCR Reagent.
- January 2023
Beckman Coulter Inc. (U.S.), a subsidiary of Danaher Corporation (U.S.), partnered with MeMed Diagnostics Ltd (Israel) to commercialize and develop the MeMed BV test. This test, which differentiates between viral and bacterial infections, is intended for use with Immunoassay Analyzers.
- September 2022
Becton, Dickinson and Company (U.S.) launched its cloud-based software solution, BD Research Cloud. This platform is designed to streamline and enhance the workflow of flow cytometry, enabling faster and higher-quality experiments.
- Abbott Laboratories (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Bio-Rad Laboratories, Inc. (U.S.)
- Danaher Corporation (U.S.)
- F. Hoffmann-La Roche Ltd. · Switzerland
- Illumina, Inc. (U.S.)
- QIAGEN N.V. · Netherlands
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd · China
- Siemens Healthineers AG · Germany
- Thermo Fisher Scientific Inc. (U.S.)
- Wama Diagnostica · Brazil
- Wiener Laboratorios SAIC · Argentina
- Ortho-Clinical Diagnostics, Inc. (U.S.)
- Agilent Technologies Inc. (U.S.)
- DiaSorin S.p.A · Italy
- Hologic, Inc. (U.S.)
- Abcam Plc (U.K.)
- Raybiotech, Inc. (U.S.), Oy Medix Biochemica Ab · Finalnd
- InBios International, Inc. (U.S.)
- Dextra Laboratories Ltd. (U.K.)
- Genecopoeia, Inc. (U.S.)
- Sakura Finetek USA, Inc. (U.S.)
- Edvotek, Inc. (U.S.)
Frequently asked questions
This study provides insights into the IVD market segmented based on product & solution (reagents & kits, systems, and software & services) and a wide range of technologies (molecular diagnostics, point of care (POC), immunoassay/immunochemistry, biochemistry/clinical chemistry, whole blood glucose monitoring, microbiology, hematology, coagulation/hemostasis, urinalysis, and other IVD technologies) offered by key companies to various end users, such as diagnostic laboratories, hospitals & clinics, home healthcare, and other end users. This report involves the value analysis of various segments and sub-segments of the IVD market at the regional and country levels.
Cite this report
Meticulous Research. (2025). In-vitro Diagnostics (IVD) Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 104132). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ivd-market-4858