EV Components Market (2026-2036)
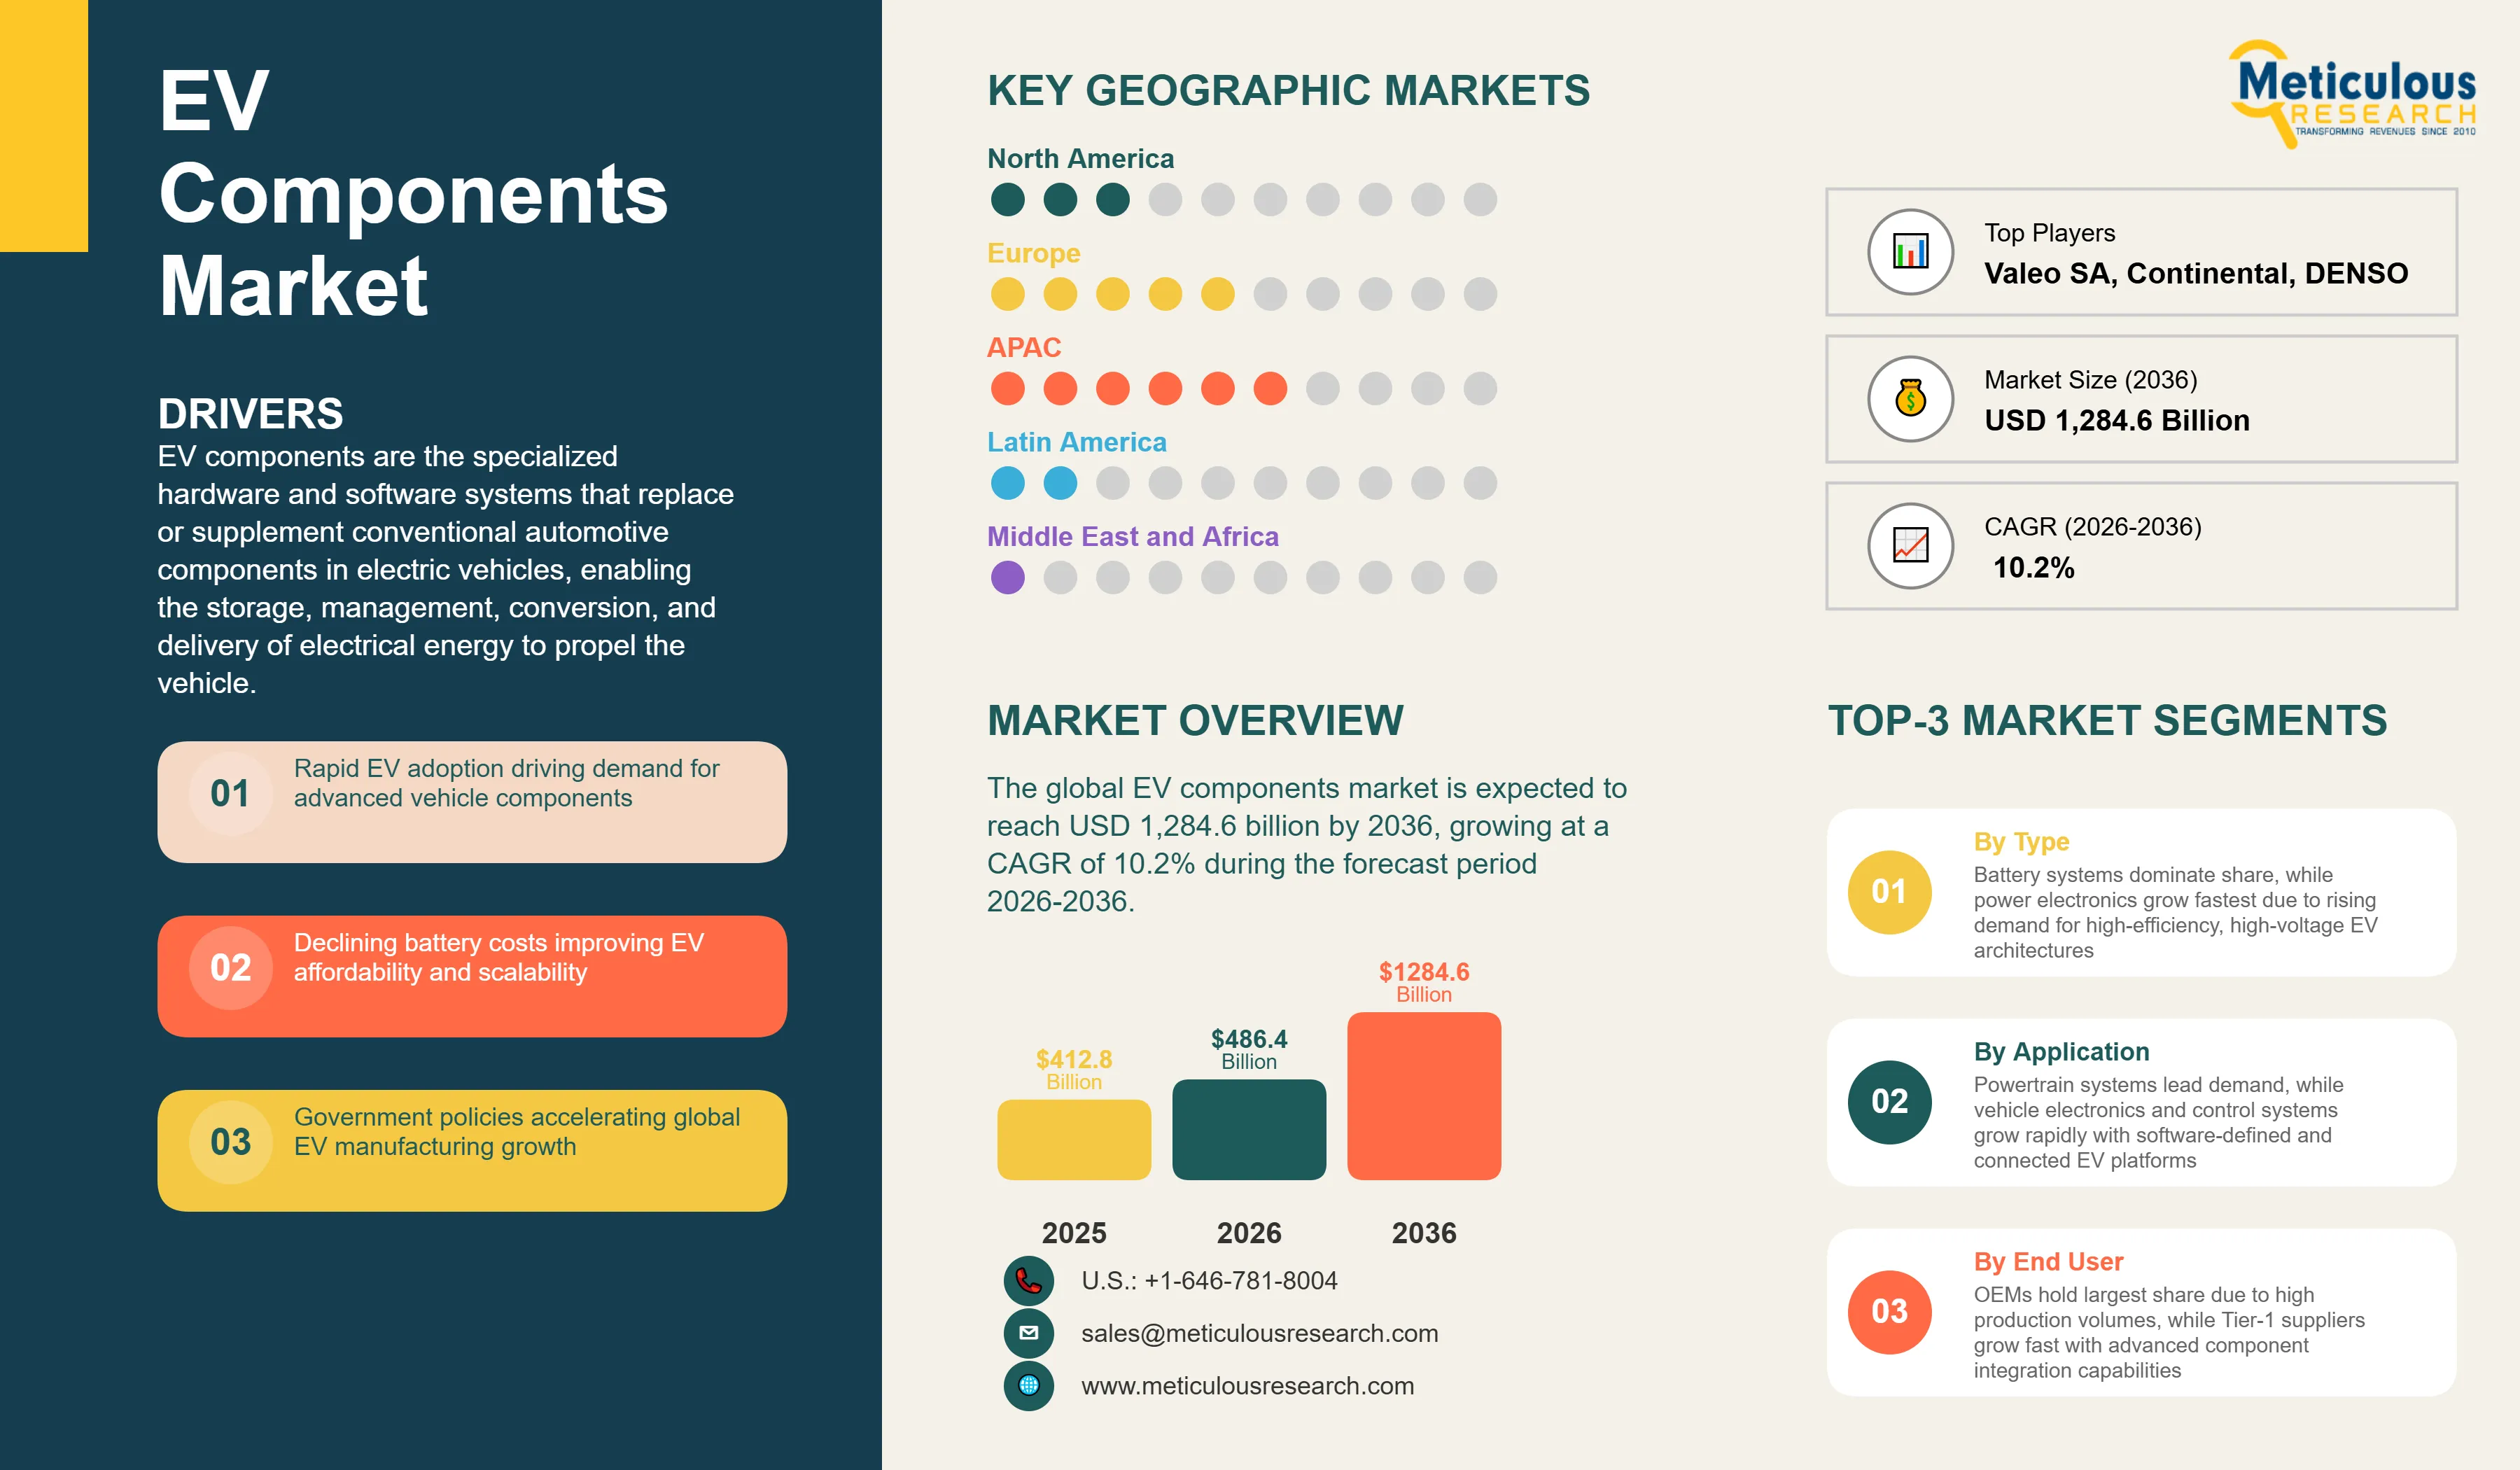
The global EV components market was valued at USD 412.8 billion in 2025. This market is expected to reach USD 1,284.6 billion by 2036 from an estimated USD 486.4 billion in 2026, growing at a CAGR of 10.2% during the forecast period 2026-2036.
- Published
- May 2026
- Pages
- 320
- Format
- PDF + Excel
- Report ID
- MR-1955
- Base year
- 2025
- 2025 · BASELINE
- $412.8B
- 2036
- $1.28T
- CAGR 2026–2036
- 10.2%
2025 baseline · 2026–2036 forecast at 10.2% CAGR · hover a bar for the value
Key highlights
The global EV components market is projected to reach USD 1, 284.6 billion by 2036.
The market is expected to grow at a CAGR of 10.2% during the forecast period 2026-2036.
The global market for EV components was valued at USD 412.8 billion in 2025 and is estimated to reach USD 486.4 billion in 2026.
Asia-Pacific is expected to dominate the global EV components market with the largest market share in 2026, while Europe is projected to register the highest CAGR during the forecast period.
By component type, the battery systems segment is expected to hold the largest share of the market in 2026, while the power electronics segment is projected to register the highest CAGR during the forecast period.
By vehicle type, the passenger vehicles segment is expected to hold the largest share in 2026, while the commercial vehicles segment is projected to register the highest CAGR during the forecast period.
By propulsion type, the battery electric vehicles segment is expected to hold the largest share in 2026, while the plug-in hybrid electric vehicles segment is projected to register the highest CAGR during the forecast period.
By application, the powertrain systems segment is expected to hold the largest share in 2026, while the vehicle electronics and control systems segment is projected to register the highest CAGR during the forecast period.
By end user, the OEMs segment is expected to hold the largest share in 2026, while the Tier-1 suppliers segment is projected to register the highest CAGR during the forecast period.
By material type, the metals (aluminum and copper) segment is expected to hold the largest share in 2026, while the semiconductor materials segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 1,284.6 Billion |
| Market Size in 2026 | USD 486.4 Billion |
| Market Size in 2025 | USD 412.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 10.2% |
| Format | PDF, Excel & Cloud Portal · 320 pages |
| Dominating Component Type | Battery Systems |
| Fastest Growing Component Type | Power Electronics |
| Dominating Vehicle Type | Passenger Vehicles |
| Fastest Growing Vehicle Type | Commercial Vehicles |
| Dominating Propulsion Type | Battery Electric Vehicles (BEVs) |
| Fastest Growing Propulsion Type | Plug-in Hybrid Electric Vehicles (PHEVs) |
| Dominating Application | Powertrain Systems |
| Fastest Growing Application | Vehicle Electronics and Control Systems |
| Dominating End User | OEMs |
| Fastest Growing End User | Tier-1 Suppliers |
| Dominating Material Type | Metals (Aluminum, Copper) |
| Fastest Growing Material Type | Semiconductor Materials |
| Dominating Geography | Asia-Pacific |
| Fastest Growing Geography | Europe |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: component type, vehicle type, propulsion type, application, end user, material type.
According to the IEA's Global EV Outlook 2025, global electric car sales reached approximately 17 million units in 2024, representing approximately 20% of all new cars sold globally, and the IEA projects electric vehicles will account for well over half of new car sales globally before the end of this decade under its Stated Policies Scenario, establishing the long-term trajectory that is driving EV component market growth.
EV components are the specialized hardware and software systems that replace or supplement conventional automotive components in electric vehicles, enabling the storage, management, conversion, and delivery of electrical energy to propel the vehicle. The battery system, which stores energy electrochemically in thousands of lithium-ion cells assembled into modules and packs with integrated battery management electronics, is the largest single component cost in an EV and the central enabling technology of the entire powertrain. The electric drive system converts the stored electrical energy into mechanical torque through a permanent magnet or induction electric motor and a reduction gearbox. Power electronics including the traction inverter, DC-DC converter, and on-board charger convert voltages and manage energy flow between the battery, motor, and electrical systems. Thermal management systems maintain the battery and drive components within their optimal temperature ranges. Vehicle control units and software tie everything together, managing energy use, driver interfaces, safety systems, and increasingly over-the-air feature updates.
The market is growing because global EV sales are growing at a pace that consistently exceeds even optimistic forecasts from a few years prior. According to the IEA's Global EV Outlook 2025, global electric car sales reached approximately 17 million units in 2024, representing approximately 20% of global new car sales. China's dominance is notable: the China Passenger Car Association reported over 12 million new energy vehicle sales in China in 2024, representing over 40% of China's total new passenger vehicle sales that year, making China's domestic EV market alone approximately equal to the entire global EV market of just three years earlier. According to BNEF and the IEA’s latest EV outlooks, global electric car sales were about 17 million in 2024 and are expected to keep rising strongly through 2030, with EVs reaching roughly 40% or more of new car sales globally under current policy settings.
Two specific technology trends are shaping the component landscape. The transition from 400-volt to 800-volt electrical architecture across premium and mass-market EV platforms is changing the specifications of every electrical component in the vehicle, requiring inverters, converters, motors, and charging systems designed for higher voltage operation that can support ultra-fast charging and improve drivetrain efficiency. According to Infineon Technologies' 2025 Automotive Market Outlook, wide-bandgap semiconductors particularly silicon carbide power devices are becoming the standard choice for 800-volt EV inverters and chargers, with the silicon carbide content per vehicle growing rapidly as 800-volt architecture adoption scales up. Separately, the progressive integration of vehicle software platforms and over-the-air update capabilities across all EV brands is expanding the vehicle control unit and software component category from a relatively minor item to a significant value driver within the overall EV component mix.
Market dynamics
7 factors across 3 forcesRapid Adoption of Electric Vehicles Globally
According to the IEA's Global EV Outlook 2025, global electric car sales reached approximately 17-18 million units in 2024, representing approximately 20% of all new cars sold globally and marking the first time that electric vehicles exceeded one in five new car sales worldwide. The China Passenger Car Association's 2025 data shows over 12 million NEV sales in China in 2024, representing more than 40% of domestic new passenger vehicle sales. According to BloombergNEF's Electric Vehicle Outlook 2025, EV penetration is expected to reach 46% of global new car sales by 2030 under its main scenario, implying continued rapid demand growth for every EV component category throughout the forecast period. Global commercial vehicle electrification is also accelerating, with electric bus deployments growing across China, Europe, and increasingly other markets, and electric trucks entering commercial service with Daimler Truck, Volvo Trucks, and Tesla Semi generating growing commercial vehicle EV component demand alongside the dominant passenger vehicle market.
Declining Battery Costs
According to BloombergNEF's Battery Price Survey 2025, average lithium-ion battery pack prices fell to approximately USD 108 per kWh in 2025. BloombergNEF projects further falls toward approximately USD 105 per kWh by 2026, approaching the price parity threshold with ICE vehicles. CATL's announcement in 2025 of its Shenxing Plus battery at above 370 Wh/kg energy density and 4C charging capability demonstrates that cost reduction and performance improvement are advancing simultaneously. The IEA's Critical Minerals Market Review 2025 noted that lithium prices in 2024 fell significantly from their 2022 peak, easing one of the primary raw material cost pressures on battery manufacturers and contributing to the continued pack cost reduction trajectory.
Table of contents
14 chapters · 175 sections · 320 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component Type | Battery Systems | Power electronics |
| By Vehicle Type | Passenger Vehicles | Commercial vehicles |
By Component Type
- Battery Systems to Dominate
- The global market for EV components is segmented into battery systems (cells, modules, packs, and BMS), electric drive systems (motors and gearboxes), power electronics (inverters, converters, and on-board chargers), thermal management systems, charging components, vehicle control units and software, and other components.
- The battery systems segment is expected to account for the largest share of the global EV components market.
- The battery pack typically represents 30 to 40% of total EV vehicle cost according to BloombergNEF's 2025 analysis, making it the single largest component cost in any EV.
- With approximately 17-18 million EV sales in 2024 and growing rapidly, the scale of battery system procurement is the dominant revenue category in the EV component market by a very large margin.
- CATL's 2025 annual revenue exceeding RMB 423 billion, a substantial portion from EV battery sales, illustrates the commercial scale of the battery systems segment.
- However, the power electronics segment is projected to register the highest CAGR during the forecast period.
- The transition to 800-volt vehicle architectures, the adoption of silicon carbide inverters, the growing complexity of multi-motor EV drivetrains, and the increasing sophistication of on-board charging systems are all driving above-average growth in power electronics content per vehicle.
By Vehicle Type
- Passenger Vehicles to Hold the Largest Share
- The passenger vehicles segment is expected to account for the largest share of the global EV components market.
- Passenger EVs represent the overwhelming majority of global EV sales by unit count and by total component procurement value.
- However, the commercial vehicles segment is projected to register the highest CAGR during the forecast period.
- Electric buses and trucks are at an earlier stage of electrification than passenger cars but are transitioning rapidly, particularly in China where electric bus fleets are already very large, and in Europe and North America where zero-emission truck regulations in California and the EU's CO2 standards for heavy-duty vehicles are compelling commercial vehicle manufacturers to accelerate electrification.
- Each commercial EV contains significantly more battery and drivetrain component value than a passenger EV due to its larger battery pack, higher-powered motor, and more robust charging system, making commercial vehicle electrification a high-value growth segment for EV component suppliers.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account by far the largest share of the global EV components market. China's dominance of the global EV industry is reflected in its dominance of the EV components market: the China Passenger Car Association reported over 12 million NEV sales in China in 2024, representing over 40% of domestic new vehicle sales and well over half of global EV sales. China hosts the world's largest battery manufacturers including CATL and BYD, the world's most active EV manufacturing base producing vehicles for domestic consumption and export, and a large domestic supply chain for EV components from battery cells to power electronics and motors. CATL's 2025 revenues exceeding RMB 423 billion confirm the commercial scale of the Chinese battery manufacturing industry. South Korea's LG Energy Solution, Samsung SDI, and SK On are the world's third, fourth, and fifth-largest EV battery manufacturers per SNE Research's 2025 data, with manufacturing facilities in South Korea and internationally, and Korea's significant automotive electronics and semiconductor industries add to Asia-Pacific's component procurement weight. Japan hosts Toyota, Honda, and major component suppliers including Denso, Aisin, and Panasonic that are all scaling up EV component development and production. India is beginning to transition its automotive production toward EVs, with domestic EV two-wheeler sales already very large and passenger EV sales growing rapidly. However, the European market for EV components is expected to grow at the fastest CAGR during the forecast period.
Europe
Europe's component market growth is driven by two powerful forces: the very large and accelerating EV production ramp-up by European automakers, and the EU's regulatory framework that creates binding demand through its 2035 effective ban on new ICE vehicle sales. According to the European Automobile Manufacturers Association's 2025 data, BEV market share in Europe reached approximately 14% of new car registrations in 2024 and is expected to continue growing as the 2035 deadline approaches. The European automotive supply chain including Bosch, Continental, ZF, Valeo, and their extensive Tier-1 and Tier-2 supplier networks is investing heavily in EV component manufacturing capacity, with Bosch's 2025 results showing its e-Mobility division growing significantly above the company's overall average. Northvolt's battery manufacturing in Sweden, and the CATL, BYD, and Samsung SDI European cell manufacturing facilities under various stages of development, are building out the European battery component supply chain. The EU Battery Regulation's domestic manufacturing incentives and battery passport requirements are creating additional policy-driven investment in European EV component production capacity.
North America
North America is a rapidly growing EV components market, driven by the U.S. Inflation Reduction Act's domestic content requirements that effectively mandate U.S.-based EV component manufacturing to qualify for the consumer EV tax credit. According to the Alliance for Automotive Innovation's 2025 data, U.S. EV sales reached approximately 1.3 million units in 2024, representing approximately 8% of new car sales and growing. The IRA's Section 45X manufacturing tax credits are supporting the construction of U.S. battery cell and component manufacturing facilities by Panasonic in Kansas, LG Energy Solution in Michigan and Arizona, Samsung SDI in Indiana, and SK On in Georgia, each representing multi-billion dollar investments that will generate significant U.S. domestic EV component procurement as they reach full production through the forecast period.
Competitive landscape
- Robert Bosch GmbH · Germany
- DENSO Corporation · Japan
- Continental AG · Germany
- BYD Company Ltd. · China
- Contemporary Amperex Technology Co. Limited/CATL · China
- LG Energy Solution Ltd. · South Korea
- Panasonic Holdings Corporation · Japan
- Samsung SDI Co. Ltd. · South Korea
- Valeo SA · France
- ZF Friedrichshafen AG · Germany
- Magna International Inc. · Canada
- Hyundai Mobis Co. Ltd. · South Korea
- Aisin Corporation · Japan
- Infineon Technologies AG · Germany
- NXP Semiconductors N.V. · Netherlands
Frequently asked questions
The global EV components market is expected to reach USD 1,284.6 billion by 2036 from an estimated USD 486.4 billion in 2026, at a CAGR of 10.2% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). EV Components Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1955). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ev-components-market-6638