Electronic Clinical Outcome Assessment (eCOA) Solutions Market (2026-2036)
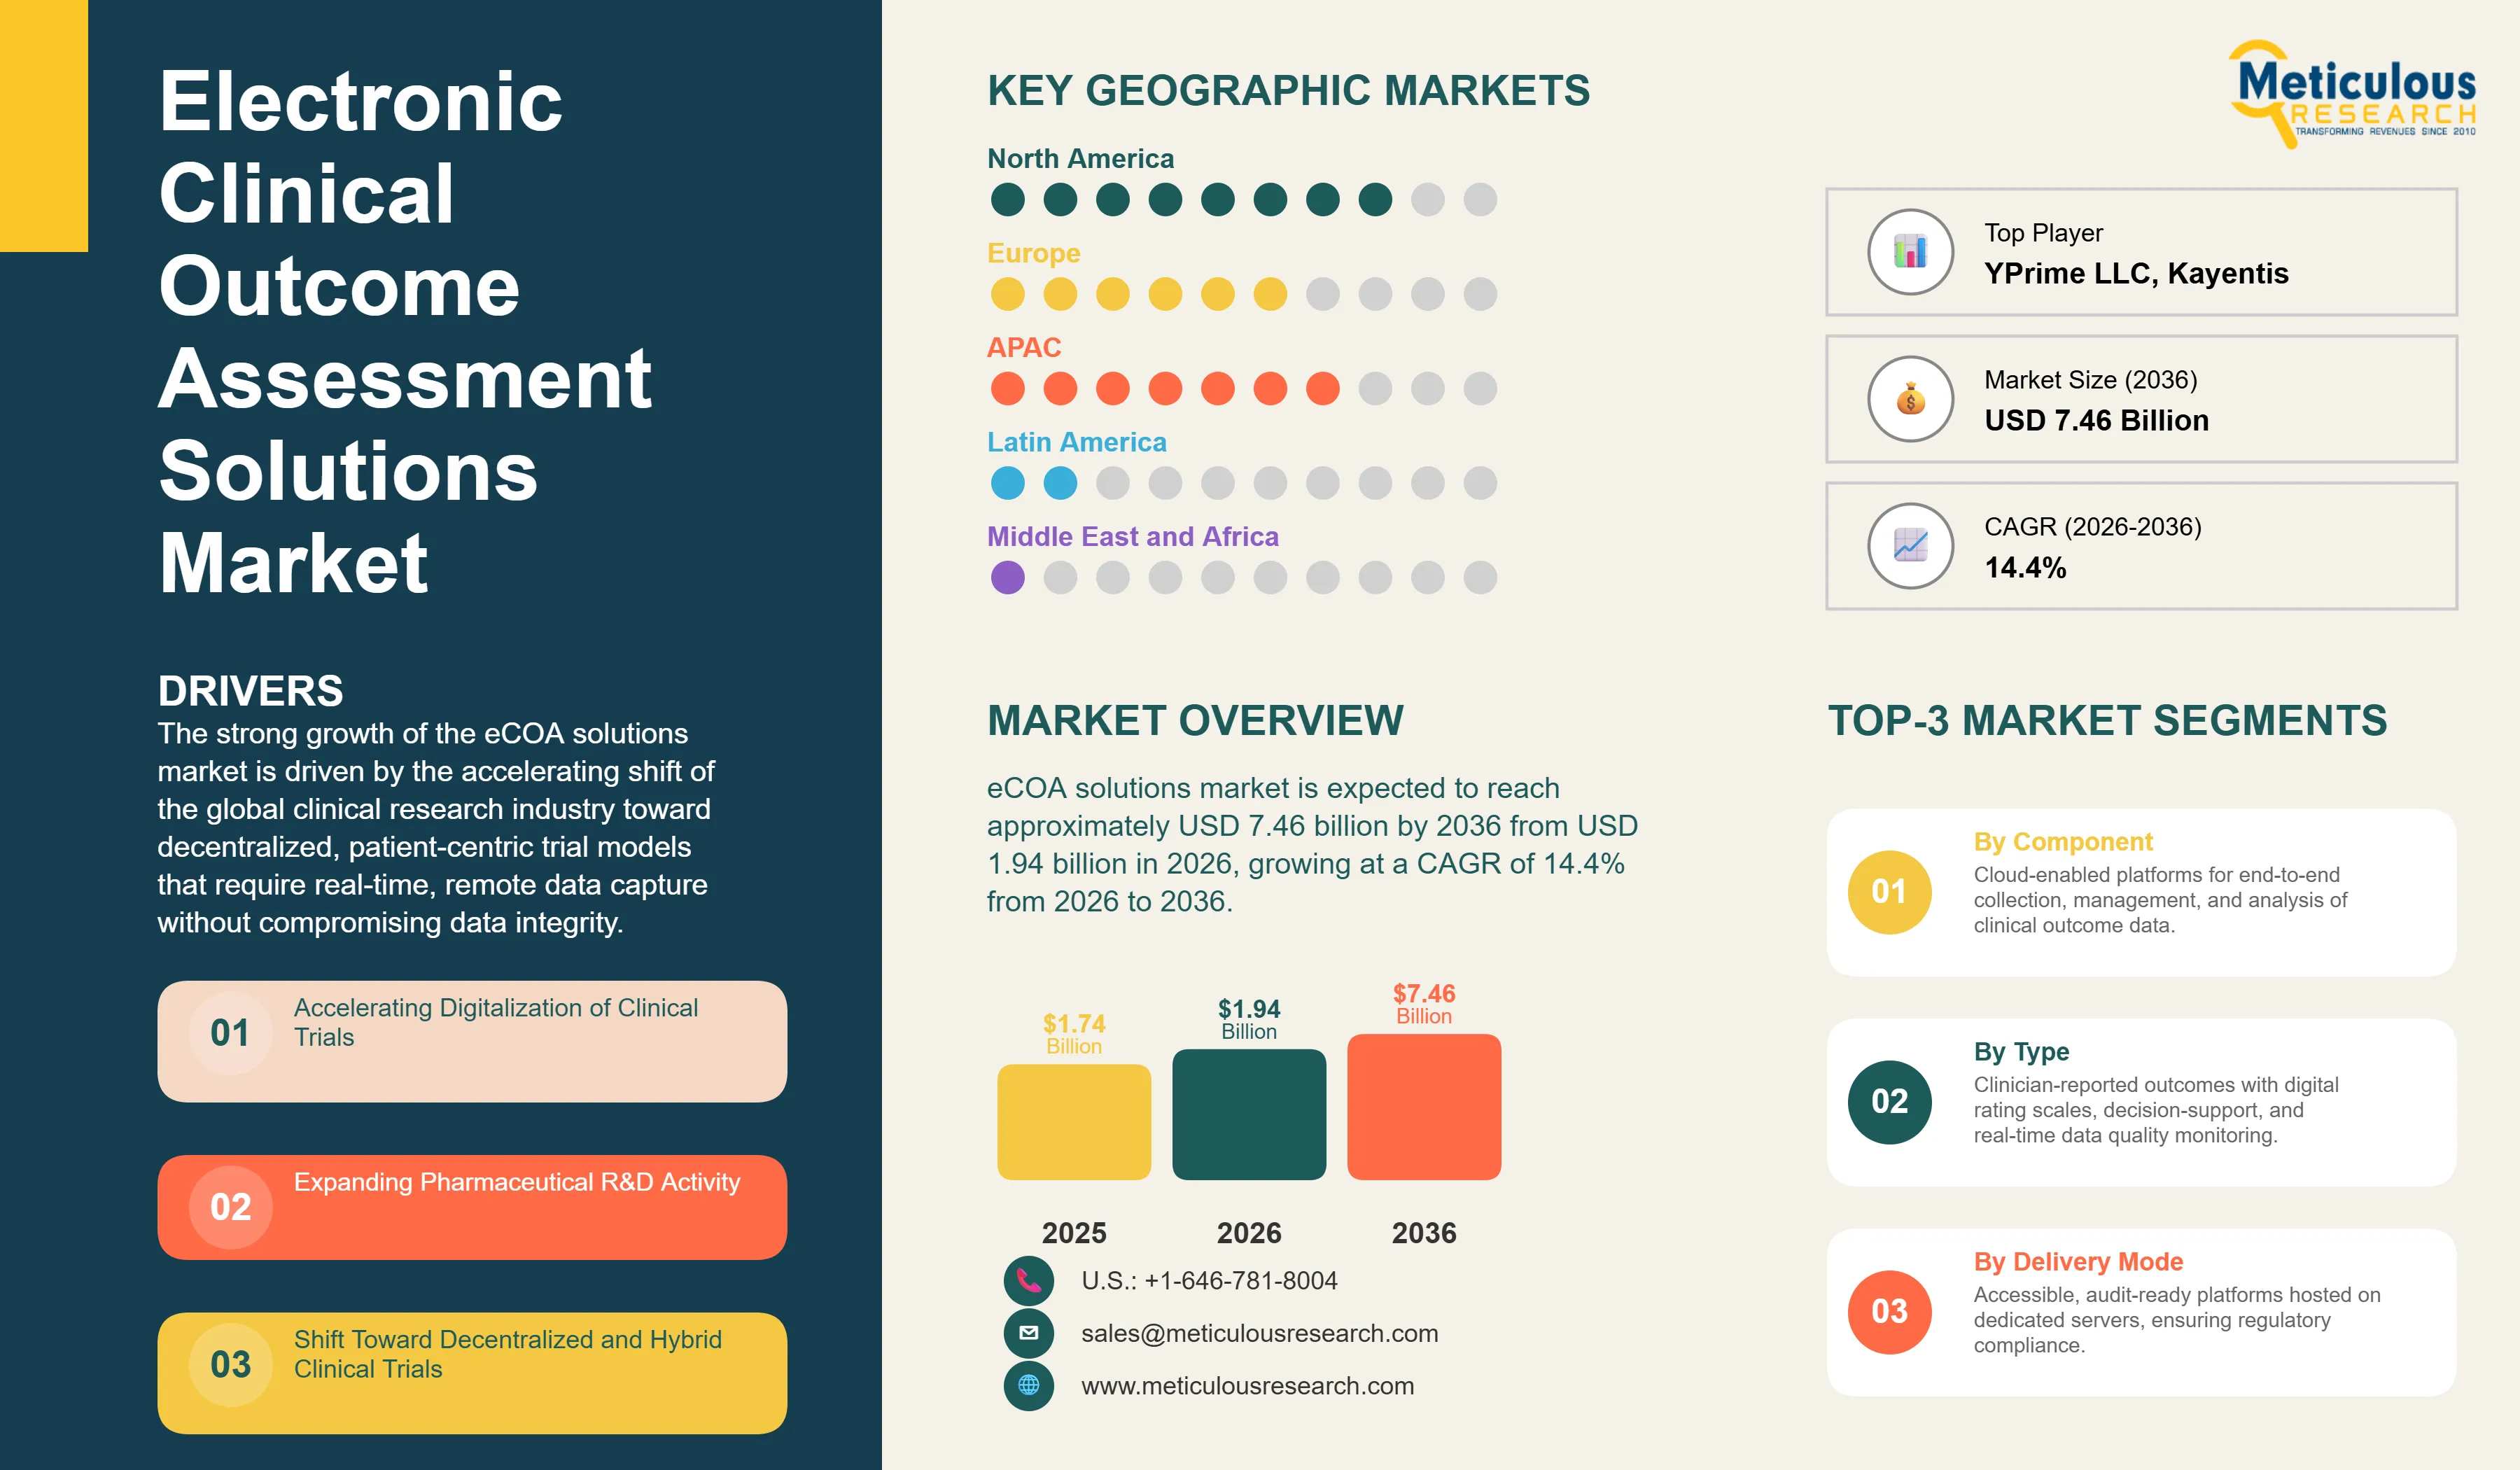
The global electronic clinical outcome assessment (eCOA) solutions market was valued at USD 1.74 billion in 2025. The market is expected to reach approximately USD 7.46 billion by 2036 from USD 1.94 billion in 2026, growing at a CAGR of 14.4% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 284
- Format
- PDF + Excel
- Report ID
- MR-1790
- Base year
- 2025
- 2025 · BASELINE
- $1.74B
- 2036
- $7.46B
- CAGR 2026–2036
- 14.4%
2025 baseline · 2026–2036 forecast at 14.4% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global eCOA solutions market is projected to reach USD 7.46 billion by 2036.
The market is expected to grow at a CAGR of 14.4% from 2026 to 2036.
North America dominates the global eCOA solutions market with the largest market share in 2026, driven by high pharmaceutical research and development expenditure, early adoption of digital clinical trial technologies, and a well-established regulatory environment that actively encourages electronic data collection and patient-centric trial designs.
Asia-Pacific is expected to witness the fastest growth during the forecast period, supported by a rapidly expanding clinical research ecosystem, increasing outsourcing of clinical trials to countries such as China, India, Japan, and South Korea, and growing government investment in digital health infrastructure.
By component, the software segment holds the largest market share in 2026, owing to the widespread adoption of cloud-enabled eCOA platform software for end-to-end management of patient outcome data across clinical trial phases.
By type, the ePRO (electronic patient-reported outcomes) segment holds the largest market share in 2026, owing to its patient-centric approach that enables direct, real-time reporting of symptoms, quality of life, and treatment responses.
By delivery mode, the web-hosted segment holds the largest share of the overall market in 2026, owing to its proven audit readiness, cost-effectiveness, and compatibility with existing sponsor data infrastructure.
By end user, the pharmaceutical and biotechnology companies segment holds the largest share of the overall market in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 7.46 Billion |
| Market Size in 2026 | USD 1.94 Billion |
| Market Size in 2025 | USD 1.74 Billion |
| Market Growth Rate (2026-2036) | CAGR of 14.4% |
| Format | PDF, Excel & Cloud Portal · 284 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Component, Type, Delivery Mode, Device Strategy, End User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: component, type, delivery mode, device strategy, end user.
The strong growth of the overall eCOA solutions market is driven by the accelerating shift of the global clinical research industry toward decentralized, patient-centric trial models that require real-time, remote data capture without compromising data integrity. As pharmaceutical sponsors and contract research organizations seek to manage increasingly complex multi-site trials across diverse geographies, eCOA platforms have become essential for maintaining high-quality endpoint data and improving participant engagement throughout the clinical trial lifecycle. The rising demand for digital health technologies, expanding regulatory support for electronic data collection, and the rapid integration of artificial intelligence and wearable devices into clinical trial workflows continue to fuel significant growth of this market across all major geographic regions.
Electronic clinical outcome assessment (eCOA) solutions are digital platforms and tools that enable the systematic collection, management, and analysis of clinical outcome data directly from patients, clinicians, observers, or through standardized performance tasks during clinical trials and real-world studies. These systems replace traditional paper-based questionnaires and manual data entry processes with technology-driven workflows that ensure greater data accuracy, reduced protocol deviations, and improved participant compliance throughout the study lifecycle. The market is defined by a diverse set of solution types, ranging from electronic patient-reported outcome (ePRO) applications deployed on smartphones and tablets to complex clinician-rating platforms with integrated rater training, decision-support prompts, and real-time data quality monitoring capabilities. These solutions are indispensable for clinical trial sponsors seeking to meet stringent regulatory requirements while reducing trial timelines and overall data management costs.
The market encompasses a broad range of offerings, from simple single-endpoint electronic diaries for patient symptom tracking to comprehensive, multi-modal endpoint management platforms that seamlessly integrate eCOA, electronic consent (eConsent), randomization and trial supply management (RTSM), and real-world evidence generation within a single unified environment. These systems are increasingly embedded with advanced components such as artificial intelligence algorithms and wearable sensor integrations that provide services such as automated compliance alerts, predictive patient adherence monitoring, and passive collection of digital biomarkers between scheduled site visits. The ability to deliver high-quality, regulatory-compliant outcome data while supporting remote and decentralized trial participation has made eCOA technology the solution of choice for pharmaceutical companies, contract research organizations, and medical device manufacturers operating in competitive, high-stakes drug development environments.
The global clinical research industry is under significant pressure to accelerate drug development timelines, reduce costs, and demonstrate meaningful patient outcomes to regulators and payers. This drive has accelerated the adoption of digital data capture solutions, with advanced eCOA platforms helping to standardize endpoint collection across multi-site, multi-country studies while supporting decentralized trial models that reduce the burden on clinical sites and patients alike. At the same time, the growing complexity of clinical trial protocols, particularly in therapeutic areas such as oncology, central nervous system disorders, and rare diseases, is reinforcing the need for specialized, validated eCOA instruments capable of supporting novel digital endpoints and real-world evidence strategies.
Report infographic
Market dynamics
4 factors across 3 forcesAccelerating Digitalization of Clinical Trials and Expanding Pharmaceutical R&D
A key driver of the eCOA solutions market is the sustained increase in global clinical trial activity and the pharmaceutical industry's growing commitment to digital data collection as a means of improving trial efficiency, data quality, and regulatory compliance. Global demand for real-time endpoint monitoring, remote patient engagement tools, and centralized data management has created powerful incentives for the adoption of eCOA infrastructure. According to Anju Software's Mid-Year 2025 Clinical Trial Wrap report published in July 2025, the number of initiated Phase I–III interventional trials in the first half of 2025 reached 6,071, representing a 20% increase compared to the same period in 2024. This expansion in trial volume translates directly into higher demand for eCOA platforms capable of managing large, geographically diverse patient populations without sacrificing data integrity. The Association of Clinical Research Professionals noted in its March 2025 report that research coordinators currently spend up to 12 hours per week on redundant data entry, reinforcing the operational case for integrated eCOA solutions that eliminate manual processes and reduce the risk of data errors across complex multi-site studies.
Table of contents
12 chapters · 100 sections · 284 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Software | — |
| By Type | EPRO | — |
| By Delivery Mode | Web-Hosted | Cloud-based |
| By Device Strategy | — | — |
| By End User | Pharmaceutical and Biotechnology Companies | Contract research organizations (CROs) |
By Component
- The software segment accounts for the largest share of the overall eCOA solutions market in 2026.
- This dominance is primarily attributable to the central role that platform software plays in enabling end-to-end clinical outcome data collection, management, validation, and reporting across the full trial lifecycle. eCOA platform software provides the foundational infrastructure through which all patient interactions, clinician ratings, and data quality checks are managed, making it the most critical and highest-value component of any eCOA deployment.
- Leading platforms such as Medidata Rave Clinical Cloud, IQVIA's Orchestrated eCOA, and Clario's Endpoint Platform are continuously expanding their software capabilities to support AI-driven analytics, multi-lingual instrument libraries, and seamless integrations with electronic data capture (EDC), RTSM, and eConsent systems.
- The services segment is, however, expected to grow at a solid pace through 2036, driven by increasing demand for regulatory consulting, linguistic validation, rater training programs, and ongoing technical support as sponsors deploy increasingly complex and multi-modal eCOA study designs.
By Type
- The ePRO (electronic patient-reported outcomes) segment holds the largest share of the overall market in 2026.
- This leadership is primarily attributable to the growing regulatory and scientific emphasis on incorporating the patient's perspective directly into the measurement of treatment benefit, both for new drug approvals and for health technology assessments that inform reimbursement decisions.
- Regulators now mandate the inclusion of patient-centered endpoint data in many therapeutic areas, and ePRO instruments directly fulfill these requirements in a way that observer-based or clinician-administered tools cannot.
- Patient-reported outcome data is also particularly well-suited to remote and decentralized collection via smartphone applications and web portals, enabling continuous symptom reporting between clinic visits and reducing the reliance on recall bias that affects paper-based instruments.
- The eClinRO (electronic clinician-reported outcomes) segment is expected to witness strong growth during the forecast period.
- The increasing complexity of clinical rating scales used in central nervous system trials, oncology, and rare disease research is driving adoption of digital clinician-rated instruments that incorporate decision-support prompts, standardized scoring guides, and real-time rater performance monitoring to ensure consistent, high-quality endpoint data across geographically dispersed investigator sites.
By Delivery Mode
- The web-hosted segment commands the largest share of the global eCOA solutions market in 2026.
- This dominance reflects the strong preference among pharmaceutical sponsors and CROs for hosted deployment models that combine the accessibility and collaborative features of internet-based platforms with the data localization and audit-readiness assurances provided by dedicated server infrastructure.
- Web-hosted eCOA solutions involve lower upfront technology investment for end users and offer proven compatibility with global data privacy regulations, including GDPR and HIPAA, as data can be hosted within jurisdiction-specific data centers to minimize cross-border transfer compliance risks.
- This combination of cost-effectiveness, regulatory predictability, and implementation familiarity continues to underpin the segment's leadership position.
- However, the cloud-based segment is expected to grow at the fastest pace through 2036, driven by its superior scalability, operational flexibility, and support for real-time data sharing across large, multinational trial networks.
- Cloud-native eCOA platforms enable sponsors to rapidly scale capacity across new study sites and geographies without the need for additional infrastructure investment, making them increasingly attractive for the decentralized and hybrid trial models that are reshaping the clinical research landscape.
By Device Strategy
- The BYOD (bring your own device) segment is gaining significant momentum within the overall eCOA solutions market.
- The BYOD model allows trial participants to use their own smartphones or tablets to complete eCOA assessments through purpose-built mobile applications, eliminating the logistical complexity and cost associated with provisioning, shipping, and recovering dedicated study devices at scale.
- This approach significantly reduces the per-patient technology cost of eCOA deployments and improves participant convenience, which in turn supports higher compliance rates and better data completeness across geographically dispersed trial populations.
- Leading eCOA providers including Medidata, Signant Health, and Medable have invested heavily in BYOD-compatible platform architectures that deliver a consistent, validated data collection experience across a wide range of consumer device types and operating systems.
- The provisioned device segment remains significant, particularly for studies in therapeutic areas requiring specialized hardware integrations, such as respiratory trials requiring connected spirometry devices, or neurology studies requiring validated cognitive testing interfaces that must be controlled for screen size and interaction design.
By End User
- The pharmaceutical and biotechnology companies segment commands the largest share of the global eCOA solutions market in 2026.
- This dominance stems from the segment's direct accountability for the quality and regulatory integrity of endpoint data submitted in support of marketing authorization applications, making it the primary decision-maker and budgetary authority for eCOA platform investments across all trial phases.
- Large pharmaceutical companies running multinational Phase II and Phase III programs require enterprise-grade eCOA solutions capable of supporting dozens of languages, hundreds of investigator sites, and complex multi-instrument endpoint strategies simultaneously.
- Leading companies in this space, including those partnering with Medidata, IQVIA, and Clario, depend on these platforms to ensure that primary and key secondary endpoints are captured consistently and in compliance with regulatory expectations across every market where registration is sought.
- The contract research organizations (CROs) segment is, however, poised for the fastest growth through 2036, fueled by the expanding outsourcing of clinical operations by pharmaceutical and biotechnology companies that seek to concentrate internal resources on core drug discovery and portfolio strategy activities.
- CROs are increasingly offering eCOA as a bundled component of their full-service trial management propositions, combining outcome data capture with randomization, patient payment, and site support services within integrated digital trial ecosystems.
Geographic analysis
North America
Largest shareNorth America holds the largest share of the global eCOA solutions market in 2026. This leadership position is primarily attributable to the region's concentration of major pharmaceutical and biotechnology research activities, high clinical research expenditure, and early institutional adoption of digital data collection technologies in clinical trials. The United States alone accounts for a significant portion of global eCOA investment, driven by the presence of the world's largest pharmaceutical companies, a dense network of contract research organizations, and a regulatory environment at the FDA that actively supports electronic endpoint collection through published guidances on patient-reported outcome development and the Computer Software Assurance framework for clinical trial systems. The presence of leading eCOA platform providers including IQVIA Inc., Medidata Solutions Inc., Clario, Signant Health, and Medable Inc. within the region also provides a robust ecosystem for both standard and highly specialized digital endpoint solutions.
Europe
Europe accounts for a substantial share of the global eCOA solutions market, driven by the high volume of clinical research activity in key pharmaceutical markets such as Germany, the United Kingdom, France, Switzerland, and the Netherlands. The European Medicines Agency's ongoing commitment to patient-centered medicine evaluation and its guidance on the use of patient-reported outcomes in regulatory submissions are reinforcing demand for validated eCOA instruments across therapeutic areas. Countries across the region also benefit from well-established clinical trial infrastructure and a growing emphasis on multi-stakeholder data sharing frameworks that position eCOA as a critical enabler of both regulatory and real-world evidence strategies.
Asia-Pacific
Fastest growthAsia-Pacific is expected to grow at the fastest pace during the forecast period. The region's expanding clinical research ecosystem, supported by large and diverse patient populations, competitive site costs, and growing regulatory harmonization in countries such as China, Japan, India, and South Korea, is attracting a rising share of global trial activity. Government-led digital health initiatives and the growing involvement of regional CROs and technology partners in multinational studies are accelerating eCOA platform adoption across both established and emerging clinical research hubs in the region.
Competitive landscape
- IQVIA Inc.
- Clario
- Signant Health
- ICON Plc
Frequently asked questions
The global eCOA solutions market is expected to grow from USD 1.94 billion in 2026 to USD 7.46 billion by 2036.
Cite this report
Meticulous Research. (2026). Electronic Clinical Outcome Assessment (eCOA) Solutions Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1790). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/electronic-clinical-outcome-assessment-solutions-market-6473