Crop Protection Chemicals Market (2024-2031)
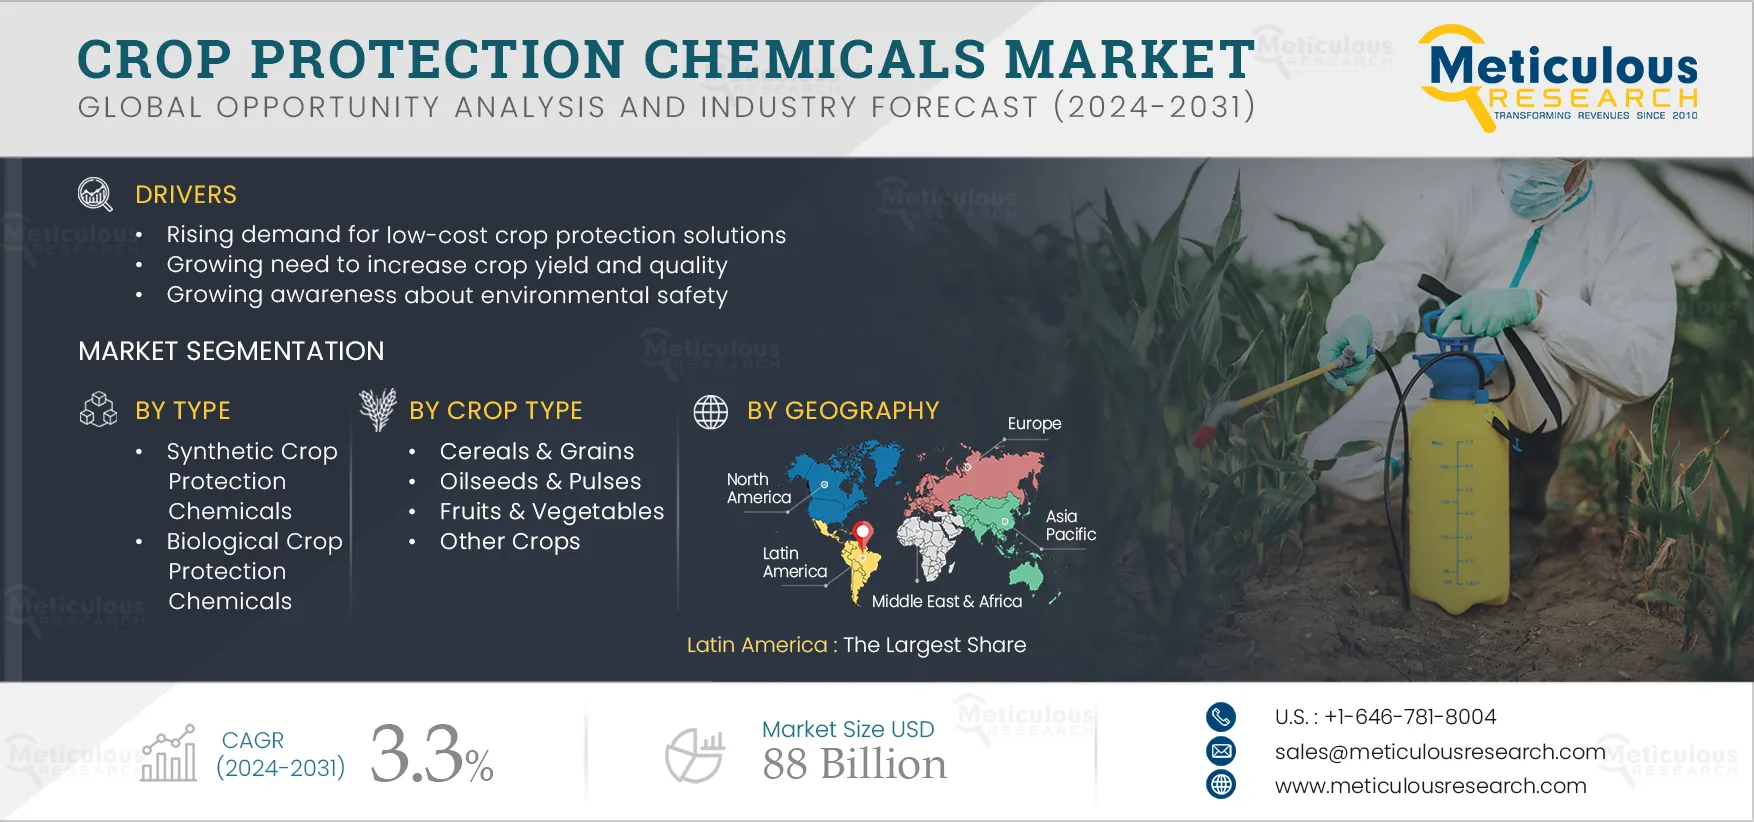
The Crop Protection Chemicals Market is projected to reach $88 billion by 2031, at a CAGR of 3.3% during the forecast period of 2024–2031.
- Published
- Jun 2024
- Pages
- 600
- Format
- PDF + Excel
- Report ID
- MRAGR - 104124
- Base year
- 2023
- 2031 · FORECAST
- $88.00B
- 2031
- $88.00B
- CAGR 2024–2031
- 3.3%
2023 baseline · 2024–2031 forecast at 3.3% CAGR · hover a bar for the value
Key highlights
By Type: In 2024, the Synthetic Crop Protection Chemicals Segment to Dominate the Crop Protection Chemicals Market
By Formulation: In 2024, the Liquid Formulation Segment to Dominate the Crop Protection Chemicals Market
By Mode of Application: The Seed Treatment Segment to Witness Highest Demand During the Forecast Period
By Crop Type: In 2024, the Cereals & Grains Segment to Dominate the Crop Protection Chemicals Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | ~600 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 3.3% |
| Market Size (Value) | $88 Billion |
| Segments Covered | By Type · Synthetic Crop Protection Chemicals · Herbicides · Glyphosate · Potassium Glyphosate · Isopropylamine Glyphosate · Other Salts of Glyphosate · Atrazine · 2,4-D · Acetochlor · Other Herbicides · Insecticides · Organophosphates · Pyrethroids · Carbamates · Organochlorides · Other Insecticides · Fungicides · Triazole · Strobilurins · Chloronitriles · Dithiocarbamates · Phenylamides · Benzimidazoles · Other Fungicides · Other Synthetic Crop Protection Chemicals · Biological Crop Protection Chemicals · Bioinsecticides · Biofungicides · Bionematicides · Bioherbicides · Other Biological Crop Protection Chemicals · By Formulation · Liquid Formulation · Dry Formulation · By Mode of Application · Foliar Spray · Seed Treatment · Soil Treatment · Other Modes of Application · By Crop Type · Cereals & Grains · Maize/Corn · Wheat · Other Cereals & Grains · Oilseeds & Pulses · Fruits & Vegetables · Other Crops |
| Countries Covered | Latin America (Brazil, Mexico, Argentina, Chile, and Rest of Latin America), Asia-Pacific (China, India, Japan, Australia, Thailand, Vietnam, Indonesia, Malaysia, and Rest of Asia-Pacific), Europe (France, Germany, Italy, Spain, U.K., and Rest of Europe), North America (U.S., Canada), and the Middle East & Africa |
| Key Companies | BASF SE (Germany), Bayer AG (Germany), Corteva, Inc. (U.S.), FMC Corporation (U.S.), Novozymes A/S (Denmark), Nufarm Limited (Australia), Syngenta AG (Switzerland), UPL Limited (India), Sumitomo Chemical Co., Ltd. (Japan), and Jiangsu Yangnong Chemical Co. Ltd (China). |
Report overview
Segments covered: type, formulation, mode of application, crop type. Regions: Latin America, Asia-Pacific, Europe, North America.
The growth of this market can be attributed to the rising demand for low-cost crop protection solutions, the growing need to increase crop yield and quality, growing awareness about environmental safety, increasing adoption of advanced agricultural practices and technologies, and rapidly decreasing agricultural land. However, growing concerns over chemical residues in food and stringent and non-standardized regulations hinder the growth of this market. Moreover, an increasing focus on integrated pest management, the growing adoption of biological seed treatments, and emerging economies in Asia-Pacific and Latin America are expected to generate significant growth opportunities for the stakeholders in the crop protection chemicals market.
On the other hand, lengthy product registration and approval processes and the complicated process of developing film coating for seed treatment pose a major challenge to market growth. The latest trends in the global crop protection chemicals market are sustainability and bio-based solutions and digitalization and precision agriculture.
Report infographic
Market dynamics
4 factors across 3 forcesGrowing Need to Increase Crop Yield and Quality Boost the Growth of the Crop Protection Chemicals Market
The world population is growing rapidly. According to the Department of Economic and Social Affairs (UN), the global population is expected to reach 8.6 billion by 2030, 9.8 billion by 2050, and 11.2 billion by 2100. This rise in global population is posing a burden on the world's resources to provide more and different types of food. Also, there has been a growing demand for nutrient-dense and residue-free food products due to growing health awareness, socio-economic changes, increased incomes, and rapid urbanization.
The agricultural sector plays a vital role in the stability of the global economy. The global demand and consumption of crops for food, feed, and fuel are increasing rapidly, consequently driving the need to increase crop yield. Since crop yields are becoming increasingly important, the demand for cost-effective strategies to boost crop yields is also rising significantly. Furthermore, the decline in agricultural land has driven agricultural producers to become more efficient and productive to meet the global food demand.
According to the Food and Agriculture Organization (FAO), the demand for cereals for human consumption and animal feed is projected to reach 3 billion tonnes by 2050, a significant increase from 2.1 billion tonnes in 2018. In addition, the rising demand for biofuels will continue to exert upward pressure on commodity prices, affecting food security and poverty levels in developing countries. Thus, crop protection chemicals and modern agricultural practices with advanced technologies are necessary for breaking yield barriers and enhancing crop productivity to meet the global food demand while ensuring environmental safety. Crop protection chemicals provide farmers with a cost-effective way of improving crop yield and quality.
Growing Awareness About Environmental Safety to Drive the Growth of the Crop Protection Chemicals Market
Biopesticides are valuable tools for growers as they are highly effective in managing pests and diseases without negatively impacting the environment, and their active and inert ingredients are generally considered safe. Besides the microbial content, carrier media for formulating biopesticides consist of several organic materials, such as animal broth, organic materials, or organic waste products. The media is a biodegradable material. Biopesticides support the stability and sustainability of the agroecosystem as they do not negatively impact the environment.
Besides their impacts on humans, pesticides cause significant damage to the environment. There have been many cases around the world wherein freshwater used for agriculture was polluted with harmful pesticides, causing serious damage to the freshwater flora and fauna. Therefore, many environmental organizations, such as the Environmental Protection Agency, have been opposing pesticides. A recent study conducted by researchers at the Public Health Institute, California Department of Health Services, and the UC Berkeley School of Public Health found a six-fold increase in risk factors for Autism Spectrum Disorders (ASD) for children of women who were exposed to organochlorine pesticides. These factors are driving the demand for biopesticides in the global market.
Biologicals are always safer and easier on the environment than chemical products. Biopesticides are often formulated to only affect the target pest and closely related organisms (selective) in direct contrast to chemical pesticides, which frequently offer broad sweeping coverage (non-selective) that negatively impacts insects, birds, and anything else that comes into contact with them. Biopesticides contain natural organisms or products and pose a lower threat to the environment and human health. Biopesticides have gained much importance in pest management and have long been promoted as prospective alternatives to synthetic pesticides. Although biopesticide use is increasing by almost 10% every year globally, there is still a considerable amount of time before biopesticides completely replace chemical pesticides.
Thus, the growing awareness about environmental safety is boosting the use of biological crop protection products, driving the growth of this market.
Table of contents
12 chapters · 200 sections · 600 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Synthetic Crop Protection Chemicals | Biological crop protection chemicals |
| By Formulation | Liquid Formulation | — |
| By Mode of Application | Foliar spray | Seed treatment |
| By Crop Type | Cereals & Grains | Fruits & vegetables |
By Type
- The synthetic crop protection chemicals segment is expected to account for the largest share of over 91.3% of the crop protection chemicals market.
- The large market share of this segment can be attributed to its increasing use in developing countries, ease of availability, high efficiency, and lower cost than biological products.
- However, the biological crop protection chemicals segment is projected to witness the highest growth rate during the forecast period of 2024–2031.
- This growth is driven by the increasing adoption of organic farming, growing environmental and public health concerns regarding the use of chemical crop protection products, high demand for chemical residue-free agricultural products, and the initiatives by governments worldwide to promote the use of biological crop protection products.
By Formulation
- The liquid formulation segment is expected to account for the larger share of over 68.8% of the crop protection chemicals market.
- The large market share of this segment can be attributed to the uniform & easy application of liquid form, better performance, and higher effective duration (up to 6 months) than dry form (up to 3 months).
By Mode of Application
- The Seed Treatment Segment to Witness Highest Demand During the Forecast Period
- The foliar spray segment is expected to account for the largest share of over 69.9% of the crop protection chemicals market.
- The large market share of this segment can be attributed to its high efficiency, uniform distribution, and minimum to no wastage of crop protection chemicals.
- However, the seed treatment segment is projected to witness the highest growth rate during the forecast period of 2024–2031.
- This growth is driven by the increased germination and uniform seedling emergence, safety, and pest resistance advantages of the seed treatment technique.
- In this method, microbial pesticides are often applied with chemical pesticides, as chemical pesticides provide early-season control, and microbial pesticides provide extended control.
By Crop Type
- The Cereals & Grains Segment to Dominate the Crop Protection Chemicals Market
- The cereals & grains segment is expected to account for the largest share of over 37.4% of the crop protection chemicals market.
- The large market share of this segment can be attributed to the growing need to increase cereal & grain production, minimize cereal & grain loss due to pests and diseases, and the increasing use of these crops in animal feed, biofuel, and starch & ethanol production.
- However, the fruits & vegetables segment is projected to witness the highest growth rate during the forecast period of 2024–2031.
- This growth is driven by the increasing fruit & vegetable production across the globe, the growing demand for chemical-free organic fruits & vegetables, and the growing number of diseases affecting fruit & vegetable crops.
Geographic analysis
Latin America
Largest shareIn 2024, Latin America is expected to account for the largest share of 3 over 2.1% of the crop protection chemicals market, followed by Asia-Pacific, North America, and the Middle East & Africa. The crop protection chemicals market in Latin America is estimated to reach $22.33 billion in 2024. Latin America’s significant market share can be attributed to several key factors, including increasing population and food requirements, rapid expansion in the agriculture sector, and the growing need to increase crop yield. Also, rising awareness among farmers about the benefits of using high-end agro products and increasing adoption of organic farming practices further support the growth of this market.
Europe
Fastest growthHowever, the market in Europe is slated to register the highest growth rate during the forecast period. This regional market's growth is driven by the increasing demand for organic products, increasing government support, increased adoption of natural products over synthetic products, and rising health consciousness.
Competitive landscape
- May 2023
BASF (Germany) launched Axalion Active insecticide. This insecticide provides farmers with a much-needed tool to control resistant pests.
- May 2023
FMC Corporation (U.S.) and Syngenta Crop Protection (Switzerland) signed an agreement to bring to market a breakthrough technology to control weeds in rice in Asia. The new active ingredient, tetflupyrolimet, was discovered and developed by FMC with support from Syngenta for development in rice. It is the first major herbicide with a novel mode of action (DHODH – HRAC Group 28) in more than three decades. It provides relief to farmers challenged by increasing weed resistance to existing herbicides. Under the agreement, FMC and Syngenta will bring tetflupyrolimet-based products to key rice markets in Asia.
- March 2023
Corteva (U.S.) launched Adavelt, an active fungicide with recent product registrations in Australia, Canada, and South Korea.
- February 2023
Bayer (Germany) partnered with Kimitec (Spain) for the biological discovery and commercialization of biological crop protection solutions and biostimulants. As part of a global agreement, both companies will become key partners to advance and establish biological solutions derived from natural sources: crop protection products that address pests, diseases, and weeds, as well as biostimulants to promote plant growth.
- BASF SE · Germany
- Bayer AG · Germany
- Corteva, Inc. (U.S.)
- FMC Corporation (U.S.)
- Novozymes A/S · Denmark
- Nufarm Limited · Australia
- Syngenta AG · Switzerland
- UPL Limited · India
- Sumitomo Chemical Co., Ltd. · Japan
- Jiangsu Yangnong Chemical Co. Ltd · China
Frequently asked questions
This report covers the market sizes and forecasts of the crop protection chemicals market based on type, formulation, mode of application, crop type, and geography. It also provides the value & volume analysis of various segments and subsegments of the crop protection chemicals market at the regional and country levels.
Cite this report
Meticulous Research. (2024). Crop Protection Chemicals Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRAGR - 104124). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/crop-protection-chemicals-market-2584