Beverage Packaging Market (2025-2032)
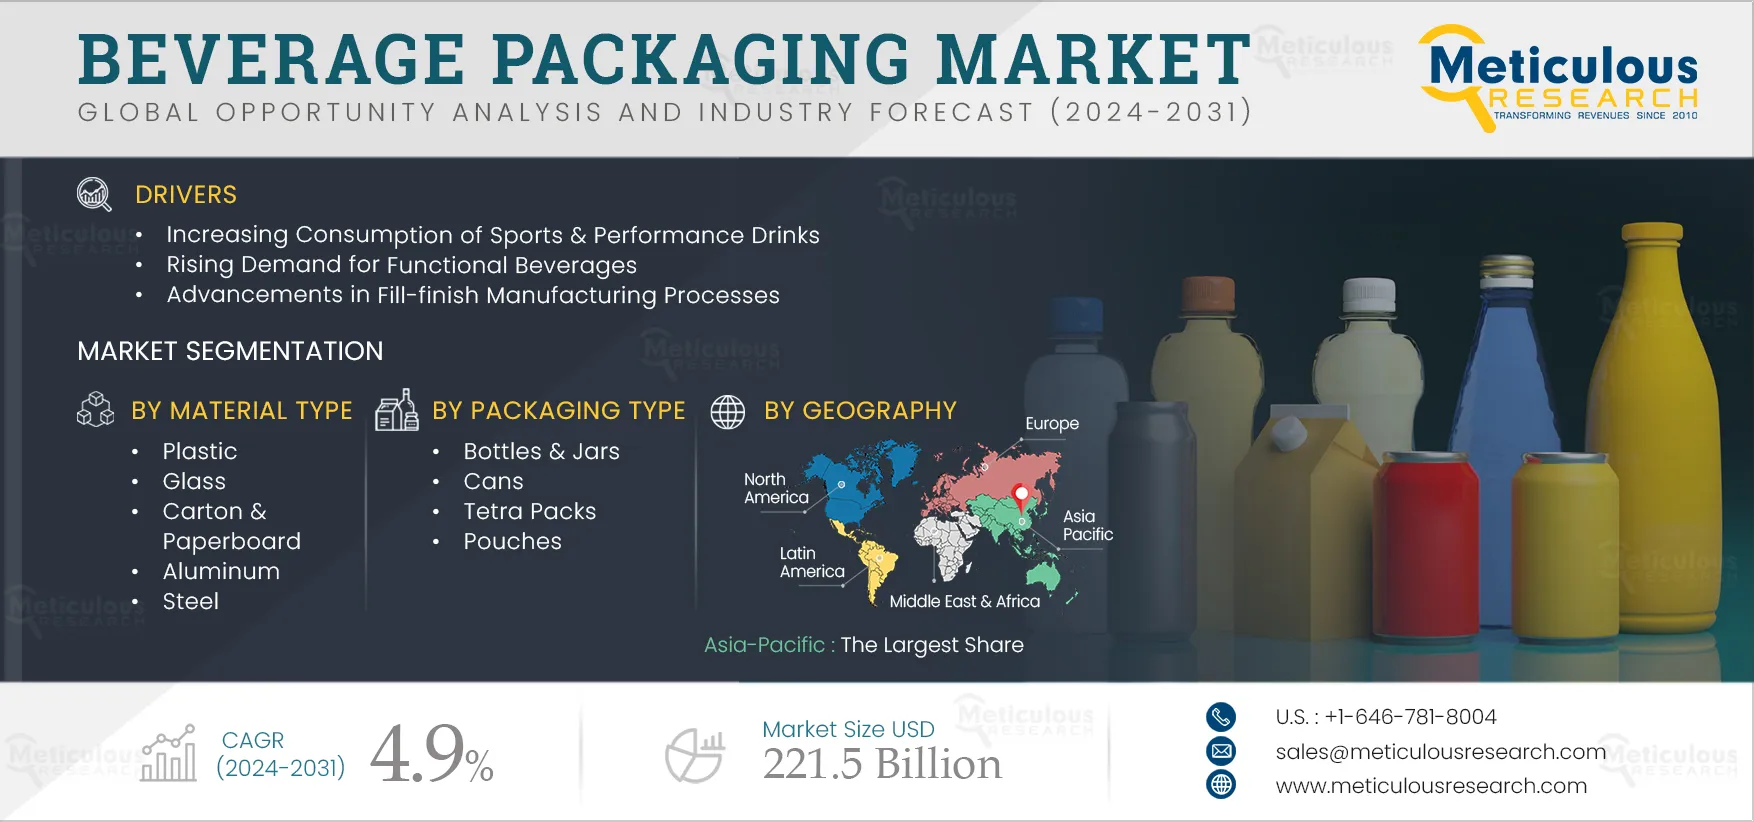
The Beverage Packaging Market is expected to reach $221.5 billion by 2032, at a CAGR of 4.9% from 2025–2032.
- Published
- Jun 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRFB - 1041242
- Base year
- 2024
- 2032 · FORECAST
- $221.5B
- 2032
- $221.5B
- CAGR 2025–2032
- 4.9%
2024 baseline · 2025–2032 forecast at 4.9% CAGR · hover a bar for the value
Key highlights
By Material Type: In 2025, the Plastic Segment to Dominate the Beverage Packaging Market
By Packaging Type: In 2025, the Bottles & Jars Segment to Dominate the Beverage Packaging Market
By Beverage Formulation: In 2025, the Ready-to-drink Beverages Segment to Dominate the Beverage Packaging Market
By Beverage Type: In 2025, the Non-alcoholic Beverages Segment to Dominate the Beverage Packaging Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR | 4.9% |
| Market Size | USD 221.5 Billion by 2032 |
| Segments Covered | By Material Type · Plastic · Glass · Carton & Paperboard · Aluminum · Steel · Foil · Others Material Types · By Packaging Type · Bottles & Jars · Cans · Tetra Packs · Pouches · Other Packaging Types · By Beverage Formulation · Concentrated Beverage & Syrups · Ready-to-drink Beverages · By Beverage Type · Alcoholic Beverages · Beer · Wine · Spirits · Other Alcoholic Beverages · Non-alcoholic Beverages · Carbonated Soft Drinks · Sports & Energy Drinks · Tea & Coffee · Juices & Nectars · Dairy & Dairy Alternatives Beverages · Flavored & Fortified Water · Other Non-Alcoholic Beverages |
| Countries Covered | Europe (Germany, U.K., France, Italy, Spain, Netherlands, Switzerland, Sweden, Denmark, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia & New Zealand, Indonesia, Thailand, Vietnam, Malaysia, Singapore, and Rest of Asia- Pacific), North America (U.S., Canada), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Israel, and Rest of Middle East & Africa) |
| Key Companies | Amcor plc (Australia), Ball Corporation (U.S.), Tetra Laval S.A. (Switzerland), Verallia SA (France), Vetropack Holding AG (Switzerland), Crown Holdings, Inc. (U.S.), Silgan Containers LLC (U.S.), Vidrala Group (Spain), CCL Container Inc. (U.S.), Berry Global Group, Inc. (U.S.), Sonoco (U.S.), Ardagh Group (Luxembourg), Mondi Group (U.K.), Tetra Pack Group (Switzerland), and O-I Glass, Inc. (U.S.) |
Report overview
Segments covered: material type, packaging type, beverage formulation, beverage type. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
The growth of the beverage packaging market is driven by the increasing consumption of sports & performance drinks, rising demand for functional beverages, and advancements in fill-finish manufacturing processes.
Moreover, the increasing availability of alcoholic ready-to-drink (RTD) beverages and the rapid growth of the retail sector are expected to create market growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Consumption of Sports & Performance Drinks
The rising consumption of sports and performance drinks drives the growth of the beverage packaging market. These beverages often contain ingredients like vitamins, electrolytes, and protein, making proper packaging essential for preserving their quality and freshness. Packaging materials that offer protection against light, oxygen, and temperature fluctuations are crucial to maintaining the efficacy and taste of these beverages.
Sports and performance drinks have specific packaging requirements due to their ingredients, necessitating portable and convenient packaging solutions. This has led to a rise in the use of PET bottles, which are lightweight, easy to handle, and resealable. Moreover, packaging plays a pivotal role in the marketing and branding strategies of sports drink manufacturers. Eye-catching designs and graphics on packaging can influence consumer purchasing decisions and contribute to building a strong brand image. This emphasis on aesthetics drives continuous innovation in beverage packaging within this category.
Rising Demand for Functional Beverages
Functional beverages encompass a wide range of products, including energy drinks, sports drinks, ready-to-drink (RTD) teas, enhanced waters, and wellness shots. This variety in product offerings creates opportunities for beverage packaging companies to innovate and develop specialized packaging solutions tailored to the unique needs of each beverage category.
The demand for functional beverages is driving innovation in packaging materials that can meet specific requirements such as product preservation, barrier properties, and sustainability. For instance, packaging materials equipped with oxygen and light barrier properties play a crucial role in maintaining the freshness and efficacy of functional beverage ingredients throughout their shelf life.
Furthermore, there is a growing emphasis on sustainable packaging solutions, driving the development of eco-friendly materials like biodegradable plastics, compostable packaging, and recyclable packaging formats.
Table of contents
12 chapters · 139 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Material Type | Plastic | Carton & paperboard |
| By Packaging Type | Bottles & Jars | Tetra packs |
| By Beverage Formulation | Ready-to-drink Beverages | — |
| By Beverage Type | Non-alcoholic Beverages | — |
By Material Type
- The Plastic Segment to Dominate the Beverage Packaging Market
- The plastic segment is expected to account for the largest share of over 31.0% of the beverage packaging market.
- This segment’s large market share can be attributed to the cost-effectiveness of plastic packaging compared to glass or metal alternatives.
- Plastic packaging is generally cheaper to produce, making it particularly attractive for companies aiming to reduce packaging expenses while ensuring product quality.
- Moreover, plastic packaging is durable and resistant to breakage, unlike glass containers that can easily shatter.
- This durability helps minimize the risk of product damage during transportation and handling, thereby reducing losses for beverage manufacturers.
- Key market players are launching new packaging solutions.
- For instance:
- In March 2025, INEOS Olefins & Polymers Europe, PepsiCo, Inc. (U.S.), and Amcor plc (Australia) announced a partnership to launch new snack packaging for Sunbites crisps made from 50% recycled plastic.
- In July 2024, PepsiCo India launched Pepsi Black bottles made entirely from 100% recycled plastic (rPET) in the carbonated beverage category.
- However, the carton & paperboard segment is projected to register the highest CAGR during the forecast period.
- This growth can be attributed to the lightweight properties of carton and paperboard packaging compared to alternatives like glass or metal.
- Their reduced weight lowers transportation costs and carbon emissions, making them environmentally friendly and cost-effective choices for beverage manufacturers.
- Furthermore, carton and paperboard packaging provides flexibility in design and printing capabilities, allowing beverage companies to craft visually appealing packaging that effectively communicates brand identity and product details.
- This customizability enhances product visibility on store shelves and captures consumer attention.
- Key market players are launching various initiatives, contributing to the market’s growth.
- For instance:
- In March 2025, AptarGroup, Inc. (U.S.), a global manufacturer of consumer dispensing packaging and drug delivery devices, launched a patented Aptar Halopack solution designed for both dry and high-moisture foods.
- This packaging is available in various configurations, including skin pack, clamshell, freezable, microwave and oven-able, and modified atmosphere packaging.
- In November 2024, Tetra Pak (Switzerland) collaborated with Lactogal, a Portuguese food products company, to launch the Tetra Brik 200 Slim Leaf aseptic beverage carton.
- This carton features a paper-based barrier and is composed of approximately 80% paperboard, significantly increasing the package's renewable content to 90%.
By Packaging Type
- The Bottles & Jars Segment to Dominate the Beverage Packaging Market
- The bottles & jars segment is expected to account for the largest share of over 42.0% of the beverage packaging market.
- Bottles and jars are the primary packaging formats for beverages.
- These containers offer convenience in handling, pouring, and storing drinks.
- Consumers often perceive bottles and jars as symbols of quality, freshness, and convenience, which contributes to their widespread acceptance in the market.
- Moreover, bottles and jars provide effective protection against external elements such as light, moisture, and air, which are crucial for preserving the freshness and quality of beverages.
- This protection helps extend the shelf life of products and maintains their taste, aroma, and nutritional value.
- As a result, beverage companies rely on bottles and jars to safeguard their products throughout the transportation, storage, and consumption phases.
- These factors contribute to the significant market share of this segment.
- However, the tetra packs segment is projected to register the highest CAGR during the forecast period.
- Tetra packs are versatile packaging solutions suitable for a diverse range of beverages, such as milk, juices, and other beverages.
- These packaging solutions are lightweight, portable, and easy to handle.
- The packaging is adaptable to various volumes, ranging from single-serving cartons to larger family-sized containers, catering effectively to different consumer preferences and usage types.
- These factors are expected to drive the growth of this segment during the forecast period.
By Beverage Formulation
- The ready-to-drink beverages segment is expected to account for the larger share of over 59.0% of the beverage packaging market.
- This segment’s large market share can be attributed to the convenience offered by RTD beverages.
- These beverages do not require preparation, saving time and effort.
- This convenience contributes to the popularity of RTD beverages and drives demand for appropriate packaging solutions.
- Furthermore, there is a growing demand for healthier beverage options, which has further fueled the popularity of RTD beverages such as functional drinks, cold-pressed juices, and plant-based alternatives.
- Several key market players have launched various initiatives to capitalize on this trend.
- For instance, in February 2025, Salud Beverages Private Limited (India), a global urban lifestyle brand, launched a new range of ready-to-drink (RTD) products.
- Moreover, the ready-to-drink beverages segment is projected to register a higher CAGR during the forecast period.
By Beverage Type
- The non-alcoholic beverages segment is expected to account for the larger share of over 57.0% of the beverage packaging market.
- Non-alcoholic beverages encompass a wide variety of products, including carbonated soft drinks, bottled water, juices, sports drinks, energy drinks, ready-to-drink teas and coffees, and functional beverages.
- This segment encompasses a diverse range of products, including carbonated soft drinks, bottled water, juices, sports drinks, energy drinks, ready-to-drink tea & coffee, and functional beverages.
- This diverse product range drives the demand for a wide array of packaging options to cater to different beverage types, flavors, and packaging sizes.
- Additionally, non-alcoholic beverages are frequently consumed on the go, driving the demand for portable, single-serving packaging formats such as cans, PET bottles, Tetra Pak cartons, and pouches.
- Moreover, packaging innovations such as interactive labels, embossed textures, and augmented reality experiences play a crucial role in differentiating brands and engaging consumers.
- These factors contribute to the large market share of this segment.
- Additionally, the non-alcoholic beverages segment is projected to register a higher CAGR during the forecast period.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of over 39.0% of the beverage packaging market. Asia-Pacific’s significant market share can be attributed to the rapid pace of urbanization and population growth in the region, which is driving increased demand for packaged beverages. The rising urbanization in Asia-Pacific is driving a shift towards urban lifestyles, which prioritize convenience and on-the-go consumption of beverages. This trend is significantly boosting the demand for packaged beverages and necessitating the development of efficient beverage packaging solutions. Moreover, consumer preferences in the Asia-Pacific region are evolving, with a noticeable shift towards healthier beverage options, convenience, and premiumization. Packaging plays a crucial role in meeting these preferences by effectively communicating product attributes, enhancing convenience, and differentiating brands through attractive designs and innovative packaging formats. Furthermore, key market players are launching various initiatives to advance beverage packaging in Asia-Pacific. For instance, in November 2024, Budweiser Brewing Company APAC (Hong Kong) launched its lightest aluminum can for beer in China, weighing only 9.57g for a 330ml can, which is 4% lighter than the industry average. Additionally, in January 2022, Ball Corporation (U.S.), specializing in aluminum packaging, invested USD 10,000 million in establishing two aluminum cans and bottle manufacturing plants in India. Moreover, the market in Asia-Pacific is projected to register the highest CAGR of 6.0% during the forecast period. Asia-Pacific to Dominate the Beverage Packaging Market in 2025
Competitive landscape
- February 2025
Tetra Pak (Switzerland) announced several strategic investments designed to enhance the recycling capacity for carton packages in the European Union (EU). The move supports the goals of the proposed EU Packaging and Packaging Waste Regulation (PPWR) by ensuring that all packaging components are recycled and valuable raw materials are kept in circulation for longer.
- March 2025
Hinojosa Packaging Group launched Foodservice, a new range of 100% recyclable primary packaging intended for the prepared foods and beverages markets. The new line is available in three ranges, including beverage, dairy, and food containers.
- July 2024
Tetra Pak (Switzerland) and Axjo Plastic AB (Sweden) collaborated on a feasibility study to build a new recycling plant for the polyAl layers in carton packages with an annual recycling capacity of 10,000 tonnes.
- September 2022
European glass packaging manufacturer Vetropack developed a returnable bottle made from tempered lightweight glass. The Echovai bottle is durable and lightweight, weighing up to 30% less than standard returnable bottles. It is also more resistant to abrasion and reduces logistical effort, producing 25% of the carbon dioxide emissions of a standard 0.33l returnable bottle.
- Amcor plc · Australia
- Ball Corporation (U.S.)
- Tetra Laval S.A. · Switzerland
- Verallia SA · France
- Vetropack Holding AG · Switzerland
- Crown Holdings, Inc. (U.S.)
- Silgan Containers LLC (U.S.)
- Vidrala Group · Spain
- CCL Container Inc. (U.S.)
- Berry Global Group, Inc. (U.S.)
- Sonoco (U.S.)
- Ardagh Group · Luxembourg
- Mondi Group (U.K.)
- Tetra Pack Group · Switzerland
- O-I Glass, Inc. (U.S.)
Frequently asked questions
The beverage packaging market is expected to reach $221.5 billion by 2032, at a CAGR of 4.9% from 2025–2032.
Cite this report
Meticulous Research. (2024). Beverage Packaging Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRFB - 1041242). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/beverage-packaging-market-5925