AI in Endoscopy Market (2026-2036)
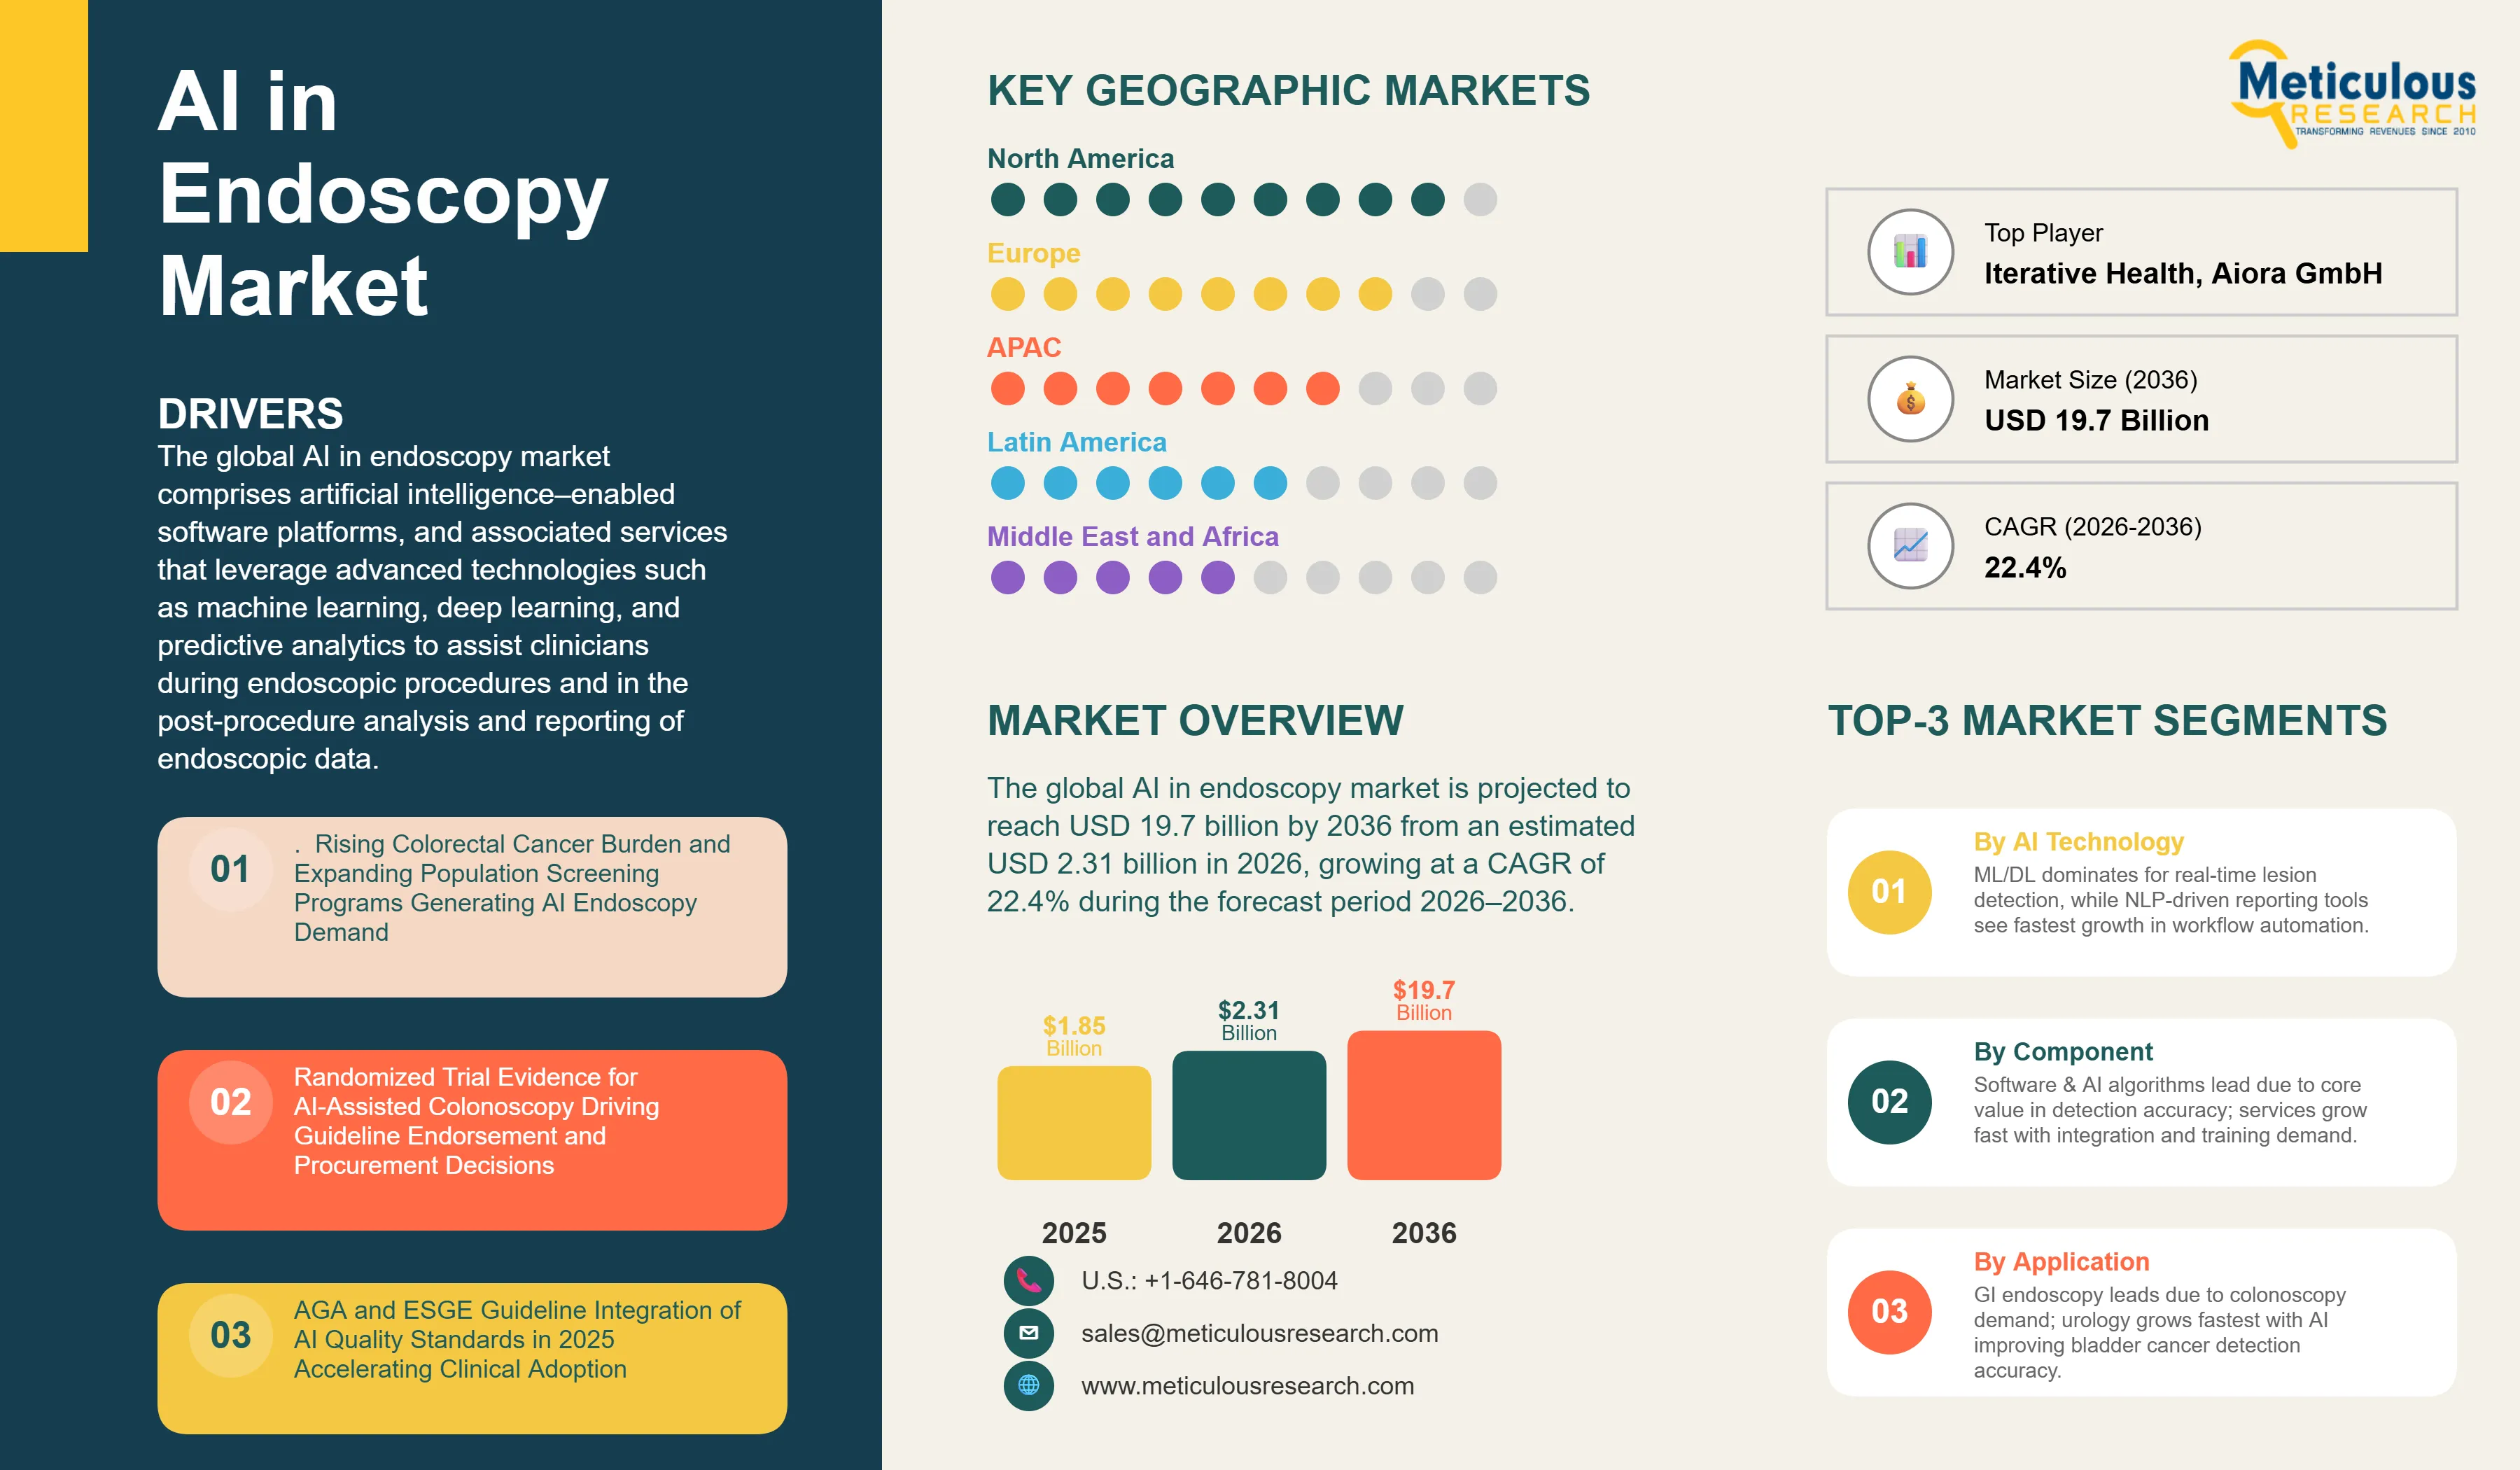
The global AI in endoscopy market was valued at USD 1.85 billion in 2025. The market is projected to reach USD 19.7 billion by 2036 from an estimated USD 2.31 billion in 2026, growing at a CAGR of 22.4% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MR-1938
- Base year
- 2025
- 2025 · BASELINE
- $1.85B
- 2036
- $19.70B
- CAGR 2026–2036
- 22.4%
2025 baseline · 2026–2036 forecast at 22.4% CAGR · hover a bar for the value
Key highlights
The global AI in endoscopy market is projected to reach USD 19.7 billion by 2036.
The market is expected to grow at a CAGR of 22.4% during the forecast period 2026–2036.
The global AI in endoscopy market was valued at USD 1.85 billion in 2025 and is estimated to reach USD 2.31 billion in 2026.
North America is expected to dominate the global AI in endoscopy market in 2026, accounting for around 35-45% of the global revenue.
The largest share of North America in the global AI in endoscopy market is mainly due to its early regulatory authorization of AI-based endoscopy tools, high healthcare expenditure per capita, dense concentration of both established endoscopy device manufacturers and AI health technology innovators, and strong clinical research infrastructure generating the randomized trial evidence base that drives adoption.
Asia Pacific AI in endoscopy market is expected to grow at the fastest CAGR during the forecast period, driven by the highest global burden of gastric and colorectal cancers concentrated in Japan, South Korea, and China; rapidly expanding hospital endoscopy infrastructure across India and Southeast Asia; strong government support for AI-based cancer screening programs in public hospitals; the presence of leading AI endoscopy hardware developers in Japan (Olympus, Fujifilm) who are leveraging high local clinical data volumes to refine algorithms; and China’s status as the global leader in AI-powered digestive endoscopy research.
Gastrointestinal endoscopy, including colonoscopy for colorectal cancer screening and upper GI endoscopy for gastric and esophageal cancer detection, is expected to dominate the global AI in endoscopy market in 2026.
The clinical imperative is well-quantified: colorectal cancer ranks as the third most common cancer globally, with approximately 1.9 million new cases annually per IARC/WHO data. Standard colonoscopy miss rates for adenomas average around 26%, with small flat polyps and sessile serrated lesions at even higher risk. AI-assisted colonoscopy demonstrates the strongest evidence base in this market, with mature randomized controlled trial data showing 40-50% miss rate reductions, supporting guideline endorsements and payer adoption.
Olympus’ strategic transformation from hardware-focused endoscopy to an intelligent integrated care platform is among the most significant competitive developments in AI endoscopy. In September 2025, Olympus launched OLYSENSE CAD/AI, a cloud-based suite in the U.S. and Europe, featuring CADDIE 2 (AI detection/characterization of colorectal polyps including sessile serrated lesions; FDA 510(k) cleared July 2024), CADU (AI detection of Barrett’s esophagus dysplasia), and SMARTIBD (AI assessment of ulcerative colitis). Medtronic launched ColonPRO, next-gen GI Genius software with real-time polyp sizing and procedural insights (CE Mark February 2026), while Fujifilm's CAD EYE integrates with the ELUXEO platform.
The European Society of Gastrointestinal Endoscopy (ESGE) issued a 2025 Position Statement endorsing AI computer-aided detection (CADe) for colonoscopy in colorectal cancer screening/surveillance, supporting quality improvements that accelerate adoption in European centers. Fujifilm’s CAD EYE (FDA 510(k) 2024), Medtronic’s GI Genius (FDA de novo 2021), and Olympus’s CADDIE (FDA 510(k) 2024) have all received FDA clearance, with randomized trials showing adenoma detection rate (ADR) improvements of 9-16 percentage points across systems.
The competitive landscape is characterized by the top 5 companies, Medtronic, Olympus, Fujifilm, HOYA/Pentax Medical, and Intuitive Surgical, accounting for around 60-70% share of the global AI endoscopy market, alongside rapidly growing specialist AI players.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 19.7 Billion |
| Market Size in 2026 | USD 2.31 Billion |
| Market Size in 2025 | USD 1.85 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 22.4% |
| Format | PDF, Excel & Cloud Portal · 280 pages |
| Dominating AI Technology | Machine Learning & Deep Learning (Computer Vision) |
| Fastest Growing AI Technology | Natural Language Processing (NLP) / Automated Reporting |
| Dominating Application | Gastrointestinal (GI) Endoscopy / Colonoscopy |
| Fastest Growing Application | Urological Endoscopy |
| Dominating Component | Software & AI Algorithms (CADe / CADx Platforms) |
| Fastest Growing Component | Services (Implementation, Integration, Training) |
| Dominating Endoscopy Type | Flexible Endoscopy |
| Fastest Growing Endoscopy Type | Capsule Endoscopy |
| Dominating Deployment Model | On-Premise / Embedded AI Systems |
| Fastest Growing Deployment Model | Cloud-Based AI Platforms |
| Dominating End User | Hospitals & Endoscopy Centers |
| Fastest Growing End User | Ambulatory Surgical Centers (ASCs) |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: ai technology, component, application, indication, deployment model, end user.
The global AI in endoscopy market comprises artificial intelligence–enabled software platforms, AI-integrated endoscopic systems, and associated services that leverage advanced technologies such as machine learning, deep learning, computer vision, natural language processing, and predictive analytics to assist clinicians during endoscopic procedures and in the post-procedure analysis and reporting of endoscopic data.
In clinical settings, AI in endoscopy is primarily deployed across two core functional paradigms: computer-aided detection (CADe) and computer-aided diagnosis/characterization (CADx). CADe systems operate in real time during endoscopic procedures, automatically identifying and highlighting suspected lesions within live video streams, thereby enhancing lesion detection rates and directing the endoscopist’s attention to areas of potential clinical significance. In contrast, CADx systems focus on the characterization of detected lesions, providing real-time optical assessments of lesion histology, morphology, and malignancy risk, and thereby supporting clinical decision-making, including resect-or-leave and biopsy-or-leave strategies at the point of care.
Beyond detection and characterization, the market covers a broadening suite of AI-driven workflow optimization solutions. These include automated bowel preparation assessment tools that evaluate and score preparation adequacy to guide procedural readiness; withdrawal time monitoring and mucosal coverage analytics to ensure adherence to quality benchmarks; and automated documentation solutions powered by natural language processing, which convert procedural data into structured, standardized endoscopy reports. Additionally, AI-enabled disease activity scoring systems are increasingly being adopted for conditions such as inflammatory bowel disease, facilitating objective and reproducible clinical assessments.
The scope of the market further extends to AI applications in capsule endoscopy, enabling automated video analysis and lesion flagging for small bowel investigations. Emerging use cases are also being observed in adjacent domains, including bronchoscopy for pulmonary nodule localization and navigation, and cystoscopy for enhanced detection of bladder malignancies.
Key end users of AI in endoscopy solutions include hospitals and large endoscopy centers, which are the primary adopters due to higher procedural volumes and infrastructure readiness; ambulatory surgical centers with established endoscopy programs; and specialized gastroenterology and endoscopy clinics. Collectively, these end users are driving the integration of AI technologies to improve diagnostic accuracy, procedural efficiency, and overall patient outcomes.
Report infographic
Market dynamics
2 factors across 1 forceClinical Evidence & Guideline Adoption Accelerate AI Colonoscopy
A key trend in the AI in endoscopy market is the rapid maturation of the clinical evidence base for AI-assisted colonoscopy, transitioning from early feasibility studies to large, multicenter randomized controlled trials (RCTs) demonstrating statistically significant and clinically meaningful improvements in adenoma detection rates (ADR) in routine practice. This strengthening evidence-base combined with formal endorsements from leading gastroenterology societies is driving the transition of AI-assisted colonoscopy from an early-adopter technology to an emerging clinical quality standard across endoscopy units and healthcare systems.
From a clinical outcomes perspective, multiple longitudinal studies have consistently shown that each 1% increase in ADR is associated with an approximate 3% reduction in the risk of colorectal cancer. Accordingly, the ~8–10 percentage point improvements in ADR reported across leading AI-assisted colonoscopy trials suggest a potentially meaningful reduction in long-term colorectal cancer incidence, reinforcing the clinical and economic value proposition of AI integration.
The translation of this evidence into formal clinical guidance marks a critical inflection point for market adoption. In 2025, the American Gastroenterological Association (AGA) issued formal guidance recognizing the role of computer-aided detection (CADe) systems in improving colonoscopy quality metrics. Similarly, the European Society of Gastrointestinal Endoscopy (ESGE) incorporated AI into its 2025 guidelines for colonoscopy quality assurance. These endorsements from leading professional bodies provide strong validation of clinical utility and are expected to play a pivotal role in accelerating procurement decisions, reimbursement considerations, and broader institutional adoption.
Collectively, the convergence of robust RCT evidence and guideline-level validation is transforming AI-assisted colonoscopy into a clinically endorsed, evidence-backed standard of care, positioning it as a key growth driver in the AI in endoscopy market.
AI Endoscopy Expansion Across Adjacent Applications
While AI-assisted colonoscopy remains the most mature and commercially established application, driven by its proven impact on adenoma detection rates, the AI in endoscopy market is rapidly expanding into adjacent clinical areas, such as upper gastrointestinal (GI) endoscopy, Barrett’s esophagus surveillance, inflammatory bowel disease (IBD) assessment, capsule endoscopy, and emerging urological and pulmonary applications. This expansion is driven by the scalability of deep learning–based computer vision models across anatomical regions and imaging modalities, as well as strategic efforts by endoscopy platform providers to extend AI capabilities across their installed base.
Barrett’s esophagus is one of the most prominent upper GI use cases. As a precancerous condition associated with esophageal adenocarcinoma, it requires high-precision surveillance to detect early dysplasia, which is often subtle and easily missed. AI-based detection tools are being developed to enhance the visualization and identification of dysplastic lesions. For instance, Olympus Corporation has introduced AI-enabled solutions such as CADU within its OLYSENSE platform (integrated via Odin Vision), targeting improved detection in Barrett’s surveillance workflows. Although the evidence base in this segment is still evolving, increasing availability of annotated datasets and ongoing clinical trials are expected to accelerate adoption.
In inflammatory bowel disease, AI applications are focused on standardizing disease activity assessment. Tools such as SMARTIBD (developed by Olympus Corporation) enable automated scoring of mucosal inflammation in ulcerative colitis, addressing longstanding challenges related to inter-observer variability and improving consistency in treatment decision-making.
Beyond GI applications, AI in endoscopy is gaining traction in urology and pulmonology. AI-assisted cystoscopy for bladder cancer detection is emerging as a high-growth segment, driven by the clinical need for improved detection of recurrent tumors, including flat carcinoma in situ lesions that are frequently missed under conventional white-light imaging. Given the high recurrence rates of bladder cancer and the requirement for lifelong surveillance, AI integration offers a strong value proposition in improving diagnostic accuracy and reducing disease burden.
Similarly, in respiratory endoscopy, AI-assisted bronchoscopy is advancing, mainly for navigation and localization of peripheral pulmonary nodules. Platforms such as the Ion system developed by Intuitive Surgical incorporate AI-driven guidance to enhance procedural precision, representing a convergence of robotics and AI within endoscopic interventions.
In addition, capsule endoscopy is witnessing increased AI adoption for automated video analysis and lesion detection in small bowel imaging, significantly reducing physician reading time and improving diagnostic yield.
Collectively, the expansion of AI across these adjacent applications is broadening the total addressable market for AI in endoscopy, enabling vendors to move beyond single-use-case solutions toward integrated, multi-application AI platforms that enhance clinical value, workflow efficiency, and return on investment for healthcare providers.
Table of contents
14 chapters · 167 sections · 280 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By AI Technology | Machine Learning & Deep Learning | — |
| By Component | Software & AI Algorithms | Services |
| By Application | Gastrointestinal Endoscopy | Urological endoscopy |
| By Indication | Colorectal Cancer & Polyp Detection | — |
| By End User | Hospitals & Endoscopy Centers | Ambulatory surgical centers (ASCs), on the other hand |
By AI Technology
- Machine Learning & Deep Learning to Dominate the Global AI in Endoscopy Market
- Machine learning (ML) and deep learning (DL) are expected to account for the largest share of the global AI in endoscopy market, driven by their central role in real-time image and video analysis.
- Deep learning, mainly convolutional neural networks (CNNs), is highly aligned with endoscopic use cases, as it enables high-speed processing of video streams with low latency suitable for real-time procedural guidance.
- These models can be trained on large, annotated datasets from high-volume endoscopy centers, achieving performance levels comparable to expert endoscopists in lesion detection tasks, while also demonstrating the ability to generalize across different endoscope platforms and imaging conditions.
- Solutions such as GI Genius (developed by Cosmo Intelligent Medical Devices and distributed by Medtronic), CADDIE, and CAD EYE by Fujifilm Holdings Corporation are all built on CNN-based frameworks for real-time polyp detection.
- Similarly, the EVIS X1 platform from Olympus Corporation incorporates ML/DL-driven image enhancement and pattern recognition capabilities for lesion characterization, further reinforcing the technological foundation of the market.
- In contrast, natural language processing (NLP) and AI-driven documentation solutions are projected to register the fastest growth rate among technology segments over the forecast period.
- This growth is primarily driven by the increasing need to automate endoscopy reporting workflows, which remain time-intensive and prone to variability.
- NLP-based systems enable automated generation of structured endoscopy reports, extraction of key quality metrics, and seamless integration with electronic medical record (EMR) systems.
By Component
- Software & AI Algorithms to Hold the Largest Share
- Software and AI algorithms are expected to account for the largest share of the overall AI in endoscopy market, indicating the inherently software-centric nature of value creation in this domain.
- The clinical and commercial differentiation of AI endoscopy solutions is primarily determined by algorithm performance, mainly in terms of detection sensitivity, specificity, false-positive rates, and robustness across varying lesion types, sizes, and morphologies, rather than the underlying hardware.
- AI software can be deployed across multiple architectures, including modular integration with existing endoscopy systems (as demonstrated by GI Genius developed by Cosmo Intelligent Medical Devices and distributed by Medtronic), cloud-based platforms accessible via connected endoscopy infrastructure (such as OLYSENSE CAD/AI by Olympus Corporation), and fully embedded solutions within next-generation AI-native endoscopy platforms.
- Cloud and edge-based deployment models are particularly significant, as they lower upfront capital requirements, enable continuous algorithm updates, and facilitate scalable adoption across healthcare institutions.
- However, the services segment is projected to register the fastest compound annual growth rate (CAGR) over the forecast period.
- This growth is driven by the increasing reliance of healthcare providers on specialized vendors for end-to-end implementation, including system integration with legacy endoscopy equipment and electronic medical record (EMR) systems, clinician training, workflow optimization, and ongoing technical support.
By Application
- Gastrointestinal Endoscopy to Dominate the Global AI in Endoscopy Market
- Gastrointestinal endoscopy is expected to account for the dominant application share, driven by the clinical evidence base for AI-assisted colonoscopy and the scale of the global colorectal cancer screening program that generates the procedure volume through which AI endoscopy creates value.
- Urological endoscopy is expected to register the fastest CAGR among application segments, driven by the high recurrence rate of bladder cancer that demands life-long surveillance cystoscopy for affected patients; the well-documented miss rate for flat and small bladder lesions during standard white-light cystoscopy; and the strong clinical logic of applying the proven AI detection paradigm from colonoscopy to the structurally similar surveillance cystoscopy context.
By Indication
- Colorectal Cancer & Polyp Detection to Hold the Largest Share
- Colorectal cancer and polyp detection is expected to account for the dominant indication share, driven by the scale of the global colorectal cancer screening program, the robustness of the randomized controlled trial evidence base including the COLO-DETECT trial, and the AGA’s March 2025 formal guidance on CADe use in colonoscopy.
- Gastric cancer and gastric lesion detection is expected to represent a large and growing indication, particularly in Asia Pacific markets where gastric cancer incidence is 8 to 10-fold higher than in Western countries.
- AI systems trained on large Japanese and South Korean gastric endoscopy datasets are now being deployed commercially and in clinical research programs across the region for early gastric cancer detection and lesion characterization.
By End User
- Hospitals & Endoscopy Centers to Hold the Largest Share
- Hospitals and endoscopy centers are expected to account for the largest share of the AI in endoscopy market, indicating their role as the primary settings for high-volume and high-complexity procedures, including colorectal cancer screening colonoscopies, upper GI endoscopy, and advanced therapeutic interventions.
- These facilities are typically early adopters of advanced imaging and AI-enabled diagnostic technologies, driven by stronger capital budgets, established digital infrastructure, and access to skilled clinical personnel.
- Hospital-based endoscopy programs derive significant value from AI platforms through improved workflow efficiency, enhanced quality benchmarking (e.g., adenoma detection rate monitoring), and clinician training support.
- In addition, procurement decisions at the hospital network or integrated delivery system level often involve multi-site deployments and long-term contracts, making this segment the primary revenue contributor in the market.
- Ambulatory surgical centers (ASCs), on the other hand, are projected to register the fastest compound annual growth rate (CAGR) during the forecast period.
- This growth is driven by the ongoing shift of routine colonoscopy procedures from inpatient hospital settings to lower-cost outpatient environments, supported by favorable reimbursement dynamics and increasing patient preference for minimally invasive, same-day procedures.
- Within ASCs, AI-assisted endoscopy is gaining traction as a tool for quality differentiation.
- The ability to consistently demonstrate high adenoma detection rates and standardized reporting supports physician referral growth and alignment with payer-driven quality programs.
- Furthermore, as professional bodies such as the American Gastroenterological Association (AGA) and the European Society of Gastrointestinal Endoscopy (ESGE) increasingly recognize AI-assisted colonoscopy as a quality-enhancing tool, adoption among ASCs is expected to accelerate.
- Thus, the expansion of AI into outpatient settings, combined with increasing emphasis on measurable quality outcomes, positions ASCs as a key high-growth end-user segment in the AI in endoscopy market.
Geographic analysis
North America
Largest shareNorth America is expected to account for the largest share of the global AI in endoscopy market in 2026. The largest share of this region is mainly attributed to the three key factors. First, regulatory precedence: the U.S. Food and Drug Administration (FDA) granted de novo clearance to GI Genius (developed by Cosmo Intelligent Medical Devices and commercialized by Medtronic) in 2021, establishing the first regulatory pathway for AI-assisted colonoscopy systems, followed by subsequent clearances for additional CADe/CADx solutions, including CADDIE. Second, strong clinical evidence generation, driven by leading academic and clinical institutions such as GI Alliance and Brigham and Women’s Hospital, which have contributed to large-scale trials validating AI efficacy. Third, a dense commercial ecosystem comprising established medtech companies and AI health startups, enabling rapid innovation and deployment. – U.S. – Canada – Mexico
Europe
Europe is the second-largest regional market for AI in endoscopy, with key countries including the U.K., Germany, France, Italy, and the Netherlands. The region benefits from strong clinical validation and early guideline adoption. The U.K., in particular, has played a pivotal role through large-scale randomized controlled trials that have influenced procurement decisions within public healthcare systems. Additionally, the 2025 guidelines issued by the European Society of Gastrointestinal Endoscopy (ESGE) endorsing AI for colonoscopy quality assurance mark a significant milestone, accelerating institutional adoption across EU healthcare systems. On the commercial front, Olympus Corporation has strengthened its position through CE-marked AI solutions (via the Odin Vision platform), offering an integrated suite for detection, characterization, and workflow support. – U.K. – Germany – France – Italy – Netherlands – Rest of Europe
Asia-Pacific
Fastest growthAsia-Pacific AI in endoscopy market is projected to grow at the fastest CAGR during the forecast period, driven by expanding healthcare infrastructure, large patient volumes, and strong government support for AI integration in healthcare. Japan and South Korea are the mature markets, supported by high endoscopy procedure volumes and the presence of leading manufacturers such as Olympus Corporation and Fujifilm Holdings Corporation. China has emerged as a major hub for AI research in digestive endoscopy, supported by significant academic output and policy-level prioritization of AI in healthcare. India is also witnessing increasing adoption, particularly within private hospital networks; for instance, deployments of AI-enabled systems such as CAD EYE by Fujifilm Holdings Corporation highlight the early-stage but accelerating market penetration. Asia Pacific – Japan – China – South Korea – India – Australia – Rest of Asia Pacific
Latin America
Latin America and the Middle East & Africa are expected to witness gradual adoption, primarily concentrated in leading private hospitals and academic medical centers. In Latin America, Brazil, Mexico, and Colombia are emerging as key markets, driven by expanding cancer screening initiatives and improving healthcare infrastructure. – Brazil – Mexico – Rest of Latin America
Middle East & Africa
Meanwhile, in the Middle East, countries such as Saudi Arabia and the UAE are investing in advanced digital health technologies as part of broader healthcare transformation programs, creating opportunities for AI-integrated endoscopy solutions. By Geography (Revenue, USD Billion, 2026–2036) Middle East & Africa – Saudi Arabia – UAE – Israel – South Africa – Rest of Middle East & Africa
Competitive landscape
- Medtronic
- Olympus Corporation
- Fujifilm Holdings Corporation
- HOYA Corporation / Pentax Medical
- Intuitive Surgical
- Boston Scientific Corporation
- Karl Storz
- Iterative Health
- Cosmo Intelligent Medical Devices
- Wision AI Co., Ltd.
- MAGENTIQ EYE Ltd.
- Ambu A/S
- Stryker Corporation
- Aiora GmbH
- Satisfai Health Inc.
- AI Medical Service Inc.
- EndoAid Ltd.
- Phathom Pharmaceuticals
Frequently asked questions
The global AI in endoscopy market is expected to reach USD 19.7 billion by 2036 from an estimated USD 2.31 billion in 2026, at a CAGR of 22.4% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). AI in Endoscopy Market - Global Opportunity Analysis And Industry Forecasts (2026-2036) (Report No. MR-1938). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ai-in-endoscopy-market-6621