Viral Vector Manufacturing Market (2026-2036)
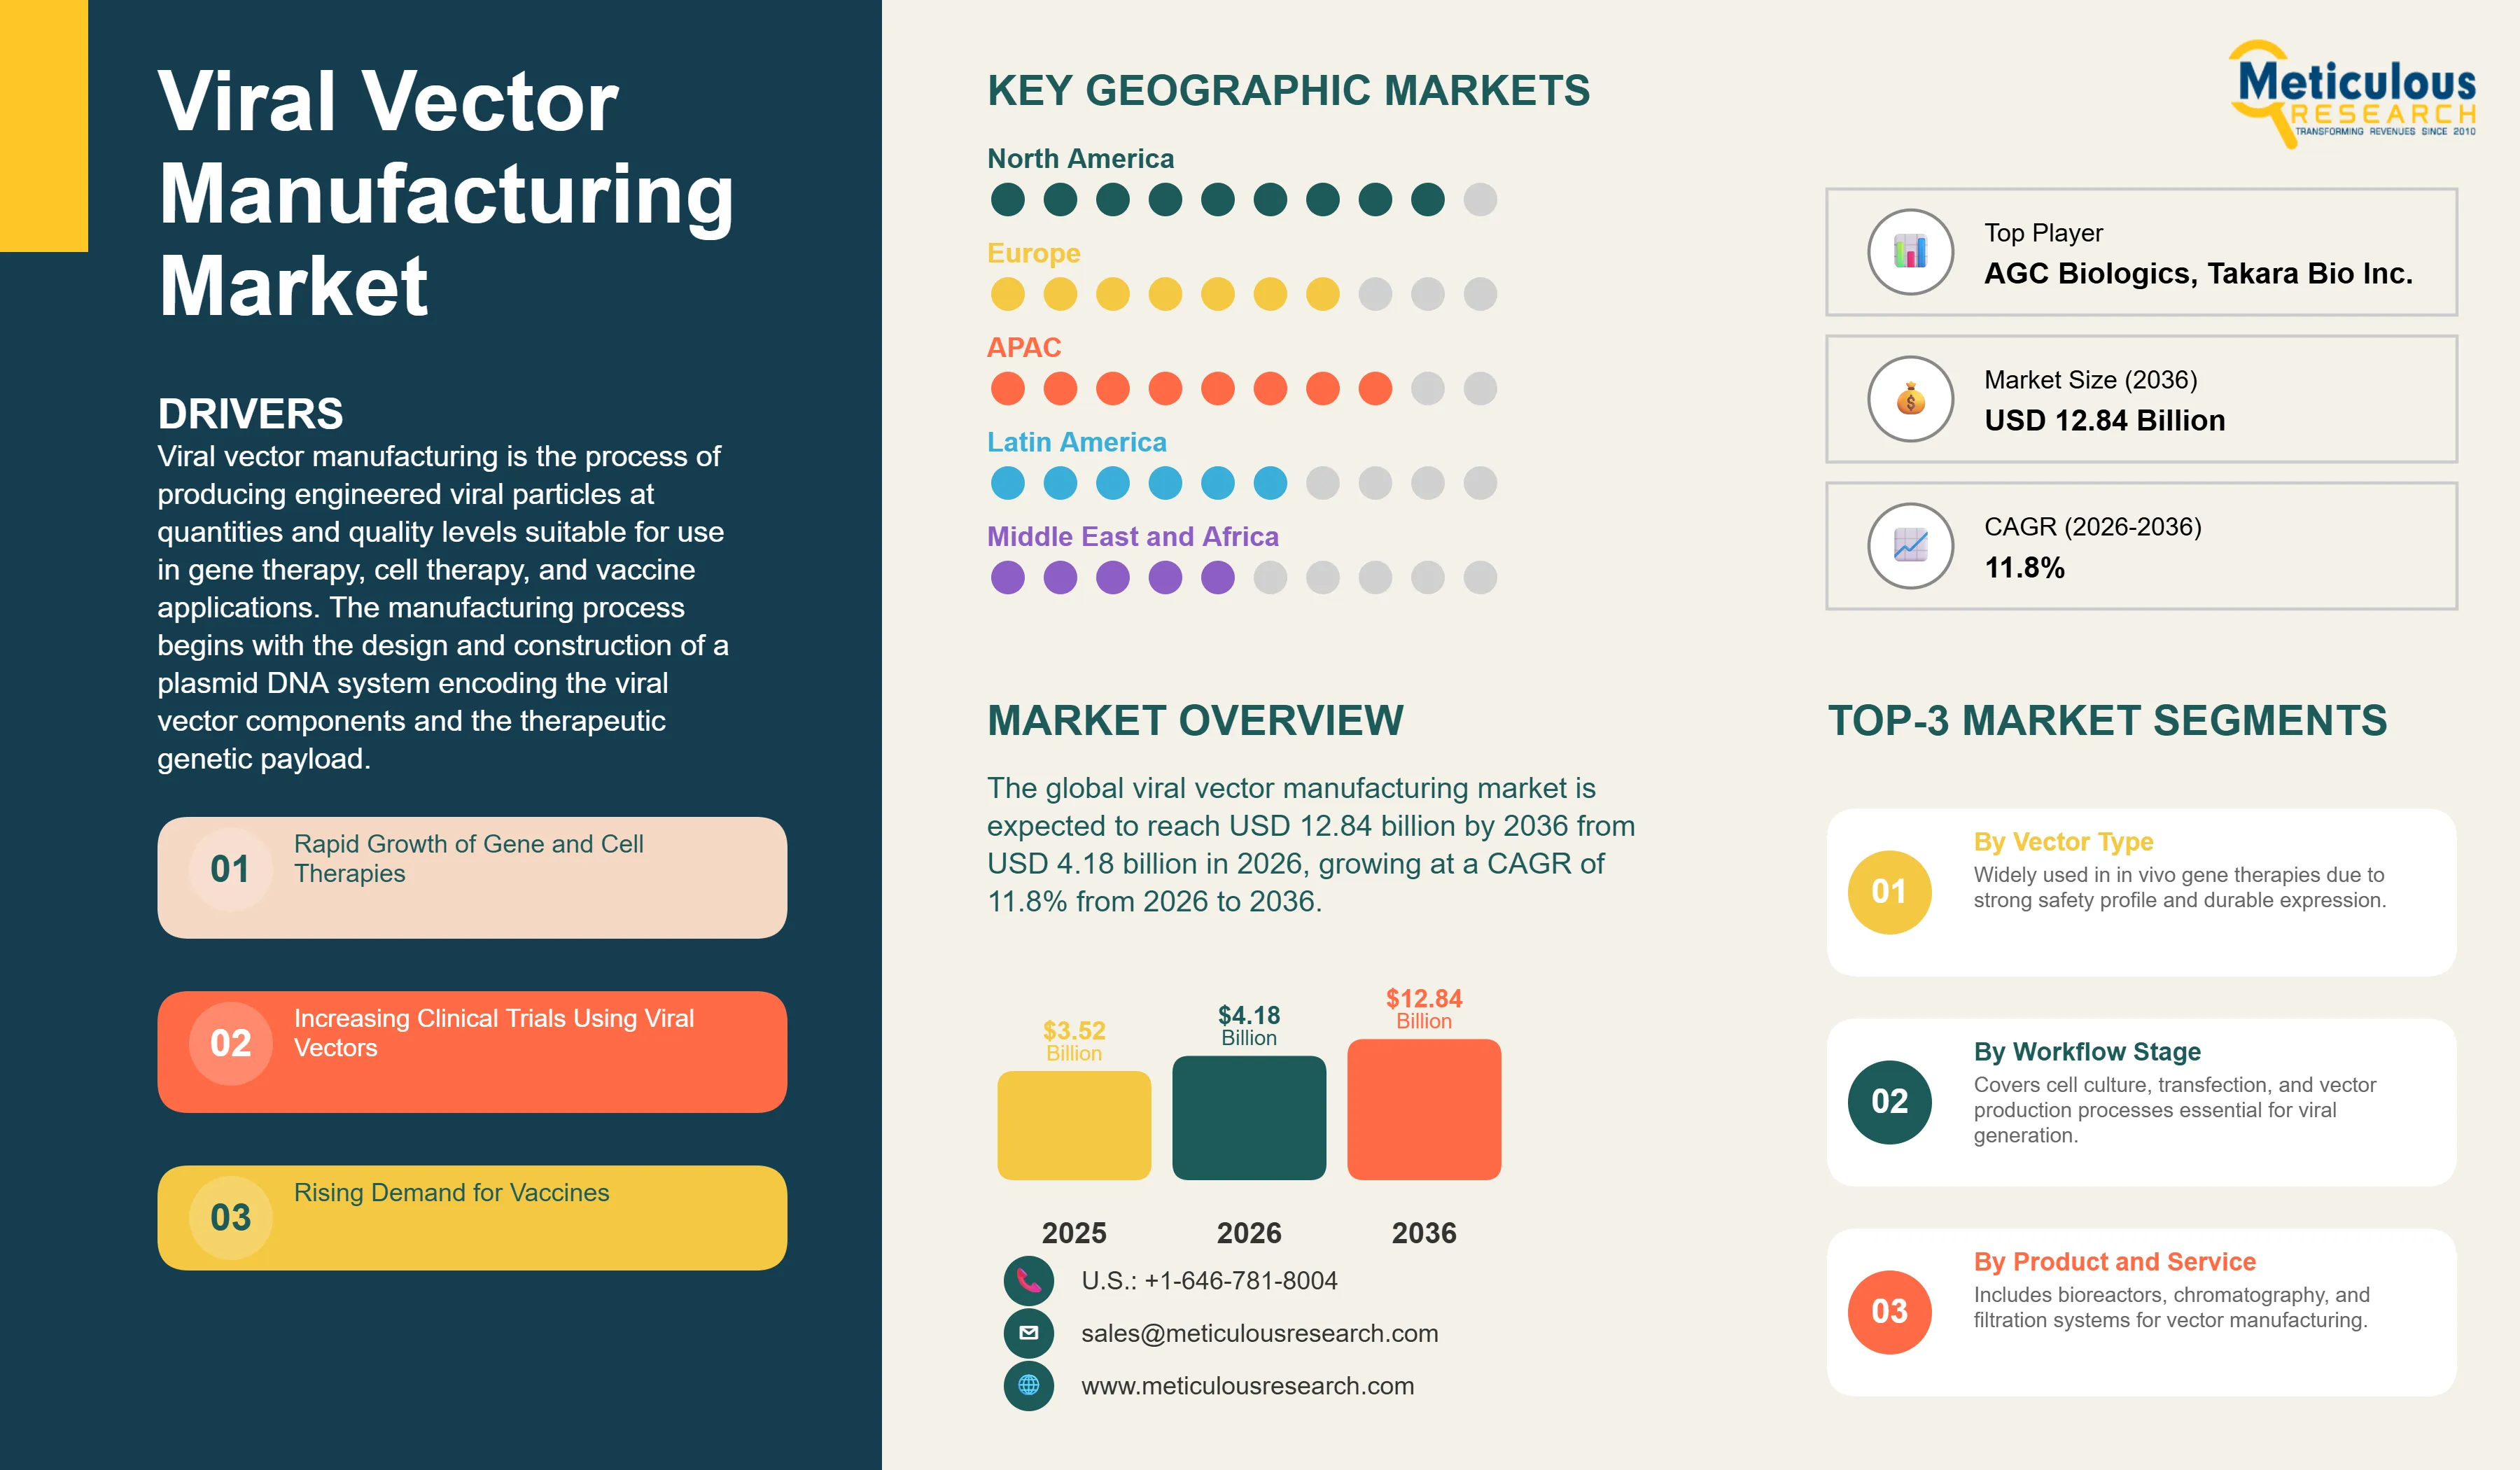
The global viral vector manufacturing market was valued at USD 3.52 billion in 2025. This market is expected to reach USD 12.84 billion by 2036 from USD 4.18 billion in 2026, growing at a CAGR of 11.8% from 2026 to 2036.
- Published
- May 2026
- Pages
- 305
- Format
- PDF + Excel
- Report ID
- MRHC - 1041974
- Base year
- 2025
- 2025 · BASELINE
- $3.52B
- 2036
- $12.84B
- CAGR 2026–2036
- 11.8%
2025 baseline · 2026–2036 forecast at 11.8% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global viral vector manufacturing market is projected to reach USD 12.84 billion by 2036.
The market is expected to grow at a CAGR of 11.8% from 2026 to 2036.
North America is expected to dominate the global market for viral vector manufacturing with the largest market share in 2026, driven by the concentration of leading gene and cell therapy innovator companies in the United States, the presence of major CDMO facilities including Catalent, Lonza, and Thermo Fisher Scientific, and the FDA's active engagement with expedited review pathways including Breakthrough Therapy and Accelerated Approval that are advancing viral vector-based therapies toward commercial launch.
Asia-Pacific is expected to witness the fastest growth during the forecast period, driven by China's rapidly expanding gene therapy clinical trial activity and domestic CDMO capacity development, Singapore's emergence as a regional biomanufacturing hub attracting investments from Lonza, AGC Biologics, and Thermo Fisher Scientific, and Japan's regulatory framework for regenerative medicine providing an accelerated approval pathway that is increasing domestic gene therapy development activity.
By vector type, the adeno-associated virus segment is expected to hold the largest share of the overall viral vector manufacturing market in 2026, as AAV is the most widely used vector for in vivo gene therapy applications and is the vector platform underlying the majority of approved gene therapy products including Zolgensma, Hemgenix, and Roctavian.
By vector type, the lentiviral vectors segment is expected to witness the fastest growth during the forecast period, driven by the rapid expansion of CAR-T cell therapy programs that use lentiviral vectors to engineer patient or donor T cells ex vivo, with multiple commercial CAR-T products including Kymriah, Yescarta, and Carvykti driving growing demand for lentiviral vector manufacturing at commercial scale.
By workflow stage, the upstream processing segment is expected to hold the largest share of the overall viral vector manufacturing market in 2026, as cell culture systems, bioreactors, and transfection reagents used in vector production represent the largest single cost and revenue component of the end-to-end viral vector manufacturing process.
By product and service, the services segment is expected to hold the largest share of the overall viral vector manufacturing market in 2026, reflecting the dominant role of CDMOs in providing contract manufacturing, process development, and analytical services to the majority of gene and cell therapy developers that do not have in-house viral vector manufacturing capability.
By manufacturing scale, the clinical segment is expected to hold the largest share of the overall viral vector manufacturing market in 2026, as the large and growing number of active gene and cell therapy clinical trials generates the majority of current viral vector manufacturing demand across preclinical, Phase I, Phase II, and Phase III production runs.
By application, the gene therapy segment is expected to hold the largest share of the overall viral vector manufacturing market in 2026, as in vivo gene therapy programs using AAV vectors represent the most advanced and commercially active segment of the viral vector-dependent therapeutic pipeline.
By end user, the CDMOs and CMOs segment is expected to hold the largest share of the overall viral vector manufacturing market in 2026, as the majority of gene and cell therapy developers outsource viral vector manufacturing to specialist CDMOs given the high capital cost, technical complexity, and regulatory burden of establishing in-house manufacturing capability.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 12.84 Billion |
| Market Size in 2026 | USD 4.18 Billion |
| Market Size in 2025 | USD 3.52 Billion |
| Market Growth Rate (2026-2036) | CAGR of 11.8% |
| Format | PDF, Excel & Cloud Portal · 305 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Vector Type, Workflow Stage, Product and Service, Manufacturing Scale, Application, End User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: vector type, product and service manufacturing scale, end user.
The growth of this market is driven by the accelerating clinical and commercial advancement of gene therapies and cell therapies that rely on viral vectors as their primary delivery mechanism. A viral vector is a modified virus, stripped of its disease-causing genes and re-engineered to carry therapeutic genetic material into target cells. Manufacturing these vectors at the purity, potency, and scale required for clinical use and commercial supply is one of the most technically demanding processes in biopharmaceutical production, requiring specialized upstream cell culture systems, complex downstream purification and characterization processes, and highly controlled fill and finish operations under strict GMP conditions.
The market has expanded significantly since the first commercial approvals of viral vector-based gene therapies. According to the U.S. Food and Drug Administration, the agency continues to project approvals of approximately 10–20 cell and gene therapy products annually, reflecting the rapid expansion of advanced biologics pipelines. FDA-approved cell and gene therapy products have increased significantly in recent years, with the total number of approved therapies reaching more than 40 products by 2025, spanning CAR-T therapies, gene therapies for rare diseases, and regenerative medicine products.
Key commercial milestones driving manufacturing demand include Novartis's Zolgensma for spinal muscular atrophy (2019), CSL Behring's Hemgenix for hemophilia B (2022), BioMarin's Roctavian for hemophilia A (2022/2023), and Sarepta's Elevidys for Duchenne muscular dystrophy (2023). According to data from ClinicalTrials.gov cited by multiple industry sources, more than 2,000 gene and cell therapy clinical trials were active globally as of 2024, with each program advancing through phases creating compounding upstream demand for GMP-grade viral vector manufacturing capacity.
Viral vector manufacturing is the process of producing engineered viral particles at quantities and quality levels suitable for use in gene therapy, cell therapy, and vaccine applications. The manufacturing process begins with the design and construction of a plasmid DNA system encoding the viral vector components and the therapeutic genetic payload. This genetic material is then introduced into a producer cell line, typically human embryonic kidney 293 cells for adenovirus and AAV production or human fibrosarcoma HT1080 cells for lentiviral vector production, which generates new viral vector particles during upstream culture. The crude viral harvest is then processed through a series of downstream purification steps including clarification, chromatography, filtration, and concentration to remove cellular debris, host cell proteins, empty capsids, and process-related impurities, yielding a purified vector bulk that is formulated and filled into final containers under sterile conditions.
The major viral vector platforms each have distinct manufacturing characteristics that influence the choice of production system, equipment, and process development approach. Adeno-associated viruses are small, non-enveloped viruses that are produced using transient transfection of producer cells with multiple plasmids or using baculovirus-insect cell production systems. AAV manufacturing is characterized by relatively low volumetric yields compared with other biological products, making upstream intensification and downstream recovery efficiency critically important cost drivers. Lentiviral vectors are enveloped retroviruses that require careful handling due to their sensitivity to physical stress during processing, and their production by transient transfection generates a complex mixture of particles that requires sophisticated downstream purification to achieve the purity levels required for clinical use. Adenoviral vectors, including the ChAdOx platform used in the AstraZeneca COVID-19 vaccine, are produced at relatively high titers in adherent or suspension HEK293 cell cultures and benefit from a more established manufacturing process infrastructure developed through decades of adenovirus-based vaccine production.
The competitive landscape of the viral vector manufacturing market is organized around two primary business models. CDMOs including Lonza, Catalent, Fujifilm Diosynth Biotechnologies, Oxford Biomedica, and WuXi AppTec provide contract manufacturing services to gene and cell therapy developers that outsource some or all of their vector manufacturing needs. These CDMOs have invested heavily in dedicated viral vector manufacturing suites with the specialized equipment, validated processes, and qualified personnel required for GMP production. Technology and equipment providers including Thermo Fisher Scientific, Cytiva (Danaher), Sartorius, and Merck KGaA supply the bioreactors, chromatography systems, filtration devices, cell culture media, and analytical kits that both CDMOs and in-house manufacturing operations use across the upstream and downstream workflow. This two-tier structure means that growth in the viral vector manufacturing market benefits both service providers and technology suppliers.
Report infographic
Market dynamics
4 factors across 3 forcesRapid Growth of Gene and Cell Therapies Advancing Through Clinical Development
The primary driver of the viral vector manufacturing market is the rapid expansion of gene and cell therapy pipelines, alongside the progression of existing programs from early-stage research into late-stage clinical development and commercialization. Viral vector-based gene therapies, particularly those using adeno-associated virus (AAV) platforms, have demonstrated durable therapeutic benefits across multiple disease areas, including hemophilia, spinal muscular atrophy, retinal disorders, and neuromuscular conditions. These clinical successes have established strong proof-of-concept and commercial validation, attracting increased investment and accelerating pipeline growth.
As more programs advance through clinical phases, manufacturing requirements scale significantly, creating sustained demand for high-quality viral vectors and associated production capabilities. The AAV segment remains a central contributor to this demand, given its widespread use in gene therapy development. In parallel, chimeric antigen receptor T-cell (CAR-T) therapies, enabled by lentiviral vectors, have further expanded the need for viral vector manufacturing since the commercial introduction of therapies such as Kymriah and Yescarta.
Overall, the increasing number of gene and cell therapy programs, combined with their progression toward commercialization, is creating a structurally expanding demand for viral vector production. Viral vectors remain a foundational technology across both gene and cell therapy modalities, reinforcing their central role in biopharmaceutical manufacturing and long-term market growth.
Table of contents
14 chapters · 165 sections · 305 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Vector Type | Adeno-associated Virus | Lentiviral vectors |
| By Workflow Stage | Upstream Processing | Downstream processing |
| By Product and Service | Services | Consumables and reagents |
| By Manufacturing Scale | Clinical Scale | Commercial production |
| By Application | Gene Therapy | Cell therapy |
| By End User | CDMOs and CMOs | Biopharmaceutical companies |
By Vector Type
- The adeno-associated virus (AAV) segment is expected to account for the largest share of the overall market for viral vector manufacturing.
- AAV is currently the most commercially advanced viral vector platform, supported by multiple approved gene therapies that continue to drive sustained manufacturing demand, as well as a robust pipeline of late-stage programs approaching commercialization.
- Therapies such as Luxturna, Zolgensma, Hemgenix, Roctavian, and Elevidys have established strong clinical and commercial precedents for AAV-based treatments.
- However, AAV manufacturing remains technically challenging, with limitations in production yield and downstream recovery driving ongoing innovation in process optimization.
- In response to growing demand, major CDMOs and biopharmaceutical companies, including Thermo Fisher Scientific, Lonza, Fujifilm Diosynth Biotechnologies, and Catalent, have made significant investments in dedicated AAV manufacturing infrastructure.
- However, the lentiviral vectors segment is expected to witness the fastest growth during the forecast period.
- This growth is primarily driven by the expansion of cell therapy manufacturing, particularly chimeric antigen receptor T-cell (CAR-T) therapies, which rely on lentiviral vectors for genetic modification of patient or donor-derived T cells.
- Commercially approved therapies such as Kymriah, Yescarta, Tecartus, Breyanzi, and Carvykti are generating increasing demand for lentiviral vector supply through patient-specific manufacturing processes.
- In addition, the development of next-generation allogeneic, off-the-shelf cell therapies is creating new requirements for large-scale lentiviral production.
- Together, these trends position lentiviral vectors as the fastest-growing segment within the viral vector manufacturing market.
By Workflow Stage
- The upstream processing segment is expected to account for the largest share of the viral vector manufacturing market.
- Upstream processing includes the core production activities such as cell culture, bioreactor operation, transfection, and the use of specialized media and consumables to generate viral vectors within host cells.
- This stage represents the most resource-intensive portion of the workflow, both in terms of capital equipment and recurring consumables.
- As a result, it is the primary focus of process development efforts, with manufacturers continuously working to improve yield, scalability, and consistency.
- Widely adopted platforms such as single-use bioreactors from Sartorius, Cytiva, and Thermo Fisher Scientific further reinforce the commercial significance of this segment by driving recurring demand for consumables and integrated production systems.
- However, the downstream processing segment is expected to witness the fastest growth during the forecast period.
- Downstream operations, including purification, filtration, and analytical characterization, have historically posed greater technical challenges, particularly for complex vectors such as AAV.
- The need to separate full viral particles from empty capsids and other impurities requires advanced purification strategies that go beyond conventional biopharmaceutical processes.
- Innovations such as high-selectivity affinity chromatography, advanced filtration techniques, and enhanced analytical methods are improving process efficiency and product quality.
- At the same time, increasing regulatory expectations for detailed vector characterization are driving greater investment in downstream capabilities, positioning this segment as a key area of innovation and growth within viral vector manufacturing.
By Product and Service
- The services segment is expected to account for the largest share of the viral vector manufacturing market.
- Contract development and manufacturing organizations (CDMOs) play a central role, as most gene and cell therapy developers lack in-house manufacturing capabilities and depend on external partners for critical production activities.
- These services span the full development lifecycle, including process development, analytical testing, clinical- and commercial-scale GMP manufacturing, and fill-finish operations.
- Beyond manufacturing capacity, CDMOs provide specialized expertise, regulatory experience, and established quality systems, making them essential partners in managing the complexity and risk associated with gene therapy development.
- This value-added offering enables service providers to command a premium over basic production costs.
- However, the consumables and reagents segment is expected to witness the fastest growth during the forecast period.
- As manufacturing volumes increase and more therapies advance toward commercialization, demand for single-use consumables and process reagents continues to scale with production activity.
- Unlike capital equipment, which is utilized across multiple campaigns, consumables must be replaced for each manufacturing run, creating a recurring revenue stream closely tied to output levels.
- Leading suppliers such as Sartorius, Cytiva, Thermo Fisher Scientific, and Merck KGaA have built business models around this recurring demand, particularly through single-use systems that generate ongoing sales of associated bags, filters, and tubing assemblies.
By Manufacturing Scale
- The clinical segment is expected to account for the largest share of the viral vector manufacturing market.
- This is driven by the large and active pipeline of gene and cell therapy programs across early and late-stage clinical trials, all of which rely heavily on viral vectors for development.
- Clinical-stage manufacturing requires full compliance with good manufacturing practice (GMP) standards, even at smaller batch sizes, resulting in high per-unit production costs and significant demand for specialized infrastructure.
- Contract development and manufacturing organizations such as Oxford Biomedica, Cobra Biologics, and Charles River Laboratories play a key role in supporting this segment by providing dedicated clinical-scale manufacturing capabilities and regulatory expertise.
- However, the commercial production segment is expected to witness the fastest growth during the forecast period.
- As more gene and cell therapy programs progress toward regulatory approval, the demand for large-scale manufacturing capacity is increasing rapidly.
- Transitioning from clinical to commercial production requires substantial scale-up of bioreactor volumes and process optimization to meet market demand while maintaining product quality and consistency.
- This shift is particularly significant for widely adopted vector types such as AAV, where manufacturing complexity and yield constraints necessitate further expansion of upstream and downstream capabilities.
- As a result, the commercialization phase is emerging as a major growth driver, supported by ongoing investments in large-scale GMP manufacturing infrastructure and process innovation.
By Application
- The gene therapy segment is expected to account for the largest share of the viral vector manufacturing market.
- In vivo gene therapies, particularly those based on adeno-associated virus (AAV) platforms, represent the most commercially advanced application of viral vectors.
- These therapies have demonstrated strong clinical outcomes across multiple disease areas, including rare genetic and neurological disorders, and continue to drive sustained manufacturing demand.
- Treatments such as Hemgenix and Zolgensma highlight both the clinical success and the manufacturing intensity of this segment, as high per-patient dosing requirements necessitate large-scale production capabilities even for relatively small patient populations.
- As a result, gene therapy remains the most demanding application in terms of manufacturing scale and process optimization.
- However, the cell therapy segment is expected to witness the fastest growth during the forecast period.
- This growth is primarily driven by the expanding adoption of chimeric antigen receptor T-cell (CAR-T) therapies, which rely on viral vectors, typically lentiviral, for genetic modification of immune cells.
- Commercial therapies such as Kymriah and Yescarta continue to generate increasing demand for vector supply through patient-specific manufacturing workflows.
- At the same time, the development of next-generation allogeneic, off-the-shelf cell therapies is expected to shift manufacturing toward larger-scale production models, further accelerating demand for viral vector capacity.
- Together, these trends position cell therapy as the fastest-growing application segment within the viral vector manufacturing market.
By End User
- The CDMOs and CMOs segment is expected to hold the largest share of the viral vector manufacturing market.
- CDMOs are the primary buyers of viral vector manufacturing technology and equipment and the primary providers of manufacturing services to gene and cell therapy developers.
- The capital and expertise requirements for establishing in-house GMP viral vector manufacturing capability are prohibitive for the majority of gene and cell therapy companies, which are typically smaller biotechnology companies or clinical-stage programs within larger pharmaceutical companies that do not yet have commercial-scale gene therapy manufacturing infrastructure.
- CDMOs including Lonza, Catalent, Fujifilm Diosynth, Oxford Biomedica, WuXi AppTec, and AGC Biologics have built the specialized facilities, qualified processes, and regulatory track records that gene therapy developers require, and they serve as the primary manufacturing partners for the majority of viral vector programs in clinical development globally.
- However, the biopharmaceutical companies segment is expected to witness the fastest growth during the forecast period.
- As gene and cell therapy programs approach and achieve commercial approval, the innovator biopharmaceutical companies that own these programs are investing in building or expanding in-house manufacturing capacity to reduce long-term supply chain risk, improve cost of goods at commercial scale, and maintain manufacturing control over products that are central to their therapeutic franchise.
- Novartis has built a dedicated gene therapy manufacturing center in Durham, North Carolina for Zolgensma production.
- BioMarin has invested in its own AAV manufacturing capability for Roctavian.
- Bluebird Bio, Sarepta Therapeutics, and Solid Biosciences are among the companies that have invested in in-house lentiviral and AAV vector manufacturing infrastructure.
- This trend of insourcing at commercial scale will increase the direct equipment and consumable procurement by biopharmaceutical companies relative to CDMOs over the forecast period.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global viral vector manufacturing industry. The United States serves as the primary growth engine, supported by a high concentration of gene and cell therapy development activity and a well-established biopharmaceutical ecosystem. Key innovation hubs such as Boston, San Francisco, Philadelphia, and the Research Triangle host a dense network of biotechnology companies, research institutions, and manufacturing facilities. In addition, major contract development and manufacturing organizations, including Catalent, Lonza, Thermo Fisher Scientific, and WuXi AppTec, have established significant viral vector production capacity in the region, reinforcing North America’s leadership in both clinical and commercial manufacturing.
Asia-Pacific
Fastest growthAsia-Pacific is expected to witness the highest growth rate in the viral vector manufacturing market during the forecast period. This growth is driven by a combination of expanding gene therapy pipelines, supportive regulatory environments, and increasing investment in biomanufacturing infrastructure across the region. Countries such as China, Japan, Singapore, South Korea, and Australia are actively strengthening their capabilities in advanced therapy development and manufacturing, positioning the region as a key emerging hub for viral vector production. China is leading this growth, supported by a rapidly expanding base of gene and cell therapy programs and strong domestic investment in biotechnology innovation. Local CDMOs such as WuXi AppTec and GenScript Biotech are scaling viral vector manufacturing capacity to serve both domestic and international demand. Singapore has emerged as a regional manufacturing hub, attracting investments from global players including Lonza, Thermo Fisher Scientific, and AGC Biologics, supported by strong government initiatives and its reputation for high-quality GMP-compliant manufacturing. Japan’s regulatory framework, including accelerated pathways for regenerative medicine, is encouraging domestic development and driving demand for local manufacturing capabilities, while South Korea is expanding its ecosystem with companies such as Samsung Biologics entering the viral vector space. Australia is also contributing through public sector investments in GMP-grade manufacturing infrastructure.
Competitive landscape
- Thermo Fisher Scientific Inc.
- Danaher Corporation · Cytiva
- Lonza Group AG
- Catalent Inc.
- Samsung Biologics Co. Ltd.
- Fujifilm Diosynth Biotechnologies
- WuXi AppTec Co. Ltd.
- Oxford Biomedica plc
- Sartorius AG
- Merck KGaA
- Charles River Laboratories International Inc.
- AGC Biologics
- Takara Bio Inc.
- GenScript Biotech Corporation
- Cobra Biologics
Frequently asked questions
The global viral vector manufacturing market is expected to grow from USD 4.18 billion in 2026 to USD 12.84 billion by 2036.
Cite this report
Meticulous Research. (2026). Viral Vector Manufacturing Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1041974). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/viral-vector-manufacturing-market-6657