Viral Vaccines Market (2025-2032)
The Viral Vaccines Market was valued at $34.41 billion in 2024. This market is expected to reach $70.53 billion by 2032 from an estimated $37.33 billion in 2025, at a CAGR of 9.5% during the forecast period from 2025 to 2032. Viral Vaccines Market Size & Forecast The growth of this market is driven
- Published
- Jun 2025
- Pages
- 230
- Format
- PDF + Excel
- Report ID
- MRHC - 1041237
- Base year
- 2024
- 2024 · BASELINE
- $34.41B
- 2032
- $70.53B
- CAGR 2025–2032
- 9.5%
2024 baseline · 2025–2032 forecast at 9.5% CAGR · hover a bar for the value
Key highlights
By Form: In 2024, the Liquid Vaccines Segment to Dominate the Viral Vaccines Market
By Vaccine Type: In 2024, the mRNA Vaccines Segment to Dominate the Viral Vaccines Market
By Approach: In 2024, the Preventive Vaccines Segment to Dominate the Viral Vaccines Market
By Indication: In 2024, the Influenza Segment to Dominate the Viral Vaccines Market
By Route of Administration: In 2024, the Intramuscular (IM) Segment to Dominate the Viral Vaccines Market
By Packaging: In 2024, the Vials Segment to Dominate the Viral Vaccines Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 230 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 9.5% |
| Market Size (Value) | USD 70.53 Billion by 2032 |
| Segments Covered | By Form · Liquid Vaccines · Lyophilized Vaccines · By Vaccine Type · mRNA Vaccines · Subunit & Conjugate Vaccines · Live-attenuated Vaccines · Inactivated Vaccines · Viral Vector Vaccines · Toxoid Vaccines · Combination Vaccines · By Route of Administration · Intramuscular (IM) · Subcutaneous (SC) · Oral · Other Routes of Administration · (Other routes of administration include nasal) · By Approach · Preventive Vaccines · Therapeutic Vaccines · By Indication · Influenza · Human Papilloma Virus (HPV) · Rotavirus · Poliomyelitis (Polio) · Hepatitis · Cancer · Other Indications · (Other indications include varicella, herpes zoster vaccines, chlorella, severe acute respiratory syndrome, and rabies diseases) · By Packaging · Vials · Prefilled Syringes |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, Switzerland, Ireland, Denmark, Belgium, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Rest of Asia-Pacific), Latin America (Brazil, Mexico, Rest of Latin America), and Middle East & Africa |
| Key Companies | Pfizer Inc. (U.S.), GlaxoSmithKline plc (U.K.), AstraZeneca plc (U.K.), CSL Limited (Australia), Merck & Co., Inc. (U.S.), Sanofi (France), Sinovac Biotech Ltd. (China), Moderna, Inc. (U.S.), Valneva SE (France), Dynavax Technologies Corporation (U.S.), EMERGENT BIOSOLUTIONS INC. (U.S.), Johnson & Johnson (U.S.), Bharat Biotech Ltd. (India), and Serum Institute of India Pvt. Ltd. (India) |
Report overview
Segments covered: form, route of administration, approach, indication, packaging. Regions: North America, Europe, Asia-Pacific, Latin America.
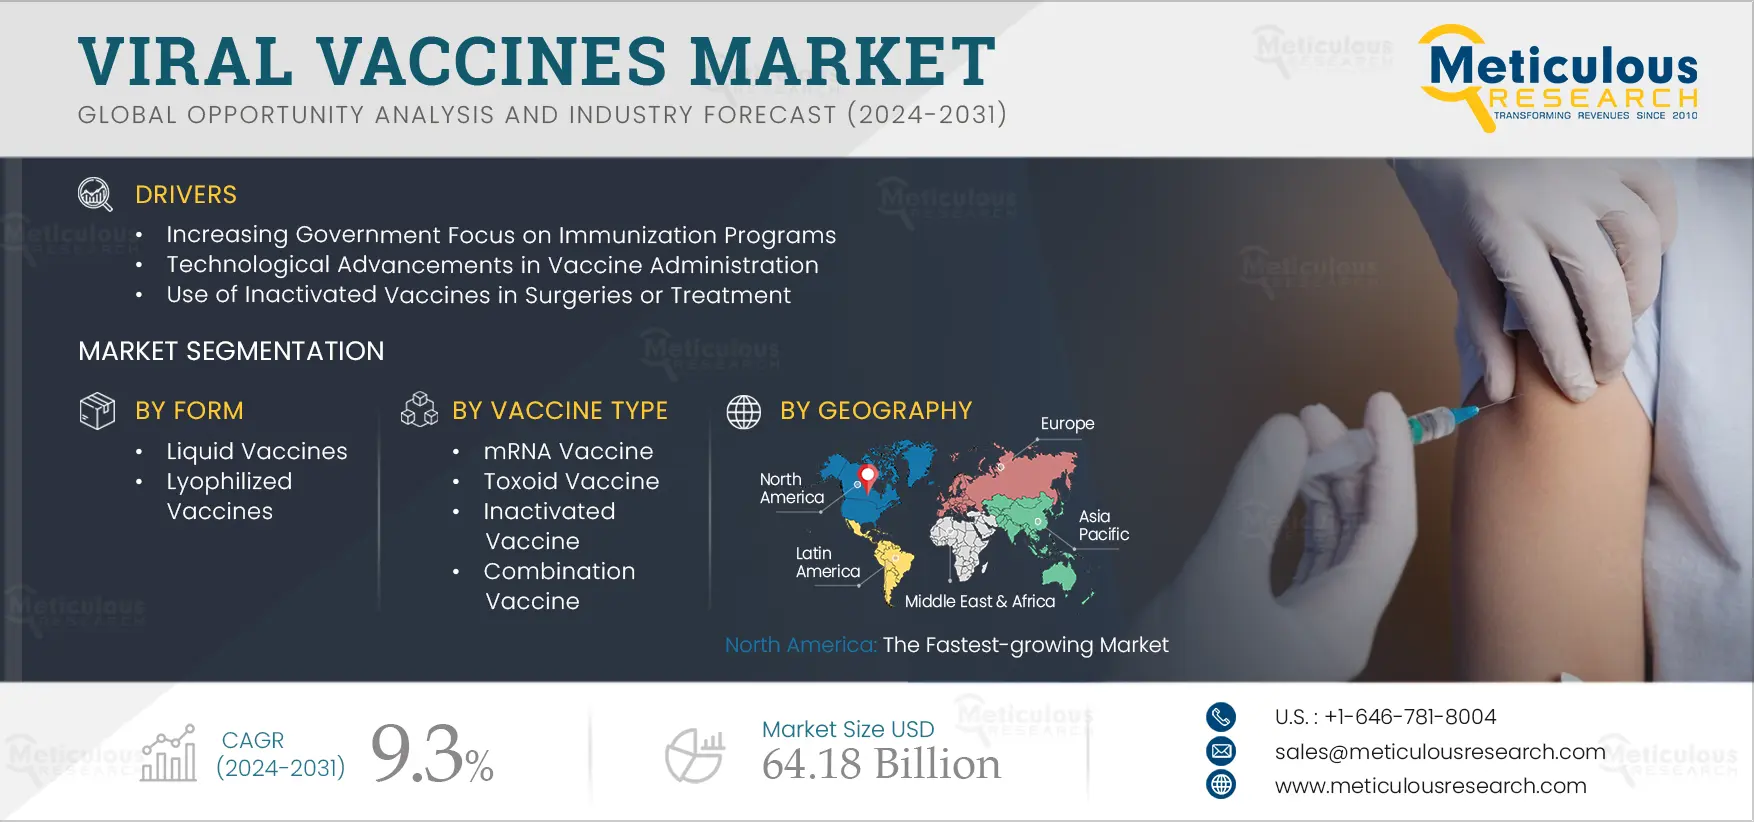
The growth of this market is driven by the increasing government focus on immunization programs, technological advances in vaccine administration, and the use of inactivated vaccines in surgeries and treatments. However, the high costs of vaccine development and the long timelines of vaccine manufacturing restrain the growth of this market.
Furthermore, the growing focus on therapeutic vaccines, this increasing use of adjuvants in vaccines, growth prospects in emerging markets, and the development of highly stable and energy-efficient ultra-low-temperature freezers are expected to generate growth opportunities for market stakeholders. However, product recalls and inadequate access to vaccines are major challenges impacting the market’s growth.
Report infographic
Market dynamics
5 factors across 3 forcesTechnological Advancements in Vaccine Administration
Vaccine technology has evolved significantly during the last decade, profoundly changing the future of vaccine development. The introduction of genetic engineering has fuelled many advances in vaccine development programs, leading to new products. Various virus vaccines that use the attenuated form of the virus have been developed through these methods. Also, new technologies enable the faster detection of viruses and allow for concentration levels to be kept high enough to generate an immune response.
Recent vaccine technologies are largely driven by the need to accelerate response times against emerging threats and make vaccines available for quick deployment. The increasing need to develop vaccines against difficult targets and improve delivery systems for maximum potency is also the focus of innovation in the vaccine industry. The development of synthetic vaccine candidates, genomic analysis of disease progression and vaccine response, structure-based antigen design, and nanoparticle delivery systems are a few of the technological advancements in vaccine delivery. Therefore, technological advancements are expected to drive the emergence of new and more effective vaccines for various new indications, fuelling the growth of the viral vaccines market.
Growing Focus on Therapeutic Vaccines
Historically, vaccines have been used primarily to prevent diseases, but a new category known as therapeutic vaccines has recently emerged. Therapeutic vaccines are designed to treat diseases by inducing or enhancing the body's immune response. Unlike preventive vaccines, which aim to prevent disease before it occurs, therapeutic vaccines target patients who are already affected by the disease, helping to treat or manage the condition. Since the success of the first therapeutic vaccine post-2010, key players in the vaccine industry have increasingly focused on developing therapeutic vaccines for various conditions, particularly cancers. For instance, as of May 2024, Pfizer Inc. (U.S.) has 17 vaccines in its pipeline, targeting diseases and infections such as influenza, hepatitis, Lyme disease, invasive group B streptococcus, and respiratory syncytial virus (RSV), among others.
Although therapeutic vaccines currently represent a small market—mainly limited to vaccines for skin, prostate, and bladder cancers, as well as a few for pollen allergies—this market is expected to expand significantly in the future. With growth projections outpacing those for preventive vaccines, therapeutic vaccines offer opportunities for manufacturers in the coming years.
Table of contents
15 chapters · 122 sections · 230 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Form | Liquid Vaccines | — |
| By Vaccine Type | MRNA Vaccines | — |
| By Approach | Preventive Vaccines | Therapeutic vaccines |
| By Indication | Influenza | — |
| By Route of Administration | Intramuscular (IM) | — |
| By Packaging | Vials | — |
By Form
- The Liquid Vaccines Segment to Dominate the Viral Vaccines Market
- The liquid vaccines segment is expected to account for the larger share of 78.9% of the viral vaccines market.
- Liquid viral vaccines are formulations containing live or weakened viruses, which serve as the primary component to induce an immune response in the body.
- These vaccines are typically administered via injection.
- The large share of this segment is attributed to factors such as ease of administration, reduced risk of errors, decreased wastage, improved patient experience, lower production costs, and enhanced stability.
- For instance, Bharat Biotech Ltd. (India), a manufacturer of vaccines and bio-therapeutics, offers a live attenuated rotavirus vaccine in its product portfolio.
- This liquid frozen vaccine contains the live rotavirus 116E strain and is used to prevent rotavirus gastroenteritis.
By Vaccine Type
- The mRNA Vaccines Segment to Dominate the Viral Vaccines Market
- The mRNA vaccines segment is expected to account for the largest share of 63.1% of the viral vaccines market. mRNA vaccines are a type of genetic vaccine that uses messenger RNA (mRNA) to instruct cells to produce proteins that trigger an immune response against a specific virus.
- The large market share of this segment is attributed to several factors, including the superior stability of mRNA vaccines compared to other types, an effective delivery system, and the use of lipid nanoparticles, which help deliver the mRNA to cells by facilitating its attachment to the cell membrane.
By Approach
- The preventive vaccines segment is expected to account for the larger share of the viral vaccines market.
- Preventive (or prophylactic) vaccines are designed to prevent diseases before exposure to pathogens.
- These vaccines stimulate the immune system to recognize and combat infectious agents, helping reduce the incidence and severity of diseases.
- The large market share of this segment is driven by factors such as the increasing prevalence of chronic and infectious diseases, rising public awareness about immunization, growing immunization programs, the induction of herd immunity, and the prevention of disease outbreaks.
- For instance, in April 2024, the Pan American Health Organization (PAHO) launched the 22nd edition of Vaccination Week in the Americas (VWA) 2024, which included updates on vaccination coverage and efforts to return to pre-pandemic vaccination levels.
- However, the therapeutic vaccines segment is expected to grow at the fastest CAGR during the forecast period.
- Therapeutic vaccines are administered to individuals already suffering from infections or diseases to help reduce symptoms and modify the course of the disease.
- These vaccines are primarily used to treat certain types of cancer.
- The growth of this segment is driven by factors such as the introduction of antiviral immunity to alter disease progression, high specificity and safety, low susceptibility to side effects, and cost-effectiveness.
By Indication
- The Influenza Segment to Dominate the Viral Vaccines Market
- The influenza segment is expected to account for the largest share of 40% of the market.
- The large market share of this segment is attributed to factors such as increased awareness about the importance of influenza vaccination, growing government initiatives for influenza vaccination, and the rising number of clinical trials focused on influenza vaccines.
By Route of Administration
- The intramuscular (IM) segment is expected to account for the largest share of 89.5% of the viral vaccines market.
- Intramuscular injections are administered into muscle tissue below the dermis and subcutaneous tissue.
- Intramuscular injections are administered into muscle tissue beneath the dermis and subcutaneous layers and are typically given at two routinely recommended sites.
- The large market share of this segment is attributed to factors such as its ability to produce the desired immune response, its safety and tolerability, and its use for most inactivated vaccines.
- In May 2023, Merck & Co., Inc. (U.S.) received approval from the U.S. Food and Drug Administration (FDA) for the intramuscular administration of its MMRV vaccine family, including M-M-RII (Measles, Mumps, and Rubella Virus Vaccine Live), VARIVAX (Varicella Virus Vaccine Live), and ProQuad (Measles, Mumps, Rubella, and Varicella Virus Vaccine Live).
By Packaging
- The Vials Segment to Dominate the Viral Vaccines Market
- The vials segment is expected to account for a larger share of 93.2% of the viral vaccines market.
- Vials are small containers, typically made of plastic or glass, used to store liquid medications or powders.
- The large market share of this segment is driven by factors such as the protective environment vials provide, which helps maintain the stability and efficacy of vaccines by shielding them from moisture, light, and contamination.
- Vials also allow for visual inspection of contents before administration and feature tamper-proof packaging to prevent unauthorized access or tampering.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 45.6% of the viral vaccines market, followed by Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America’s large market share is attributed to several factors, including the presence of leading manufacturers, significant investments in R&D, strong government and regulatory support, a rising number of infections, the availability of healthcare professionals to administer vaccines, and expanding immunization programs. For instance, in March 2021, Sanofi S.A. (Italy) announced a USD 925 million investment to expand its vaccine manufacturing operations in Toronto, Canada. This investment aims to boost the supply of Sanofi’s FLUZONE High-Dose Quadrivalent influenza vaccine, enhancing its antigen and filling capacity. The new facility will also serve as an international production and distribution hub for Sanofi's high-dose seasonal influenza vaccine. By Geography: In 2024, North America to Dominate the Viral Vaccines Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest CAGR of 10. 2% during the forecast period. This growth is driven by factors such as the rising emergence of infectious diseases, a large patient population, increasing public awareness of vaccination, and strong governmental support for immunization. For example, in October 2023, Singapore’s Health Sciences Authority (HSA) approved the updated Spikevax vaccine from Moderna, Inc. (U.S.) for COVID-19 prevention in individuals aged 6 months and older. Additionally, in March 2022, the Government of Thailand, in collaboration with the Pediatric Infectious Disease Society of Thailand (PIDST), launched an expanded immunization program (EPI) that now includes vaccines for BCG, HB, DTwP, Hib, OPV, Rota, MMR, Live JE, Influenza, and HPV for children.
Competitive landscape
- March 2024
Cadila Pharmaceuticals (India) launched the Cadiflu Tetra vaccine that was approved by the Drugs Controller General of India (DCGI) to be used in adults and children for protection against the Influenza virus.
- November 2023
Valneva SE (France) received approval for its single-dose live attenuated IXCHIQ vaccine to prevent the disease caused by the chikungunya virus (CHIKV) in individuals aged 18 years and older.
- May 2023
The U.S. Food and Drug Administration (FDA) approved GlaxoSmithKline plc’s (U.K.) Arexvy, which is a respiratory syncytial virus (RSV) vaccine for use in the U.S. This is a preventive vaccine used for the prevention of lower respiratory tract diseases caused by RSV in individuals aged 60 years and above.
- May 2023
The U.S FDA approved ABRYSVO, Pfizer, Inc.’s (U.S.) vaccine for the prevention of RSV in older adults.
- Pfizer Inc. (U.S.)
- GlaxoSmithKline plc (U.K.)
- AstraZeneca plc (U.K.)
- CSL Limited · Australia
- Merck & Co., Inc. (U.S.)
- Sanofi · France
- Sinovac Biotech Ltd. · China
- Moderna, Inc. (U.S.)
- Valneva SE · France
- Dynavax Technologies Corporation (U.S.)
- EMERGENT BIOSOLUTIONS INC. (U.S.)
- Johnson & Johnson (U.S.)
- Bharat Biotech Ltd. · India
- Serum Institute of India Pvt. Ltd. · India
Frequently asked questions
This market study covers the market sizes & forecasts of the viral vaccines market based on form, vaccine type, route of administration, indication, application, packaging, and geography. This market study also provides the value analysis of various segments and subsegments of the global viral vaccines market at the regional & country levels.
Cite this report
Meticulous Research. (2025). Viral Vaccines Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041237). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/viral-vaccines-market-5920