Vertebral Compression Fracture (VCF) Devices Market (2026-2036)
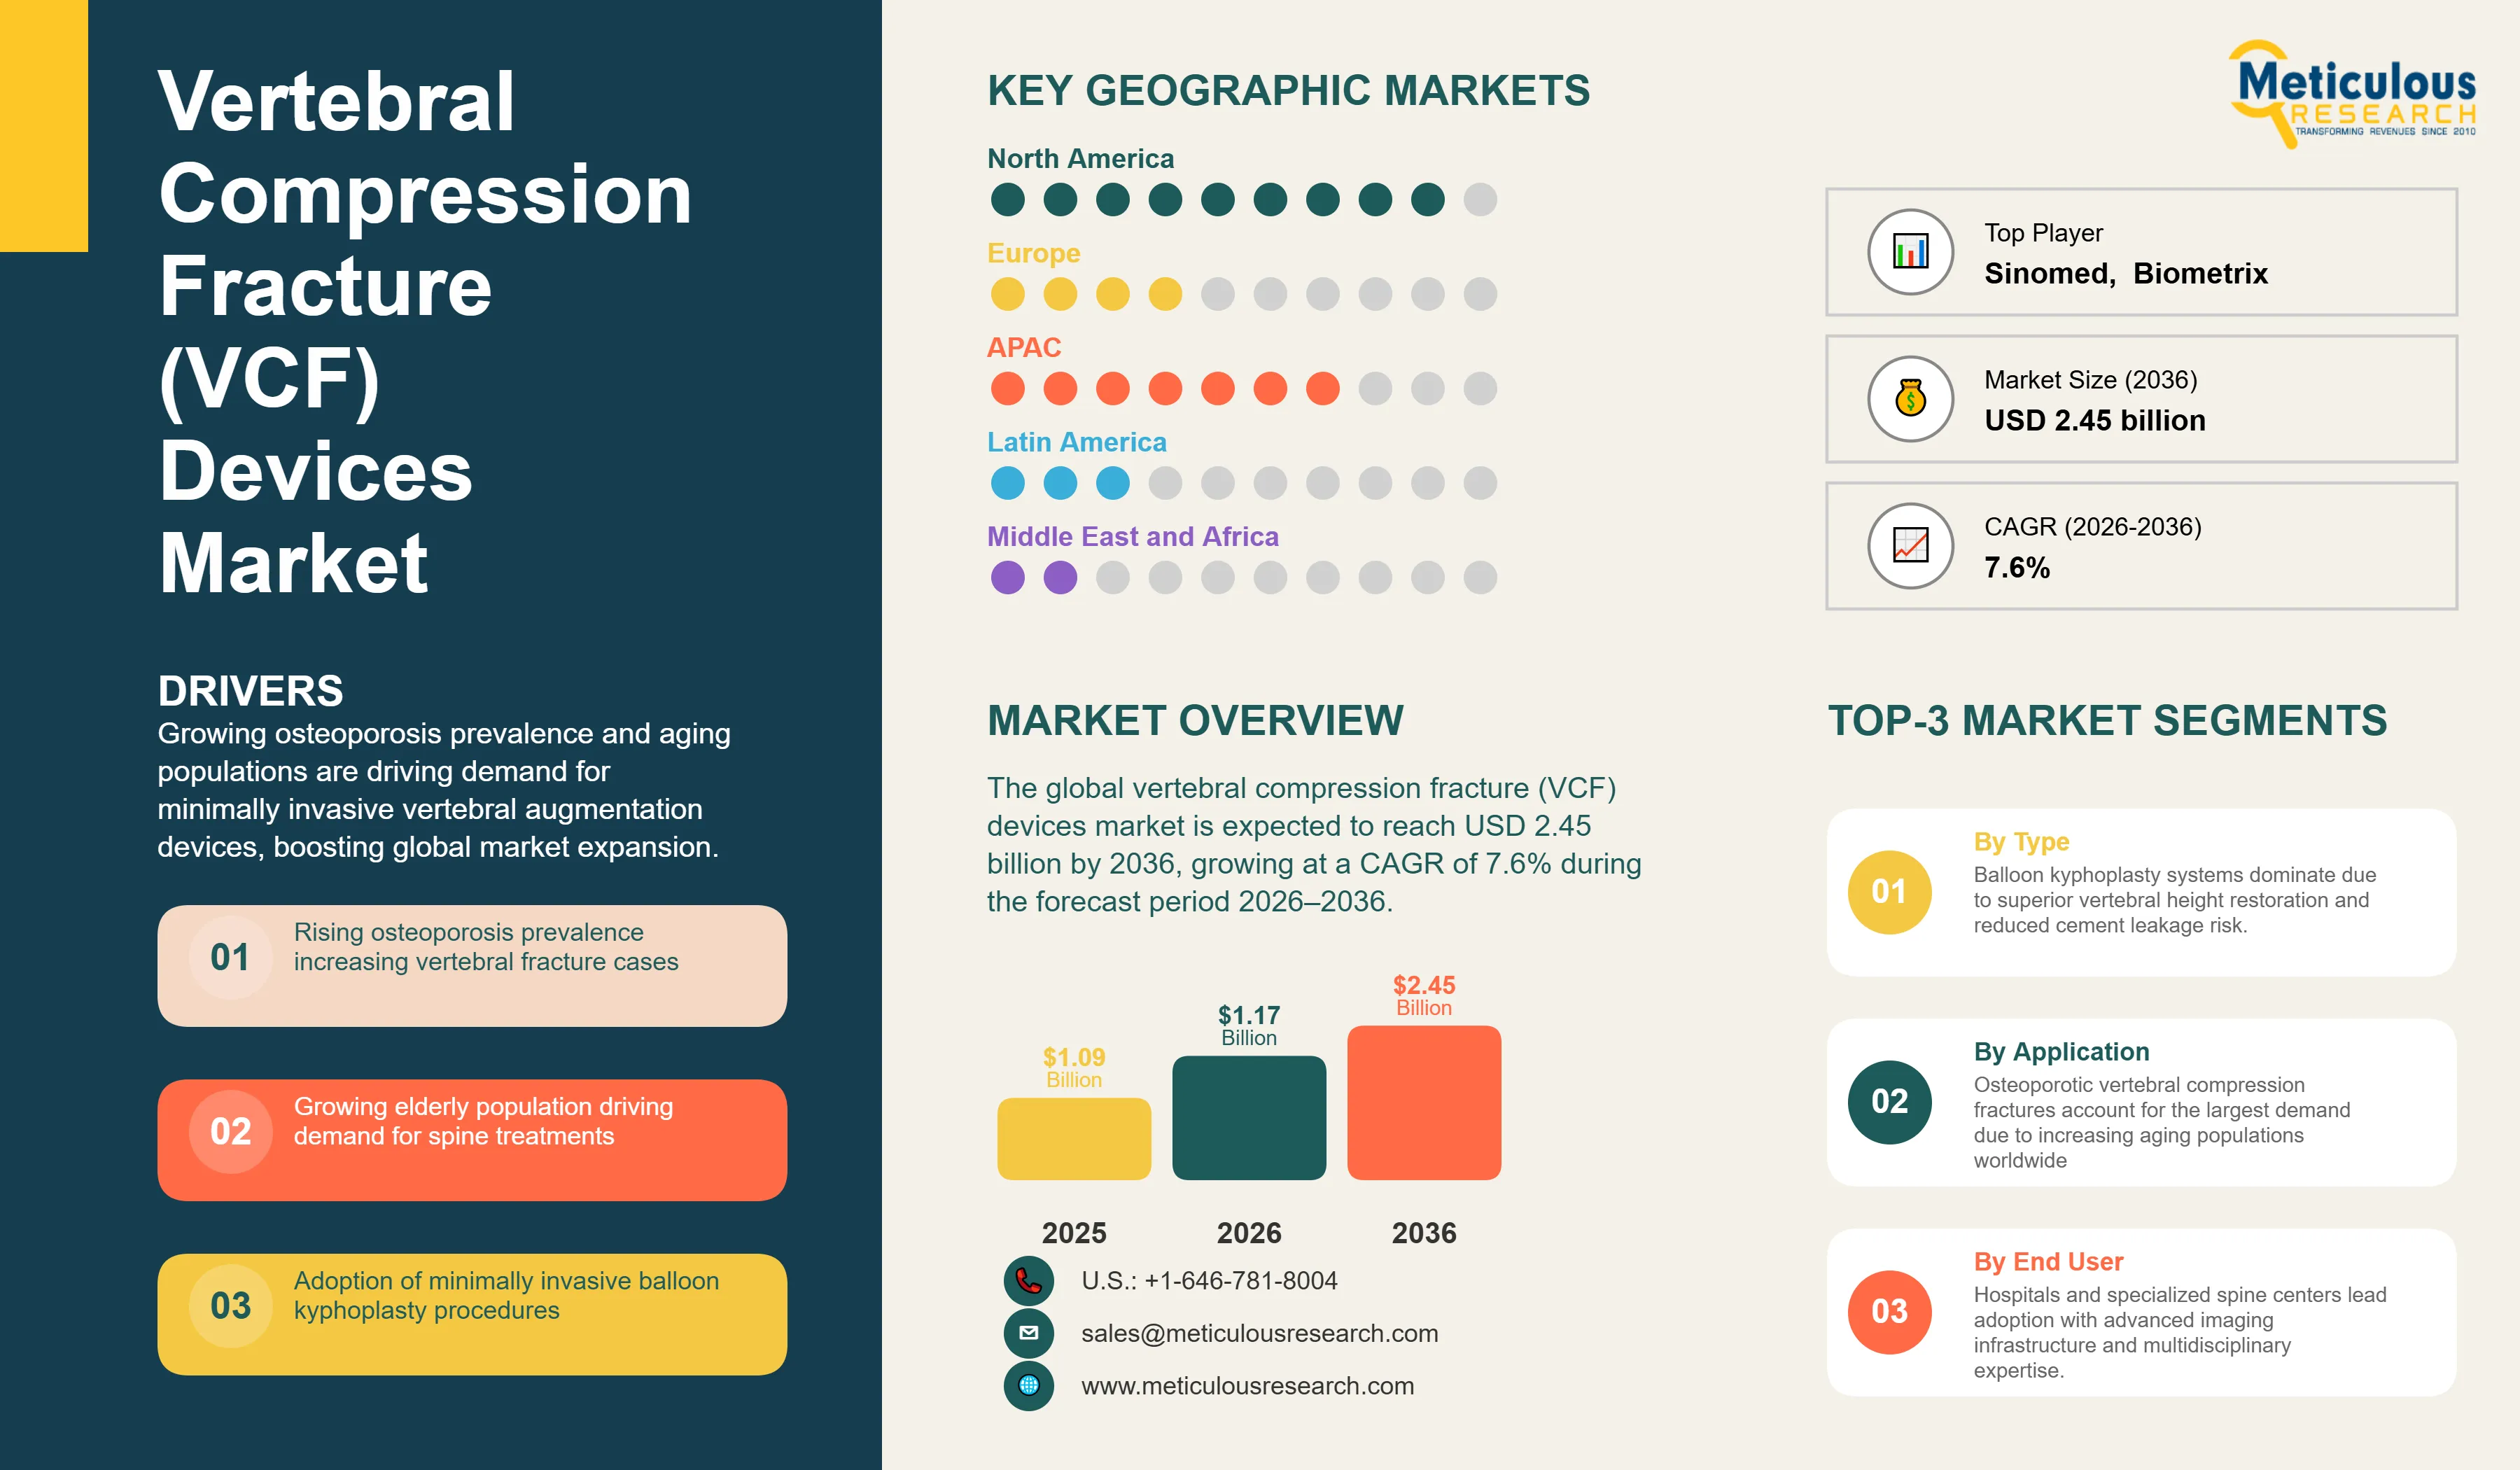
The global vertebral compression fracture (VCF) devices market was valued at USD 1.09 in 2025. This market is estimated to be USD 1.17 billion in 2026 and is expected to reach USD 2.45 billion by 2036, growing at a CAGR of 7.6% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 277
- Format
- PDF + Excel
- Report ID
- MRHC - 1042086
- Base year
- 2025
- 2026 · ESTIMATED
- $1.17B
- 2036
- $2.45B
- CAGR 2026–2036
- 7.6%
2025 baseline · 2026–2036 forecast at 7.6% CAGR · hover a bar for the value
Key highlights
The global vertebral compression fracture (VCF) devices market is projected to reach USD 2.45 billion by 2036, growing at a CAGR of 7.6% during the forecast period 2026–2036.
North America is expected to dominate the global market in 2026, driven by high osteoporosis prevalence, advanced spine surgery infrastructure, and robust reimbursement frameworks.
Asia-Pacific is projected to witness the fastest growth, fueled by a rapidly aging population, increasing healthcare expenditures, and expanding orthopedic care networks.
By product type, the balloon kyphoplasty segment is expected to hold the largest share in 2026, supported by its clinical superiority in height restoration and safety.
By product type, the balloon kyphoplasty systems segment is projected to register the highest CAGR, driven by continuous innovations in balloon materials and high-viscosity cements.
By end user, the hospitals & specialized spine centers segment is expected to hold the largest share in 2026, due to the availability of advanced fluoroscopic imaging and multidisciplinary teams.
By end user, the ambulatory surgical centers (ASCs) segment is projected to be the fastest-growing, driven by the migration of minimally invasive spine procedures to outpatient settings.
Key players operating in the global market include Medtronic plc, Stryker Corporation, Merit Medical Systems, Inc., Johnson & Johnson (DePuy Synthes), and Globus Medical, Inc.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 1.17 billion |
| Market Size (2036) | USD 2.45 billion |
| CAGR (2026–2036) | 7.6% |
| Format | PDF, Excel & Cloud Portal · 277 pages |
| Segments Covered | By Product Type · By End User |
| Key Companies | Medtronic plc, Stryker Corporation, Merit Medical Systems, Inc., Johnson & Johnson (DePuy Synthes), Globus Medical, Inc., Zimmer Biomet Holdings, Inc., Izi Medical Products, Argon Medical Devices, Inc., SpineWave, Inc., Alphatec Holdings, Inc., Joimax GmbH, Ulrich GmbH & Co. KG, Biometrix, G-21 S.r.l, Tecres S.p.A, Sinomed, Shanghai Kinetic Medical Co., Ltd., Lepu Medical Technology (Beijing) Co., Ltd., B. Braun Melsungen AG, Boston Scientific Corporation |
Report overview
Segments covered: product type, end user.
The global vertebral compression fracture (VCF) devices market is at the forefront of a clinical paradigm shift, driven by the increasing global burden of osteoporosis and the rapid advancement of minimally invasive spine augmentation technologies. As a leading cause of debilitating back pain and spinal deformity in the elderly, VCFs demand rapid, effective stabilization to restore mobility and quality of life. The market is primarily fueled by the growing adoption of balloon kyphoplasty and vertebroplasty, which offer immediate pain relief and mechanical stabilization of the fractured vertebral body. Clinical guidelines from the North American Spine Society (NASS), the International Society for the Advancement of Spine Surgery (ISASS), and the World Health Organization (WHO) increasingly emphasize the importance of early intervention to prevent secondary complications such as respiratory compromise and functional decline. The market is also witnessing a significant shift toward the integration of high-viscosity cements and specialized balloon materials that minimize the risk of cement leakage and enhance procedural safety. Furthermore, the migration of these procedures to specialized ambulatory surgical centers (ASCs) is optimizing healthcare delivery and improving patient access to outpatient-based spine care. As the industry focuses on precision height restoration and personalized spine stabilization, the development of integrated, percutaneous delivery systems is expected to further drive market growth, ensuring sustained expansion through 2036.
Report infographic
Market dynamics
8 factors across 4 forcesEscalating Global Prevalence of Osteoporosis and the Increasing Incidence of Fragility Fractures
A major driver for the market is the rising global incidence of osteoporosis, which remains a silent epidemic affecting millions of elderly individuals worldwide. According to the International Osteoporosis Foundation, approximately 500 million people worldwide are affected by osteoporosis, and an estimated 8.9 million osteoporotic fractures occur each year—equivalent to one fracture every 3 seconds. Vertebral compression fractures (VCFs) represent one of the most common osteoporotic fragility fractures, with incidence increasing sharply among older adults. Furthermore, the United Nations projects that the global population aged 65 years and older will reach nearly 1.6 billion by 2050, significantly expanding the at-risk population. Government initiatives to improve geriatric health screening and growing awareness of the consequences of untreated vertebral fractures are increasing diagnosis and treatment rates. This sustained rise in osteoporotic fractures continues to drive demand for vertebral augmentation devices and associated surgical systems.
Technological Shift toward Balloon Kyphoplasty for Superior Clinical Outcomes and Height Restoration
The market is significantly driven by the clinical shift toward balloon kyphoplasty over traditional vertebroplasty. Kyphoplasty offers the unique advantage of restoring vertebral body height and correcting kyphotic deformity by creating a void before cement injection. This controlled delivery significantly reduces the risk of cement extravasation, which is a critical safety concern in spinal augmentation. The ability to provide immediate pain relief and mechanical stabilization with minimal patient trauma is making kyphoplasty the preferred choice for most osteoporotic fractures. Continuous innovation in balloon hardware, including the development of specialized materials for higher inflation pressures and better anatomical conformability, is further accelerating its adoption across clinical settings.
Table of contents
11 chapters · 102 sections · 277 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Balloon kyphoplasty | Balloon kyphoplasty systems |
| By End User | Hospitals & specialized spine centers | Ambulatory surgical centers (ASCs) |
By Product Type
- The balloon kyphoplasty segment is expected to hold the largest share of the global vertebral compression fracture (VCF) devices market in 2026.
- This leadership is substantiated by its superior clinical outcomes in restoring vertebral body height and correcting kyphotic deformity compared to traditional vertebroplasty.
- Additionally, this segment is projected to register the highest CAGR during the forecast period.
- The continuous innovation in balloon materials for higher inflation pressures and the increasing clinical preference for its enhanced safety profile, particularly in reducing cement leakage, are driving its rapid and sustained growth.
By End User
- The hospitals & specialized spine centers segment is expected to hold the largest share in 2026, as these facilities provide a full continuum of care and house advanced fluoroscopic imaging systems necessary for complex spine augmentation.
- However, the ambulatory surgical centers (ASCs) segment is projected to register the highest CAGR during the forecast period.
- The ongoing shift toward outpatient-based, minimally invasive spine care and the development of specialized, compact VCF kits that are optimized for ASC workflows are significantly accelerating adoption in this segment.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global vertebral compression fracture (VCF) devices market in 2026, holding a market share of approximately 40-45%. This leading position is attributed to its advanced healthcare infrastructure, high prevalence of osteoporosis among the aging population, and robust reimbursement frameworks (CMS and private insurers). The region has a high adoption rate of minimally invasive spine technologies and a well-established network of specialized spine centers. Data from the National Institutes of Health (NIH) and the American Academy of Orthopaedic Surgeons (AAOS) indicate a consistent and high demand for diagnostic and treatment procedures, with over 2 million osteoporotic fractures occurring annually in the U.S. alone. Largest Share: North America
Asia-Pacific
Fastest growthThe Asia-Pacific region is projected to witness the fastest growth in the global vertebral compression fracture (VCF) devices market, with a CAGR of 9.8% during the forecast period. This rapid expansion is driven by the rapidly aging population in countries like China and Japan, increasing healthcare expenditures, and the expansion of specialized orthopedic care. Government initiatives to improve geriatric health and the rising awareness of spine augmentation procedures are significantly accelerating market adoption. According to the World Health Organization (WHO) and regional geriatric societies, the number of individuals aged 60 and above in the APAC region is expected to double by 2050, creating a massive patient pool for osteoporosis-related fracture management. Fastest Growing: Asia-Pacific
Competitive landscape
The global vertebral compression fracture (VCF) devices market is characterized by intense competition between established medical technology giants and specialized orthopedic firms. Competition is primarily focused on enhancing the procedural safety and mechanical stability of spine augmentation and improving the patient experience through minimally invasive percutaneous techniques. Key players are investing heavily in R&D to develop next-generation balloon kyphoplasty systems and advanced high-viscosity cements to capture the growing specialized and outpatient markets. Strategic developments often involve acquisitions of innovative spine technology firms and partnerships with leading specialized spine centers to validate new surgical protocols. Furthermore, there is a growing focus on providing integrated digital solutions that combine robotic-assisted guidance with precise cement delivery. Manufacturers are also increasingly focusing on comprehensive clinical training programs and robust supply chain management to ensure the successful implementation and consistent availability of their technologies in diverse healthcare settings, which is critical for maintaining market leadership in this rapidly evolving spine care field.
- Medtronic plc
- Stryker Corporation
- Merit Medical Systems, Inc.
- Johnson & Johnson (DePuy Synthes)
- Globus Medical, Inc.
- Zimmer Biomet Holdings, Inc.
- Izi Medical Products
- Argon Medical Devices, Inc.
- SpineWave, Inc.
- Alphatec Holdings, Inc.
- Joimax GmbH
- Ulrich GmbH & Co. KG
- Biometrix
- G-21 S.r.l
- Tecres S.p.A
- Sinomed
- Shanghai Kinetic Medical Co., Ltd.
- Lepu Medical Technology (Beijing) Co., Ltd.
- B. Braun Melsungen AG
- Boston Scientific Corporation
Frequently asked questions
The global market is estimated at USD 1.17 billion in 2026, with a projected growth to USD 2.45 billion by 2036, at a CAGR of 7.6%.
Cite this report
Meticulous Research. (2026). Vertebral Compression Fracture (VCF) Devices Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042086). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/vertebral-compression-fracture-devices-market-6770