Vegan Collagen Market (2026-2036)
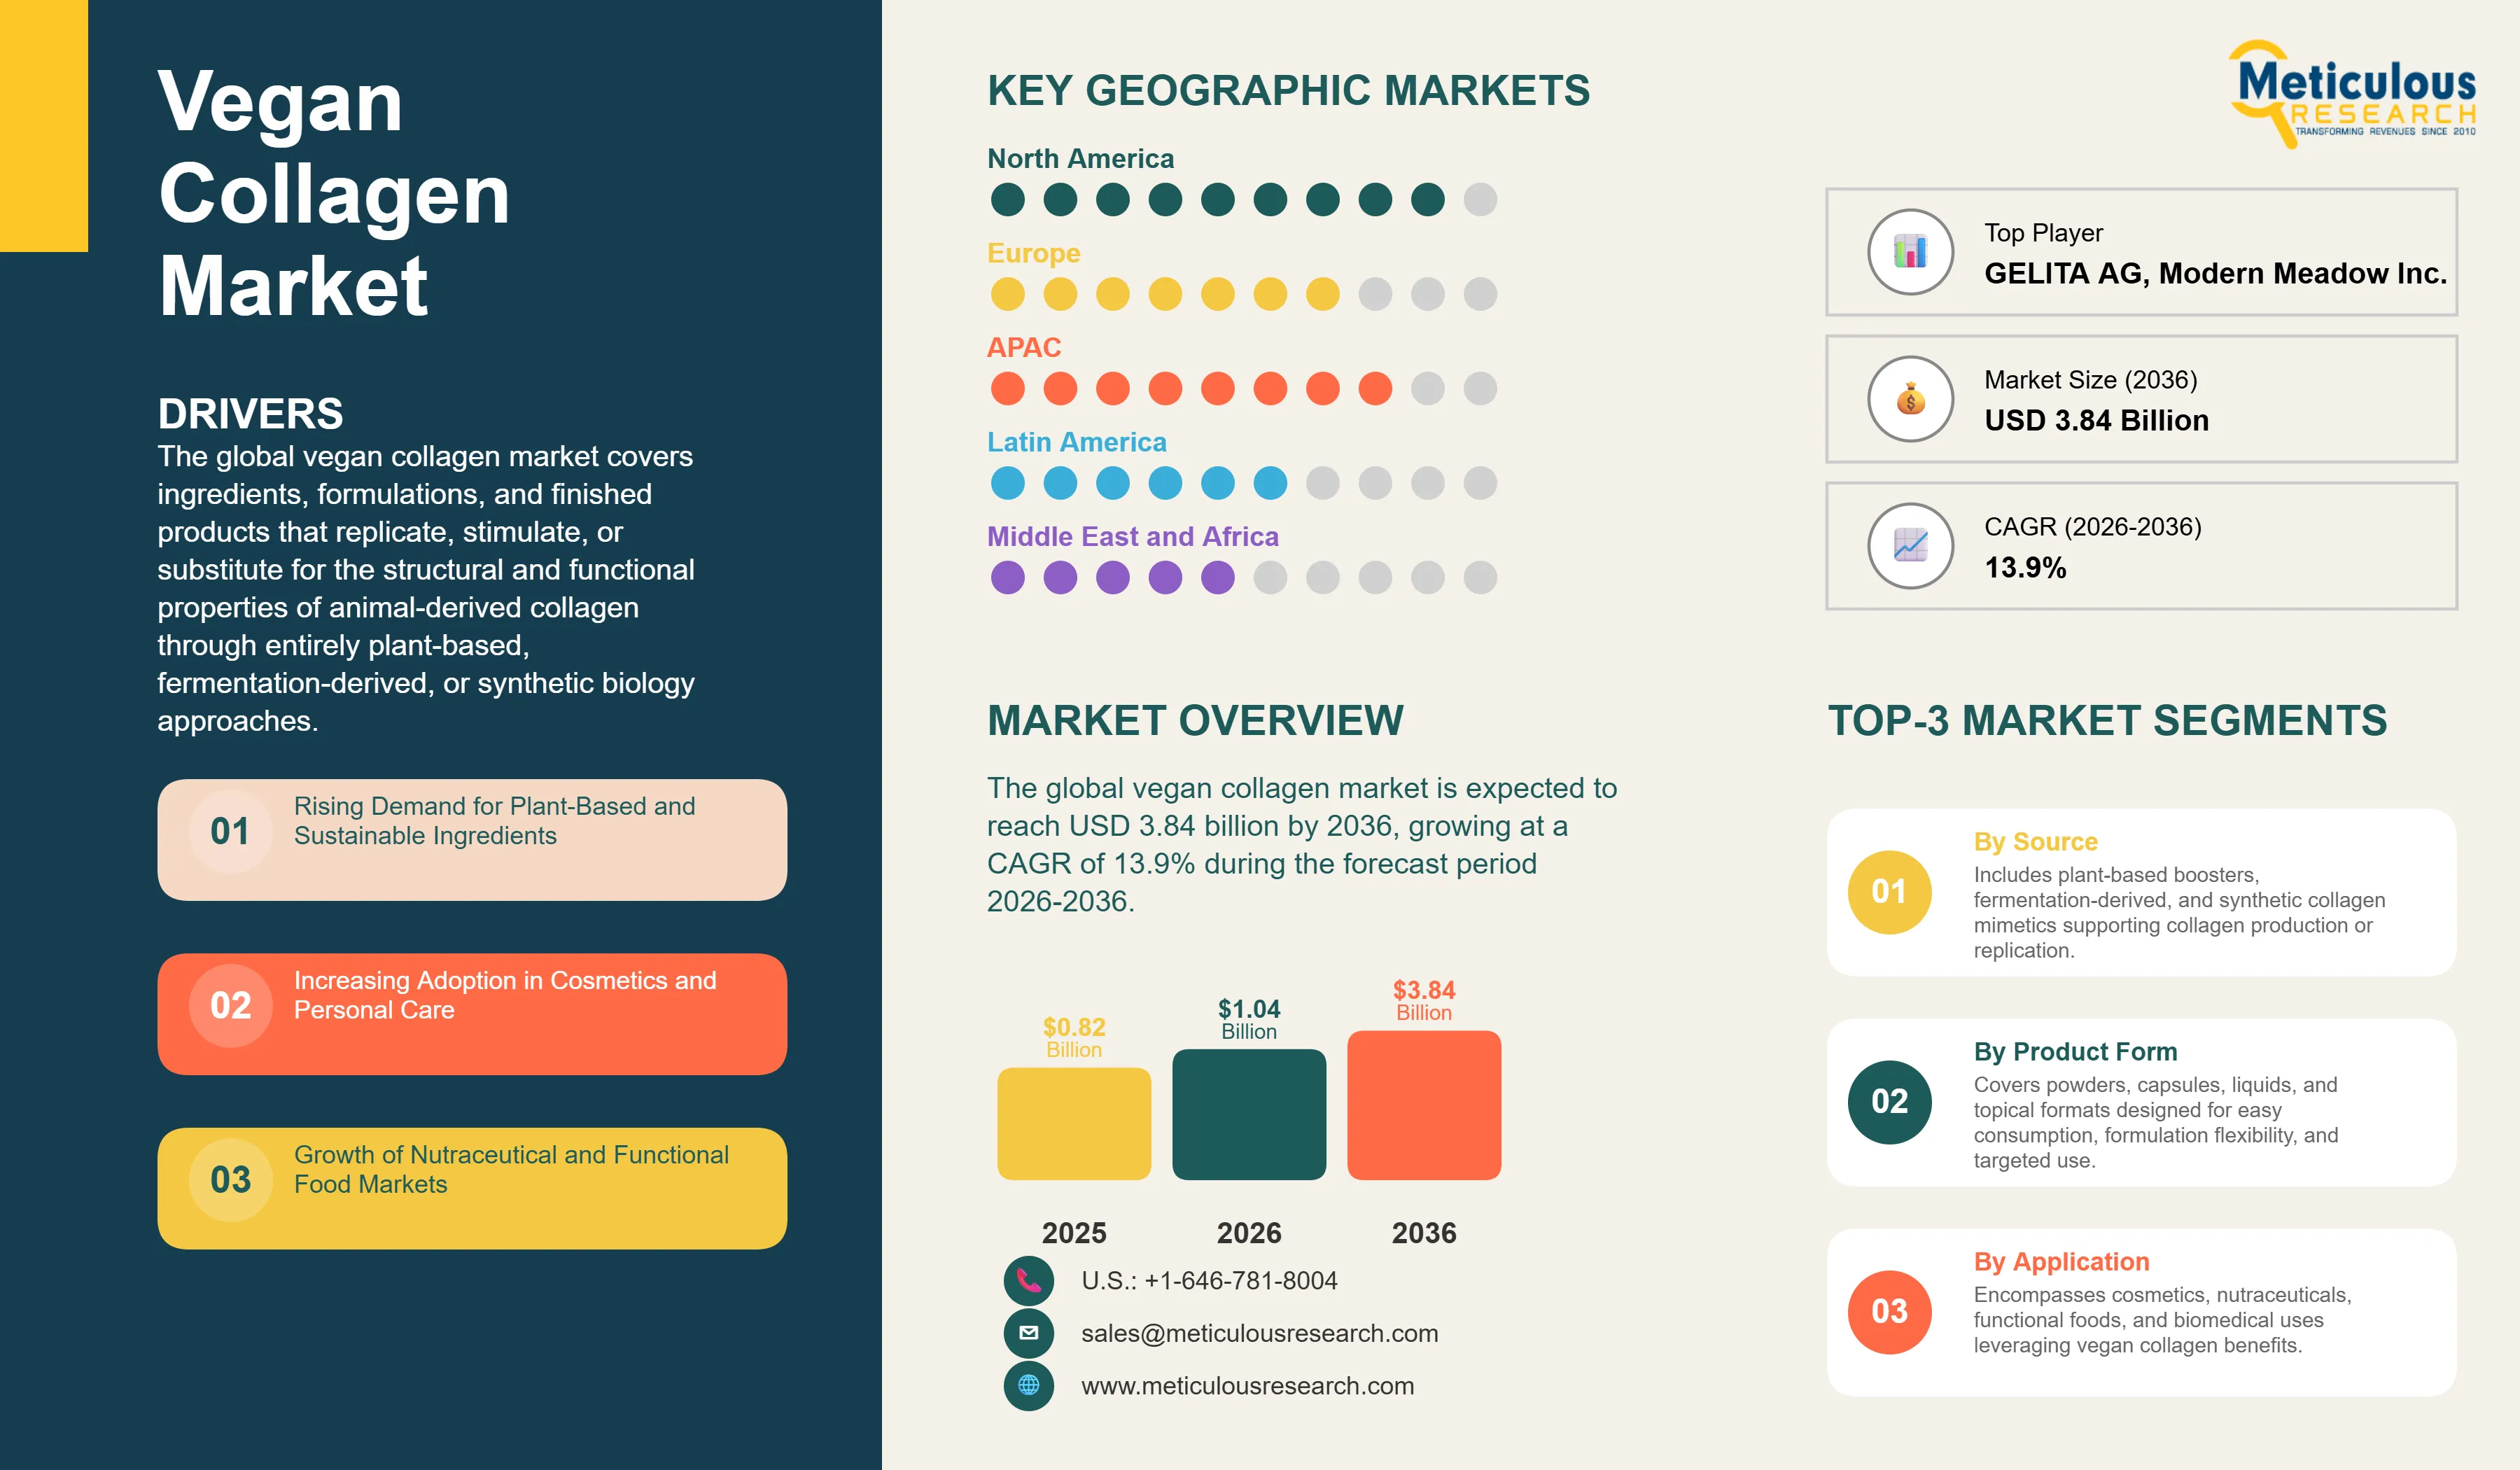
The global vegan collagen market was valued at USD 0.82 billion in 2025. This market is expected to reach USD 3.84 billion by 2036 from an estimated USD 1.04 billion in 2026, growing at a CAGR of 13.9% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 268
- Format
- PDF + Excel
- Report ID
- MRFB - 1041904
- Base year
- 2025
- 2025 · BASELINE
- $820.0M
- 2036
- $3.84B
- CAGR 2026–2036
- 13.9%
2025 baseline · 2026–2036 forecast at 13.9% CAGR · hover a bar for the value
Key highlights
The global vegan collagen market is projected to reach USD 3.84 billion by 2036.
The market is expected to grow at a CAGR of 13.9% during the forecast period 2026-2036.
The global vegan collagen market was valued at USD 0.82 billion in 2025 and is estimated to reach USD 1.04 billion in 2026.
North America is expected to dominate the global vegan collagen market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By source/technology, the plant-based collagen boosters segment is expected to hold the largest share of the market in 2026, while the fermentation-derived collagen segment is projected to register the highest CAGR during the forecast period.
By product form, the powders segment is expected to hold the largest share in 2026, while the liquid formulations segment is projected to register the highest CAGR during the forecast period.
By application, the cosmetics and personal care segment is expected to hold the largest share in 2026, while the nutraceuticals and dietary supplements segment is projected to register the highest CAGR during the forecast period.
By end user, the cosmetics manufacturers segment is expected to hold the largest share in 2026, while the pharmaceutical and biotech companies segment is projected to register the highest CAGR during the forecast period.
By distribution channel, the online channels segment is expected to hold the largest share in 2026, while the direct sales (B2B) segment is projected to register the highest CAGR during the forecast period.
By functionality, the skin health and anti-aging segment is expected to hold the largest share in 2026, while the joint and bone health segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 3.84 Billion |
| Market Size in 2026 | USD 1.04 Billion |
| Market Size in 2025 | USD 0.82 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 13.9% |
| Format | PDF, Excel & Cloud Portal · 268 pages |
| Dominating Source/Technology | Plant-Based Collagen Boosters |
| Fastest Growing Source/Technology | Fermentation-Derived Collagen |
| Dominating Product Form | Powders |
| Fastest Growing Product Form | Liquid Formulations |
| Dominating Application | Cosmetics & Personal Care |
| Fastest Growing Application | Nutraceuticals & Dietary Supplements |
| Dominating End User | Cosmetics Manufacturers |
| Fastest Growing End User | Pharmaceutical & Biotech Companies |
| Dominating Distribution Channel | Online Channels |
| Fastest Growing Distribution Channel | Direct Sales (B2B) |
| Dominating Functionality | Skin Health & Anti-Aging |
| Fastest Growing Functionality | Joint & Bone Health |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: source/technology, product form, application, end user, distribution channel, functionality.
The global vegan collagen market covers ingredients, formulations, and finished products that replicate, stimulate, or substitute for the structural and functional properties of animal-derived collagen through entirely plant-based, fermentation-derived, or synthetic biology approaches. This encompasses plant-based collagen booster blends combining amino acids such as glycine, proline, hydroxyproline, and lysine with cofactor vitamins including C and B vitamins that support the body's endogenous collagen synthesis pathways, fermentation-derived recombinant collagen proteins produced through precision fermentation using genetically engineered yeast or bacteria expressing human or plant collagen gene sequences, and biomimetic synthetic collagen peptide structures designed to mimic the triple-helix structural properties of natural collagen across skincare, nutraceutical, dietary supplement, functional food, and biomedical application segments.
The growth of the global vegan collagen market is primarily driven by the rapid mainstream adoption of vegan, plant-based, and cruelty-free product preferences across cosmetics, personal care, and nutritional supplement consumer segments, which is progressively shifting purchasing decisions away from conventional marine and bovine collagen products toward plant-based and biotechnology-derived alternatives that align with ethical consumption values. The cosmetics and personal care industry's accelerating clean beauty movement, which prioritizes vegan certification, sustainable ingredient sourcing, and transparency about ingredient origins, is creating strong brand-driven demand for vegan collagen ingredients from formulators seeking to remove animal-derived collagen from their product formulations without compromising efficacy claims.
Two significant opportunities are shaping the market's long-term trajectory. The commercial maturation of precision fermentation technology for recombinant human collagen production, demonstrated by Geltor's successful commercialization of fermentation-derived human collagen proteins for cosmetic applications, is opening a pathway to functionally superior vegan collagen ingredients that replicate the exact molecular structure of human collagen rather than simply stimulating endogenous collagen synthesis, addressing the functional performance gap between current plant-based booster formulations and genuine collagen replacement. The expansion of vegan collagen applications into biomedical uses including tissue engineering scaffolds, wound dressings, and drug delivery matrices represents a high-value frontier market where the regulatory acceptance and clinical validation advantages of recombinant human collagen over xenogeneic animal collagen are driving strong institutional demand from pharmaceutical and medical device companies.
Report infographic
Market dynamics
7 factors across 3 forcesRising Demand for Plant-Based and Sustainable Ingredients
The primary driver of the global vegan collagen market is the structural shift in consumer product purchasing preferences toward plant-based, sustainably sourced, and ethically produced ingredients across cosmetics, dietary supplements, and functional food categories that is progressively displacing conventional animal-derived collagen ingredients from formulations targeting health-conscious and ethically motivated consumer segments. The global vegan product market has grown from a niche alternative food and lifestyle category to a mainstream consumer preference dimension that influences purchasing decisions across beauty, nutrition, and functional food categories for a consumer population estimated at hundreds of millions globally. Conventional collagen derived from bovine hides, porcine skin, and marine sources carries inherent ethical and sustainability objections for vegan and flexitarian consumers that are creating product reformulation pressure on brands seeking to address this consumer segment, driving demand for the vegan collagen ingredients that enable cruelty-free collagen benefit claims on reformulated products. The documented environmental impact of animal agriculture on greenhouse gas emissions, land use, and water consumption is further reinforcing the sustainability positioning of vegan collagen as a lower-impact alternative to conventional animal-derived collagen.
Increasing Adoption in Cosmetics and Personal Care
The cosmetics and personal care industry's rapid adoption of vegan collagen ingredients across prestige, mass-market, and direct-to-consumer brand formulations is the largest and most commercially developed demand channel for vegan collagen ingredients, as the industry's established collagen skin benefit claims, well-developed consumer understanding of collagen's role in skin firmness and anti-aging, and the large and premium-priced anti-aging skincare segment collectively create a natural commercial context for premium vegan collagen ingredient products. The EU's expanding regulatory pressure on animal testing in cosmetics and the progressive adoption of vegan certification by major European and Asian beauty retailers as a shelf listing requirement for new products are creating compliance-driven adoption incentives that extend vegan collagen adoption beyond voluntary sustainability commitments into commercially mandatory positioning. Brand investments in vegan collagen product lines from L'Oreal, Shiseido, Croda International, and Symrise are demonstrating the category's commercial viability at scale and establishing the ingredient supply chain relationships required for broad formulator adoption.
Table of contents
14 chapters · 169 sections · 268 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Source/Technology | Plant-Based Collagen Boosters | Fermentation-derived collagen |
| By Product Form | Powders | Liquid formulations |
| By Application | Cosmetics & Personal Care | Nutraceuticals and dietary supplements |
| By End User | Cosmetics Manufacturers | Pharmaceutical and biotech companies |
| By Distribution Channel | Online | Direct sales (B2B) |
By Source/Technology
- Plant-Based Collagen Boosters to Dominate
- The plant-based collagen boosters segment is expected to account for the largest share of the global vegan collagen market.
- The large share of this segment is attributed to plant-based collagen booster formulations combining vitamin C, glycine, proline, lysine, silica, and other collagen-supportive nutrients representing the most commercially established, most widely distributed, and most affordable category of vegan collagen products currently available, with broad retail presence across supplement, natural beauty, and functional food channels globally.
- The accessibility and cost-effectiveness of plant-based collagen booster formulations relative to fermentation-derived recombinant collagen, combined with the established consumer familiarity with vitamin C and amino acid supplementation for collagen synthesis support, have made this the entry-point segment for most brands entering the vegan collagen market.
- However, the fermentation-derived collagen segment is poised to register the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the commercial momentum of precision fermentation vegan collagen companies including Geltor and Modern Meadow securing major cosmetic brand partnerships, the progressive improvement in fermentation collagen production economics creating competitive pricing trajectories, and the superior functional differentiation of recombinant collagen proteins relative to collagen booster blends that positions fermentation-derived products as the premium tier of the vegan collagen market capable of commanding the highest per-unit value.
By Product Form
- Powders to Hold the Largest Share
- The powders segment is expected to account for the largest share of the global vegan collagen market.
- The dominance of powders reflects the format's versatility across supplement, functional food, and ingredient supply applications, its cost-efficiency in production and packaging relative to liquid and topical formats, and the established consumer adoption of collagen powder supplements that has driven the development of smoothie-compatible, flavorless, and flavored vegan collagen powder products by a large number of direct-to-consumer and retail supplement brands.
- The B2B ingredient supply application of vegan collagen powders to food, beverage, and supplement formulators represents a large and volume-efficient demand channel that reinforces the segment's market size dominance.
- However, the liquid formulations segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the rapidly growing consumer preference for convenience-oriented beauty supplement formats including single-serve liquid shots, ready-to-drink collagen beauty beverages, and liquid collagen drops that deliver premium supplement experiences with high perceived bioavailability that commands higher retail price points than equivalent powder or capsule formats.
By Application
- Cosmetics & Personal Care to Hold the Largest Share
- The cosmetics and personal care segment is expected to account for the largest share of the global vegan collagen market.
- This dominance reflects cosmetics' position as the most established and highest-value application channel for vegan collagen ingredients, driven by the large global anti-aging skincare market's well-developed collagen benefit communication framework, the premium pricing achievable for vegan-certified collagen skincare formulations, and the broad formulator adoption of vegan collagen ingredient options by prestige and mass-market cosmetic brands as a clean beauty ingredient substitution for animal-derived collagen.
- However, the nutraceuticals and dietary supplements segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the rapid mainstream adoption of vegan dietary supplement lifestyles across the key supplement-consuming demographics in North America, Europe, and Asia-Pacific, the explosive growth of the beauty-from-within supplement category creating a large new consumer market for ingestible vegan collagen products, and the improving product quality and efficacy communication of vegan collagen supplement brands that is converting conventional collagen supplement users.
By End User
- Cosmetics Manufacturers to Hold the Largest Share
- The cosmetics manufacturers segment is expected to account for the largest share of the global vegan collagen market.
- Cosmetic companies represent the primary and most commercially mature end-user segment for vegan collagen ingredients, with vegan collagen ingredient procurement driven by the clean beauty reformulation programs of prestige brands including L'Oreal, Shiseido, and Unilever alongside the proliferating direct-to-consumer vegan beauty brands that have specifically built their brand identities around vegan collagen formulations.
- The high per-unit value of premium skincare products containing vegan collagen ingredients generates strong purchasing motivation that supports premium ingredient pricing, making cosmetics manufacturers the highest-value customer segment for vegan collagen ingredient suppliers.
- However, the pharmaceutical and biotech companies segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the growing pharmaceutical industry interest in recombinant human collagen proteins for drug delivery matrices, tissue engineering scaffolds, wound healing products, and regenerative medicine applications where the regulatory and safety profile advantages of human-sequence recombinant collagen over xenogeneic animal collagen are compelling, and by the biomedical research community's rapidly expanding use of fermentation-derived collagen proteins as defined and reproducible research tools replacing variable animal-derived collagen preparations.
By Distribution Channel
- Online Channels to Hold the Largest Share
- The online channels segment is expected to account for the largest share of the global vegan collagen market.
- The dominance of online channels reflects both the strong direct-to-consumer e-commerce business model adopted by most vegan collagen consumer brand companies, which leverage digital marketing, social media health and beauty communities, and subscription commerce to build consumer bases without the slotting fee and minimum volume requirements of conventional retail, and the large B2B ingredient e-commerce platforms that increasingly facilitate vegan collagen ingredient procurement by smaller cosmetic, supplement, and food formulators who lack direct supplier relationship infrastructure.
- Amazon, Thrive Market, iHerb, and brand-direct websites collectively represent the largest retail revenue channels for vegan collagen consumer products.
- However, the direct sales (B2B) segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the expanding commercial-scale ingredient procurement programs of major cosmetic and supplement companies establishing direct supply agreements with vegan collagen ingredient producers as they scale vegan reformulation programs across their product portfolios, creating large-volume B2B ingredient purchase relationships that represent the highest-value and most strategically important revenue streams for vegan collagen ingredient manufacturers.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global vegan collagen market. The largest share of this region is mainly due to the concentration of leading precision fermentation and synthetic biology vegan collagen technology companies including Geltor, Modern Meadow, Jellatech, and Amyris in the United States, the large and highly developed vegan supplement and clean beauty consumer markets in the U.S. and Canada that represent the largest addressable consumer demand bases for vegan collagen products globally, and the advanced early-adoption culture of the North American natural products and wellness retail channels that has established vegan collagen as a mainstream supplement category ahead of other regional markets. The U.S. natural and specialty food and supplement retail ecosystem anchored by Whole Foods Market, Sprouts, and iHerb, combined with the very large direct-to-consumer digital supplement market, provides the distribution infrastructure through which vegan collagen brands including Vital Proteins, Garden of Life, and numerous emerging brands have built commercially meaningful businesses. The biotechnology investment ecosystem of Silicon Valley and the Boston-Cambridge biotech cluster is providing the venture capital and strategic partnership infrastructure supporting the leading fermentation-derived vegan collagen companies whose commercial development represents the market's highest-value near-term growth trajectory.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific vegan collagen market is expected to grow at the fastest CAGR during the forecast period. The region's rapid growth is driven by the extraordinary scale and innovation intensity of the South Korean K-beauty industry's adoption of vegan collagen formulations for its global export product lines, the very large and rapidly growing premium skincare consumer market in China where both ethical consumption awareness and anti-aging skincare spending are rising simultaneously among urban middle-class consumers, Japan's well-established and scientifically sophisticated beauty and nutraceutical supplement culture that is progressively adopting vegan alternatives to its traditional marine collagen supplement category, and the rapidly developing vegan lifestyle consumer segments in Australia, Singapore, and India that are generating growing demand for vegan-certified personal care and supplement products incorporating plant-based or fermentation-derived collagen alternatives.
Europe
Europe represents an important and growing vegan collagen market with a strong policy and regulatory foundation for market development, anchored by the EU's comprehensive vegan and cruelty-free cosmetic ingredient regulatory framework, the EFSA's novel food assessment process for fermentation-derived collagen proteins, and the strong vegan consumer culture of the U.K., Germany, Netherlands, and Sweden that generates high per-capita demand for vegan-certified beauty and supplement products. European ingredient companies including Evonik, DSM-Firmenich, Symrise, Croda International, and BASF are developing vegan collagen ingredient portfolios for the European cosmetic and supplement formulation market, creating a European supply chain that reduces import dependence and enables EFSA-compliant novel ingredient development.
Competitive landscape
- Geltor Inc. (U.S.)
- Evonik Industries AG · Germany
- DSM-Firmenich · Switzerland/Netherlands
- Amyris Inc. (U.S.)
- Modern Meadow Inc. (U.S.)
- Jellatech Inc. (U.S.)
- CollPlant Biotechnologies Ltd. · Israel
- GELITA AG · Germany
- Symrise AG · Germany
- Croda International Plc (U.K.)
- BASF SE · Germany
- L'Oreal S.A. · France
- Shiseido Company Limited · Japan
- Unilever PLC (U.K./Netherlands)
- Procter & Gamble Company (U.S.)
Frequently asked questions
The global vegan collagen market is expected to reach USD 3.84 billion by 2036 from an estimated USD 1.04 billion in 2026, at a CAGR of 13.9% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Vegan Collagen Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRFB - 1041904). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/vegan-collagen-market-6587