Spatial Computing Market (2026-2036)
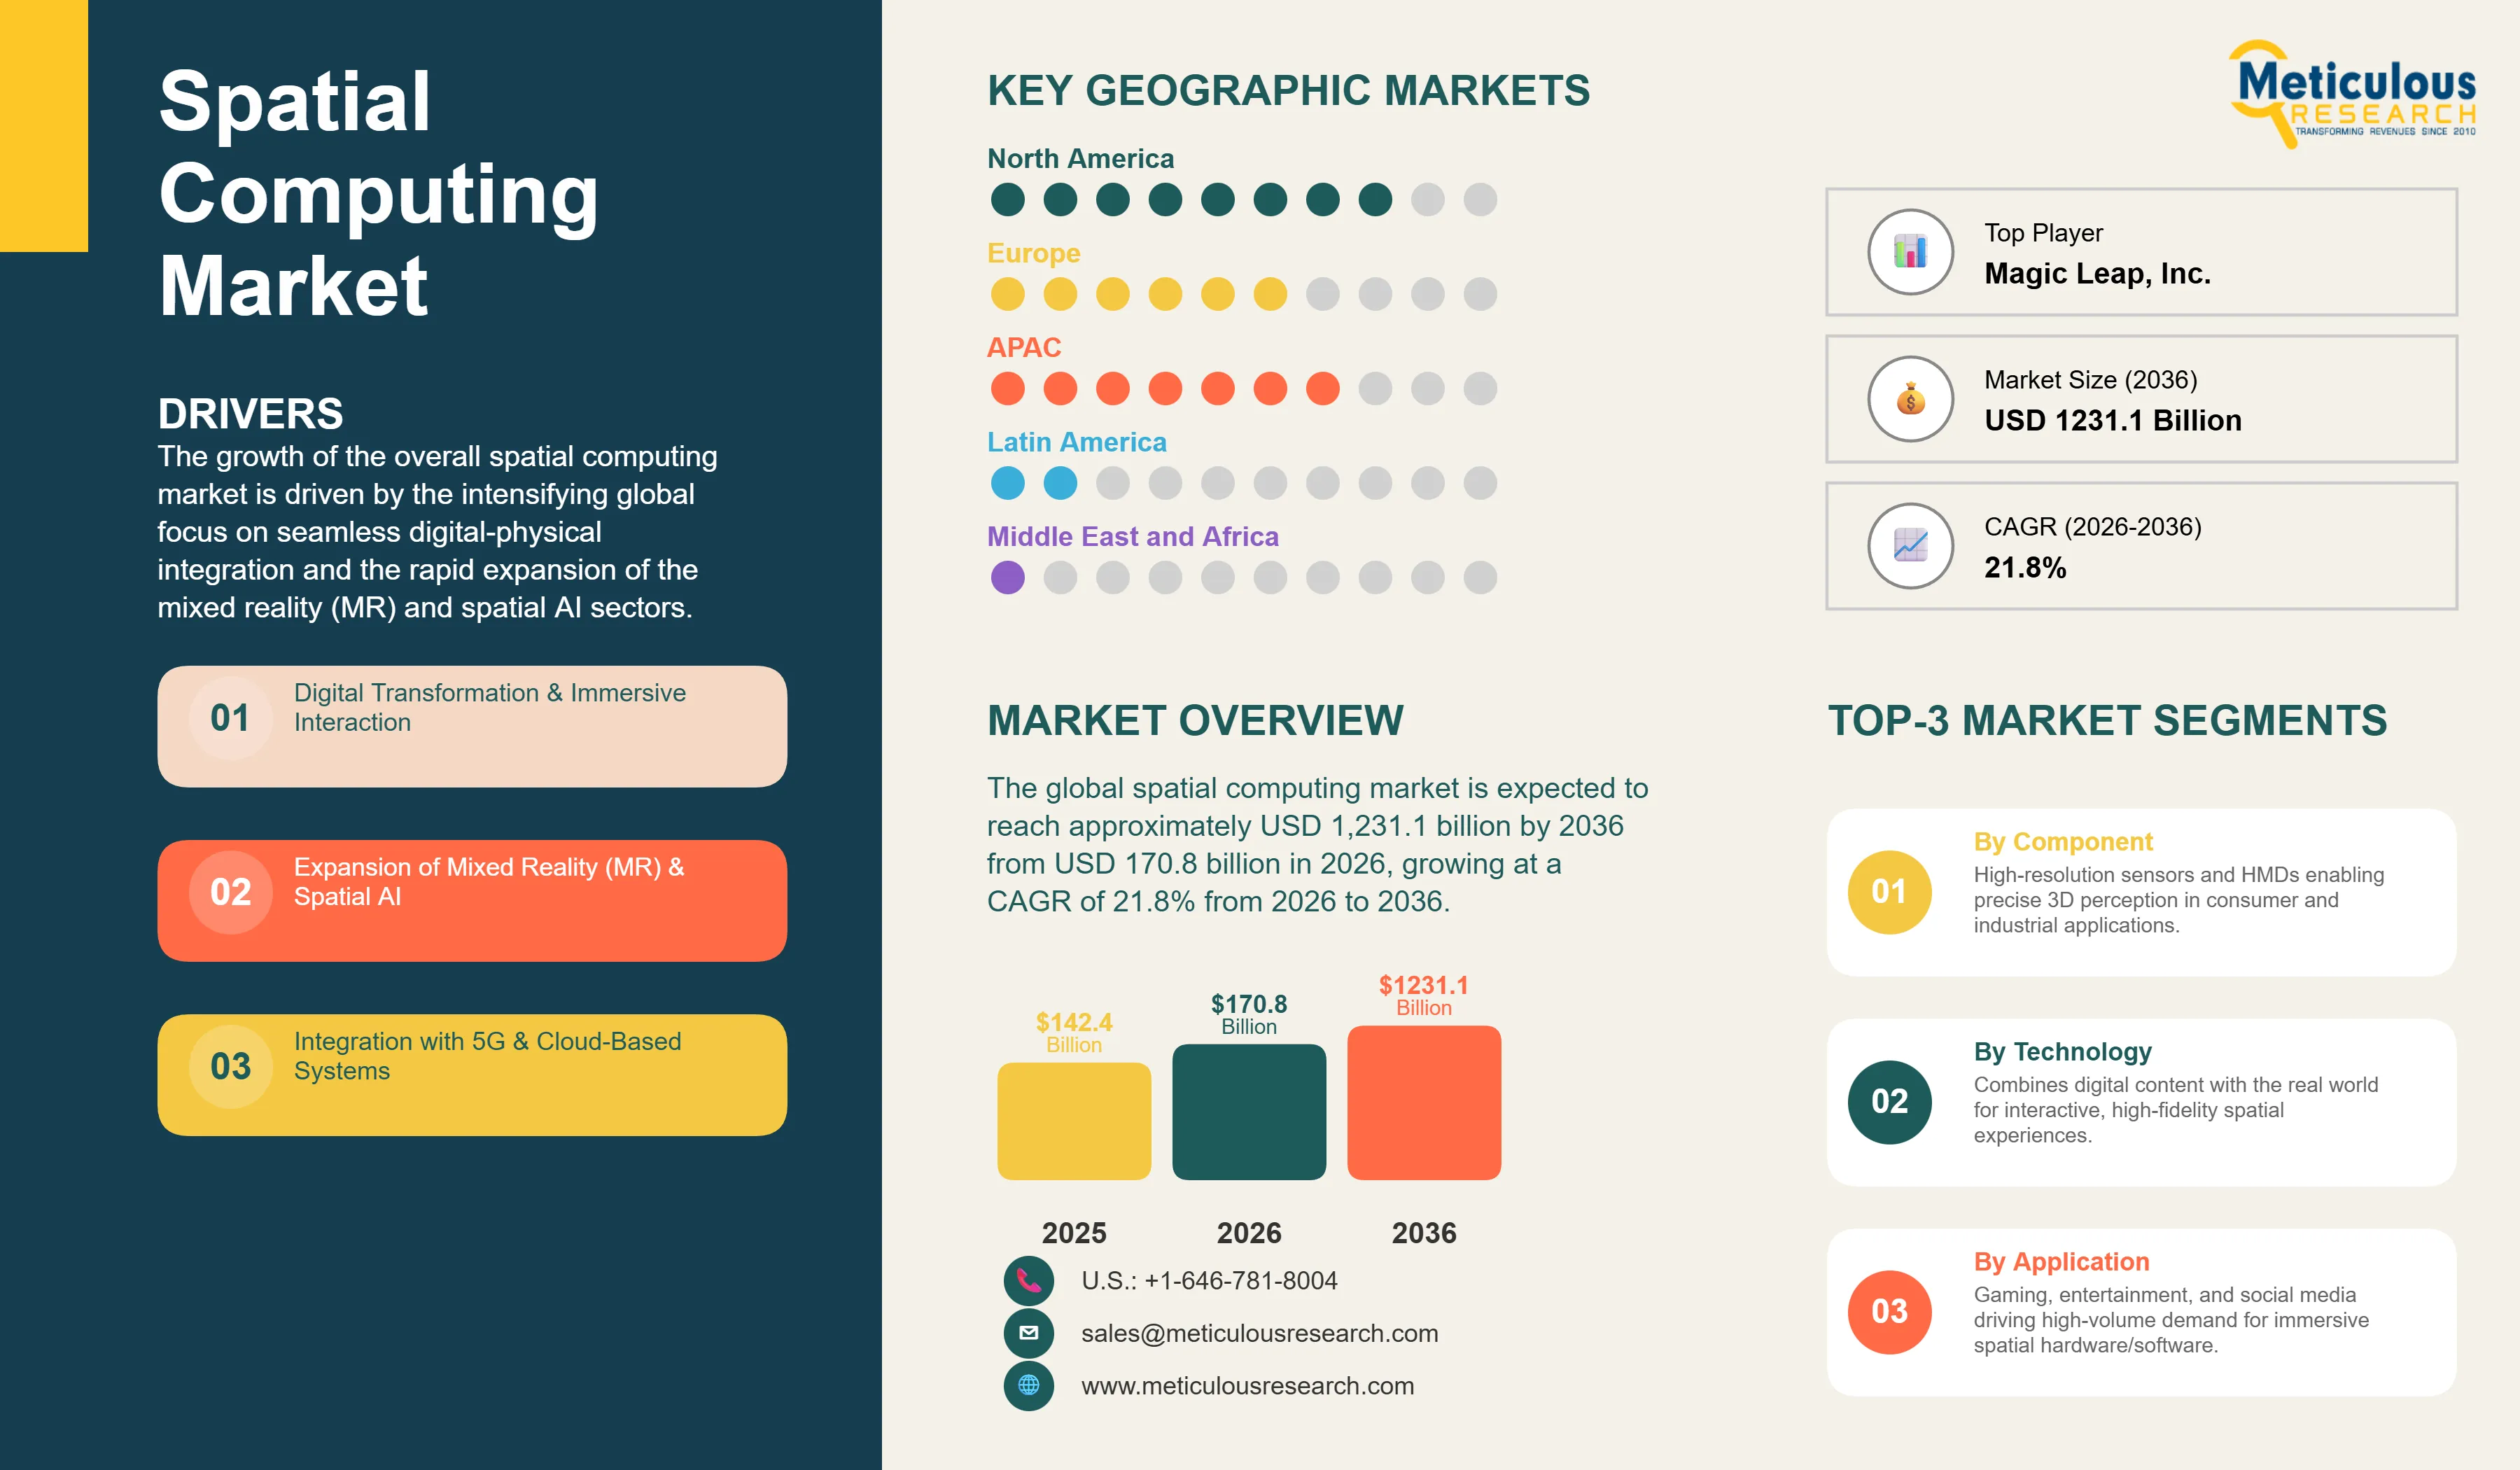
The global spatial computing market was valued at USD 142.4 billion in 2025. The market is expected to reach approximately USD 1,231.1 billion by 2036 from USD 170.8 billion in 2026, growing at a CAGR of 21.8% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 220
- Format
- PDF + Excel
- Report ID
- MR-1731
- Base year
- 2025
- 2025 · BASELINE
- $142.4B
- 2036
- $1.23T
- CAGR 2026–2036
- 21.8%
2025 baseline · 2026–2036 forecast at 21.8% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global spatial computing market is projected to reach USD 1,231.1 billion by 2036.
The market is expected to grow at a CAGR of 21.8% from 2026 to 2036.
North America dominates the global spatial computing market with the largest market share in 2026, driven by massive industrialization of immersive technologies and the presence of leading technology hubs in the U.S. and Canada.
Asia-Pacific is expected to witness the fastest growth during the forecast period, supported by aggressive consumer electronics investments and the rapid adoption of advanced spatial manufacturing strategies.
By component, the hardware segment holds the largest market share in 2026, particularly in supporting high-resolution passthrough and complex sensor fusion in premium head-mounted displays (HMDs) and smart glasses.
By application, the consumer segment holds the largest market share in 2026, due to the high volume of gaming and entertainment production and the rising demand for spatial social interaction.
By technology, the mixed reality (MR) segment holds the largest share of the overall market in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 1,231.1 Billion |
| Market Size in 2026 | USD 170.8 Billion |
| Market Size in 2025 | USD 142.4 Billion |
| Market Growth Rate (2026-2036) | CAGR of 21.8% |
| Format | PDF, Excel & Cloud Portal · 220 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Component, Technology, Application, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: component, technology, application.
The growth of the overall spatial computing market is driven by the intensifying global focus on seamless digital-physical integration and the rapid expansion of the mixed reality (MR) and spatial AI sectors. As manufacturers seek to integrate more functionality into wearable form factors and reduce the friction between human interaction and digital data, spatial computing systems have become essential for maintaining high-speed information flow and mechanical durability. The rapid expansion of the 5G infrastructure and the increasing need for high-density spatial mapping solutions in industrial automation and advanced surgical navigation continue to fuel significant growth of this market across all major geographic regions.
Spatial Computing refers to critical computational frameworks used to provide 3D environment perception while allowing for automated digital content anchoring and optimized interaction throughout the physical workspace. These systems include integrated hardware, software, and services designed to withstand high-frequency spatial data processing and fit into non-planar real-world environments. The market is defined by high-efficiency technologies such as computer vision and spatial AI, which significantly enhance environmental awareness and signal performance in high-fidelity applications. These systems are indispensable for manufacturers seeking to optimize their internal operational architecture and meet aggressive digital transformation targets.
The market includes a diverse range of configurations, ranging from simple AR overlays for basic information display to complex multilayer MR systems for high-performance engineering and medical simulation. These systems are increasingly integrated with advanced components such as eye-tracking sensors and ultra-fast spatial mapping engines to provide services such as real-time occlusion and improved depth perception. The ability to provide stable, high-precision interaction while minimizing physical cognitive load has made advanced spatial computing the technology of choice for industries where operational efficiency and reliability are paramount.
The global technology sector is pushing hard to modernize production capabilities, aiming to meet AI-driven hardware and IoT connectivity targets. This drive has increased the adoption of high-density spatial pipelines, with advanced SLAM (Simultaneous Localization and Mapping) techniques helping to stabilize environment tracking for ultra-fine industrial grids. At the same time, the rapid growth in the remote collaboration and digital twin markets is increasing the need for high-reliability, low-latency spatial solutions.
Manufacturers across the technology industry are rapidly shifting to AI-optimized hardware, moving well beyond traditional display designs toward high-speed, low-latency spatial setups. Apple’s latest Vision Pro systems deliver significantly higher interaction depth for spatial personas, while Meta’s recent Quest installations have slashed environment mapping times in consumer and enterprise projects. The real game-changer comes with “smart” spatial computers featuring integrated AI processors and sensor arrays that maintain peak performance even in complex, electromagnetically noisy environments. These advancements make high-precision spatial computing practical and cost-effective for everyone from tech startups to global industrial giants chasing operational excellence and lower system weight.
Innovation in mixed reality and ultra-thin optical systems is rapidly driving the spatial computing market, as wearable devices become more compact and multi-functional. Equipment suppliers are now designing units that combine the structural integrity of traditional headsets with the versatility of lightweight smart glasses in a single assembly, saving valuable internal space and simplifying user logistics. These systems often involve advanced waveguide optics and pancake lenses capable of handling ultra-high resolutions without compromising mechanical strength or electrical reliability.
At the same time, growing focus on sustainable technology is pushing manufacturers to develop spatial solutions tailored to circular economy principles. These systems help reduce material waste through modular hardware designs and the use of recyclable substrates. By combining high-density spatial connectivity with robust environmental performance, these new designs support both technological advancement and corporate sustainability, strengthening the resilience of the broader technology value chain.
However, the enterprise and industrial segment is poised for steady growth through 2036, fueled by expanding applications in remote collaboration and simple spatial training.
Manufacturers face mounting pressure to optimize costs for high-volume, less demanding applications, where enterprise spatial solutions provide a cost-effective alternative for basic intelligent connectivity.
Market dynamics
2 factors across 2 forcesDigital Transformation and Rise of Immersive Interaction
A key driver of the spatial computing market is the rapid movement of the global technology industry toward more intuitive, 3D-aware, and highly functional computing platforms. Global demand for seamless collaboration, real-time data visualization, and immersive training has created significant incentives for the adoption of spatial computing. The trend toward “physical AI” and the integration of digital twins into industrial workflows and medical procedures drive manufacturers toward scalable solutions that spatial computing can uniquely provide. It is estimated that as enterprise adoption of MR-enabled headsets rises and development tools become more decentralized through 2036, the need for robust, intelligent systems increases significantly; therefore, spatial mapping and computer vision, with their ability to ensure high-density data processing, are considered a crucial enabler of modern digital design strategies.
Table of contents
10 chapters · 92 sections · 220 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Hardware | — |
| By Technology | Mixed reality (MR) | — |
| Other segments | — | Artificial intelligence (AI) and computer vision |
By Component
- The hardware segment accounts for a significant portion of the overall spatial computing market in 2026.
- This is mainly attributed to the versatile use of this technology in supporting high-resolution passthrough and complex sensor fusion within extremely tight wearable spaces, such as in premium HMDs and industrial smart glasses.
- These systems offer the most comprehensive way to ensure environment perception across diverse high-frequency applications.
- The consumer and industrial sectors alone consume a large share of spatial hardware production, with major projects in North America and Asia Pacific demonstrating the technology’s capability to handle high-density data requirements.
- However, the software segment is expected to grow at a rapid CAGR during the forecast period, driven by the growing need for robust spatial OS, development SDKs, and AI-driven mapping suites in expanding enterprise and consumer ecosystems.
- The consumer segment commands the largest share of the global spatial computing market in 2026.
- This dominance stems from its superior volume of gaming, entertainment, and social media applications, making it the primary driver of spatial hardware and software adoption.
- Large-scale operations in gaming and social platforms drive demand, with advanced headsets from suppliers like Apple and Meta enabling reliable performance in diverse home environments.
By Technology
- The mixed reality (MR) segment holds the largest share of the overall market in 2026.
- This is primarily due to the massive volume of enterprise and consumer demand for systems that can blend digital content with the physical world and the rigorous performance standards required for modern spatial interaction.
- Current large-scale infrastructure projects are increasingly specifying high-density MR solutions to ensure compliance with global performance standards and user expectations for more realistic, interactive digital overlays.
Other segments
- The artificial intelligence (AI) and computer vision segment is expected to witness the fastest growth during the forecast period.
- The shift toward on-device spatial intelligence and the complexity of environment perception suites are pushing the requirement for advanced AI systems that can handle varied lighting conditions and mechanical stresses while ensuring absolute reliability for safety-critical spatial systems.
Geographic analysis
North America
Largest shareNorth America holds the largest share of the global spatial computing market in 2026. The largest share of this region is primarily attributed to the massive industrialization of immersive tech and the presence of the world’s largest technology hubs, particularly in the United States. The U.S. alone accounts for a significant portion of global spatial computing investment, with its position as a leading exporter of high-end spatial software driving sustained growth. The presence of leading manufacturers like Apple, Meta, and Microsoft and a well-developed technology supply chain provides a robust market for both standard and high-density spatial solutions.
Europe
Asia-Pacific and Europe together account for a substantial share of the global spatial computing market. The growth of these markets is mainly driven by the need for technological modernization in the consumer electronics and industrial sectors. The demand for advanced spatial systems in Asia-Pacific is mainly due to its large-scale consumer electronics projects and the presence of innovators in China, Japan, and South Korea. In Europe, the leadership in industrial engineering and the push for medical technology innovation are driving the adoption of high-reliability spatial solutions. Countries like Germany, France, and the UK are at the forefront, with significant focus on integrating smart spatial solutions into manufacturing workflows and advanced healthcare systems to ensure the highest levels of performance and reliability.
Competitive landscape
- Apple Inc.
- Meta Platforms, Inc.
- Microsoft Corporation
- Google LLC
Frequently asked questions
The global spatial computing market is expected to grow from USD 170.8 billion in 2026 to USD 1,231.1 billion by 2036.
Cite this report
Meticulous Research. (2026). Spatial Computing Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1731). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/spatial-computing-market-6414