Smart Inhalers Market (2026-2036)
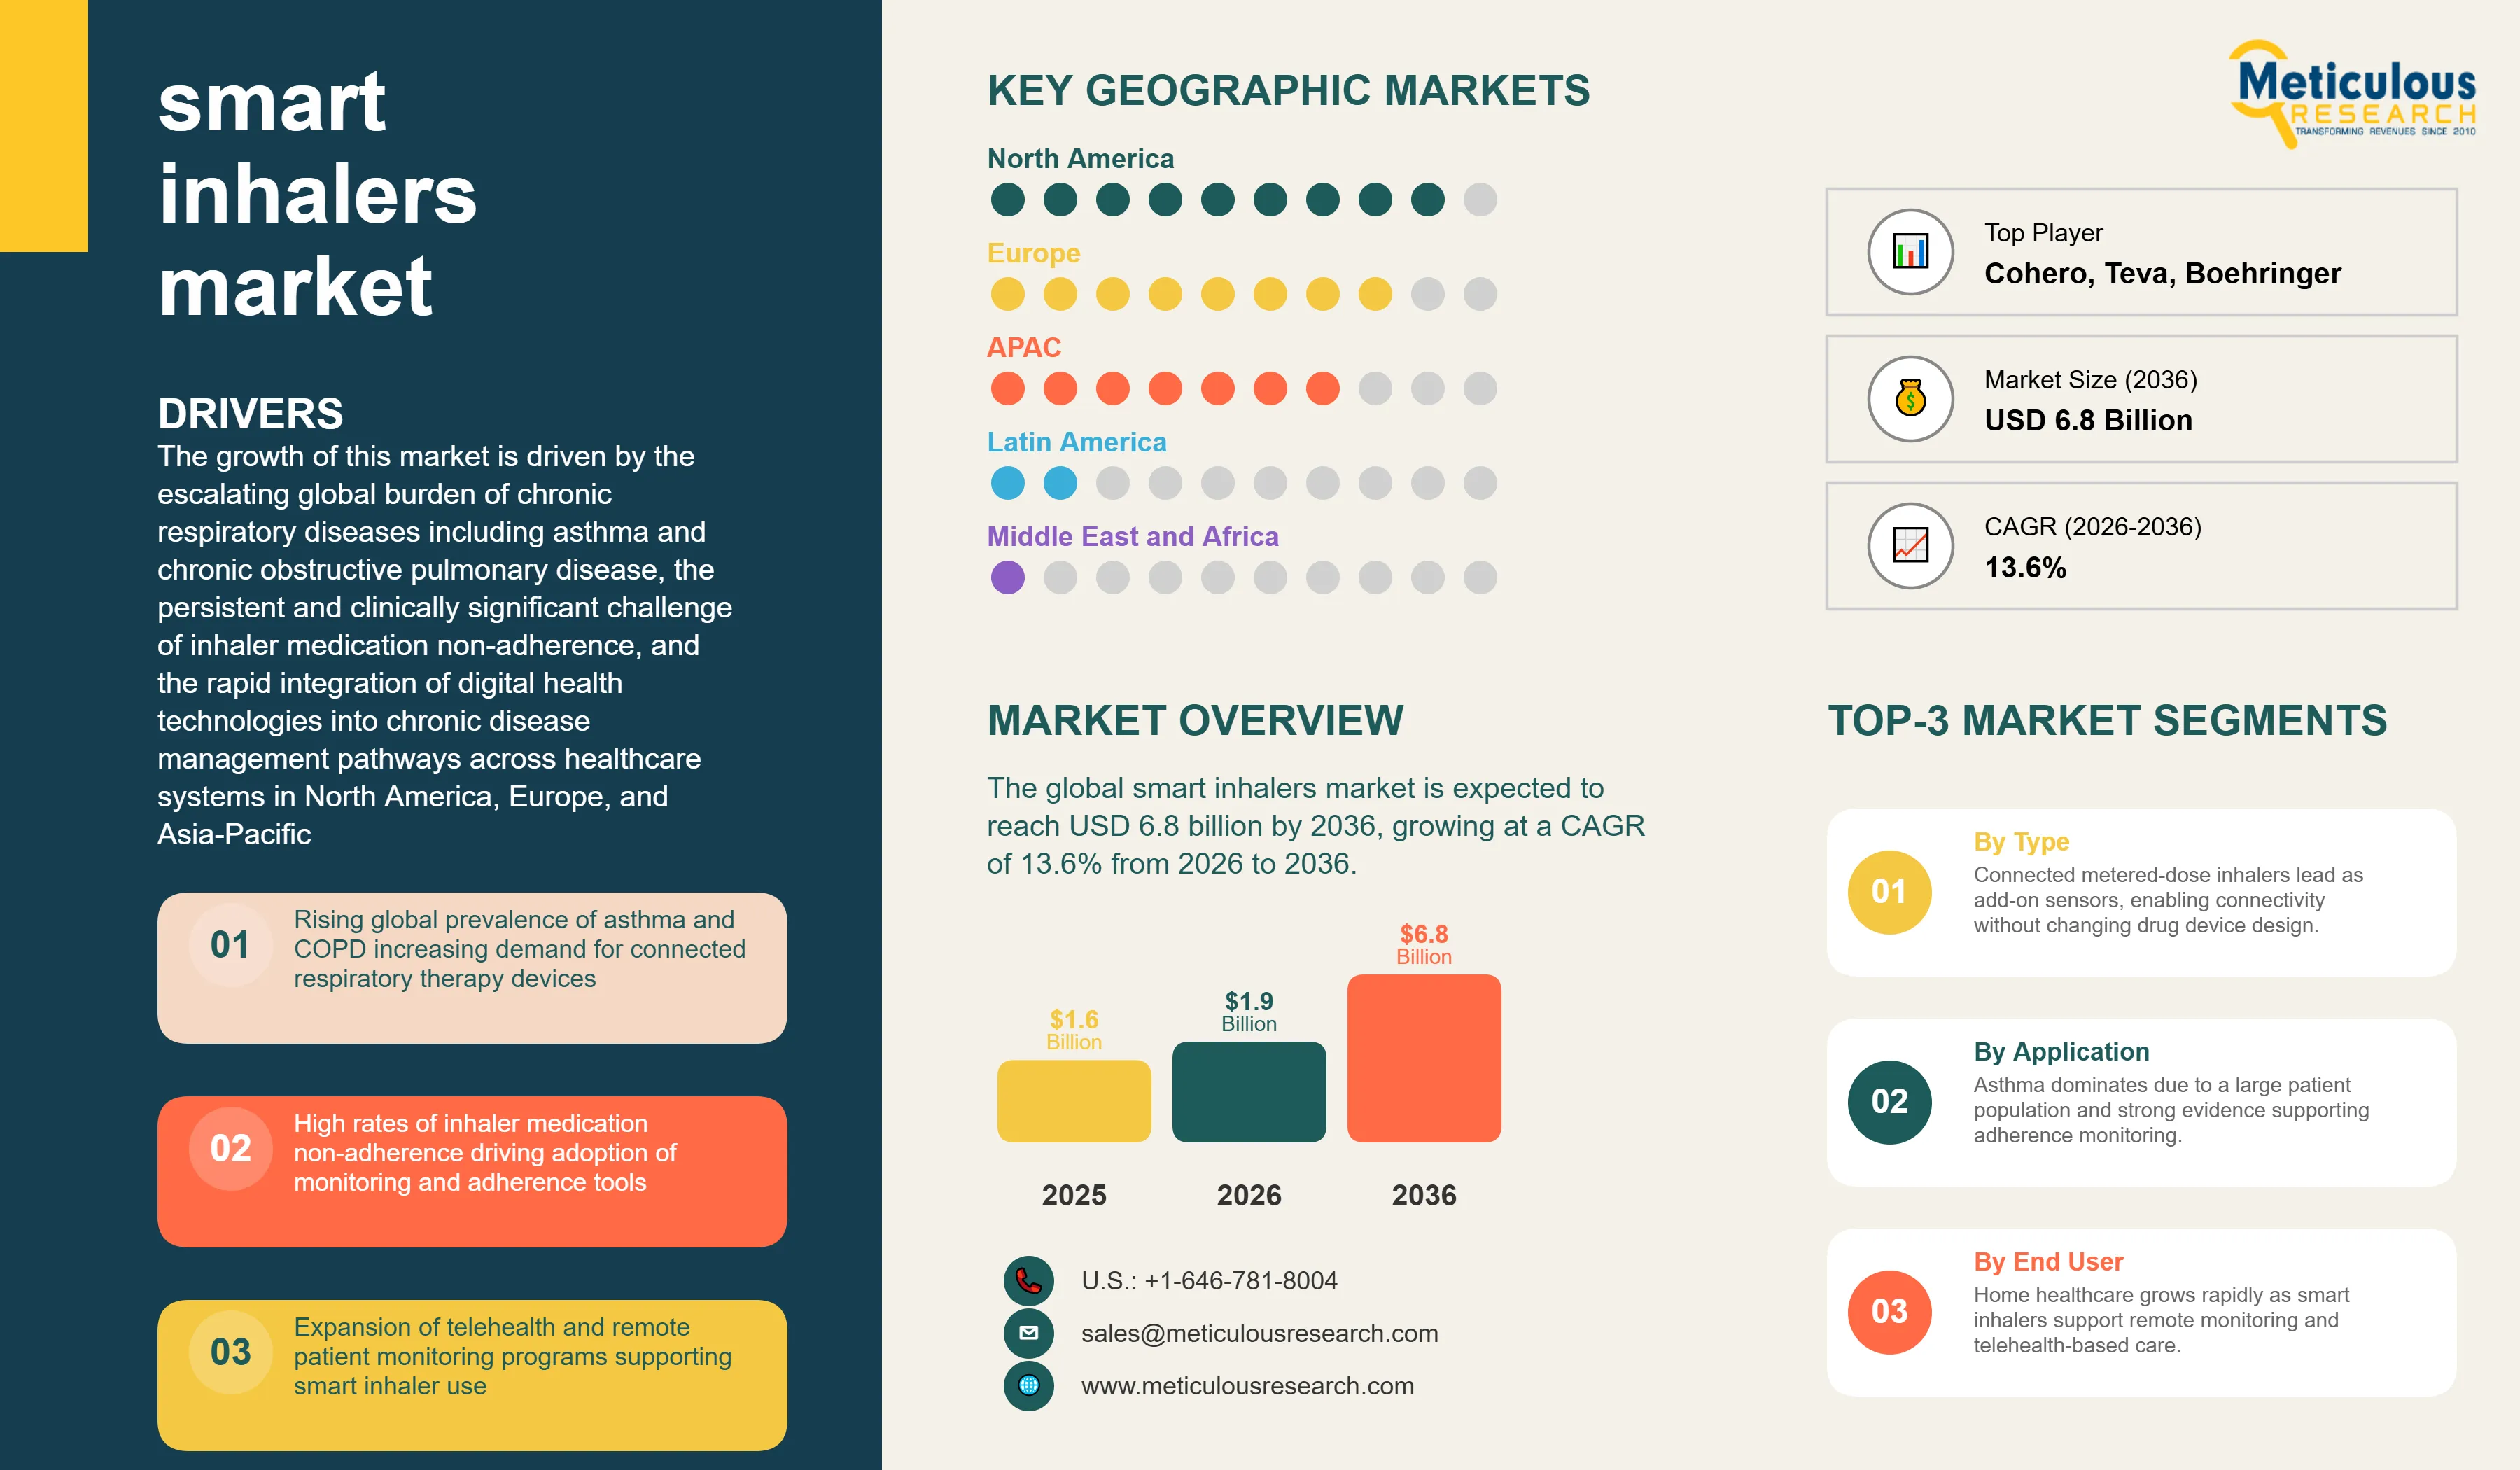
The global smart inhalers market was valued at USD 1.6 billion in 2025. This market is expected to reach USD 6.8 billion by 2036 from USD 1.9 billion in 2026, growing at a CAGR of 13.6% from 2026 to 2036.
- Published
- Mar 2026
- Pages
- 282
- Format
- PDF + Excel
- Report ID
- MRHC - 1041844
- Base year
- 2025
- 2025 · BASELINE
- $1.60B
- 2036
- $6.80B
- CAGR 2026–2036
- 13.6%
2025 baseline · 2026–2036 forecast at 13.6% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global smart inhalers market is projected to reach USD 6.8 billion by 2036.
The market is expected to grow at a CAGR of 13.6% from 2026 to 2036.
North America is expected to dominate the global smart inhalers market with the largest market share in 2026, driven by the high prevalence of asthma and COPD within a well-insured patient population, active reimbursement coverage by major payers for digital therapeutics and remote patient monitoring programs that include smart inhaler adherence services, and the leading commercial positions of Propeller Health, Adherium, and Cohero Health alongside major pharmaceutical companies including AstraZeneca, GSK, and Boehringer Ingelheim that have embedded smart inhaler connectivity into their U.S. product strategies.
Asia-Pacific is expected to witness the fastest growth during the forecast period, driven by China's rapidly growing urban air pollution-related respiratory disease burden, India's large and underserved COPD patient population with increasing smartphone penetration enabling digital adherence platforms, and Japan's and South Korea's strong digital health infrastructure and health system investment in remote chronic disease management technologies.
By product type, the connected metered-dose inhalers (cMDI) segment is expected to hold the largest share of the overall smart inhalers market in 2026, as pressurized metered-dose inhalers remain the most globally prescribed inhaler format for asthma and COPD maintenance and rescue therapy, and the add-on sensor attachment approach pioneered by Propeller Health and Adherium enables connectivity to be retrofitted onto existing conventional inhaler devices without requiring changes to the drug formulation or regulatory approvals.
By product type, the connected dry powder inhalers (cDPI) segment is expected to witness the fastest growth during the forecast period, driven by pharmaceutical companies including AstraZeneca and GSK integrating connectivity directly into new-generation DPI device designs, the strong and growing market position of DPI platforms in the maintenance therapy segment for severe asthma and COPD, and the superior dose consistency and environmental sustainability profile of DPI systems relative to propellant-containing pMDI platforms.
By technology, the Bluetooth Low Energy segment is expected to hold the largest share of the smart inhalers market in 2026, as BLE provides the optimal combination of reliable short-range data transmission, minimal battery consumption consistent with the need for devices to operate for months between battery changes, and universal compatibility with iOS and Android smartphones that patients already own.
By indication, the asthma segment is expected to hold the largest share of the overall smart inhalers market in 2026, as the large and well-defined asthma patient population, the availability of multiple validated smart inhaler products specifically targeting asthma management, and the particularly strong clinical and health-economic evidence base for smart inhaler-based adherence interventions in asthma make this the most commercially mature indication for smart inhaler deployment.
By indication, the COPD segment is expected to witness the fastest growth during the forecast period, driven by the large global COPD patient population, the very high rate of inhaler non-adherence in COPD patients who frequently manage multiple concurrent inhaler devices, and the strong economic case for smart inhaler-based adherence programs in COPD where each prevented exacerbation avoids substantial hospitalization costs that payers are motivated to reduce.
By end user, the home healthcare settings segment is expected to witness the fastest growth during the forecast period, as the smart inhaler value proposition of enabling remote adherence monitoring, technique coaching, and exacerbation early warning without requiring frequent in-clinic visits aligns directly with the telehealth and remote patient monitoring models that health systems and payers are actively expanding.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 6.8 Billion |
| Market Size in 2026 | USD 1.9 Billion |
| Market Size in 2025 | USD 1.6 Billion |
| Market Growth Rate (2026–2036) | CAGR of 13.6% |
| Format | PDF, Excel & Cloud Portal · 282 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Product Type, Technology, Indication, Distribution Channel, End User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: product type, technology, indication, distribution channel, end user.
The growth of this market is driven by the escalating global burden of chronic respiratory diseases including asthma and chronic obstructive pulmonary disease, the persistent and clinically significant challenge of inhaler medication non-adherence, and the rapid integration of digital health technologies into chronic disease management pathways across healthcare systems in North America, Europe, and Asia-Pacific. A smart inhaler system is a connected drug delivery device that combines a conventional inhalation therapy platform — whether a metered-dose inhaler, dry powder inhaler, soft mist inhaler, or nebulizer — with embedded electronic sensors, wireless communication modules, and linked mobile application and cloud analytics software that together capture detailed data on inhaler actuation timing, technique quality, inhalation flow rate, and environmental context. This data is transmitted to patient-facing mobile applications and clinician dashboards that provide adherence feedback, technique coaching, exacerbation risk alerts, and longitudinal therapy performance reporting.
The fundamental clinical problem that smart inhaler systems address is inhaler medication non-adherence, which affects an estimated 50 to 60 percent of patients with asthma and COPD globally and is directly associated with increased rates of acute exacerbations, unplanned emergency department visits, hospitalizations, and disease-related mortality. Conventional adherence monitoring approaches based on patient self-report and prescription refill records are widely recognized as inaccurate, and clinical studies using electronic monitoring have demonstrated that patients' actual inhaler use patterns differ dramatically from their self-reported behavior. Smart inhaler systems provide objective, timestamped records of every inhaler actuation that enable clinicians to identify specific adherence failure patterns, distinguish between non-adherence and poor inhaler technique as causes of inadequate disease control, and design targeted behavioral interventions that have been shown in randomized controlled trials to significantly improve adherence rates and clinical outcomes.
Smart inhaler systems represent the convergence of established pharmaceutical inhaled drug delivery technology with miniaturized consumer electronics, wireless communication, mobile health application software, and cloud-based data analytics platforms. The core hardware innovation enabling smart inhalers is the development of sensor and electronics modules sufficiently small, energy-efficient, and cost-effective to be incorporated either within new inhaler device designs by pharmaceutical manufacturers or as retrofit attachments that clip onto existing conventional inhaler canisters or caps. These sensor modules detect inhaler use events through one or more physical sensing modalities including acoustic microphones that detect the characteristic sound signature of drug canister actuation, airflow sensors that measure the inhalation flow rate through the inhaler mouthpiece, MEMS accelerometers that detect the orientation and movement patterns characteristic of inhaler use, and capacitive or optical sensors that detect the position of the inhaler dose counter or actuator. The combination of multiple sensing modalities in advanced smart inhaler designs enables the system to detect not only that an inhaler was used but also to assess whether the inhalation technique was adequate — specifically whether the patient's inspiratory flow rate was within the range required for effective drug deposition in the lungs for the specific device type.
The wireless data transmission layer of smart inhaler systems has largely standardized on Bluetooth Low Energy protocols that enable timestamped inhaler event data to be transmitted from the inhaler to the patient's smartphone automatically at the time of inhaler use or through periodic synchronization sessions. Smartphone-based mobile applications serve as the primary patient interface, presenting adherence tracking information in visualizations designed to motivate consistent use, providing inhalation technique feedback based on sensor data, sending programmed reminder notifications when scheduled doses are missed, and enabling patients to log symptom reports and environmental exposure data that contextualizes their inhaler use patterns. Cloud analytics platforms aggregate data from large patient populations to generate population-level adherence metrics and predictive exacerbation risk models that health system and payer customers use to identify high-risk patients requiring clinical intervention.
The market ecosystem includes three distinct business model approaches. Pharmaceutical companies including AstraZeneca, GSK, Boehringer Ingelheim, and Novartis are pursuing connectivity as a product differentiator, embedding smart features into new inhaler device platforms or partnering with specialist digital health companies to create connected versions of existing marketed drugs. Digital health platform companies including Propeller Health (acquired by ResMed), Adherium, and Cohero Health provide drug-agnostic smart inhaler add-on devices and analytics platforms that connect to multiple different pharmaceutical companies' inhaler products, selling adherence management services to health systems, payers, and pharmaceutical companies. Integrated care organizations and pharmacy benefit managers are increasingly procuring smart inhaler programs as disease management services where the adherence improvement and exacerbation prevention outcomes provide demonstrable return on investment through reduced emergency department and hospitalization costs.
Report infographic
Market dynamics
4 factors across 3 forcesRising Global Burden of Chronic Respiratory Diseases and Medication Non-Adherence
The primary driver of the smart inhalers market is the growing global prevalence of asthma and COPD combined with the persistent and clinically consequential failure of conventional inhaler therapy delivery to achieve adequate medication adherence in the patient populations affected by these conditions. The World Health Organization estimates that over 330 million people worldwide currently live with asthma, and approximately 480 million with COPD, with both disease burdens continuing to grow due to urbanization, air pollution, tobacco use in developing countries, and the aging of global populations. These two conditions together account for substantial direct healthcare expenditure through emergency department visits, hospitalizations, and intensive care admissions associated with acute exacerbations, the majority of which are considered preventable through adequate maintenance therapy adherence.
The clinical and economic consequences of inhaler non-adherence are well-documented. Studies conducted across multiple healthcare systems consistently demonstrate that patients with poorly controlled asthma who are classified as treatment-refractory frequently improve substantially when objective adherence monitoring reveals and addresses underlying non-adherence, rather than requiring treatment escalation to more expensive biologic therapies. For payers, the cost of a single COPD exacerbation requiring hospitalization in the United States ranges from USD 20,000 to USD 50,000, creating strong incentives to fund adherence management programs that can prevent even a small fraction of exacerbation events across a managed patient population. Smart inhaler systems that provide objective adherence data and enable targeted clinical intervention represent a clinically credible and increasingly cost-effective mechanism for addressing this adherence gap.
Table of contents
15 chapters · 199 sections · 282 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Connected Metered-Dose Inhalers | CDPI segment, however |
| By Indication | Asthma Indication | COPD indication |
| By Distribution Channel | Hospital Pharmacies | Online and e-commerce channels |
By Product Type
- The connected metered-dose inhalers (cMDI) segment is expected to hold the largest share of the smart inhalers market.
- Pressurized metered-dose inhalers remain the most widely prescribed inhaler format globally for both asthma rescue therapy and maintenance therapy, with billions of units dispensed annually across North America, Europe, and Asia.
- The retrofit add-on sensor attachment model developed by Propeller Health and Adherium enables smart inhaler connectivity to be applied to existing marketed MDI products without requiring changes to the drug formulation or canister, which in many regulatory jurisdictions avoids the need for full device combination product reapproval.
- This approach has enabled rapid commercial scaling by allowing pharmaceutical companies to offer connected versions of their existing MDI products with relatively low incremental development investment, and has allowed smart inhaler platform companies to support multiple different pharmaceutical companies' products on a single sensor and analytics platform.
- The cDPI segment, however, is expected to witness the fastest growth during the forecast period.
- This growth is driven by the progressive clinical shift toward DPI-based maintenance therapy platforms for severe asthma and COPD, where the Ellipta and Turbuhaler DPI device families from GSK and AstraZeneca respectively hold dominant market positions.
- As pharmaceutical companies integrate connectivity directly into next-generation DPI device designs rather than relying on retrofit attachments, the sensor and analytics capabilities available for DPI-delivered maintenance therapies will surpass those achievable with add-on approaches, and the seamless patient experience of a fully integrated smart DPI is expected to drive adoption in the high-value severe disease patient segments where smart inhaler programs generate the greatest clinical and economic returns.
By Indication
- The asthma indication segment is expected to hold the largest share of the smart inhaler systems market.
- Asthma is the most prevalent chronic respiratory condition globally among both adults and children, and the smart inhaler market for asthma management has benefited from the earliest and most extensive clinical evidence base demonstrating the adherence improvement and outcome benefits of connected inhaler programs.
- The availability of multiple validated smart inhaler products specifically developed and regulatory-cleared for asthma management, including Propeller Health's connected platform for Ventolin and QVAR, Adherium's Smartinhaler for Symbicort and Foster, and Cohero Health's mSpirometer and connected inhaler system, provides commercial choice for health systems and payers seeking to implement asthma adherence programs.
- The strong pediatric asthma segment within the overall indication, where parents are particularly motivated to engage with digital tools that provide reassurance about their child's medication adherence and technique, is a commercially attractive subsegment for smart inhaler vendors offering child-friendly device designs and family engagement application features.
- However, the COPD indication is expected to witness the fastest growth during the forecast period.
- COPD affects a predominantly elderly and often less digitally confident patient population, which has historically made mobile application-based adherence programs more challenging to deploy successfully in COPD than in asthma.
- However, the particularly strong health economic case for adherence improvement in COPD, where exacerbation costs are high and maintenance therapy adherence rates are very low, is motivating health systems and payers to invest in implementation support infrastructure including device onboarding support, simplified application interfaces, and care coordinator-mediated program enrollment that addresses the usability barriers for older COPD patients.
- The multiple device burden common in severe COPD, where patients manage two or three concurrent inhaler devices with different usage schedules and techniques, creates a compelling use case for smart inhaler monitoring that distinguishes non-adherence from technique errors and device confusion as causes of inadequate disease control.
By Distribution Channel
- The hospital pharmacies segment is expected to hold the largest share of the smart inhaler systems market.
- Hospital pharmacies serve as the primary dispensing channel for smart inhaler systems in European markets where national health service procurement programs are the dominant commercial pathway, and in the United States where specialty hospital-based respiratory disease management programs incorporate smart inhalers as a standard component of discharge planning for patients admitted with severe asthma or COPD exacerbations.
- Hospital-based pulmonology programs that prescribe smart inhaler systems as part of structured respiratory disease management pathways benefit from the clinical infrastructure to provide device onboarding, patient education, and systematic adherence data review, which are the implementation requirements that determine whether smart inhaler programs achieve their full clinical benefit potential.
- However, the online and e-commerce channels segment is expected to witness the fastest growth during the forecast period, reflecting the broader trend toward direct-to-consumer health product purchasing and the increasing availability of smart inhaler add-on devices as over-the-counter consumer health products in some markets.
- The ability to purchase smart inhaler sensor attachments directly and link them to manufacturer-provided mobile applications without a clinical prescription is expanding the accessible patient population for smart inhaler benefits beyond the healthcare system-enrolled population, creating a consumer health market segment alongside the established clinical program market.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to hold the largest share of the global smart inhalers market. The United States is the largest and most commercially advanced national market for smart inhaler systems, supported by the combination of high asthma and COPD disease burden, sophisticated payer infrastructure that has established reimbursement frameworks for digital therapeutics and remote patient monitoring services incorporating smart inhaler data, and the commercial leadership of Propeller Health, Adherium's U.S. operations, and pharmaceutical company digital health initiatives including AstraZeneca's AMAZE and CONNECT studies that have generated the clinical evidence base required for payer contracting. Canada's provincial health system interest in smart inhaler programs for Indigenous and remote community respiratory disease management, where in-person clinical access is limited, represents a growing market segment for connected inhaler and telehealth-integrated respiratory care solutions.
Europe
The United Kingdom contributes significantly to North American market leadership by demonstrating through NHS commissioning of smart inhaler programs that health system-level smart inhaler deployment at population scale is operationally and economically feasible. NHS Scotland's national smart inhaler initiative and NHS England's integrated care system respiratory digital health programs have provided real-world outcome data that health systems in North America and across Europe are using to justify their own commissioning decisions.
Asia-Pacific
Fastest growthAsia-Pacific is expected to witness the highest growth rate in the smart inhalers market during the forecast period. This growth is driven by the convergence of rapidly growing respiratory disease burden attributable to urban air quality deterioration in China and India, expanding smartphone and mobile health infrastructure enabling digital adherence platforms, and growing health system investment in chronic disease management technologies in Japan, South Korea, Singapore, and Australia. China represents the largest growth opportunity within Asia-Pacific, with an estimated COPD patient population of over 100 million and urban air pollution levels that drive high rates of asthma exacerbation in major cities. The Chinese government's digital health infrastructure investment, including national electronic health record standardization programs and provincial telemedicine network development, is creating the connectivity infrastructure that smart inhaler analytics platforms require to deliver their full value to clinical and public health system users. India's large and underdiagnosed COPD population, estimated to exceed 55 million patients, combined with rapidly growing smartphone penetration among working-age adults, creates a large addressable market for smart inhaler programs delivered through primary care digital health platforms. Australia's strong digital health infrastructure, well-developed telehealth reimbursement framework, and highly active respiratory research community, including the Woolcock Institute of Medical Research and multiple university clinical trials programs, are supporting both commercial smart inhaler market development and the generation of real-world clinical evidence that informs global market adoption.
Competitive landscape
- AstraZeneca PLC
- GlaxoSmithKline PLC (GSK)
- Boehringer Ingelheim GmbH
- Novartis AG
- Teva Pharmaceutical Industries Ltd.
- Propeller Health (a ResMed company)
- Adherium Ltd.
- 3M Health Care (Kindeva Drug Delivery)
- Philips Respironics
- PARI Medical Holding GmbH
- Cohero Health Inc.
- Vectura Group PLC
- Respira Therapeutics
- Voluntis SA
- Gridscape Solutions Inc
Frequently asked questions
The global smart inhalers market is expected to grow from USD 1.9 billion in 2026 to USD 6.8 billion by 2036.
Cite this report
Meticulous Research. (2026). Smart Inhalers Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MRHC - 1041844). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/smart-inhalers-market-6527